
 Global Emergency Medical Services Billing Software Market | 2026-2036
Global Emergency Medical Services Billing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Emergency Medical Services Billing Software Market Analysis
HIPAA compliance certification is collapsing the vendor landscape, as platforms must demonstrate end-to-end encryption, audit logging, and Business Associate Agreement automation to qualify for hospital system procurement. Zoll Medical Corporation leverages its established presence in emergency care workflows to anchor billing software within broader patient data ecosystems. Digitech Computer specializes in ambulance-specific claims management, while ESO competes through cloud-native architecture designed for multi-agency deployments.
Emergency Medical Services Billing Software constitutes specialized revenue cycle management platforms engineered to process claims for pre-hospital care, incorporating NEMSIS-compliant data capture, payer-specific coding engines, and real-time eligibility verification at the point of service. Cloud-based deployment dominates new procurement as public cloud infrastructure enables elastic scaling during mass-casualty events without capital-intensive server commitments. The service type dimension concentrates margin pools in system integration, where vendors must map proprietary CAD dispatch data into standardized billing formats for Medicare, Medicaid, and commercial payers.
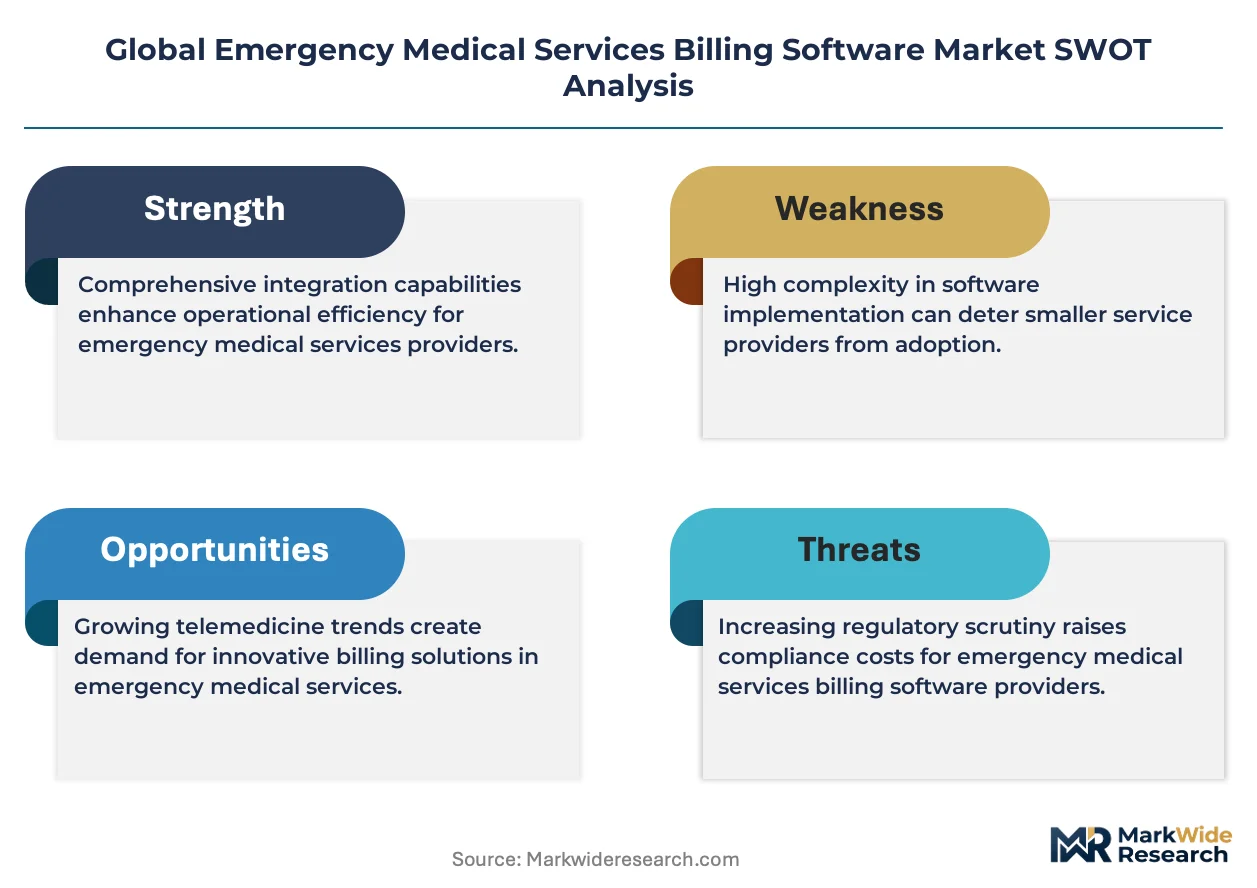
The US Department of Health and Human Services enforces HIPAA Security Rule mandates that shape product architecture, while CMS reimbursement policy revisions directly alter feature prioritization for claims scrubbing modules. The EU AI Act introduces emerging compliance obligations for automated coding assistance tools deployed across European EMS networks. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent data localization requirements threaten to fragment platform development roadmaps and inflate compliance engineering costs.
Market Dynamics
The HIPAA Security Rule and CMS reimbursement protocol revisions are compressing implementation timelines for EMS billing platforms, forcing providers to replace legacy systems with interoperable, audit-ready infrastructure that automates compliance documentation.
Growth Catalysts
- CMS Reimbursement Modernization:The Centers for Medicare and Medicaid Services mandates electronic claims submission with NEMSIS-compliant data elements, compelling ambulance services to upgrade billing infrastructure.
- Cloud-Native Architecture:Public cloud deployment enables elastic scaling during mass-casualty events without capital-intensive server commitments, accelerating procurement cycles for municipal EMS agencies.
- Interoperability Mandates:Hospital system consolidation demands seamless data exchange between CAD dispatch systems and revenue cycle platforms, creating pull-through demand for integrated billing solutions.
Market Restraints
- Compliance Engineering Costs:End-to-end encryption, audit logging, and Business Associate Agreement automation require substantial development resources that strain mid-tier vendor margins.
- Data Localization Requirements:Divergent sovereignty rules across European Union member states fragment platform development roadmaps and inflate cloud infrastructure expenditure.
- Legacy System Entrenchment:Decades-old proprietary billing databases in rural ambulance districts create technical debt that resists API-based integration with modern platforms.
Strategic Opportunities
- AI-Assisted Coding Tools:The EU AI Act creates a regulatory framework for automated claims scrubbing modules that reduce denial rates while maintaining human oversight requirements.
- Multi-Agency Deployments:Regional EMS consortiums in Texas and California seek unified billing platforms spanning fire departments, private ambulance operators, and hospital-based transport services.
- Subscription Pricing Models:SaaS-based revenue recognition aligns vendor incentives with customer outcomes, displacing perpetual license structures in mid-market procurement.
Industry Challenges
- NEMSIS Standardization Gaps:Version 3.5.0 data element implementation varies across state trauma registries, forcing vendors to maintain multiple validation engines for interstate billing.
- Revenue Cycle Talent Scarcity:Certified EMS billers with dual expertise in clinical documentation and payer-specific coding command premium wages that strain provider operating budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Emergency Medical Services Billing Software Market |
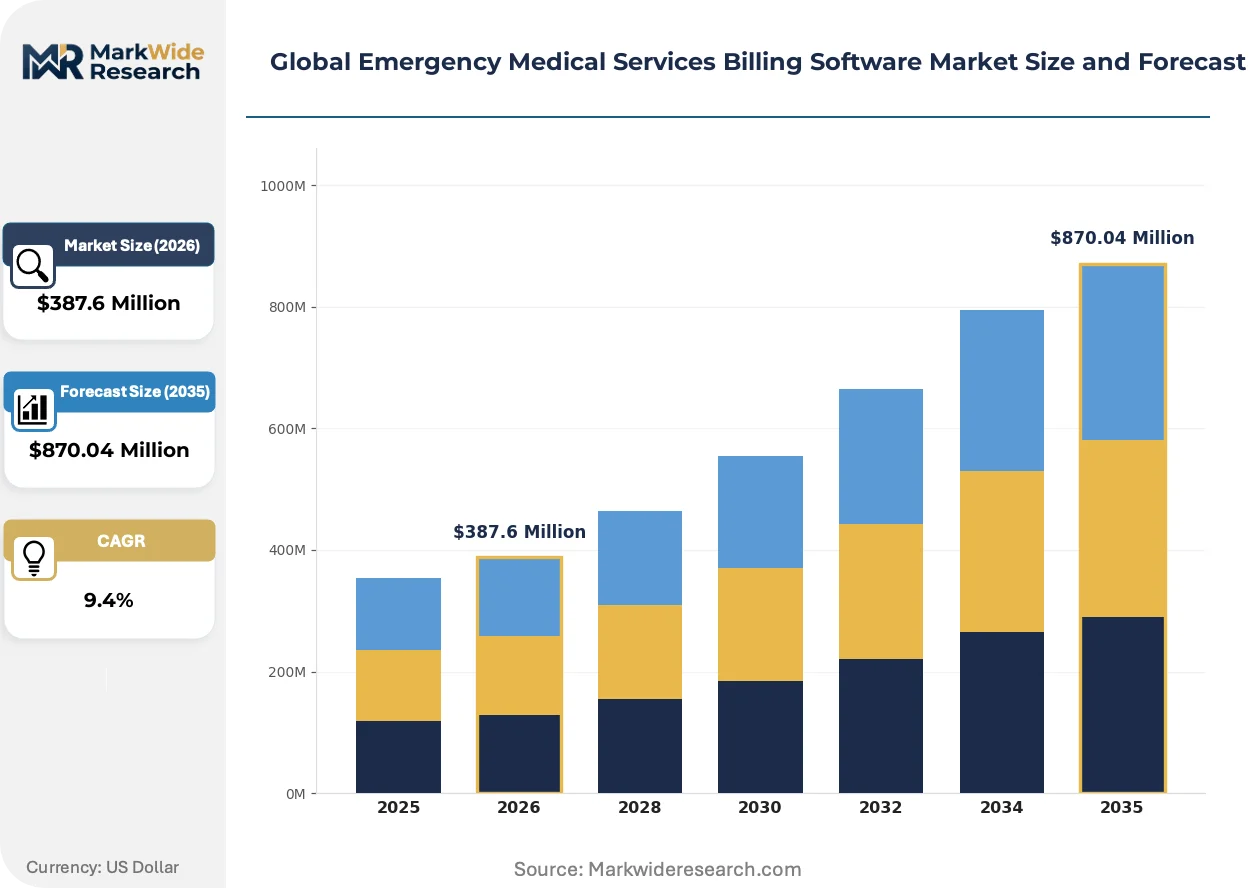
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $870.04 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Mobile End User: Hospitals, Ambulance Services, Emergency Departments, Healthcare Providers Deployment Model: Public Cloud, Private Cloud, Community Cloud, Onsite Service Type: Software Support, System Integration, Training, Consulting |
| Companies Covered | Zoll Medical Corporation, Digitech Computer, Inc, ESO, Change Healthcare, Traumasoft, AIM EMS Software & Services, MP Cloud Technologies, ImageTrend, iSalus Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Emergency Medical Services Billing Software Market Emerging Trajectories
Real-time eligibility verification and automated prior authorization are reshaping how EMS agencies capture revenue at the point of service, compressing the gap between patient transport and claims submission.
Automated coding assistance powered by natural language processing is bifurcating the vendor landscape. Ambulance services with high call volumes deploy machine learning models that translate clinical narratives into ICD-10 and procedure codes. This compression of manual coding labor is enabling mid-sized EMS agencies to operate without dedicated billing departments.
The EU AI Act introduces conformity assessment obligations for algorithmic decision-support tools deployed across European EMS networks. Vendors must demonstrate transparency in automated coding recommendations and maintain human-in-the-loop architectures. German and French ambulance operators are prioritizing platforms with pre-certified AI modules to accelerate procurement timelines.
Hospital systems are unbundling after-sales support from core software licenses, demanding à la carte implementation services and outcome-based training contracts. This procurement model shift displaces traditional bundled pricing in United States markets. Integrated delivery networks in Florida and Ohio now separately negotiate data migration, staff certification, and denial management consulting.
Global Emergency Medical Services Billing Software Market Segmentation
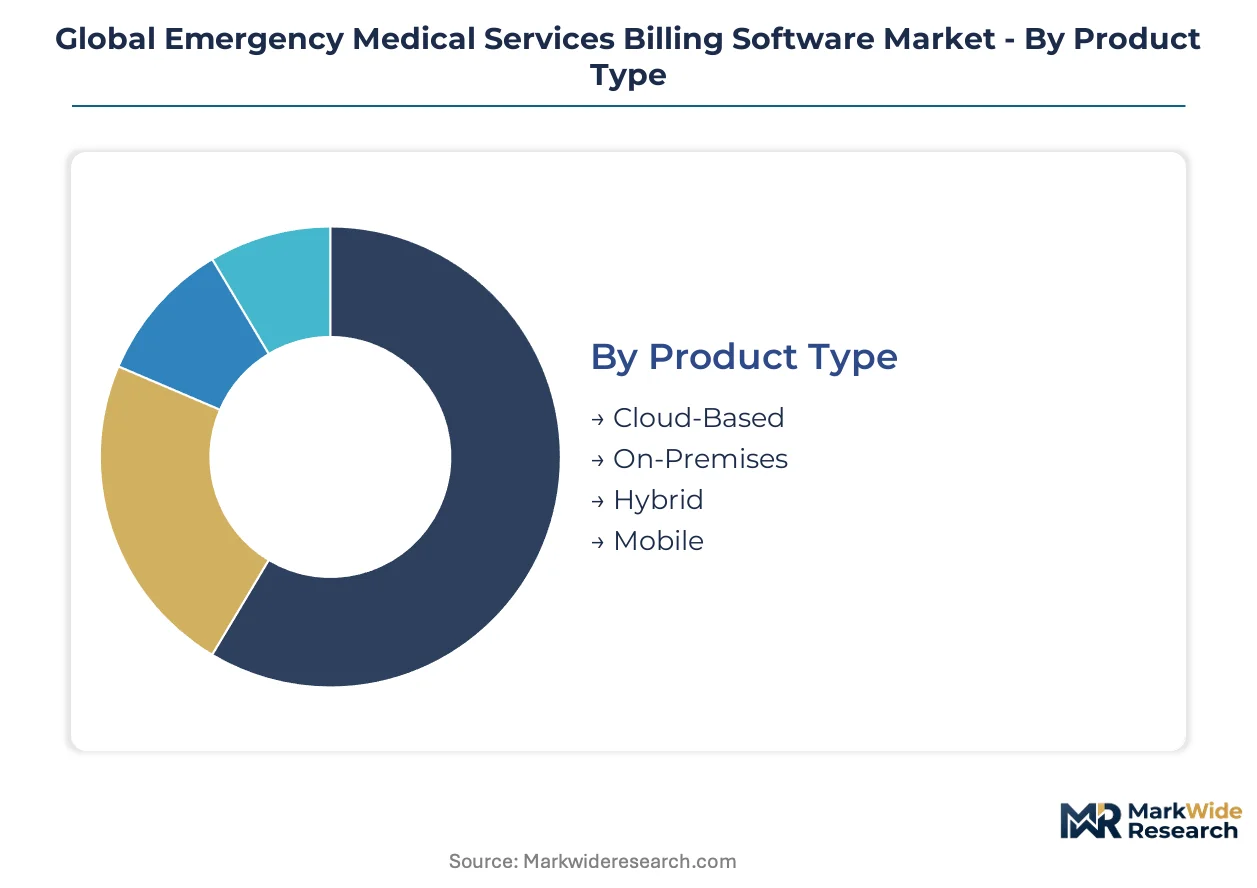
EMS billing software segmentation reveals how procurement patterns diverge between municipal agencies with legacy infrastructure constraints and private operators prioritizing cloud elasticity. Understanding these divides enables vendors to align product architecture with distinct compliance burdens and capital availability across customer types.
Product Type:
Cloud-based platforms dominate procurement in the United States and Western Europe where HIPAA and GDPR compliance frameworks have matured, while on-premises installations persist in regions with data sovereignty restrictions or unreliable connectivity.
- Cloud-Based:Multi-tenant architectures with automatic security patching and NEMSIS-compliant data lakes. Demand concentrates in Texas and California regional EMS consortiums seeking elastic capacity during wildfire and hurricane mass-casualty surges.
- On-Premises:Air-gapped servers with localized backup protocols for rural ambulance districts facing broadband gaps. German and French operators favor these configurations under EU AI Act algorithmic transparency mandates requiring physical data control.
- Hybrid:Core billing functions remain local while analytics and reporting sync to cloud instances.
- Mobile:Point-of-service applications running on ruggedized tablets for field crews.
Cloud-Based holds the largest share; momentum sits with Hybrid configurations bridging legacy and modern infrastructure.
End User:
Capital availability and reimbursement complexity create tiered demand patterns, with hospital-affiliated operators absorbing premium pricing for integrated revenue cycle platforms while independent ambulance services prioritize modular, subscription-based procurement.
- Ambulance Services:Standalone billing modules with CAD dispatch integration and real-time eligibility verification. Fire-department-based EMS in Florida and Ohio drives demand for multi-agency platforms spanning municipal and private transport providers.
- Hospitals:Enterprise revenue cycle suites embedding EMS claims within broader patient financial services. Integrated delivery networks in the United States require seamless data exchange between emergency transport and inpatient billing systems.
- Emergency Departments:Lightweight implementations focused on patient handoff documentation and payer notification.
- Healthcare Providers:Federated deployments across physician groups with varying technical sophistication.
Ambulance Services command the deepest feature requirements; Hospitals represent the steepest expansion trajectory as consolidation accelerates.
Deployment Model:
Security clearance levels and patient volume volatility determine infrastructure selection, with public cloud dominating mid-market procurement and private cloud reserved for entities handling classified or sensitive population data.
- Public Cloud:Shared infrastructure with consumption-based pricing and automatic disaster recovery. Municipal EMS agencies in the United States favor this model to avoid capital expenditure approval cycles.
- Private Cloud:Dedicated tenant environments with customizable encryption protocols. German ambulance operators select these under federal data protection authority guidance for cross-border patient transfers.
- Community Cloud:Multi-organization instances shared among regional healthcare coalitions.
- Onsite:Physical server installations with manual maintenance obligations.
Public Cloud holds the largest share; momentum sits with Community Cloud models as regional EMS consortiums consolidate procurement.
Service Type:
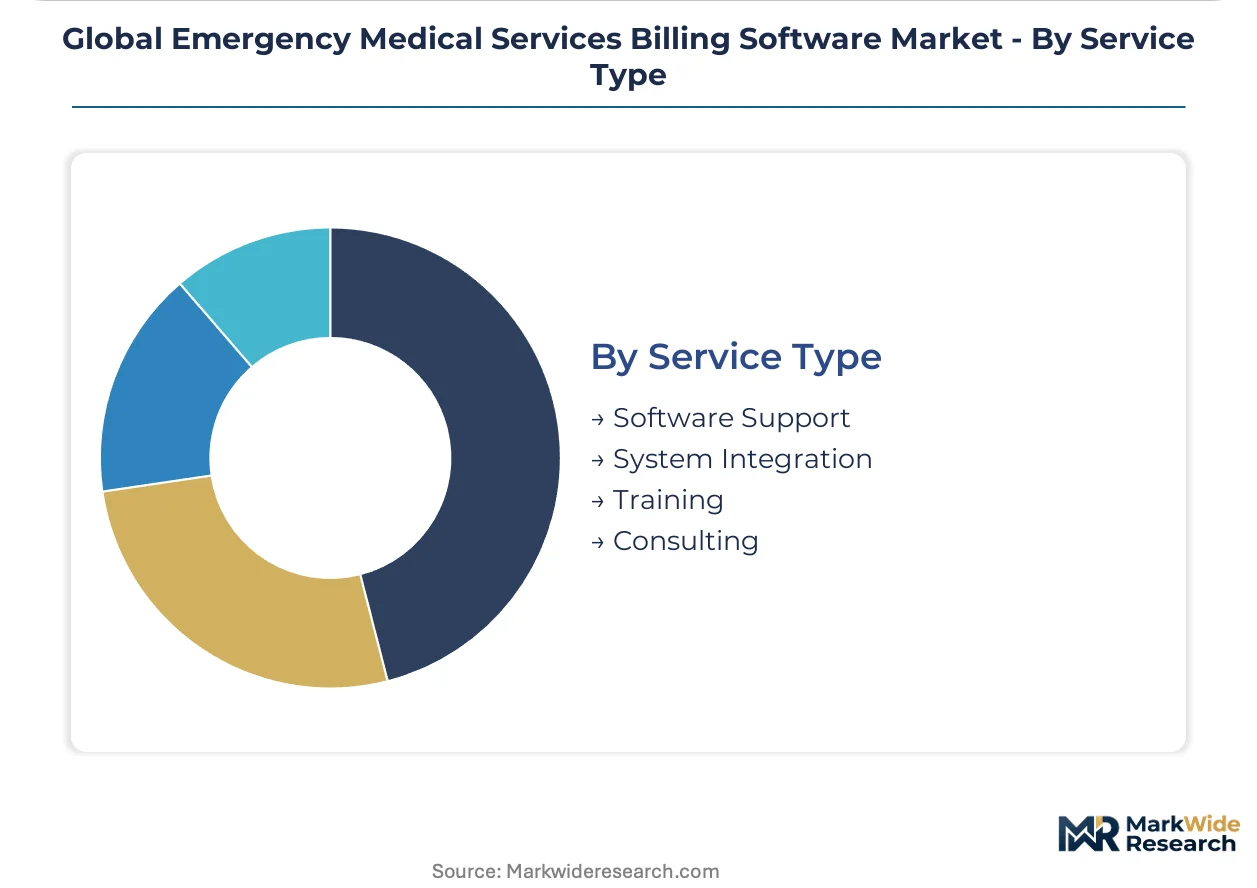
Margin concentration shifts toward implementation complexity, with system integration commanding premium pricing due to proprietary CAD dispatch mapping requirements while support services face commoditization from standardized SaaS platforms.
- System Integration:Custom API development connecting dispatch, ePCR, and billing data streams. Vendors map proprietary state trauma registry formats into NEMSIS-compliant structures for Medicare submission.
- Software Support:Tiered response commitments with guaranteed uptime SLAs and security patch management.
- Training:Certification programs for certified EMS billers combining clinical documentation and payer-specific coding expertise.
- Consulting:Denial management advisory and revenue cycle optimization engagements.
System Integration holds the largest share; momentum sits with Consulting as reimbursement complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS reimbursement modernization and HIPAA Security Rule enforcement are compressing implementation timelines across mature healthcare markets, while emerging economies grapple with foundational digitization of pre-hospital revenue cycles.
United States
Ambulance services in Texas and California regional consortiums are consolidating procurement for multi-agency cloud platforms. HIPAA Security Rule mandates from the Department of Health and Human Services require end-to-end encryption and audit logging for hospital system integration. Florida fire-department-based EMS drives demand for platforms spanning municipal and private transport providers.
Germany
Federal data protection authority guidance pushes ambulance operators toward private cloud configurations with physical data control for cross-border patient transfers. The EU AI Act conformity assessment obligations shape vendor selection for algorithmic transparency in automated coding tools. Bavarian and North Rhine-Westphalian EMS networks prioritize pre-certified AI modules to accelerate deployment timelines.
United Kingdom
NHS ambulance trusts are unbundling after-sales support from core licenses, demanding à la carte implementation services and outcome-based training contracts. GDPR compliance frameworks mature procurement toward cloud-native architectures with automatic security patching. London and Southeast integrated delivery networks separately negotiate data migration and denial management consulting engagements.
France
CNIL oversight intersects with EU AI Act requirements for human-in-the-loop architectures in automated coding assistance. Île-de-France and Auvergne-Rhône-Alpes ambulance operators concentrate procurement activity for platforms demonstrating transparency in algorithmic recommendations. Regional healthcare coalitions explore community cloud models for shared infrastructure across public and private EMS providers.
Australia
State-based trauma registry variations create NEMSIS-standardization complexity for interstate billing, forcing vendors to maintain multiple validation engines. TGA regulatory guidance shapes software procurement for hospital-affiliated ambulance services. New South Wales and Victoria EMS agencies lead cloud adoption for elastic scaling during bushfire and flood mass-casualty surges.
Global Emergency Medical Services Billing Software Market Vendor Landscape
Player mix skews toward specialized healthcare IT vendors with emergency care workflow expertise, creating a tiered structure where ambulance-specific specialists compete against enterprise revenue cycle suites. Consolidation pressure intensifies as HIPAA compliance certification collapses the vendor landscape. Three archetypes dominate: emergency care workflow incumbents extending into billing, pure-play ambulance revenue cycle specialists, and cloud-native platforms targeting multi-agency deployments. M&A activity concentrates around API-based integration capabilities, while portfolio diversification moves emphasize NEMSIS-compliant data capture modules.
Within the emergency care workflow tier, Zoll Medical Corporation leverages established patient data ecosystems to anchor billing software within broader pre-hospital platforms. Digitech Computer, Inc exemplifies the ambulance-specific specialist archetype with concentrated claims management expertise. ESO occupies a cloud-native position designed for elastic multi-agency deployments across fragmented provider networks.
| Leading Market Players |
|---|
| Zoll Medical Corporation |
| Digitech Computer, Inc |
| ESO |
| Change Healthcare |
| Traumasoft |
| AIM EMS Software & Services |
| MP Cloud Technologies |
| ImageTrend |
| iSalus Healthcare |
| Others |
Supply Flow & Price Mechanics
Ninety-day implementation timelines for HIPAA-compliant platforms concentrate pricing power among vendors with pre-certified encryption architectures, while buyers facing CMS deadline pressure absorb premium deployment costs. Municipal EMS agencies with constrained capital budgets negotiate extended payment terms against fire-department-based operators consolidating multi-agency procurement leverage.
Pricing Analysis
Certification level (HIPAA-compliant vs. non-compliant) creates the primary spread between premium and standard tiers, with end-to-end encryption and audit logging commanding substantial premiums. Subscription-based SaaS pricing dominates municipal procurement, while hospital-affiliated operators negotiate enterprise licenses bundling implementation services. Price erosion runs through mid-tier vendors as compliance engineering costs compress margins. Independent ambulance services exhibit highest price sensitivity; integrated delivery networks absorb premium pricing for seamless CAD-to-billing integration.
Supply Chain Analysis
Just-in-time delivery of cloud infrastructure capacity dominates procurement, though Texas and California regional consortiums maintain strategic reserve agreements for mass-casualty surge capacity. Software development draws from engineering talent pools in the United States, Ireland, and India, with cloud infrastructure anchored in AWS, Azure, and Google Cloud data centers. Single-source vulnerability concentrates in NEMSIS validation engine providers, where state-specific compliance requirements fragment supplier bases. Distribution runs through direct vendor sales teams and specialized healthcare IT resellers serving rural ambulance districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as hospital system consolidation demands interoperable billing ecosystems spanning dispatch, clinical documentation, and revenue cycle operations. NEMSIS standardization and CMS reimbursement modernization are compressing vendor timelines toward integrated, API-first architectures.
For Market Incumbents: Shield installed base relationships by embedding billing modules within broader patient data ecosystems, leveraging existing CAD and ePCR integrations as switching-cost barriers. Accelerate certification investment ahead of EU AI Act conformity assessment deadlines to preempt European market entry by cloud-native competitors. Prioritize vertical integration into denial management consulting services to capture recurring revenue streams beyond software licenses.
For New Entrants and Emerging Players: Regional EMS consortiums in fragmented US markets represent the most penetrable white-space, where multi-agency deployments lack unified billing platforms spanning fire departments and private operators. Target mid-sized ambulance services in Florida and Ohio with modular, subscription-based procurement avoiding capital expenditure approval cycles. Pursue API-first go-to-market positioning emphasizing rapid CAD dispatch integration without legacy database migration.
For Investors and Strategic Acquirers: Carve-out targets emerge from hospital system IT divisions and regional healthcare coalitions seeking to monetize internally developed billing platforms. Long-term viability hinges on NEMSIS compliance automation capabilities and cloud-native architecture enabling elastic scaling. Monitor CMS reimbursement protocol revisions as inflection indicators; material policy shifts toward value-based pre-hospital payment models would favor platforms with real-time eligibility verification and outcomes analytics.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CAD dispatch, ePCR documentation, and billing within single data ecosystem for hospital systems. |
| Acquisition of Specialist Firm | Absorbs NEMSIS validation engine providers to compress multi-state compliance engineering timelines. |
| Geographic Expansion | Establishes private cloud infrastructure in Germany and France under EU AI Act data localization mandates. |
| Strategic Partnership | Aligns with regional EMS consortiums in Texas and California for multi-agency deployment reference accounts. |
| Product Launch | Introduces pre-certified AI-assisted coding modules accelerating procurement in Bavarian and North Rhine-Westphalian networks. |
Methodological Framework
A standing panel of EMS billing directors, hospital revenue cycle executives, CAD dispatch system engineers, and CMS policy specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from CMS Medicare claims data, state trauma registry filings, hospital GPO contract databases, and NEMSIS technical documentation. Bottom-up sizing of ambulance service deployments triangulated against top-down healthcare IT expenditure benchmarks from HHS and trade associations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated deployment model, end-user type, service tier, and regional regulatory cluster dimensions. CAGRs derived from historical adoption curves weighted by HIPAA compliance implementation waves and CMS reimbursement modernization deadlines. Forecast inputs included cloud infrastructure capex disclosures from hyperscalers and EMS agency budget cycle timing patterns.
Forecasts assume regulatory continuity in HIPAA Security Rule enforcement and EU AI Act implementation; material policy shifts would require re-modeling. Revision becomes warranted when CMS reimbursement protocol changes alter claims scrubbing feature prioritization or when NEMSIS version updates fragment validation engine requirements across state trauma registries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Connected Health and Wellness Solutions Market
Digital Health Solutions
Distance Health Technologies Market
Digital Health Solutions
Medical Animation Market
Digital Health Solutions
Artificial Intelligence in Precision Medicine Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Digital Twins in Healthcare Market
Digital Health Solutions
Global Physical Therapy Software Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
Econsent in Healthcare Market
Digital Health Solutions
Heart Failure Software Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Smart Cards in Healthcare Market
Digital Health Solutions
Digital Healthcare Solutions Market