
 Global Patient Centric Healthcare App Market | 2026-2036
Global Patient Centric Healthcare App Market Size, Share, and Industry Trends Forecast 2026-2036
Global Patient Centric Healthcare App Market Foresight
Platform unbundling is shifting buyer choice across the Global Patient Centric Healthcare App Market as healthcare providers move from monolithic suites to modular point solutions. Epic Systems Corporation anchors enterprise EHR-integrated deployments across large hospital networks. Philips leverages its diagnostic hardware footprint to sustain wearable-connected app ecosystems. IBM competes through cloud infrastructure and AI analytics layers that underpin third-party developer marketplaces.
Patient centric healthcare apps constitute software interfaces that collect, process, and visualize individual health data through FHIR-compliant APIs, Bluetooth-enabled biometric sensors, and cloud-native architectures to enable self-management and clinical decision support. Remote Monitoring leads product type adoption where chronic disease management creates recurring data streams and sticky user engagement. Telehealth Solutions within the technology dimension generates the fastest expansion as reimbursement parity laws in multiple jurisdictions normalize virtual-first consultations.
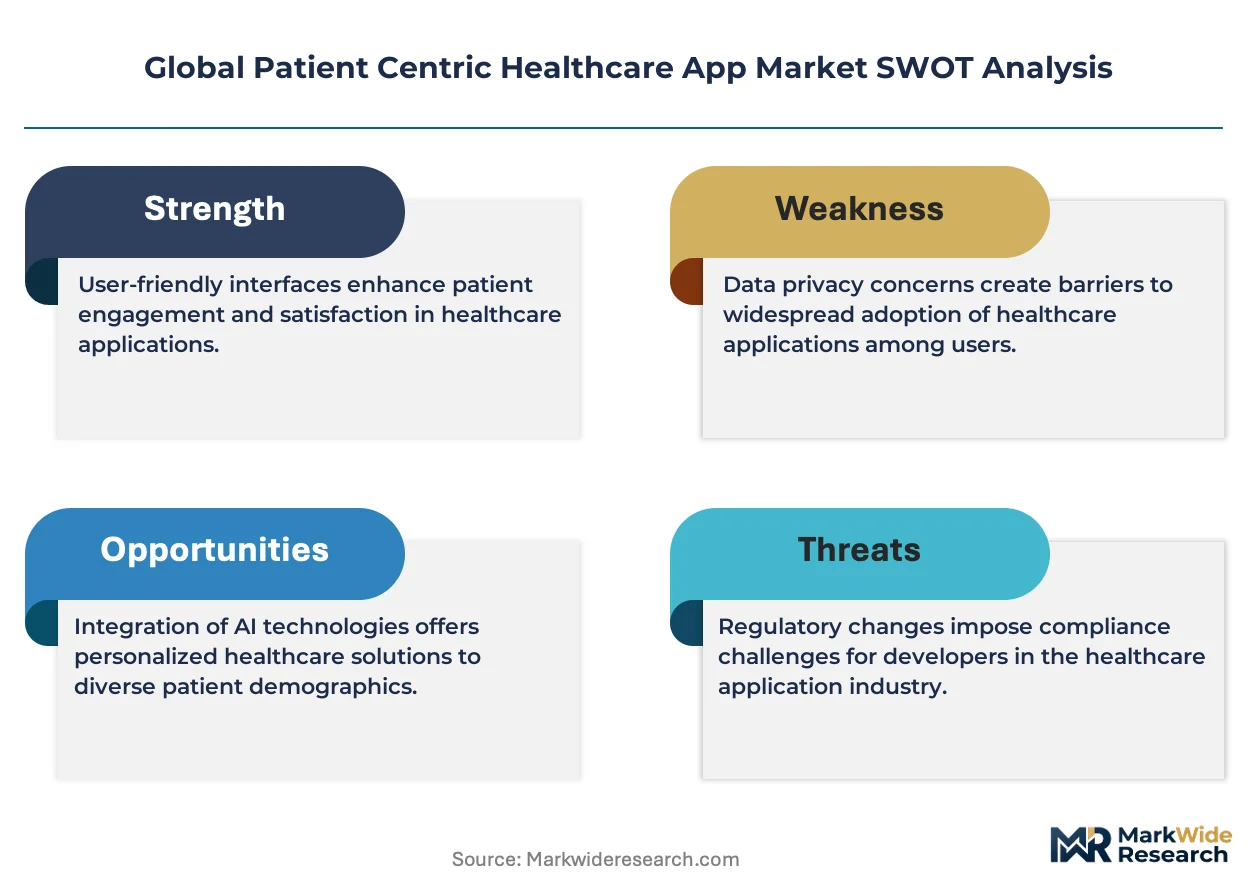
FDA digital health pre-certification and EU MDR software-as-medical-device classification are tightening quality management system requirements for app developers seeking market access. HIPAA security rule enforcement and GDPR health data processing standards further constrain cross-border data architectures and vendor liability exposure. Stakeholders must monitor evolving software reimbursement catalogs from national health technology assessment bodies to anticipate which functionality categories achieve sustainable payment pathways.
Market Dynamics
Platform unbundling is fragmenting purchasing authority across health systems as clinical departments gain autonomy to select specialized point solutions over monolithic EHR suites.
Growth Catalysts
- EU MDR software classification:Clear regulatory pathways for Software as a Medical Device accelerate developer investment in quality management systems.
- Bluetooth-enabled biometric sensors:Consumer-grade hardware is converging with clinical-grade accuracy, expanding remote monitoring into home settings.
- Germany:Statutory health insurer reimbursement for prescription digital therapies creates sustainable payment infrastructure for chronic disease apps.
Market Restraints
- GDPR health data processing:Cross-border data architectures face strict adequacy requirements, constraining vendor liability exposure.
- Cloud infrastructure concentration:Hyperscaler dominance in compute and storage creates single-point-of-failure risk for app uptime.
- FHIR implementation variability:Inconsistent API maturity across hospital systems forces redundant integration engineering.
Strategic Opportunities
- India:CDSCO digital health guidelines and PLI scheme incentives position the market for localized manufacturing of connected diagnostic peripherals.
- AI-augmented clinical decision support:Machine learning models are converging with regulatory-grade evidence generation to enable pre-certification pathways.
- Direct-to-employer channels:Self-insured corporations are bypassing traditional payers to contract population health platforms directly.
Industry Challenges
- Interoperability engineering talent:Scarcity of developers with simultaneous expertise in HL7 FHIR, cybersecurity, and clinical workflow design inflates compensation costs.
- HIPAA security rule enforcement:OCR audit expansion demands continuous compliance monitoring infrastructure that mid-size vendors struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Patient Centric Healthcare App Market |
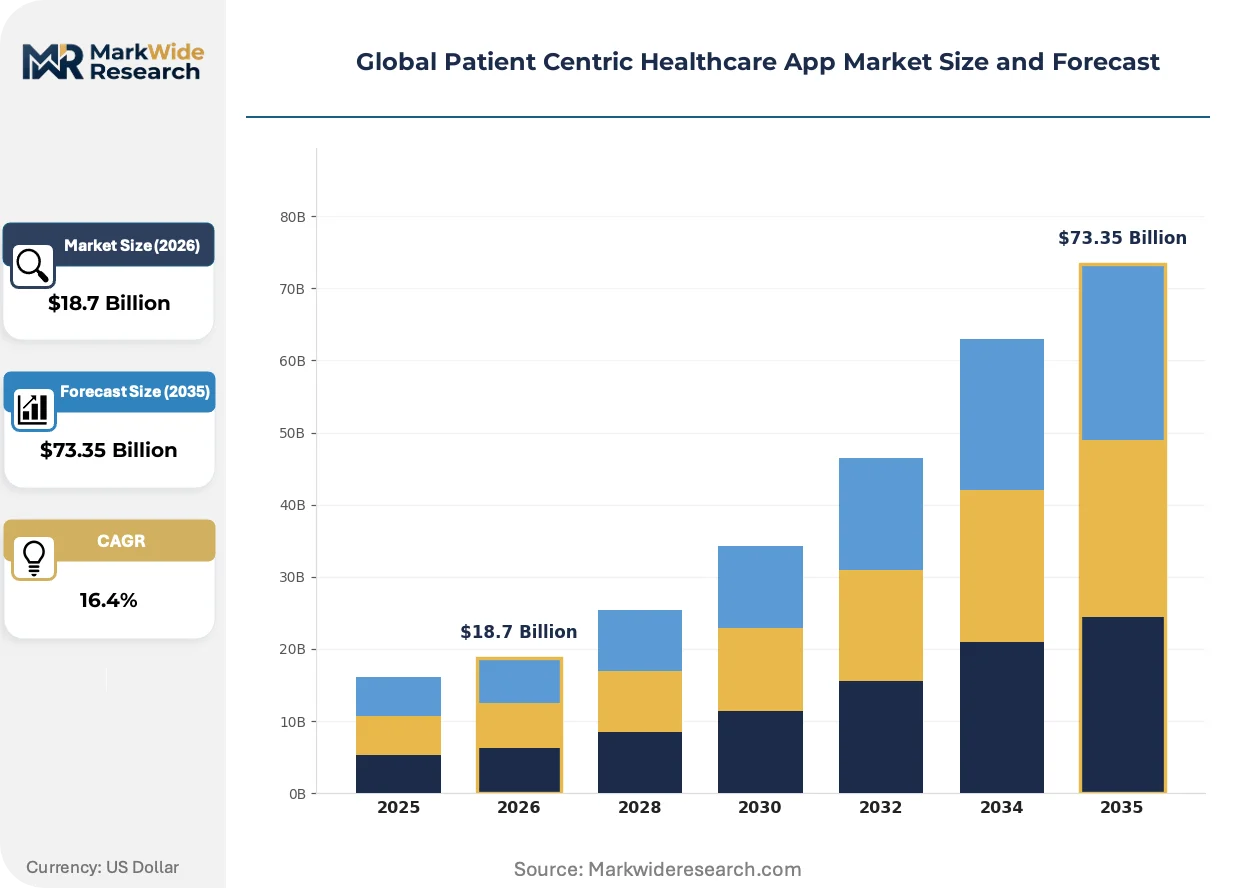
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication Management, Remote Monitoring, Appointment Scheduling, Health Tracking Technology: Mobile Apps, Web-Based Platforms, Wearable Integration, Telehealth Solutions End User: Patients, Healthcare Providers, Caregivers, Insurance Companies Delivery Mode: Subscription-Based, One-Time Purchase, Freemium, Pay-Per-Use |
| Companies Covered | Allscripts Healthcare Solutions, Koninklijke Philips, IBM, Athenahealth, Merck & Co., Bayer AG, MobileSmith, Siemens Healthineers, Epic Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Patient Centric Healthcare App Market Shifts & Advancements
Generative AI is compressing development cycles for patient-facing interfaces while regulatory frameworks race to define clinical liability boundaries for algorithmic outputs.
FHIR-native architectures are converging with cloud-native microservices to enable modular health data exchange. Large hospital networks in the United States are mandating SMART on FHIR compliance for all third-party app integrations. This convergence is compressing vendor onboarding timelines from eighteen months to under ninety days.
MDR Article 10 quality management requirements are forcing software developers to adopt ISO 13485-certified processes previously reserved for hardware manufacturers. European notified bodies are backlogged twelve to eighteen months for conformity assessment. Class IIa diagnostic apps face the steepest certification delays, pushing developers toward de-risked wellness-monitored positioning.
Virtual-first care models are displacing traditional primary care gatekeeping in employer-sponsored plans. Large purchasers in the United States are unbundling telehealth from medical benefits administration. This shift is most visible in self-insured corporations contracting directly with asynchronous messaging platforms for routine condition management.
Global Patient Centric Healthcare App Market Segmentation
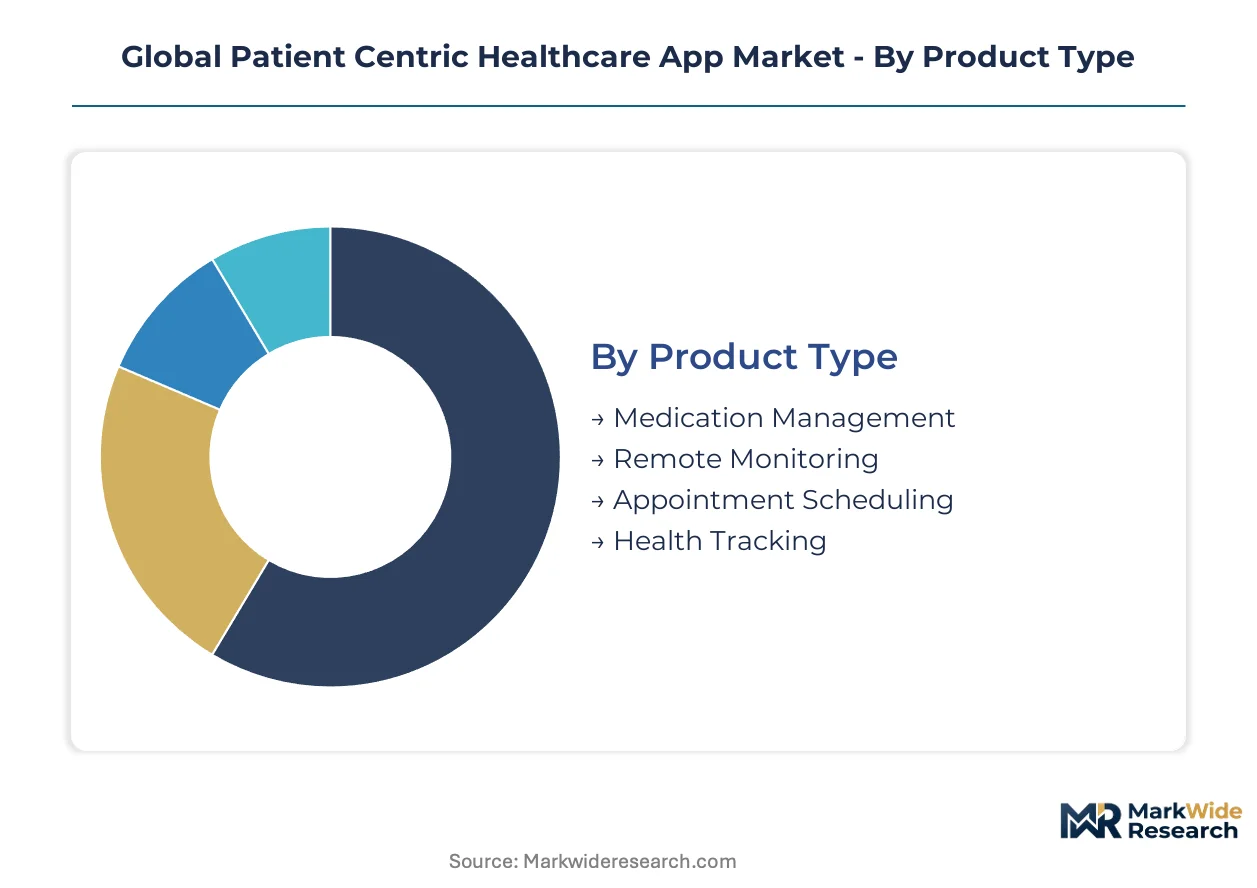
Patient centric healthcare apps fragment across four functional dimensions that determine procurement authority, reimbursement eligibility, and integration complexity. Each segmentation axis reveals distinct supply concentration patterns that shape vendor competitive positioning and buyer decision hierarchies.
Product Type:
Supply concentration clusters around chronic disease management platforms where recurring data streams justify sustained development investment and regulatory certification costs.
- Remote Monitoring:Bluetooth-enabled biometric sensors and cloud-native architectures capture continuous physiological data streams for diabetes, hypertension, and cardiac conditions. Hospital systems in the United States prioritize these platforms for readmission reduction programs.
- Medication Management:Dose tracking algorithms and adherence analytics reduce therapeutic failure rates in polypharmacy populations. Germany's statutory health insurers reimburse prescription-integrated apps under DiGA pathways, anchoring European demand concentration.
- Appointment Scheduling:FHIR-compliant calendar integration reduces no-show rates across ambulatory networks.
- Health Tracking:Consumer-grade wellness metrics feed into employer-sponsored prevention programs.
Remote Monitoring absorbs the bulk of installed capacity; Telehealth Solutions within the technology dimension is expanding most quickly.
Technology:
Cost tier differentiation separates enterprise-grade clinical platforms from consumer wellness tools, with integration depth determining pricing power and customer stickiness.
- Telehealth Solutions:Synchronous video and asynchronous messaging platforms enable virtual-first consultations with reimbursement parity in multiple jurisdictions. Self-insured corporations in the United States contract these directly, bypassing traditional payer intermediaries.
- Wearable Integration:Consumer-grade hardware from Apple and Garmin converges with clinical-grade accuracy standards through FDA-cleared algorithms. Philips leverages diagnostic device footprints to sustain ecosystem control over data pipelines.
- Mobile Apps:Native iOS and Android deployments dominate patient-facing interfaces for medication reminders and symptom logging.
- Web-Based Platforms:Browser-accessible dashboards serve caregiver coordination and population health analytics.
Mobile Apps command the largest user base; Wearable Integration climbs the fastest as sensor accuracy improves.
End User:
Volume concentration follows procurement authority shifts, with clinical departments gaining autonomy over point solutions while enterprise IT retains EHR backbone control.
- Healthcare Providers:Epic Systems and Cerner-integrated workflows demand SMART on FHIR compliance for all third-party deployments. Large hospital networks mandate ninety-day onboarding timelines, compressing vendor sales cycles.
- Patients:Direct-to-consumer channels bypass institutional procurement, with Germany's DiGA catalog and FDA pre-certification pathways determining accessible functionality tiers.
- Caregivers:Family coordination features address aging-in-place demographics with shared access protocols.
- Insurance Companies:Risk stratification algorithms inform premium pricing and care management investments.
Healthcare Providers dominate enterprise contract value; Patients represent the steepest expansion trajectory as reimbursement catalogs mature.
Delivery Mode:
Margin structures diverge sharply between recurring revenue platforms and transactional models, with regulatory compliance costs favoring subscription economics.
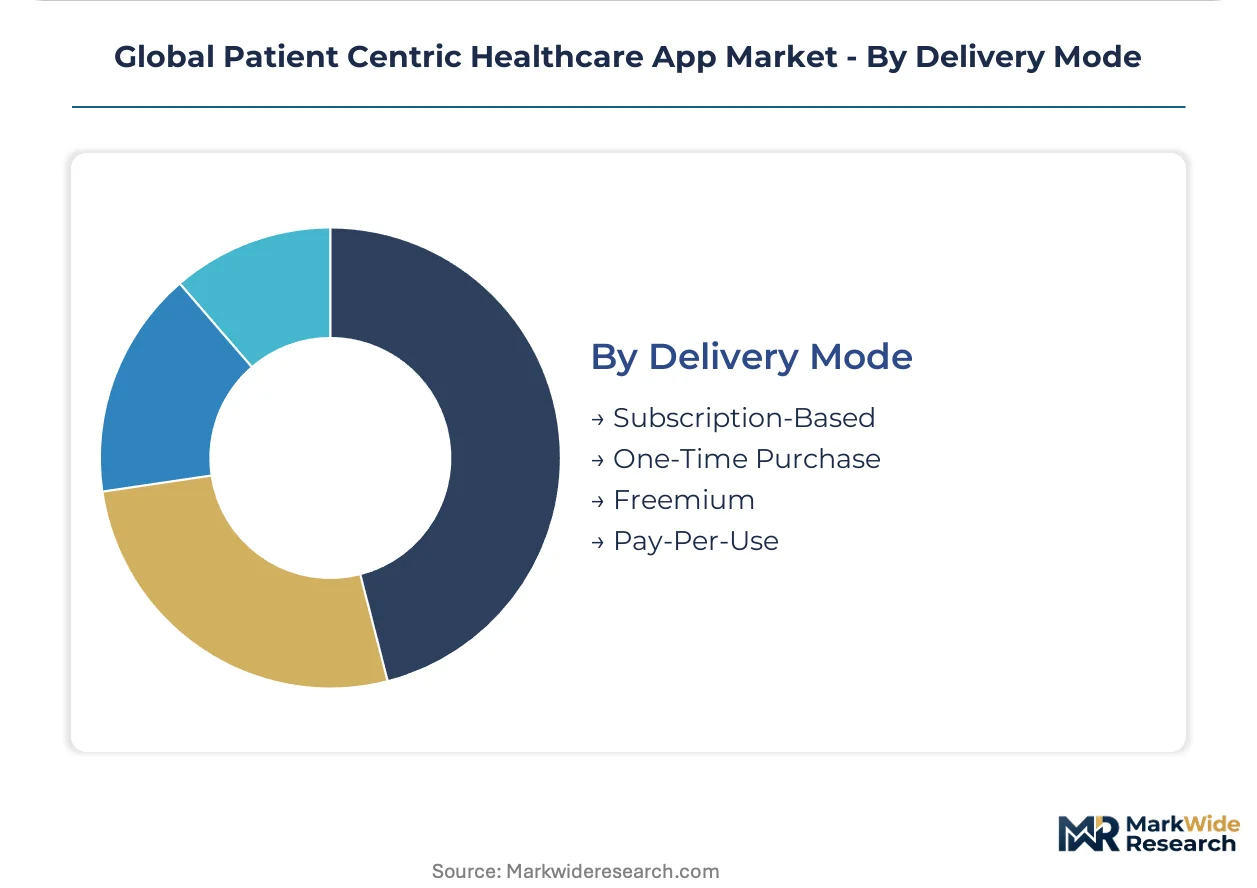
- Subscription-Based:Monthly or annual recurring revenue models fund continuous compliance monitoring for HIPAA security rule enforcement and GDPR health data processing. Mid-size vendors struggle to fund OCR audit expansion without predictable cash flows.
- Freemium:Basic functionality hooks convert to premium tiers through clinical outcome validation and prescriber endorsement.
- One-Time Purchase:Perpetual licenses persist in institutional settings with capital budget cycles.
- Pay-Per-Use:Event-based pricing aligns with episodic care models and telehealth consultation volumes.
Subscription-Based captures the majority of vendor revenue stability; Freemium gains share fastest among direct-to-consumer entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States and Germany while patient adoption spreads across diverse reimbursement environments. Consumption patterns diverge sharply between markets with statutory digital therapy coverage and those relying on employer-sponsored benefits.
United States
Hospital networks prioritize SMART on FHIR compliance for third-party integrations, compressing vendor onboarding timelines. FDA digital health pre-certification pathways accelerate market entry for qualified developers. The Greater Boston corridor anchors clinical decision support algorithm development alongside Stanford Research Park in California.
Germany
Statutory health insurers reimburse prescription digital therapies under DiGA pathways, creating sustainable payment infrastructure. EU MDR software-as-medical-device classification tightens quality management requirements for developers. Berlin-Brandenburg clusters telehealth platform engineering while Bavaria concentrates diagnostic app certification expertise.
United Kingdom
NHS Digital approves apps for national procurement frameworks, filtering market access through clinical evidence gates. GDPR health data processing standards constrain cross-border cloud architectures for vendors. London's Silicon Roundabout hosts patient engagement platform startups alongside Manchester's health data science institutes.
India
CDSCO digital health guidelines and PLI scheme incentives attract localized manufacturing of connected diagnostic peripherals. The national digital health mission expands unique health identifier coverage for app-based care coordination. Karnataka's Bangalore clusters health-tech engineering talent while Telangana's Hyderabad anchors medical device software testing facilities.
Japan
PMDA software certification requirements favor established medical device manufacturers entering the app market. METI promotes FHIR-based data exchange standards for aging-in-place technologies. Tokyo's Shinagawa district concentrates digital therapeutics development while Osaka's Kansai region specializes in wearable integration engineering.
Global Patient Centric Healthcare App Market Competitive Landscape
The competitive structure tilts toward integrated health record platforms over standalone point solutions. Enterprise procurement favors vendors with pre-existing hospital network relationships and certified interoperability stacks. Three archetypes dominate: EHR-anchored suites, diagnostic hardware extenders, and cloud-native specialist platforms. Consolidation pressures intensify as mid-size vendors face HIPAA audit infrastructure costs and MDR certification backlogs.
Among EHR-anchored specialists, Epic Systems Corporation exemplifies the enterprise integration archetype through its dominance of large hospital network deployments. Koninklijke Philips occupies a position bridging diagnostic hardware and connected app ecosystems, leveraging installed imaging and monitoring device footprints. IBM sits within the infrastructure layer, supplying cloud and AI analytics capabilities that underpin third-party developer marketplaces without direct patient-facing competition.
| Leading Market Players |
|---|
| Allscripts Healthcare Solutions |
| Koninklijke Philips |
| IBM |
| Athenahealth |
| Merck & Co. |
| Bayer AG |
| MobileSmith |
| Siemens Healthineers |
| Epic Systems Corporation |
| Others |
Supply & Pricing Matrix
Hospital procurement committees demanding ninety-day SMART on FHIR compliance timelines are compressing vendor sales cycles and forcing supply-side investment in pre-certified integration stacks, which in turn stratifies pricing around interoperability maturity rather than feature depth.
Pricing Analysis
Margin tightening in mid-tier subscription offerings reflects EU MDR certification backlogs that delay revenue recognition for Class IIa diagnostic apps. Pricing stratifies across FHIR-native enterprise tiers, ISO 13485-certified clinical tiers, and wellness-monitored consumer tiers, with certification grade and integration complexity as primary differentiation drivers. Cost-down pressure on standalone point solutions accelerates as EHR-anchored suites bundle competing functionality. Self-insured corporations show lowest price sensitivity given direct contracting authority, while mid-size health systems face acute budget constraints.
Supply Chain Analysis
Bluetooth-enabled biometric sensor supply rests on Chinese hardware manufacturers, Taiwanese semiconductor fabricators, and German precision component specialists. Cloud-native architecture development draws from hyperscaler infrastructure concentrated in the United States, Ireland, and Singapore. Single-source vulnerability in EU MDR notified body capacity creates twelve-to-eighteen-month conformity assessment delays. Distribution runs through hospital procurement frameworks in the United States, statutory insurer reimbursement catalogs in Germany, and direct-to-employer channels for self-insured corporations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI is displacing legacy rule-based clinical decision support, creating a technology-transition phase where algorithmic output liability frameworks remain unsettled.
For Market Incumbents: Deploy backward integration into FHIR-native microservices to capture integration layer margins threatened by cloud-native specialists. Acquire ISO 13485-certified quality management capabilities to compress EU MDR conformity timelines. Consolidate around hospital network relationships before procurement autonomy fragments further to clinical departments. For New Entrants and Emerging Players: The price-point gap between DiGA-reimbursed prescription apps and wellness-monitored consumer tools creates white-space opportunity in medication management for polypharmacy populations. Target direct-to-employer channels bypassing traditional payer intermediaries. Pursue asynchronous messaging platforms for routine condition management as the most penetrable telehealth segment. For Investors and Strategic Acquirers: Re-rating potential sits with FHIR-native specialist platforms given FDA pre-certification pathway acceleration and reimbursement parity normalization. Long-term viability favors vendors with sustainable compliance infrastructure funding across HIPAA audit expansion and GDPR health data processing adequacy requirements. Watch EU MDR notified body capacity expansion as the signal for Class IIa diagnostic app certification velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| SMART on FHIR Compliance Investment | Epic Systems and Cerner-integrated workflows mandate ninety-day onboarding timelines for all third-party deployments. |
| EU MDR Quality Management Certification | ISO 13485-certified processes previously reserved for hardware manufacturers now anchor software-as-medical-device market access. |
| Direct-to-Employer Channel Development | Self-insured corporations in the United States unbundle telehealth from medical benefits administration for population health platforms. |
| AI-Augmented Clinical Decision Support Pre-Certification | FDA digital health guidance accelerates developer investment in regulatory-grade evidence generation pathways. |
| Bluetooth Sensor Accuracy Convergence | Consumer-grade hardware from Apple and Garmin achieves clinical-grade standards through FDA-cleared algorithms. |
Research Methodology
Document review covered FDA digital health guidance documents, EU MDR software classification rules, and statutory health insurer reimbursement catalogs, complemented by interviews with hospital procurement committee members, biomedical engineers, GPO contracts managers, and health technology assessment body officials. Secondary validation drew from CMS Medicare reimbursement data, hospital procurement databases, and clinical trials registries. Bottom-up installed base estimates and top-down expenditure flows were triangulated to anchor market sizing.
Historical adoption curves were cross-referenced against panel input from health system IT directors and payer innovation leads to inform projection trajectories across the analysis window. Segmentation modeling incorporated product type, technology tier, end-user procurement authority, and delivery mode economics. CAGRs were derived from regression analysis against reimbursement catalog expansion rates and regulatory pathway velocity. FHIR implementation maturity indices and MDR certification queue lengths served as industry-specific forecast inputs.
Inputs from notified body conformity assessment databases and hospital procurement framework approvals were available through the study window; gaps in real-time DiGA prescription volume data introduce uncertainty bands around Germany demand forecasts. Forecasts reflect documented assumptions regarding reimbursement parity law expansion and cloud infrastructure concentration stability. Regulatory guidance revision, notified body capacity shocks, and hyperscaler service disruption represent triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Cardiac AI Monitoring and Diagnostic Market
Digital Health Solutions
Global Real World Evidence Solutions Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
Healthcare Navigation Platform Market
Digital Health Solutions
Middle East and Africa Virtual Reality (VR) Health Market
Digital Health Solutions
Connected Health and Wellness Solutions Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Patient Case Management Software Market
Digital Health Solutions
GCC E-Health Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Occupational Therapy Software Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Long Term Post-Acute Care Software Market
Digital Health Solutions
Cloud Technologies in Healthcare Market