
 Healthcare Adhesive Tapes Market | 2026-2036
Healthcare Adhesive Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Adhesive Tapes Market Outlook
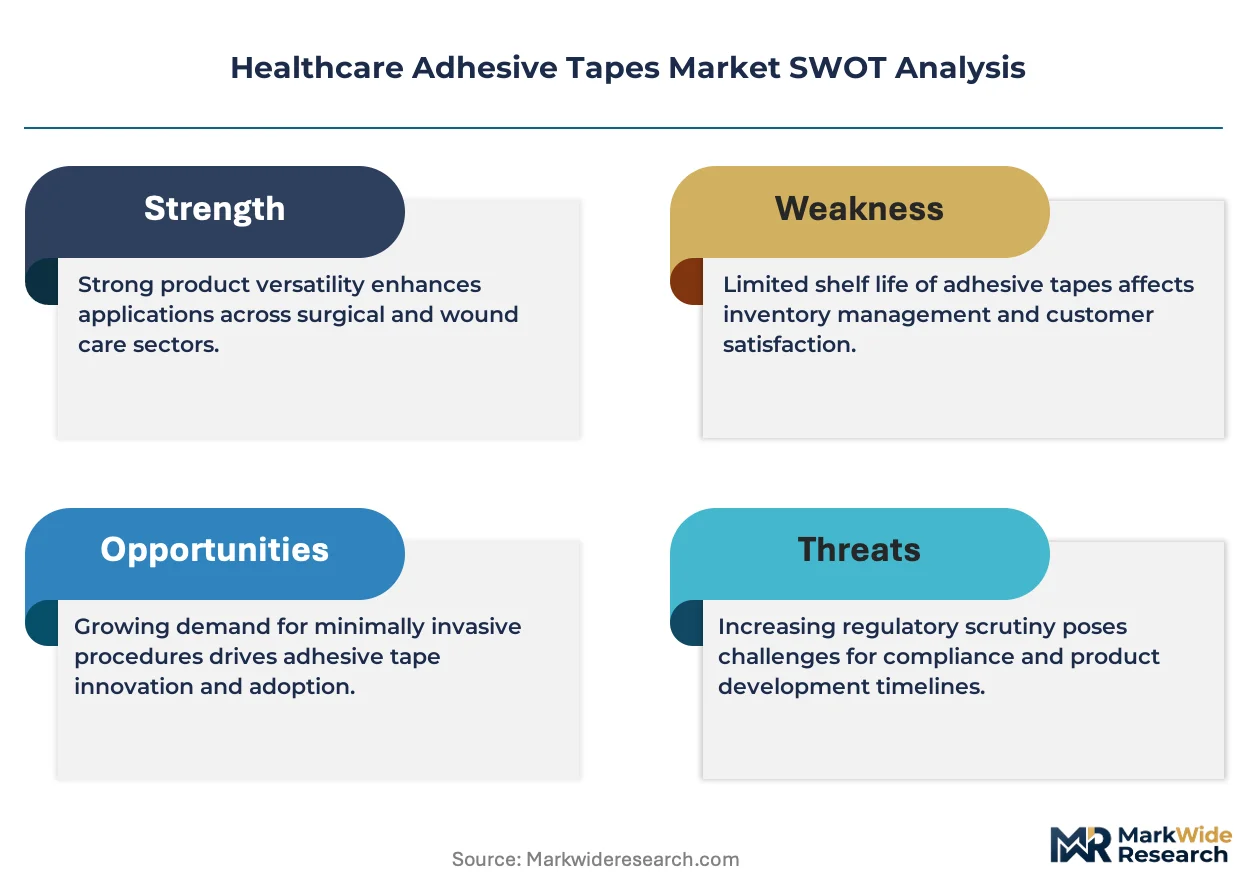
Hospital procurement channels is rewriting how healthcare adhesive tapes reach end users, with group purchasing organizations consolidating vendor lists and squeezing out regional distributors. 3M leverages its direct-to-health-system contracts to sustain volume leadership across North American acute care networks. Cardinal Health competes through integrated distribution, anchoring its position by bundling tapes with broader medical-surgical portfolios. Smith & Nephew differentiates via specialty portfolios, dominating advanced silicone and antimicrobial tape segments in European wound clinics.
Healthcare adhesive tapes are pressure-sensitive or biocompatible substrates coated with medical-grade acrylic, silicone, or rubber-based adhesives, designed to adhere to human skin or surgical drapes without causing trauma upon removal; they typically achieve peel adhesion forces of 300-800 g/cm width and breathable moisture vapor transmission rates exceeding 500 g/m²/day to prevent maceration. Their primary purpose spans wound fixation, surgical incision closure, orthopedic support, and device securement across acute and ambulatory settings. Silicone tapes command premium positioning in fragile-skin applications where gentle removal prevents epidermal stripping, while fabric tapes retain cost-driven volume in general hospital settings. Foam tapes represent the fastest-growing structural category as post-surgical drainage and cushioning needs expand in orthopedic and bariatric patient populations.
The FDA enforces biocompatibility testing under ISO 10993 standards for all skin-contact tapes, while the EU MDR requires updated clinical evidence and notified body certification for Class I reusable and Class IIa wound care devices entering European markets. Japan's PMDA maintains distinct pharmaceutical affairs law classifications that delay tape registration timelines relative to US 510(k) pathways. Stakeholders must monitor evolving MDR transition deadlines and FDA guidance on antimicrobial claims to avoid market access disruptions.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins and forcing tape manufacturers to secure direct contracts with integrated delivery networks or risk exclusion from formulary lists entirely.
Growth Catalysts
- EU MDR compliance deadlines:European wound care clinics are accelerating tape upgrades to meet stricter clinical evidence requirements, pulling forward replacement cycles for legacy fabric and rubber-based products.
- Silicone adhesive chemistry:Advanced polymer formulations enable gentle removal from fragile epidermis, expanding tape use in geriatric and neonatal populations previously excluded from adhesive-based interventions.
- Japan's aging demographic:The country's super-aged society generates sustained demand for chronic wound management products in home care and long-term care facility settings.
Market Restraints
- Medical-grade silicone supply concentration:Specialty silicone feedstock production clusters in northeastern China and the German Rhineland, exposing converters to geopolitical freight disruptions and input cost volatility.
- FDA 510(k) pathway friction:Antimicrobial claim substantiation requirements have lengthened premarket notification review timelines, delaying revenue recognition for tape lines with silver or iodine additives.
- Advanced wound dressing substitution:Negative pressure wound therapy systems and hydrocolloid patches capture complex cases that previously required multi-layer tape fixation, narrowing the addressable case mix.
Strategic Opportunities
- Indian domestic manufacturing:The country's PLI scheme for medical devices offers capital subsidies to tape converters establishing local production, circumventing import duties and BIS certification delays for foreign suppliers.
- Wearable device securement:Continuous glucose monitors and cardiac patches require skin-friendly adhesives with 7-14 day wear times, opening a high-margin application beyond traditional wound care.
- Home health channel expansion:Direct-to-patient distribution models bypass hospital procurement gatekeepers, capturing margin previously allocated to group purchasing organization administrative fees.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization studies face backlog at contract research organizations, extending product development timelines by 4-6 months for novel adhesive formulations.
- Legacy ERP integration:Tape manufacturers upgrading to EU MDR-compliant quality management systems encounter data migration friction with decades-old batch record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Adhesive Tapes Market |
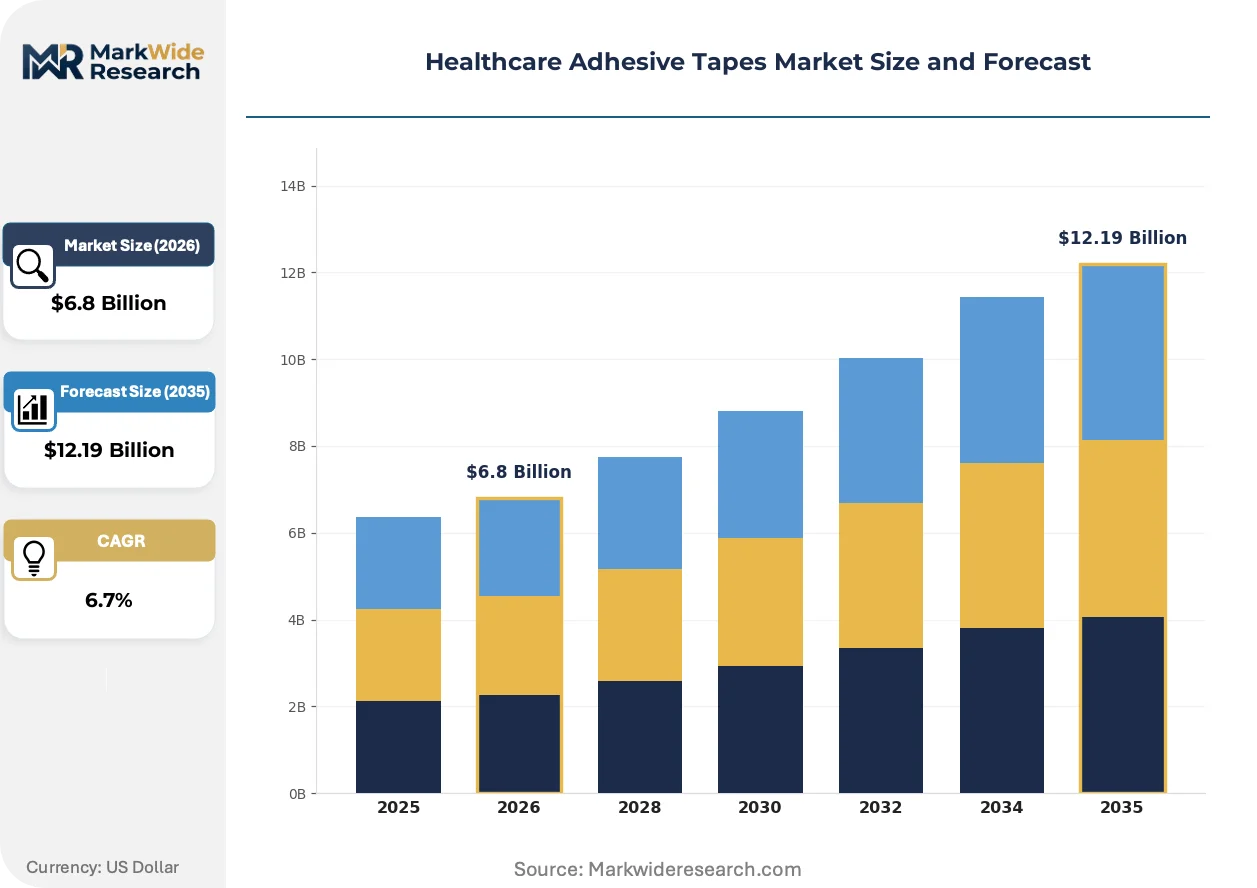
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Tapes, Fabric Tapes, Foam Tapes, Waterproof Tapes Application: Wound Care, Surgical Procedures, Orthopedics, Skin Closure End User: Hospitals, Clinics, Home Health Care, Rehabilitation Centers Technology: Hydrocolloid, Adhesive Bonding, Pressure-Sensitive, Biocompatible |
| Companies Covered | 3M, Solventum, Johnson & Johnson, Cardinal Health, Avery Dennison Corporation, Smith & Nephew, Medline Industries, Nitto Denko Corporation, Lintec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Adhesive Tapes Market Strategic Shifts
Active adhesive technologies are displacing passive substrates as the defining competitive frontier, with smart materials and regulatory automation reshaping product development cycles and go-to-market economics.
Silicone gel adhesive layers with patterned microstructures are rendering obsolete traditional continuous-coat silicone tapes in neonatal intensive care units. Pediatric specialists at academic medical centers in the United States and Germany have adopted these breathable, low-trauma alternatives for premature infant skin monitoring. The shift is compressing R&D investment into legacy silicone chemistries while redirecting technical resources toward biomimetic surface engineering.
Japan's PMDA has tightened pharmaceutical affairs law enforcement for adhesives classified as quasi-drugs, requiring local clinical trials for tapes with antimicrobial or drug-eluting claims. Domestic manufacturers face 18-24 month registration timelines versus 6-9 months for standard mechanical tapes. The regulatory divergence is forcing multinational suppliers to maintain parallel product portfolios: simplified mechanical tapes for Japan and enhanced antimicrobial versions for FDA and EU MDR jurisdictions.
Hospital value analysis committees now mandate total cost-of-ownership documentation spanning application time, removal trauma incidents, and nursing labor hours. This purchasing behavior shift elevates premium silicone and foam tapes over economy fabric alternatives in United States acute care settings. Integrated delivery networks in Texas and Florida have piloted outcome-based vendor contracts tying tape procurement to measured reductions in medical adhesive-related skin injuries.
Healthcare Adhesive Tapes Market Segmentation
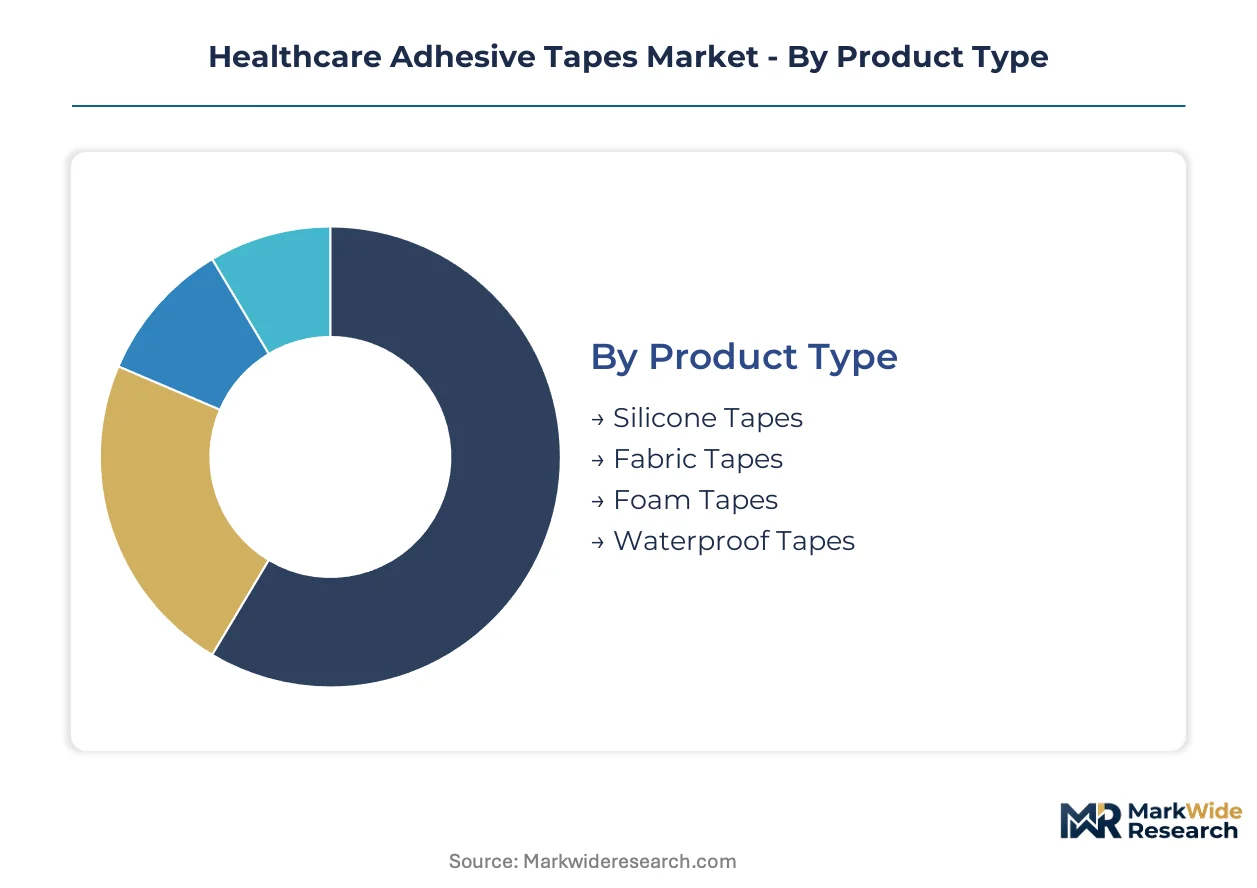
Segmentation in healthcare adhesive tapes reveals how material chemistry, clinical setting, and patient population intersect to determine purchasing decisions and margin structures. Understanding these dimensions exposes where manufacturers can defend premium positioning versus where cost competition dominates procurement.
Product Type:
Mature commodity substrates coexist with emerging specialty formulations as converters balance volume scale against margin expansion.
- Silicone Tapes:Medical-grade polydimethylsiloxane adhesives achieve peel forces below 200 g/cm for trauma-free removal from fragile epidermis. Demand concentrates in neonatal intensive care units across the United States and Germany where epidermal stripping prevention drives formulary preference.
- Foam Tapes:Polyurethane or polyethylene carrier layers with open-cell structures absorb exudate and cushion bony prominences. Post-surgical drainage management in orthopedic and bariatric populations in Japan and the United States accelerates adoption fastest.
- Fabric Tapes:Woven cotton or synthetic backings with rubber-based adhesives serve general hospital fixation at lowest unit cost.
- Waterproof Tapes:Occlusive polymer films with aggressive acrylic bonding protect incision sites during patient bathing and mobility.
Fabric tapes retain volume leadership; foam tapes hold the steepest expansion curve.
Application:
Acute intervention sites generate fundamentally different adhesive performance requirements than chronic management settings.
- Wound Care:Chronic ulcer and pressure injury treatment demands breathable, moisture-managing adhesives with 3-7 day wear times. Home health agencies in Germany and Japan source silicone and hydrocolloid variants for aging patient populations requiring long-term dressing fixation.
- Surgical Procedures:Sterile field draping and incision closure require immediate tack and reliable adhesion under irrigation. Operating rooms in United States academic medical centers prioritize latex-free synthetic rubber formulations to eliminate anaphylaxis risk.
- Orthopedics:Rigid strapping and kinesiology taping for joint stabilization employ high-tensile fabric carriers with zinc oxide adhesives.
- Skin Closure:Surgical incision approximation substitutes tapes for sutures in low-tension wounds, demanding precise peel adhesion control.
Wound care commands the largest addressable base; surgical applications deliver the highest per-procedure value capture.
End User:
Procurement authority concentration varies dramatically across delivery settings, reshaping vendor access economics.
- Hospitals:Integrated delivery networks and group purchasing organizations consolidate buying power across thousands of beds. United States health systems in Texas and Florida have implemented outcome-based contracts tying tape procurement to measured reductions in medical adhesive-related skin injuries.
- Home Health Care:Direct-to-patient distribution bypasses institutional procurement gatekeepers entirely. Japan's super-aged society generates sustained demand for chronic wound management products delivered to residential and long-term care settings.
- Clinics:Outpatient wound centers and surgical suites operate with decentralized purchasing, favoring distributor relationships over direct manufacturer contracts.
- Rehabilitation Centers:Physical therapy and post-acute facilities prioritize cost-efficient bulk purchasing for supportive taping applications.
Hospitals dominate absolute volume; home health care channels expand most quickly as aging demographics shift care location.
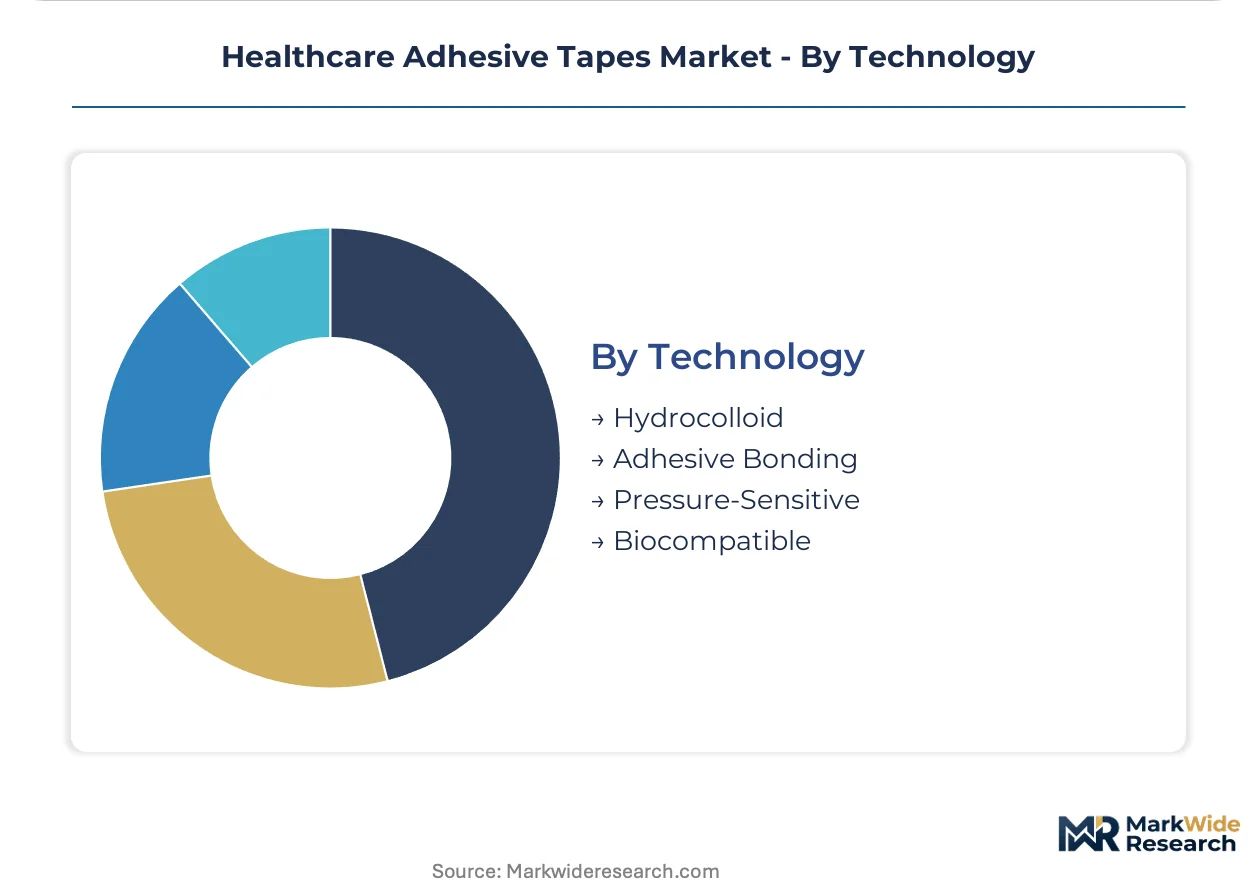
Technology:
Adhesive mechanism selection determines biocompatibility certification pathway and clinical indication breadth.
- Pressure-Sensitive:Tackified elastomer or acrylic formulations bond on light contact without solvent activation or heat. This mature technology serves the broadest indication range across all end-user settings.
- Biocompatible:ISO 10993-tested adhesives eliminate cytotoxicity and sensitization risks for prolonged skin contact. FDA 510(k) and EU MDR compliance requirements extend development timelines but command premium pricing in regulated markets.
- Hydrocolloid:Gel-forming particles integrated into adhesive mass absorb exudate and maintain moist wound healing environments.
- Adhesive Bonding:Structural joining of dissimilar substrates in device assembly applications beyond direct patient contact.
Pressure-sensitive technology anchors current volume; biocompatible formulations gain share fastest as regulatory scrutiny intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German wound care clinics while procurement consolidation compresses margins across United States hospital networks. This asymmetry drives divergent competitive strategies between premium silicone tape specialists and volume fabric tape converters.
United States
Integrated delivery networks in Texas and Florida pilot outcome-based contracts tying tape procurement to measured reductions in medical adhesive-related skin injuries. FDA 510(k) pathway friction for antimicrobial claim substantiation has lengthened premarket notification review timelines. Academic medical centers in Boston and the Research Triangle anchor demand for neonatal silicone tapes with patterned microstructures.
Germany
EU MDR compliance deadlines accelerate tape upgrades across wound care clinics, pulling forward replacement cycles for legacy fabric and rubber-based products. ECHA REACH regulations govern silicone feedstock import certification for converters in the Rhineland industrial cluster. Specialty tape manufacturers in Baden-Württemberg dominate advanced silicone and antimicrobial segments serving European wound clinics.
Japan
The super-aged society generates sustained demand for chronic wound management products in home care and long-term care facility settings. PMDA pharmaceutical affairs law enforcement has tightened for adhesives classified as quasi-drugs, requiring local clinical trials for tapes with antimicrobial claims. Manufacturing concentration in the Kanto region around Tokyo supplies domestic converters with medical-grade substrates.
India
Domestic manufacturing incentives under the PLI scheme for medical devices attract tape converters establishing local production to circumvent import duties and BIS certification delays. CDSCO medical device rules govern skin-contact adhesive registration timelines. Industrial corridors in Maharashtra and Gujarat host emerging converter capacity serving South Asian hospital procurement channels.
China
Specialty silicone feedstock production clusters in northeastern provinces expose converters to geopolitical freight disruptions and input cost volatility. NMPA medical device registration requirements differentiate Class II wound care tapes from general fixation products. Manufacturing hubs in Jiangsu and Zhejiang provinces supply both domestic hospital networks and export markets with fabric and waterproof tape variants.
Healthcare Adhesive Tapes Market Competitive Environment
Diversified healthcare conglomerates and adhesive technology specialists split the market between integrated distribution scale and polymer chemistry depth. The vendor base organizes into three tiers: multinational health systems suppliers with direct-to-hospital contracts, regional converters serving distributor networks, and niche silicone formulation specialists. Consolidation pressures favor players securing group purchasing organization formulary placement or capturing wearable device securement partnerships.
Among diversified healthcare suppliers, 3M leverages direct-to-health-system contracts across North American acute care networks. Cardinal Health competes through integrated distribution, anchoring its position by bundling tapes with broader medical-surgical portfolios. Smith & Nephew exemplifies the specialty archetype, occupying a position in advanced silicone and antimicrobial tape segments where gentle removal and infection control command premium positioning.
| Leading Market Players |
|---|
| 3M |
| Solventum |
| Johnson & Johnson |
| Cardinal Health |
| Avery Dennison Corporation |
| Smith & Nephew |
| Medline Industries |
| Nitto Denko Corporation |
| Lintec Corporation |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight cost volatility transmits directly into silicone tape pricing differentials between Asian converters and European wound clinics, amplifying margin compression for distributors lacking direct manufacturer contracts while enabling integrated suppliers to capture premium positioning through captive logistics control.
Pricing Analysis
The customization-premium spread between configured-to-order silicone tapes and standard fabric SKUs widens as hospital value analysis committees demand total cost-of-ownership documentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 certification tier and volume commitment scale. Pricing pressure stems from group purchasing organization formulary consolidation squeezing regional distributors. Home health agencies exhibit highest price sensitivity; neonatal intensive care units show lowest sensitivity due to medical adhesive-related skin injury liability exposure.
Supply Chain Analysis
Upstream medical-grade silicone feedstock production draws from northeastern China, the German Rhineland, and Japan's Kanto industrial belt. Raw material dependencies center on polydimethylsiloxane resins, woven cotton backings, and acrylic adhesive monomers. Single-source vulnerability concentrates in specialty silicone polymerization capacity. Distribution runs through integrated delivery networks and group purchasing organizations in United States hospital systems, direct-to-patient channels in Japan's home care sector, and distributor networks for European outpatient clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare adhesive tapes function as a service-attach opportunity where clinical training programs and dressing change protocol consulting expand recurring revenue faster than substrate hardware sales alone.
For Market Incumbents: Harden formulary position by securing exclusive direct contracts with integrated delivery networks in Texas and Florida before group purchasing organization consolidation excludes secondary vendors. Deepen backward integration into medical-grade silicone polymerization to offset feedstock cost volatility from northeastern China supply concentration. Anchor portfolio bundles with outcome-based guarantees tying tape procurement to measured reductions in medical adhesive-related skin injuries. For New Entrants and Emerging Players: Build out wearable device securement specialization for continuous glucose monitors and cardiac patches requiring 7-14 day skin-friendly adhesion, the most penetrable white-space segment beyond traditional wound care. Target India's domestic manufacturing incentives under the PLI scheme for medical devices to circumvent import duties and BIS certification delays. Establish clinical validation partnerships with academic medical centers in Boston and the Research Triangle to generate peer-reviewed efficacy data for neonatal silicone applications. For Investors and Strategic Acquirers: Niche silicone formulation specialists with patterned microstructure patents and established neonatal intensive care unit formulary placement represent the priority acquisition archetype for portfolio differentiation. Long-term viability hinges on regulatory automation capabilities enabling rapid EU MDR and FDA 510(k) pathway navigation as antimicrobial claim substantiation requirements tighten. Watch for inflection when hospital value analysis committees in United States academic medical centers mandate total cost-of-ownership documentation as standard procurement practice.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Automation | Accelerates tape registration timelines for Class IIa wound care devices entering European markets through notified body certification streamlining. |
| Silicone Microstructure R&D Investment | Captures neonatal intensive care unit preference in United States and Germany through biomimetic surface engineering differentiation. |
| Indian PLI Scheme Manufacturing Localization | Circumvents BIS certification delays and import duties for South Asian hospital procurement channel access. |
| Wearable Device Securement Partnerships | Opens high-margin application beyond traditional wound care for continuous glucose monitors and cardiac patches. |
| Outcome-Based Hospital Contracts | Ties tape procurement to measured reductions in medical adhesive-related skin injuries in Texas and Florida health systems. |
Study Parameters
A spread of perspectives from hospital purchasing committee members, biomedical engineers specializing in wound care, group purchasing organization contracts managers, and silicone adhesive R&D directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR notified body certification databases, hospital procurement records, and trade customs data for medical-grade silicone feedstock flows. Bottom-up segment sizing triangulated against top-down market aggregation across product type, application, end user, and technology dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling wound care fixation volumes against surgical procedure incidence and home care patient census expansion. Segmentation dimensions spanned material chemistry tier, clinical setting acuity, patient population fragility, and regulatory certification pathway. CAGRs derived from slope-intercept trajectory analysis of historical adoption curves adjusted for EU MDR transition deadlines and Japan's PMDA quasi-drug classification enforcement. Forecast inputs incorporated antimicrobial claim substantiation timeline elongation and silicone feedstock freight cost volatility assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified healthcare conglomerates or sudden PMDA regulatory relaxation for antimicrobial tapes would shift outcomes beyond modeled ranges. Cross-checking against hospital value analysis committee purchasing criteria documentation and GPO contract renewal schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Evidence Collection Tubes Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Sequencing Consumables Market
Medical Supplies
Cell Culture Media Storage Containers Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Suture Tapes Market
Medical Supplies
Glass Pasteur Pipettes Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Suture Wire Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
Cell Culture Media Bags Market
Medical Supplies
Therapeutic Elastic Tapes Market
Medical Supplies
Americas Medical Rubber and Balloon Product Market