
 AI in Patient Engagement Market | 2026-2036
AI in Patient Engagement Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Patient Engagement Market Analytics
Cloud distribution channels are reshaping how AI patient engagement platforms reach hospital buyers. Epic Systems Corporation leverages its entrenched EHR footprint to embed AI workflows directly into clinical documentation. Microsoft anchors enterprise-grade Azure infrastructure for health systems requiring HIPAA-compliant scalability. Nuance Communications specializes in ambient clinical intelligence that feeds downstream engagement algorithms.
AI in patient engagement denotes software systems that apply natural language processing, predictive analytics, and machine learning to automate, personalize, and sustain interactions between patients and care teams across pre-visit, acute, and post-discharge phases. These platforms process structured and unstructured health data to generate risk scores, trigger outreach, and tailor educational content to individual adherence profiles. Chatbot deployments now dominate front-end patient access workflows, while predictive analytics commands premium positioning by stratifying populations for proactive intervention. Remote monitoring applications represent the fastest-expanding segment as reimbursement codes mature for continuous physiologic surveillance outside facility walls.
FDA software-as-a-medical-device frameworks and HIPAA security rules jointly determine which AI engagement tools gain market access in the United States. The EU AI Act and GDPR impose additional conformity requirements for vendors serving European health systems, forcing architectural decisions around data residency and algorithmic transparency. Stakeholders must monitor whether emerging FDA guidance on adaptive AI will require continuous validation protocols that reshape development economics.
Market Dynamics
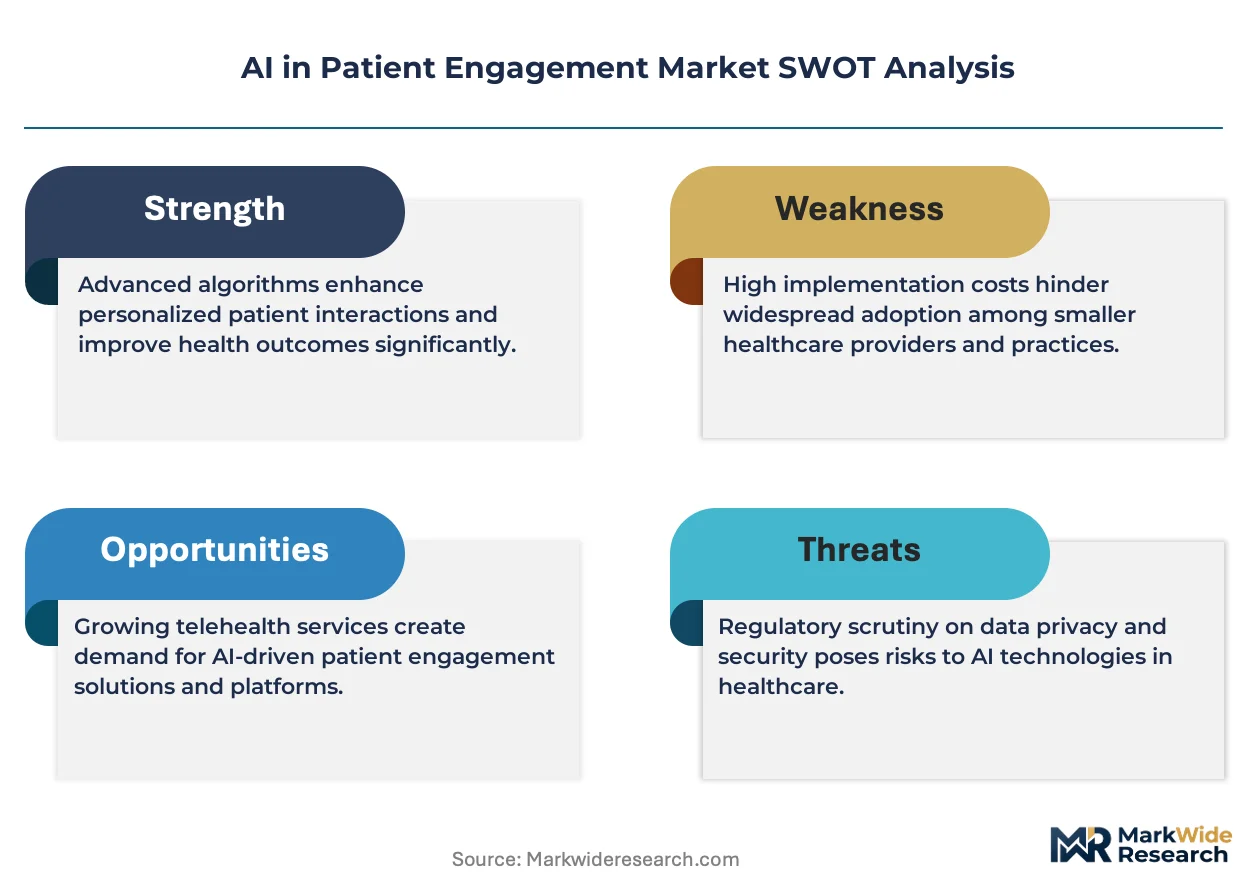
The FDA's software-as-a-medical-device guidance is compressing commercialization timelines for AI patient engagement vendors, forcing architectural choices between locked algorithms and adaptive learning systems that require continuous validation protocols.
Growth Catalysts
- CMS reimbursement expansion:New billing codes for remote physiologic monitoring are pulling capital into continuous surveillance platforms that feed AI engagement engines.
- Interoperability mandates:The 21st Century Cures Act information blocking rules are prying open EHR data silos, enabling third-party AI tools to ingest clinical records for risk stratification.
- Chronic disease burden:Diabetes and heart failure populations in the United States are driving demand for automated outreach that sustains medication adherence between specialist visits.
Market Restraints
- Algorithmic bias liability:FDA premarket review pathways for machine learning-based software devices create legal exposure when training data underrepresents minority populations.
- Cloud infrastructure concentration:HIPAA-compliant hosting options cluster among three hyperscale providers, creating single-point-of-failure risk for patient data pipelines.
- Clinician workflow friction:Alert fatigue from poorly tuned predictive models degrades trust in AI-generated care recommendations.
Strategic Opportunities
- Mental health integration:Anxiety and depression screening chatbots represent an underpenetrated application where natural language processing can bridge access gaps in rural counties.
- EU AI Act readiness:Conformity assessment frameworks for high-risk medical AI create first-mover advantage for vendors that architect explainability features early.
- Voice biomarker convergence:Combining ambient clinical intelligence with vocal stress analysis opens new diagnostic channels for early cognitive decline detection.
Industry Challenges
- Health informatics talent scarcity:The hybrid skill set bridging clinical knowledge and machine learning engineering commands premium compensation that mid-size vendors struggle to match.
- Legacy EHR integration complexity:Custom HL7 FHIR mapping projects consume six to twelve months per health system deployment, delaying recurring revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Patient Engagement Market |
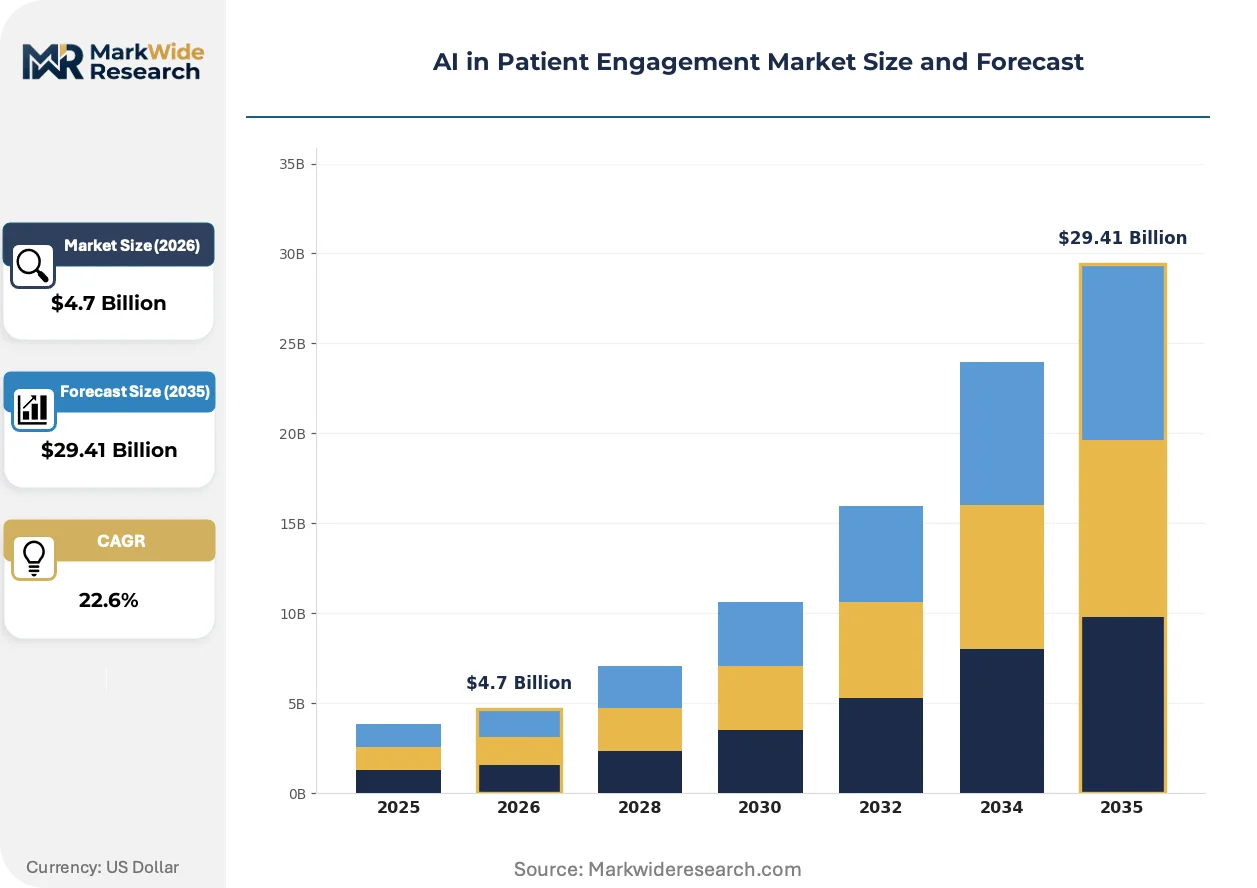
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Natural Language Processing, Chatbots, Predictive Analytics, Machine Learning Application: Remote Monitoring, Medication Management, Appointment Scheduling, Patient Education End User: Healthcare Providers, Patients, Caregivers, Health Insurance Companies Deployment: Cloud-based, On-premises, Hybrid, Mobile Applications |
| Companies Covered | IBM, Oracle, Microsoft, Epic Systems Corporation, Salesforce, Nuance Communications, Innovaccer, Health Catalyst, Notable Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Patient Engagement Market Evolving Landscape
Generative AI architectures are displacing rules-based chatbots across patient access workflows, compressing development cycles for conversational interfaces while raising new questions about hallucination risk in clinical contexts.
Ambient clinical intelligence is digitizing the exam room encounter, capturing physician-patient dialogue through edge devices and structuring unstructured data for downstream engagement algorithms. Health systems in the United States are deploying these systems in primary care networks to automate documentation burden. This technology is digitizing the clinical narrative itself, transforming spoken interaction into queryable data that feeds predictive outreach.
The EU AI Act's high-risk system classification is forcing architectural pivots for vendors serving European health systems, mandating human oversight mechanisms and conformity assessment procedures that add twelve to eighteen months to product launches. Medical device manufacturers are responding by segregating algorithm training environments by geography to satisfy data residency requirements. French and German hospital procurement teams now weight explainability documentation heavily in competitive tenders.
Integrated delivery networks are consolidating vendor relationships around platforms that bundle predictive analytics with care coordination workflows, displacing point solutions that handle only scheduling or only risk scoring. Health systems in California and Texas are demanding unified patient records that span acute, ambulatory, and home settings. This concentration of procurement authority favors enterprise-grade platforms with established EHR connectors over niche specialists.
AI in Patient Engagement Market Segmentation
Segmentation reveals how AI patient engagement platforms align technical capabilities with specific care workflows. Vendors configure modular architectures around technology cores, application targets, and deployment constraints to match buyer infrastructure and regulatory requirements.
Technology:
Use-case spectrum spans conversational interfaces through predictive risk engines, with each technology commanding distinct integration protocols and validation requirements.
- Natural Language Processing:Core engine for parsing unstructured clinical notes, patient messages, and voice interactions into structured data elements. Epic Systems and Cerner deployments in Texas and California health systems drive concentrated demand for clinical documentation NLP.
- Chatbots:Rules-based and generative conversational agents handling appointment triage, symptom checking, and administrative queries. Front-end patient access workflows at integrated delivery networks prioritize 24/7 automated response capacity.
- Predictive Analytics:Algorithms stratifying populations for readmission risk, no-show probability, and deterioration signals. Machine learning models processing EHR feeds and claims data command premium positioning in Medicare Advantage contracts.
- Machine Learning:Adaptive systems refining engagement timing and channel selection based on individual response patterns. FDA software-as-a-medical-device frameworks impose continuous validation protocols on self-learning deployments.
Established volume favors chatbots; emerging adoption favors predictive analytics.
Application:
Cost tier segmentation separates infrastructure-heavy continuous monitoring from lightweight administrative automation.
- Remote Monitoring:Continuous physiologic surveillance via connected devices feeding AI triage algorithms. CMS reimbursement codes for remote patient monitoring pull capital into platforms integrating glucose meters, blood pressure cuffs, and pulse oximeters with automated escalation protocols.
- Medication Management:Adherence tracking through smart packaging, refill prompts, and side-effect reporting. Pharmacy benefit managers and specialty pharmacies deploy these tools for high-cost biologics in oncology and immunology.
- Appointment Scheduling:Intelligent routing matching patient preferences with provider capacity and clinical urgency. Health systems in Florida and Arizona leverage these tools to reduce no-show rates in value-based care contracts.
- Patient Education:Personalized content delivery adapting to health literacy levels and cultural preferences. Medicaid managed care organizations prioritize multilingual educational modules for chronic disease populations.
Revenue concentration sits with remote monitoring infrastructure; margin expansion favors medication management adherence tools.
End User:
Customer type determines purchasing authority, with healthcare providers controlling capital budgets and health insurers driving population-scale procurement.
- Healthcare Providers:Hospitals, physician groups, and integrated delivery networks acquiring enterprise platforms. Mayo Clinic and Kaiser Permanente anchor demand for unified patient records spanning acute, ambulatory, and home settings.
- Patients:Direct-to-consumer applications for chronic condition self-management and wellness tracking. Diabetes and heart failure populations in the United States represent addressable demand for automated coaching between specialist visits.
- Caregivers:Family members and home health aides coordinating care transitions and medication schedules. AARP-aligned platforms target adult children managing aging parent care across dispersed geographies.
- Health Insurance Companies:Payers deploying engagement tools to reduce emergency department utilization and improve HEDIS scores. UnitedHealth Group and Anthem invest in predictive outreach for high-risk member stratification.
Procurement scale favors healthcare providers; growth velocity favors health insurance company population health contracts.
Deployment:
Maturity segmentation contrasts proven cloud architectures with emerging edge computing models for latency-sensitive applications.
- Cloud-based:HIPAA-compliant hosting on Azure, AWS, or Google Cloud with API-based EHR integration. Hyperscale concentration creates single-point-of-failure risk for patient data pipelines.
- On-premises:Local server installations satisfying strict data residency requirements and air-gapped security protocols. Veterans Affairs facilities and defense health systems mandate on-premises deployment for classified or sensitive populations.
- Hybrid:Split architectures processing PHI in private clouds while leveraging public infrastructure for analytics and model training. EU AI Act data residency rules force geographic segregation of algorithm training environments.
- Mobile Applications:Native iOS and Android clients enabling patient-facing engagement outside facility walls. Smartphone penetration and 5G latency improvements expand addressable markets for real-time symptom monitoring.
Deployment share concentrates in cloud-based architectures; regulatory pressure favors hybrid models for cross-border operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' dense fiber-optic backbone and hyperscale cloud regions in Virginia, Oregon, and Ohio underwrite its dominance in health AI infrastructure. Hospital systems in Dallas, Boston, and San Francisco anchor procurement for conversational platforms that integrate with Epic and Cerner deployments. FDA software-as-a-medical-device guidance shapes vendor compliance investments, while HIPAA security rules determine hosting architecture choices for patient data pipelines.
United States
Integrated delivery networks in California and Texas prioritize automated care coordination to reduce readmission penalties under CMS value-based programs. The FDA's evolving guidance on adaptive AI systems forces architectural choices between locked algorithms and continuous learning models requiring validation protocols. Mayo Clinic in Minnesota and Kaiser Permanente across the West Coast anchor demand for unified patient records spanning acute, ambulatory, and home settings.
Germany
Hospital groups in Bavaria and North Rhine-Westphalia deploy AI engagement tools to manage chronic disease populations within statutory health insurance frameworks. The EU AI Act's high-risk system classification mandates human oversight mechanisms and conformity assessment procedures that extend product launch timelines. Berlin-Brandenburg health technology clusters concentrate vendor development activity for explainable AI features that satisfy procurement weighting in French and German tenders.
United Kingdom
NHS Integrated Care Systems in London and the Midlands pilot conversational AI to reduce administrative burden on primary care networks facing workforce shortages. NHS England's guidance on AI deployment in clinical settings shapes procurement specifications for algorithmic transparency and bias auditing. The Cambridge-Oxford-London health technology corridor concentrates startup activity for natural language processing applications in patient access workflows.
France
Hospital networks in Île-de-France and Auvergne-Rhône-Alpes invest in remote monitoring infrastructure to manage heart failure and diabetes populations under regional health agency contracts. ANSM and CNIL joint oversight of medical AI and data protection creates layered compliance requirements for vendors serving French health systems. The Paris-Saclay cluster concentrates research activity for voice biomarker applications in early cognitive decline detection.
Canada
Provincial health authorities in Ontario and Quebec deploy AI engagement platforms to coordinate care transitions for aging populations in rural and remote communities. Health Canada and provincial privacy commissioners jointly regulate software-as-a-medical-device classifications and health data residency requirements. Toronto's MaRS Discovery District and Montreal's AI research institutes anchor vendor development partnerships for French-English bilingual conversational interfaces.
AI in Patient Engagement Market Competitive Landscape
On the supply side, the industry is consolidating around enterprise-grade platforms that bundle predictive analytics with EHR-integrated workflows, displacing point solutions that handle only scheduling or risk scoring in isolation. Three strategic archetypes dominate: hyperscale cloud providers anchoring HIPAA-compliant infrastructure, EHR-embedded workflow specialists leveraging entrenched hospital relationships, and natural language processing vendors feeding ambient clinical intelligence into downstream engagement algorithms. Competitive dynamics center on strategic partnerships with integrated delivery networks and portfolio diversification into remote monitoring reimbursement streams.
Within the EHR-embedded tier, Epic Systems Corporation exemplifies platform consolidation through its entrenched footprint in Texas and California health systems. Microsoft anchors enterprise-grade cloud infrastructure for health systems requiring HIPAA-compliant scalability across multi-state networks. Nuance Communications occupies a position among ambient clinical intelligence specialists whose structured data outputs feed predictive engagement algorithms. These three represent the dominant competitive anchors shaping procurement patterns among North American hospital buyers.
| Leading Market Players |
|---|
| IBM |
| Oracle |
| Microsoft |
| Epic Systems Corporation |
| Salesforce |
| Nuance Communications |
| Innovaccer |
| Health Catalyst |
| Notable Health |
| Others |
Value Network & Pricing Analysis
Underutilized cloud compute capacity in US West Coast hyperscale regions is compressing infrastructure costs for AI patient engagement vendors while simultaneously enabling aggressive SaaS pricing postures that lock hospital systems into long-term contracts.
Pricing Analysis
Volume-discount tiering structures separate enterprise health systems purchasing predictive analytics suites from mid-size hospitals acquiring standalone chatbot modules. Three-tier pricing stratifies across premium adaptive-learning platforms, standard rules-based deployments, and economy-tier administrative automation tools. Price differentiation hinges on FDA software-as-a-medical-device certification status and integration depth with Epic or Cerner EHRs. Pricing pressure stems from consolidation among integrated delivery networks demanding bundled platform discounts, while federally qualified health centers exhibit highest price sensitivity due to constrained capital budgets.
Supply Chain Analysis
Upstream feedstock for AI patient engagement platforms draws from specialized semiconductor fabrication in Taiwan, South Korea, and the United States for GPU clusters powering machine learning training. NVIDIA tensor processing units, high-bandwidth memory modules from SK Hynix, and custom ASICs from Google Cloud TPU operations constitute critical component dependencies. Single-source vulnerability concentrates in Taiwan Semiconductor Manufacturing for advanced node production. Distribution runs through HIPAA-compliant hosting partnerships with Microsoft Azure, AWS, and Google Cloud, supplemented by systems integrators like Accenture and Deloitte for hospital deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated delivery networks consolidating procurement authority across multi-state footprints, fragmenting vendor relationships and compressing pricing for point solutions lacking comprehensive platform breadth.
For Market Incumbents: Insulate recurring revenue streams by embedding AI workflows directly into EHR documentation pipelines that health systems cannot easily displace. Acquire ambient clinical intelligence specialists to capture unstructured data feeds before competitors structure competing engagement algorithms. Counter emerging threats from generative AI-native entrants by accelerating FDA premarket submissions for locked-algorithm configurations that reduce validation burden for hospital buyers. For New Entrants and Emerging Players: Rural county mental health networks in the United States represent the most penetrable entry point for anxiety and depression screening chatbots where natural language processing bridges specialist access gaps. EU AI Act readiness creates first-mover positioning for explainable AI features in French and German hospital procurement cycles. Pursue direct contracting with pharmacy benefit managers for medication management adherence tools rather than competing for capital-intensive hospital platform deals. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among predictive analytics vendors with Medicare Advantage risk-stratification contracts that renew annually. Long-term viability across a 5-10 year window favors platforms bundling remote monitoring reimbursement capture with care coordination workflows. Monitor FDA guidance on adaptive AI continuous validation protocols as the critical inflection signal determining development economics for machine learning-based engagement tools.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Locked-algorithm configurations reduce validation burden and accelerate hospital procurement cycles. |
| Epic Systems Integration Partnership | Embedded AI workflows in EHR documentation pipelines create high-switching-cost customer relationships. |
| Remote Monitoring Reimbursement Strategy | CMS billing code capture for continuous physiologic surveillance expands addressable revenue streams. |
| EU AI Act Conformity Assessment | Explainability documentation satisfies French and German hospital procurement weighting requirements. |
| Ambient Clinical Intelligence Acquisition | Structured voice data feeds downstream predictive engagement algorithms with proprietary input streams. |
Research Methodology
A spread of perspectives from hospital CIOs, health system procurement committees, FDA regulatory affairs specialists, and Medicare Advantage plan executives converged on the working assumptions shaping this analysis. Primary interviews with biomedical engineers and GPO contracts managers combined with secondary validation against FDA 510(k) filings, CMS reimbursement code databases, hospital procurement records, and Epic Systems integration documentation. Bottom-up deployment counts across integrated delivery networks triangulated against top-down market sizing from hyperscaler health cloud revenue disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling technology segmentation by natural language processing, chatbot, predictive analytics, and machine learning architectures alongside application dimensions spanning remote monitoring, medication management, and patient education. Deployment models separated cloud-based, on-premises, hybrid, and mobile application configurations. CAGRs derived from patient population growth in chronic disease segments, CMS reimbursement expansion trajectories, and EHR interoperability mandate implementation timelines.
Practitioners should monitor FDA adaptive AI guidance revisions, EU AI Act enforcement patterns, and integrated delivery network consolidation announcements for early signals requiring forecast reassessment. Cross-checking against hospital capital expenditure surveys and health IT trade association deployment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
Advanced Clinical Decision Support Platforms Market
Digital Health Solutions
Global Plastic Surgery Software Market
Digital Health Solutions
Digital Biomarkers Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
Global Smart Hospital Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Mhealth Apps Market
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
Mixed Reality in Healthcare Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Amblyopia Treatment Softwares Market