
 North America Mobile Health (Mhealth) Market | 2026-2036
North America Mobile Health (Mhealth) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mobile Health (Mhealth) Market Analytics
Subscription-based leasing for connected medical devices is fragmenting traditional capital expenditure barriers in remote patient monitoring. Medtronic PLC anchors its competitive position through backward integration into sensor manufacturing and proprietary data analytics platforms. Apple Inc. leverages its consumer electronics ecosystem to bridge wellness tracking with clinical-grade data pipelines. Philips N.V. sustains hospital system relationships through enterprise-scale telehealth infrastructure deployments.
Mobile health encompasses wireless-enabled technologies that capture, transmit, and analyze physiological data through FDA-cleared algorithms operating on smartphones, wearables, and cloud-connected diagnostic peripherals. The architecture relies on Bluetooth Low Energy protocols, encrypted HL7 FHIR data exchange, and rechargeable lithium-polymer power systems to enable continuous ambulatory monitoring outside clinical settings. Wearable Devices and Remote Monitoring Tools command the deepest margin pools due to recurring data subscription revenues and hardware replacement cycles. mHealth Apps face structural pressure from platform fees and reimbursement uncertainty despite user volume leadership. Telehealth Solutions retain enterprise stickiness through EHR integration requirements and clinician workflow embedding.
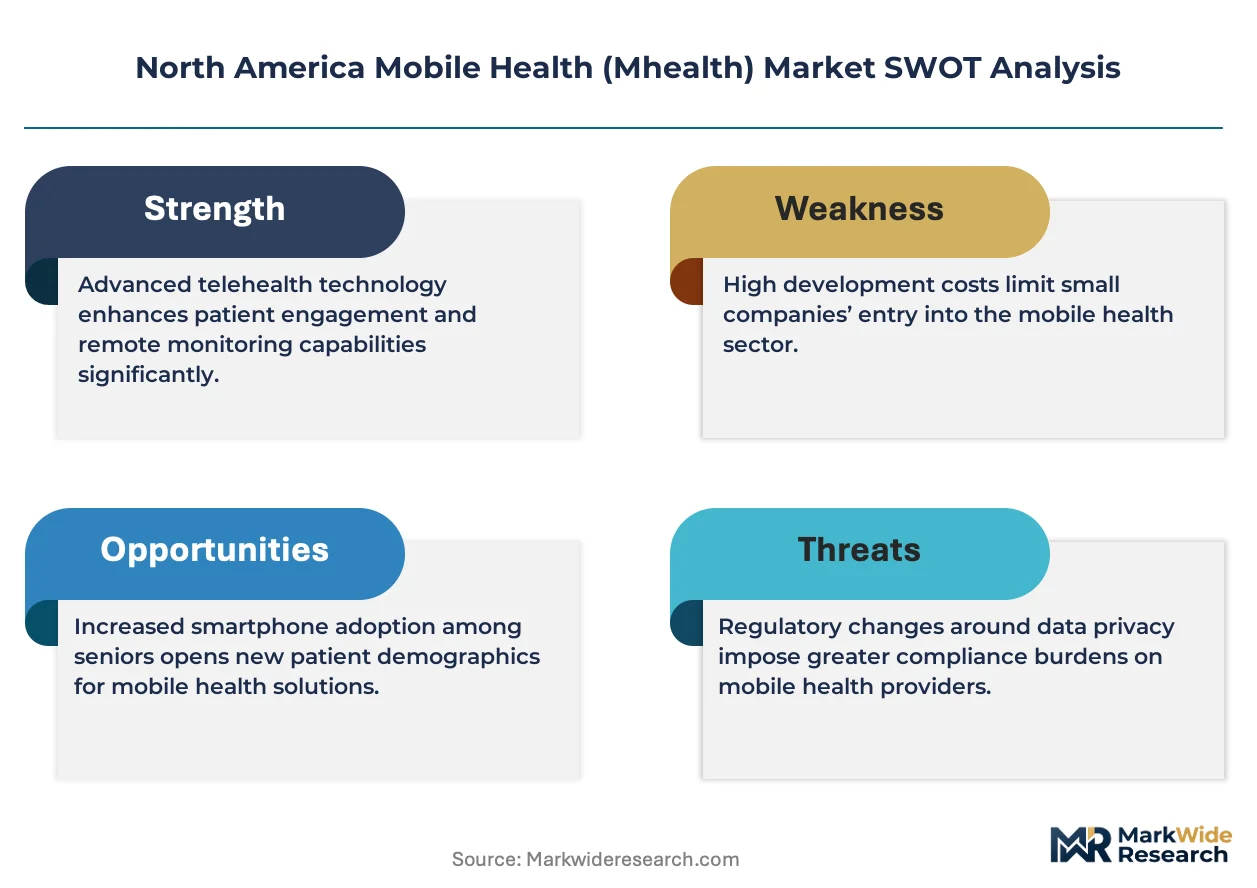
FDA software-as-a-medical-device frameworks and CMS remote therapeutic monitoring reimbursement codes jointly determine which platforms achieve sustainable revenue models in the United States. Health Canada and the Office for Civil Rights HIPAA enforcement shape cross-border data architecture requirements and liability exposure for multi-jurisdictional deployments. Stakeholders must monitor evolving state-level telehealth parity legislation and FDA artificial intelligence guidance to anticipate which delivery modalities secure durable reimbursement pathways.
Market Dynamics
FDA software-as-a-medical-device frameworks and CMS remote therapeutic monitoring reimbursement codes are restructuring how mHealth platforms monetize, privileging those with clinical-grade validation over consumer wellness applications.
Growth Catalysts
- CMS Remote Monitoring Reimbursement:Medicare Advantage plans now cover continuous glucose monitors and blood pressure cuffs for home use, expanding addressable patient populations beyond traditional clinic-based care.
- Bluetooth Low Energy Protocol Maturation:Improved power efficiency enables multi-day continuous monitoring on single charges, reducing patient adherence barriers for ambulatory cardiac and respiratory tracking.
- California Digital Health Corridor:Venture concentration in San Francisco and San Diego accelerates FDA-cleared algorithm development through proximity to regulatory consultants and clinical trial networks.
Market Restraints
- Lithium-Polymer Supply Concentration:Battery cell production for wearable sensors concentrates among East Asian suppliers, exposing hardware manufacturers to input cost volatility and logistics disruptions.
- HIPAA State-Level Fragmentation:Variation in privacy enforcement across state attorneys general creates compliance complexity for multi-jurisdictional deployments, particularly for cloud-hosted patient data.
- Platform Fee Extraction:Apple App Store and Google Play commission structures compress margins for mHealth app developers, diverting resources from clinical validation investments.
Strategic Opportunities
- Mental Health Integration:Remote therapeutic monitoring codes now cover psychiatric medication adherence and mood tracking, opening reimbursement pathways previously restricted to physiological metrics.
- Boston-Cambridge Medtech Cluster:Proximity to Massachusetts General Hospital and MIT Media Lab enables rapid clinical validation partnerships for AI diagnostic algorithms.
- HL7 FHIR Data Interoperability:Standardized health record exchange protocols reduce EHR integration costs, lowering barriers for telehealth platforms seeking hospital system adoption.
Industry Challenges
- FDA 510(k) Timeline Compression:Software-as-a-medical-device submissions face extended review periods as artificial intelligence algorithms require novel predicate device comparisons, delaying commercialization.
- Clinical Workflow Embedding:Telehealth platforms struggle to demonstrate time savings for clinicians accustomed to in-person examination protocols, slowing enterprise adoption despite administrative enthusiasm.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mobile Health (Mhealth) Market |
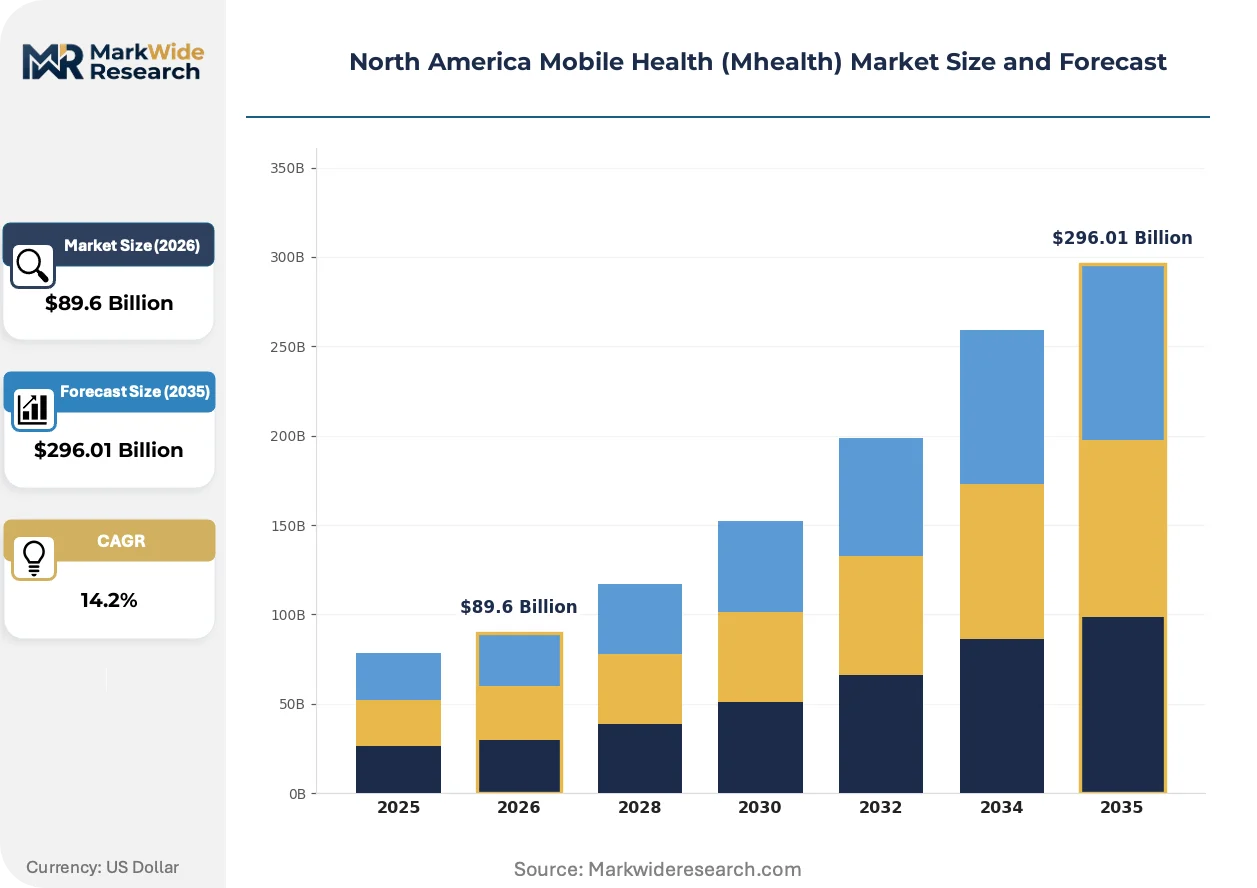
| Market Size in 2026 | $89.6 Billion |
| Market Size in 2035 | $296.01 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wearable Devices, mHealth Apps, Telehealth Solutions, Remote Monitoring Tools Product Type: Fitness Trackers, Blood Pressure Monitors, Glucose Meters, Medication Management Systems End User: Patients, Healthcare Providers, Payers, Enterprises Delivery Mode: Cloud-Based, On-Premises, Hybrid, Mobile Applications |
| Companies Covered | Boston Scientific Corporation, Koninklijke Philips N.V., Medtronic PLC, AT&T Inc., Veradigm, Apple Inc., Fitbit, Inc., Abbott, Omron Healthcare, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mobile Health (Mhealth) Market Evolving Landscape
Continuous ambulatory monitoring architectures are displacing episodic clinical measurements, embedding physiological tracking into daily routines through imperceptible form factors and automated data transmission.
Photoplethysmography sensors embedded in smart rings and earbuds are digitizing cardiovascular surveillance. Medicare Advantage plans covering these devices for atrial fibrillation screening are accelerating patient adoption beyond early tech enthusiasts. The technology is compressing time-to-diagnosis for arrhythmias while generating longitudinal datasets that pharmaceutical sponsors purchase for real-world evidence generation.
FDA's evolving guidance on machine-learning-enabled diagnostic software is reshaping algorithm development roadmaps. Developers must now document locked versus continuously learning model architectures prior to 510(k) submission, forcing upfront design commitments that constrain post-market adaptation flexibility. Cardiology and dermatology applications face the steepest compliance burden given higher-risk classification thresholds.
Hospital procurement committees are unbundling telehealth infrastructure from EHR vendor bundles, creating openings for standalone platforms with superior clinician workflow integration. Health systems in Texas and Florida lead this disintermediation, driven by value-based care contracts requiring measurable readmission reduction. Vendors demonstrating quantifiable nursing time savings secure multi-year enterprise agreements faster than those competing on feature breadth alone.
North America Mobile Health (Mhealth) Market Segmentation
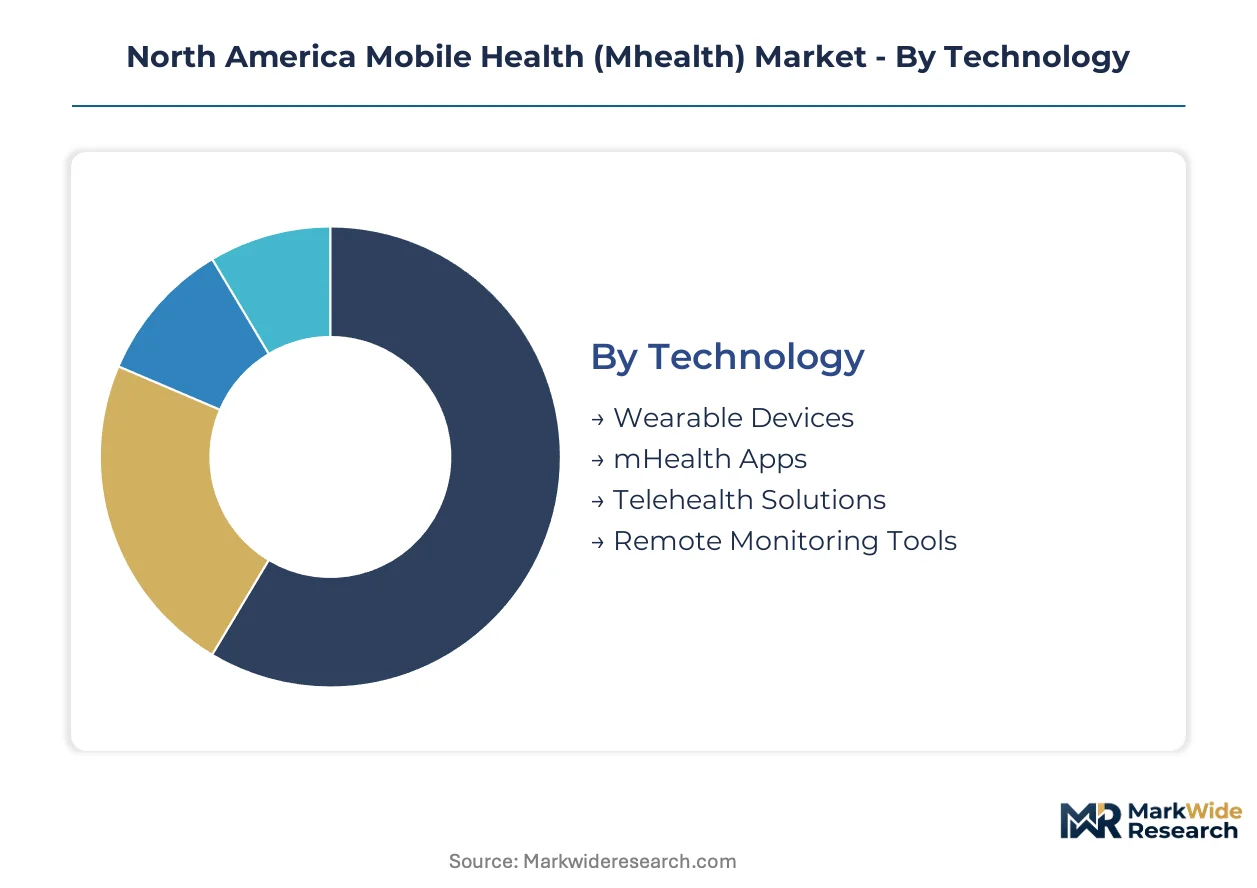
Segmentation in North American mHealth reveals divergent margin profiles and regulatory burdens across technology platforms. Each category demands distinct commercial strategies shaped by reimbursement pathways, hardware replacement cycles, and clinical validation requirements.
Technology:
After-sales service intensity varies dramatically across technology segments, with hardware-dependent categories requiring field calibration support and software platforms demanding continuous security patching and API maintenance.
- Wearable Devices:Photoplethysmography sensors, accelerometers, and rechargeable lithium-polymer power systems embedded in wrist-worn or ring-form factors capture continuous physiological streams. California's digital health corridor concentrates FDA-cleared algorithm development for cardiac and metabolic monitoring, driven by Medicare Advantage coverage expansion for home-based diagnostic peripherals.
- Remote Monitoring Tools:Bluetooth Low Energy-enabled peripherals including blood pressure cuffs, pulse oximeters, and weight scales transmit encrypted data to cloud analytics platforms. Texas and Florida health systems lead enterprise procurement for readmission reduction programs under value-based care contracts, prioritizing vendors with quantifiable nursing workflow integration.
- mHealth Apps:FDA-regulated software running on iOS and Android platforms delivers medication adherence prompts, symptom tracking, and patient education modules.
- Telehealth Solutions:Enterprise-scale video consultation infrastructure with EHR integration and clinician scheduling systems serves hospital network deployments.
By volume, mHealth Apps leads. By growth pace, Remote Monitoring Tools is ahead.
Product Type:
Cost tier stratification separates premium clinical-grade peripherals from consumer wellness accessories, with reimbursement eligibility determining addressable market scale.
- Glucose Meters:Continuous glucose monitoring systems with factory-calibrated sensors and smartphone-connected receivers enable real-time glycemic management without fingerstick calibration. Medicare Advantage plans in Massachusetts and California now cover these devices for Type 2 diabetes populations beyond insulin-dependent patients, expanding reimbursement-qualified user bases.
- Medication Management Systems:Smart pill dispensers with cellular connectivity and adherence sensors alert caregivers and clinicians to dosing deviations. Florida's aging population concentration drives skilled nursing facility adoption for polypharmacy reduction, supported by remote therapeutic monitoring reimbursement codes.
- Fitness Trackers:Consumer-grade accelerometer and heart rate monitors for wellness goal tracking without clinical diagnostic claims.
- Blood Pressure Monitors:Upper-arm and wrist-worn oscillometric devices with automated data transmission for hypertension management programs.
By installed base, Fitness Trackers dominates. By revenue per unit, Glucose Meters commands premium positioning.
End User:
Customer type dictates purchasing authority and evaluation criteria, with clinical validation requirements escalating from consumer self-pay to enterprise procurement committees.
- Healthcare Providers:Hospital systems, physician practices, and accountable care organizations procure FDA-cleared platforms with EHR interoperability and liability coverage. The Boston-Cambridge medtech cluster anchors clinical validation partnerships for AI diagnostic algorithms, with Massachusetts General Hospital and MIT Media Lab enabling rapid regulatory pathway navigation.
- Payers:Medicare Advantage plans and commercial insurers negotiate device coverage policies and remote monitoring reimbursement rates based on actuarial evidence of readmission reduction.
- Patients:Individual consumers purchasing direct-to-consumer wellness trackers and subscription health coaching applications.
- Enterprises:Self-insured employers deploying population health programs for workforce productivity and insurance cost containment.
By contract value, Healthcare Providers leads. By growth pace, Payers is expanding most quickly.
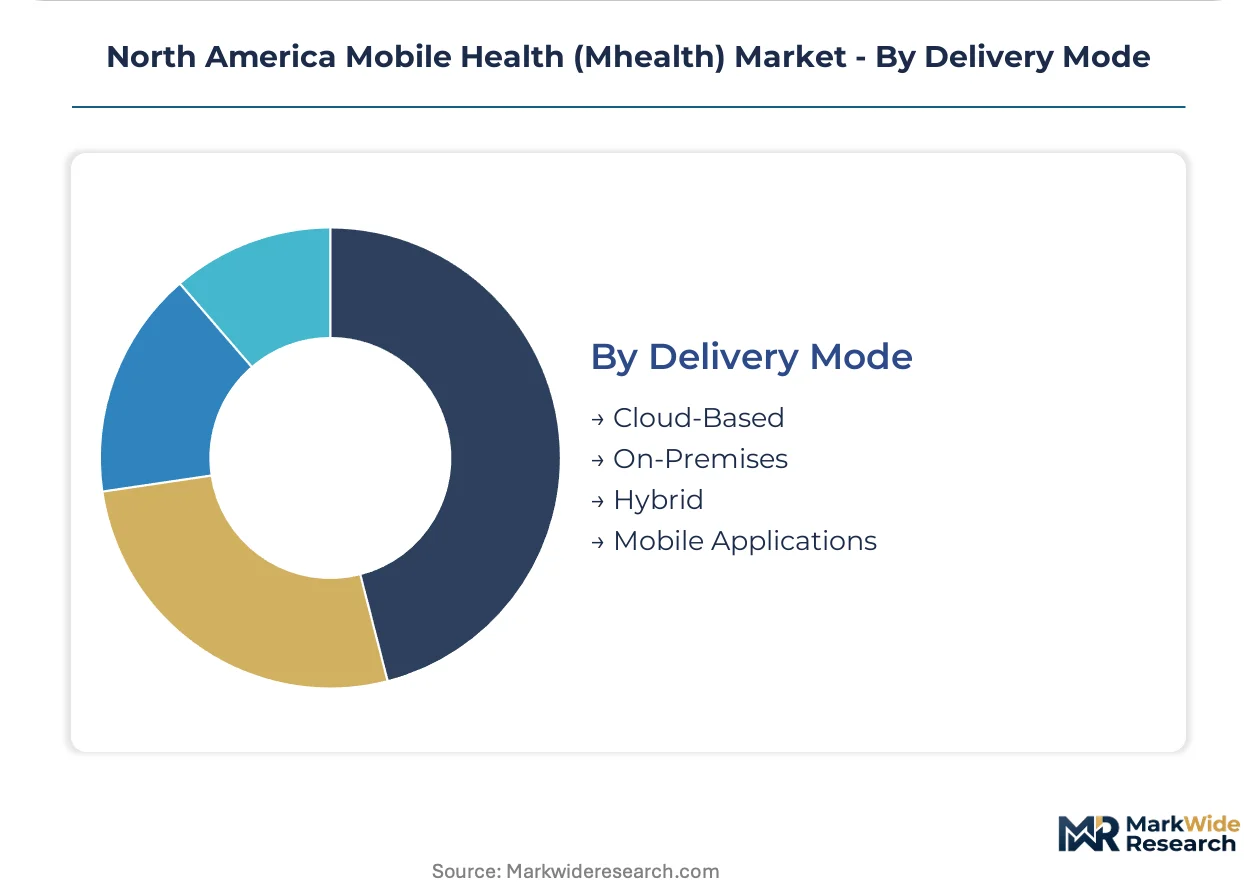
Delivery Mode:
Architecture decisions trade data sovereignty against scalability, with HIPAA compliance complexity escalating for cloud-hosted deployments across state jurisdictions.
- Cloud-Based:Multi-tenant SaaS platforms with automated scaling, continuous security updates, and HL7 FHIR data exchange capabilities reduce IT infrastructure burdens for mid-size health systems. State-level HIPAA enforcement fragmentation creates compliance complexity for multi-jurisdictional deployments, particularly when patient data crosses California, Texas, and Massachusetts regulatory boundaries.
- Hybrid:Edge computing architectures process sensitive biometric data locally while transmitting anonymized analytics to cloud dashboards, addressing latency and privacy requirements for cardiology monitoring.
- On-Premises:Dedicated server installations within health system data centers for maximum data control and customized security policies.
- Mobile Applications:Native iOS and Android clients with offline functionality and periodic synchronization for patient-facing engagement tools.
By deployment count, Cloud-Based leads. By security-driven selection, Hybrid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America runs a technology surplus in mobile health hardware and software, importing lithium-polymer battery cells from East Asian suppliers while exporting FDA-cleared diagnostic algorithms and enterprise telehealth platforms to European and Asia-Pacific markets.
United States
Medicare Advantage plans in Massachusetts and California now reimburse continuous glucose monitors for Type 2 diabetes populations beyond insulin-dependent patients. FDA software-as-a-medical-device frameworks privilege clinical-grade validation over consumer wellness applications, compressing review timelines for AI-enabled diagnostic submissions. The Boston-Cambridge medtech cluster anchors rapid clinical validation partnerships through proximity to Massachusetts General Hospital and MIT Media Lab.
California
San Francisco and San Diego venture concentration accelerates FDA-cleared algorithm development through proximity to regulatory consultants and clinical trial networks. State-level HIPAA enforcement creates compliance complexity for cloud-hosted patient data crossing into Texas and Massachusetts jurisdictions. The digital health corridor generates longitudinal cardiovascular datasets that pharmaceutical sponsors purchase for real-world evidence generation.
Texas
Health systems in Dallas and Houston lead enterprise telehealth procurement unbundling from EHR vendor bundles, driven by value-based care contracts requiring measurable readmission reduction. State-level telehealth parity legislation shapes durable reimbursement pathways for remote therapeutic monitoring. Vendors demonstrating quantifiable nursing time savings secure multi-year enterprise agreements faster than competitors competing on feature breadth alone.
Massachusetts
Accountable care organizations in Greater Boston prioritize FDA-cleared platforms with EHR interoperability and liability coverage for AI diagnostic algorithm deployment. The state's concentration of academic medical centers enables rapid regulatory pathway navigation for machine-learning-enabled cardiology and dermatology applications. Remote monitoring tool vendors cluster near Massachusetts General Hospital to embed clinician workflow integration.
Canada
Health Canada and the Office for Civil Rights HIPAA enforcement jointly shape cross-border data architecture requirements for multi-jurisdictional deployments spanning Ontario and British Columbia. Provincial health systems in Toronto and Vancouver pilot hybrid edge computing architectures that process sensitive biometric data locally while transmitting anonymized analytics to cloud dashboards. Lithium-polymer supply concentration among East Asian suppliers exposes hardware manufacturers to input cost volatility.
North America Mobile Health (Mhealth) Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: diversified medtech conglomerates with backward integration into sensor manufacturing, consumer electronics ecosystems bridging wellness tracking with clinical-grade data pipelines, and standalone telehealth platforms with enterprise-scale infrastructure deployments. Two dominant competitive moves define current positioning: M&A activity targeting FDA-cleared algorithm portfolios and strategic partnerships with Medicare Advantage plans for remote monitoring reimbursement coverage.
Within the diversified medtech tier, Medtronic PLC and Boston Scientific Corporation exemplify supply-chain control through captive sensor production and proprietary data analytics platforms. Among consumer electronics ecosystems, Apple Inc. and Fitbit, Inc. occupy positions that leverage installed base scale to bridge wellness applications with clinical data pipelines. Koninklijke Philips N.V. anchors the enterprise infrastructure segment through hospital system relationships and telehealth platform deployments. Abbott and Omron Healthcare, Inc. represent specialists in physiological monitoring peripherals with Medicare Advantage reimbursement qualification.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Koninklijke Philips N.V. |
| Medtronic PLC |
| AT&T Inc. |
| Veradigm |
| Apple Inc. |
| Fitbit, Inc. |
| Abbott |
| Omron Healthcare, Inc. |
| Others |
Value Network & Pricing Analysis
The Los Angeles-Long Beach freight corridor channels lithium-polymer battery imports from East Asian suppliers into California's digital health manufacturing cluster, with container cost volatility feeding directly into hardware pricing tiers and subscription model design across remote patient monitoring devices.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in North American mHealth hardware. Price differentiation rests on FDA 510(k) clearance tier and enterprise-scale volume commitments, with Medicare Advantage procurement committees extracting steepest discounts. Cost compression in consumer wellness wearables is intensifying because platform fee extraction from Apple App Store and Google Play diverts R&D resources. Direct-to-consumer patients exhibit highest price sensitivity; hospital systems with GPO contracts demonstrate lowest.
Supply Chain Analysis
Export-control restrictions on advanced sensor fabrication equipment limit domestic capacity expansion for photoplethysmography components. Hardware manufacturing concentrates in China, South Korea, and Taiwan, with final assembly drawing from Mexican maquiladora facilities to satisfy USMCA rules-of-origin requirements. Lithium-polymer cells, MEMS accelerometers, and Bluetooth Low Energy chipsets constitute critical input dependencies. Single-source vulnerability concentrates in East Asian battery cell production. Distribution runs through medical device distributors and direct hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Medicare Advantage plans and hospital procurement committees as these entities consolidate purchasing volume and unbundle telehealth from EHR vendor bundles, compressing vendor margins and privileging workflow-integrated platforms.
For Market Incumbents: Pre-empt standalone telehealth platform encroachment by deepening proprietary data analytics capabilities and securing exclusive Medicare Advantage remote monitoring contracts. Backward integration into sensor manufacturing mitigates lithium-polymer supply concentration risk. FDA software-as-a-medical-device submission pipelines require accelerated investment to maintain clearance portfolio breadth against emerging AI-diagnostic entrants. For New Entrants and Emerging Players: Pursue psychiatric medication adherence and mood tracking applications newly eligible under remote therapeutic monitoring reimbursement codes, a segment with limited incumbent saturation. Texas and Florida health systems offer most penetrable enterprise entry points due to aggressive value-based care contract expansion. Go-to-market positioning should emphasize quantifiable nursing time savings documentation rather than feature breadth. For Investors and Strategic Acquirers: Standalone AI diagnostic algorithm developers with locked-model FDA 510(k) clearances represent priority acquisition targets as regulatory timelines compress competitive windows. Long-term viability hinges on reimbursement pathway durability rather than consumer adoption metrics. Watch CMS remote therapeutic monitoring code expansion decisions as the critical inflection signal for platform revenue sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Software-as-a-medical-device clearances determine Medicare Advantage reimbursement eligibility and revenue durability. |
| Hospital System Partnership | Texas and Florida value-based care contracts require measurable readmission reduction for vendor selection. |
| Backward Integration into Sensors | Captive photoplethysmography production insulates margin from East Asian lithium-polymer supply volatility. |
| Reimbursement Strategy | Remote therapeutic monitoring code coverage expansion opens psychiatric and metabolic monitoring revenue streams. |
| Software Companion Development | HL7 FHIR-integrated platforms reduce EHR adoption friction for mid-size health system procurement committees. |
Research Methodology
A standing panel of hospital purchasing committee chairs, biomedical engineers, Medicare Advantage plan medical directors, and GPO contracts managers provided ongoing calibration for primary interview findings, which were cross-referenced against FDA 510(k) clearance databases, CMS reimbursement code filings, hospital procurement contract disclosures, and Bluetooth SIG certification records. Bottom-up device shipment estimates and top-down healthcare IT spending allocations were triangulated to constrain forecast variance.
Scenario-bracketing around CMS remote monitoring reimbursement expansion timelines and FDA artificial intelligence guidance release schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology platform, product type, end-user category, and delivery mode architecture. CAGRs were derived from fitted growth curves against historical adoption inflection points in cardiac and metabolic monitoring categories.
Sensitivities concentrate around FDA review timeline extensions for machine-learning-enabled diagnostics and state-level telehealth parity legislation fragmentation. Forecasts reflect documented assumptions regarding reimbursement code stability and hardware replacement cycle duration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
Global Mhealth Solutions Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Global Digital Medicines Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Pregnancy Tracking and Postpartum Care Apps Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
Women Health Applications Market
Digital Health Solutions
Care Coordination Software Market
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
Mobile Tablets in Healthcare Market