
 Global Metaverse in Healthcare Market | 2026-2036
Global Metaverse in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metaverse in Healthcare Market Foresight
ISO 13485 certification for medical device quality management is bifurcating the competitive landscape between qualified incumbents and unproven entrants. NVIDIA Corporation leverages its GPU architecture to dominate real-time surgical rendering workloads. Siemens Healthineers anchors its position through deep integration with existing imaging modalities and hospital IT infrastructure.
The metaverse in healthcare denotes persistent, immersive digital environments that combine spatial computing, real-time 3D rendering, and multi-user interaction to simulate clinical scenarios, anatomical structures, and therapeutic interventions with sub-millimeter positional tracking accuracy. Medical Training applications lead current deployment, while Surgical Planning segments capture concentrated margin pools due to high-value software licensing and specialist workflow integration. Software Platforms are maturing fastest as hospitals consolidate vendor relationships around interoperable architectures that reduce integration overhead.
FDA digital health pre-certification, EMA's medical device regulation under MDR, and HIPAA privacy safeguards collectively shape product development timelines and market access conditions for immersive healthcare technologies. The EU AI Act adds algorithmic transparency requirements that filter which machine-learning-driven diagnostic modules reach clinical deployment. Stakeholders must monitor evolving reimbursement codes for procedural VR applications as the decisive gate for scaled hospital procurement.
Market Dynamics
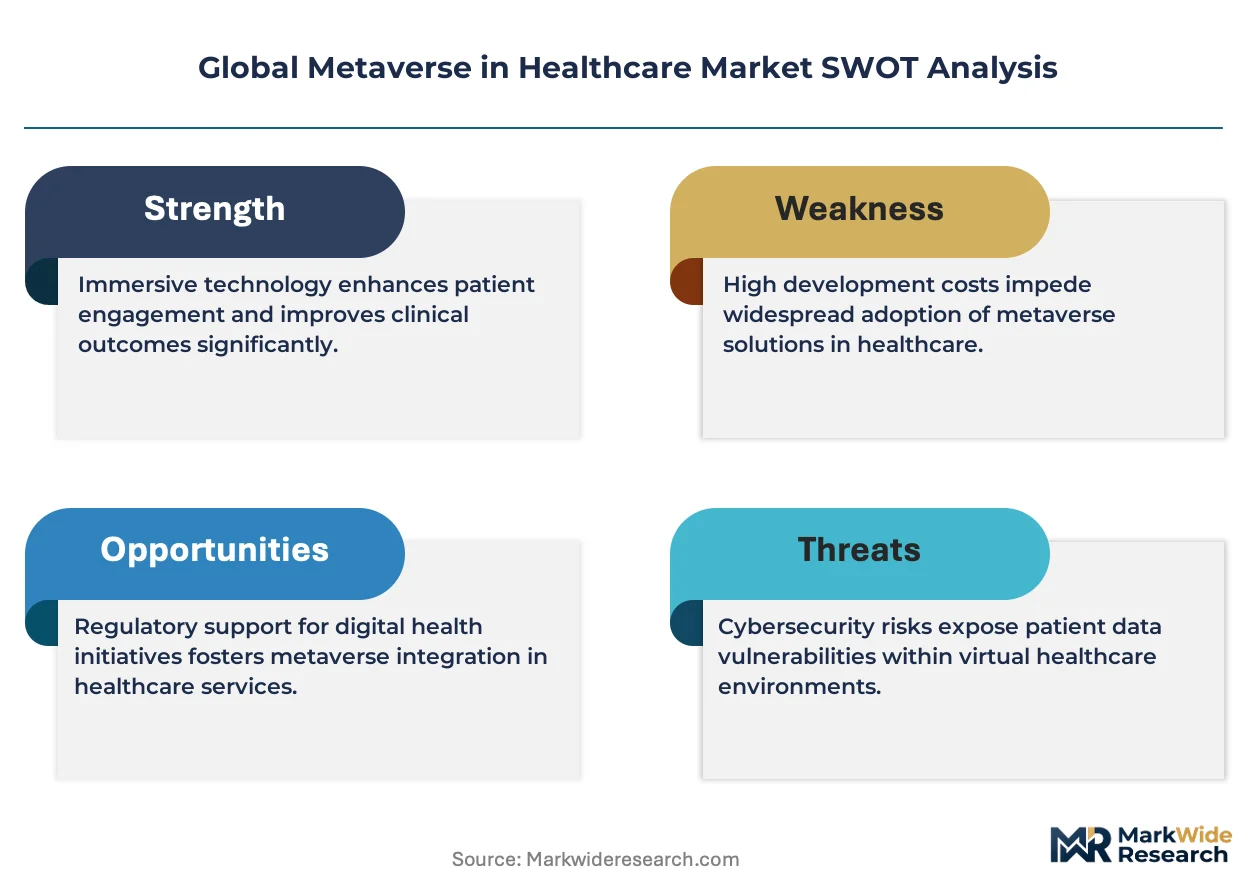
ISO 13485 certification requirements are bifurcating vendor access to hospital procurement channels, as qualified incumbents capture surgical planning contracts while unproven entrants face extended validation timelines.
Growth Catalysts
- FDA Digital Health Pre-Certification:The streamlined pathway accelerates platform qualification for immersive therapeutic applications, reducing time-to-market for compliant developers.
- University Hospital Training Mandates:Leading academic medical centers in the United States, Germany, and Japan are expanding immersive simulation adoption as core curriculum requirements.
- GPU Rendering Architectures:Advances in real-time 3D processing enable sub-millimeter positional tracking accuracy for surgical planning workflows.
Market Restraints
- Specialist Hardware Costs:Haptic feedback devices and mixed-reality headsets impose capital expenditure burdens that limit deployment at mid-tier hospitals.
- EU AI Act Algorithmic Transparency:Machine-learning diagnostic modules face additional validation layers that extend development cycles before clinical deployment.
- Data Localization Requirements:HIPAA safeguards and GDPR cross-border transfer rules fragment cloud infrastructure strategies for multi-tenant platforms.
Strategic Opportunities
- Reimbursement Pilot Expansion:Operational VR therapy programs in Germany and Japan provide templates for coverage code development in additional national health systems.
- Rural Telemedicine Integration:Persistent virtual environments enable specialist consultation access for underserved regions lacking physical infrastructure.
- Interoperable Architecture Consolidation:Hospitals are converging on vendor relationships that reduce IT integration overhead across imaging modalities.
Industry Challenges
- Computational Biomechanics Talent Scarcity:The shortage of engineers capable of real-time soft-tissue simulation constrains development velocity for surgical training modules.
- Legacy PACS Integration Complexity:DICOM compatibility requirements and hospital IT security protocols create friction in enterprise software deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metaverse in Healthcare Market |
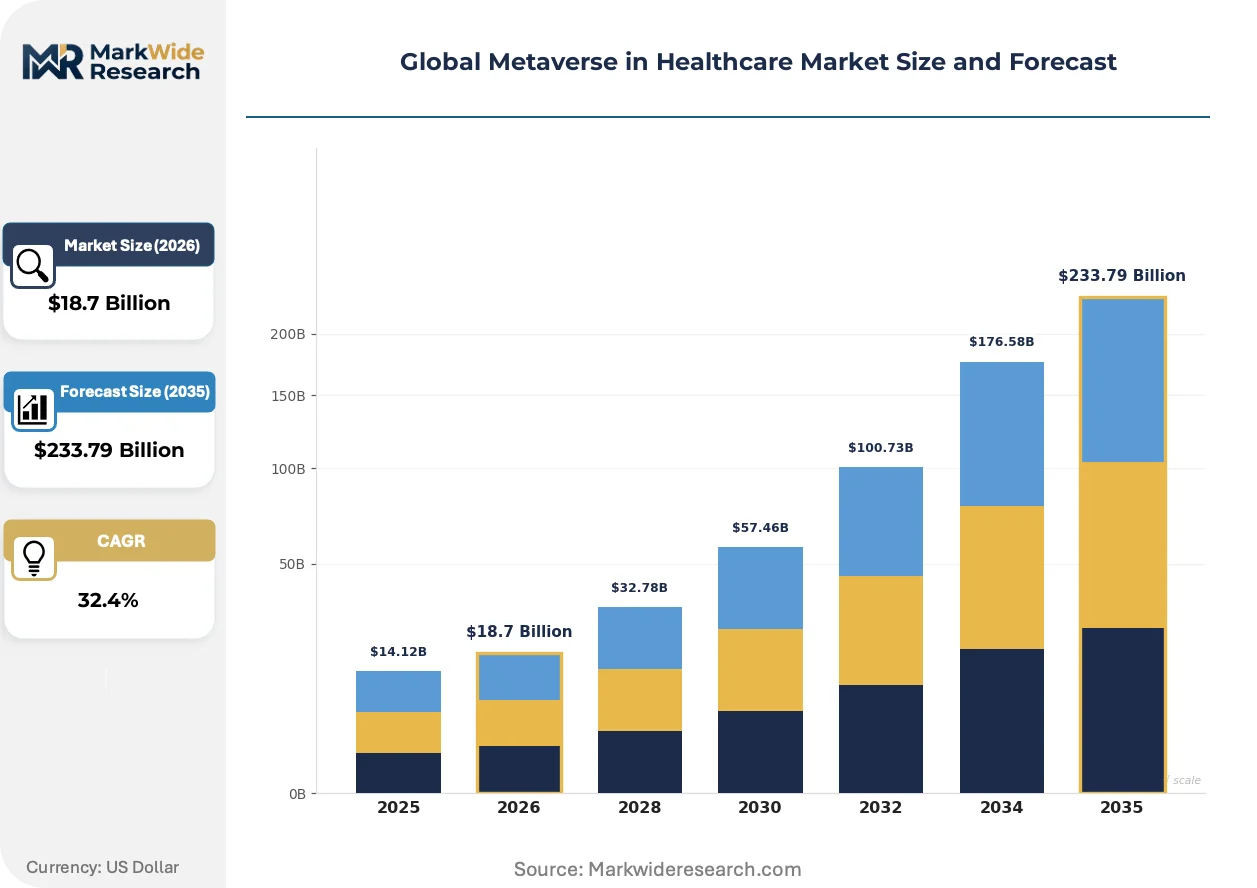
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $233.79 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality Devices, Augmented Reality Devices, Mixed Reality Devices, Software Platforms, Sensors Application: Medical Training, Patient Therapy, Surgical Planning, Telemedicine Services, Wellness Programs End User: Hospitals, Medical Schools, Rehabilitation Centers, Research Institutes, Telehealth Providers Technology: Artificial Intelligence, Blockchain, 5G Connectivity, Cloud Computing, Haptic Feedback |
| Companies Covered | NVIDIA Corporation, Medtronic, Siemens Healthineers, Koninklijke Philips N.V., Microsoft, Intuitive Surgical, GE Healthcare, Meta Platforms, XRHealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metaverse in Healthcare Market Shifts & Advancements
Spatial computing architectures are compressing the latency threshold for real-time multi-user clinical collaboration, enabling synchronous surgical planning across distributed specialist teams.
Photorealistic volumetric rendering is bifurcating the training simulation market. High-fidelity anatomy visualization enables university hospitals to replace cadaver-based instruction at scale. Lower-tier institutions face capability gaps without equivalent infrastructure investment.
The EU AI Act imposes algorithmic transparency mandates on machine-learning diagnostic modules. Developers must document training data provenance and decision logic for regulatory submission. Surgical planning segments with AI-assisted segmentation tools are restructuring compliance teams to meet documentation requirements.
Subscription licensing models are displacing perpetual software purchases in hospital procurement. Chief information officers favor operational expenditure structures that align costs with utilization metrics. This pattern concentrates in the United States where capital budget constraints pressure finance departments.
Global Metaverse in Healthcare Market Segmentation
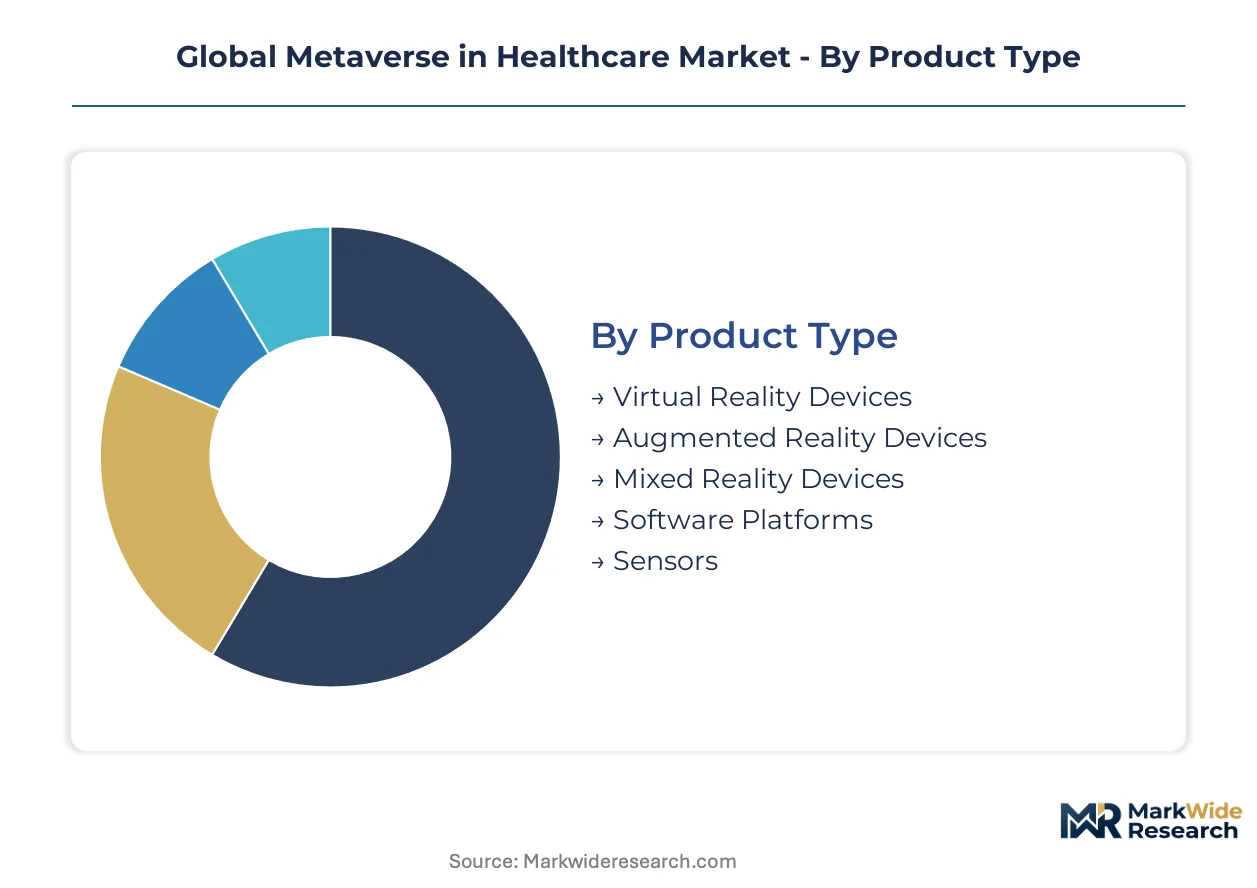
Segmentation in the metaverse healthcare market reveals divergent technology maturities and procurement priorities. Product type splits expose hardware-software margin disparities, while application segmentation tracks reimbursement readiness across clinical use cases.
Product Type:
Software platforms face intensifying substitution pressure from open-source rendering engines and gaming-derived toolkits that commoditize baseline immersive functionality.
- Software Platforms:Interoperable middleware stacks integrating DICOM imaging, real-time physics, and multi-user session management. Demand concentrates in university hospitals in the United States and Germany where IT consolidation mandates favor vendor reduction. ISO 13485 certification requirements filter qualified suppliers from commodity entrants.
- Virtual Reality Devices:Head-mounted displays with sub-20ms motion-to-photon latency and inside-out tracking. Procurement clusters at academic medical centers in Japan expanding procedural simulation programs. Specialist hardware costs constrain penetration at mid-tier institutions.
- Augmented Reality Devices:Optical see-through headsets overlaying patient-specific anatomy onto surgical fields. FDA 510(k) clearance pathways accelerate qualification for spine and orthopedic applications.
- Mixed Reality Devices:Passthrough cameras enabling seamless physical-digital interaction. Siemens Healthineers and NVIDIA Corporation dominate integration with existing surgical navigation systems.
- Sensors:Positional tracking arrays and biometric monitors feeding real-time physiological data into immersive environments. GDPR data localization requirements fragment cloud deployment strategies.
Software platforms anchor the volume base while mixed reality devices gain share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive surgical planning from operational-expenditure therapy programs.
- Surgical Planning:Preoperative 3D reconstruction and virtual rehearsal of complex procedures. High-value licensing models capture concentrated margins at German university hospitals with deep PACS integration. EMA MDR compliance extends validation timelines for AI-assisted segmentation modules.
- Medical Training:Cadaver-replacement curricula using photorealistic volumetric anatomy. Deployment accelerates at Japanese medical schools with METI-funded simulation infrastructure. Photorealistic rendering capabilities bifurcate institutional access.
- Patient Therapy:VR exposure protocols for chronic pain and psychiatric conditions. Reimbursement pilot programs in Germany and Japan provide coverage templates for expansion.
- Telemedicine Services:Persistent virtual consultation rooms enabling rural specialist access. HIPAA safeguards impose data residency constraints on multi-tenant platform architectures.
- Wellness Programs:Preventive immersive experiences for stress reduction and lifestyle modification. Consumer-grade hardware compatibility broadens addressable population.
Medical training commands the installed base while surgical planning delivers the steepest margin expansion trajectory.
End User:
Customer type determines procurement authority structure and validation burden intensity.
- Hospitals:Enterprise IT departments consolidating vendor relationships around interoperable architectures. Chief information officers in the United States favor subscription licensing aligning costs with utilization.
- Medical Schools:Curriculum committees mandating immersive simulation as graduation requirements. Adoption concentrates at Johns Hopkins University Hospital and Charité – Universitätsmedizin Berlin.
- Rehabilitation Centers:Physical therapy departments integrating haptic feedback for motor recovery. Reimbursement code development lags acute care applications.
- Research Institutes:Computational biomechanics laboratories advancing soft-tissue simulation fidelity. Talent scarcity constrains development velocity for real-time deformation modeling.
- Telehealth Providers:Virtual-first platforms extending specialist reach to underserved regions. 5G latency thresholds enable synchronous multi-user clinical collaboration.
Hospitals dominate current procurement volume while telehealth providers represent the most rapidly scaling customer category.
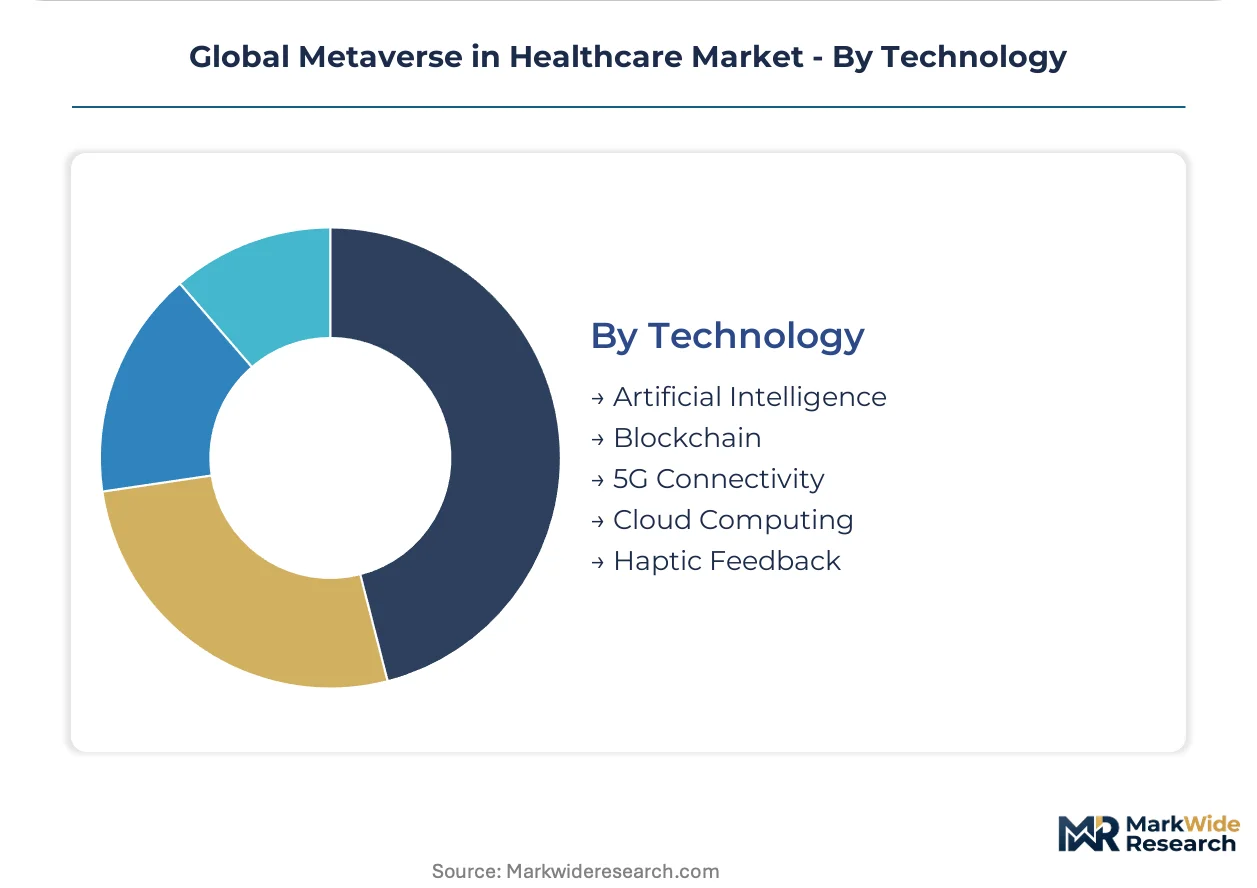
Technology:
Supply concentration in GPU silicon and cloud infrastructure shapes vendor dependency structures.
- Artificial Intelligence:Machine learning modules for automated segmentation and predictive outcome modeling. EU AI Act transparency mandates restructure compliance documentation requirements.
- Cloud Computing:Elastic rendering farms processing photorealistic anatomy at scale. GDPR cross-border transfer rules fragment infrastructure strategies.
- Haptic Feedback:Force-feedback gloves and exoskeletons enabling tactile surgical rehearsal. Specialist hardware costs limit deployment outside tier-one academic centers.
- 5G Connectivity:Ultra-reliable low-latency communication enabling distributed surgical planning. Japanese METI infrastructure investments accelerate metropolitan deployment.
- Blockchain:Decentralized credentialing and consent management for patient data. Regulatory clarity remains underdeveloped relative to clinical application maturity.
Cloud computing underpins current platform delivery while haptic feedback technology is climbing the fastest adoption curve among enabling layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
University hospital procurement departments concentrate purchasing power in the United States, Germany, and Japan where reimbursement pilots for VR therapy are already operational. These three markets anchor current demand while regulatory frameworks in each jurisdiction create divergent qualification timelines for immersive healthcare platforms.
United States
Academic medical centers at Johns Hopkins and Mayo Clinic drive immersive simulation procurement as core curriculum mandates expand. FDA digital health pre-certification accelerates platform qualification pathways for compliant developers. Boston and San Francisco clusters concentrate venture funding for surgical planning startups.
Germany
Charité – Universitätsmedizin Berlin and Heidelberg University Hospital anchor European demand for photorealistic volumetric anatomy systems. EMA medical device regulation under MDR extends validation timelines for AI-assisted segmentation modules. Bavaria's medical technology corridor around Munich hosts concentrated vendor integration activity.
Japan
METI-funded simulation infrastructure at Tokyo and Osaka medical schools accelerates cadaver-replacement curriculum adoption. PMDA guidance frameworks align with international standards for mixed-reality surgical devices. The Kanto region dominates haptic feedback device deployment for motor recovery applications.
United Kingdom
NHS digital transformation budgets channel procurement toward interoperable middleware stacks reducing IT vendor fragmentation. MHRA recognition of FDA-cleared devices streamlines parallel market entry for US-qualified platforms. London's Imperial College Healthcare anchors surgical planning validation studies.
South Korea
MFDS fast-track designation for VR therapeutic devices attracts multinational platform developers seeking Asian market entry. Seoul National University Hospital leads regional adoption of 5G-enabled distributed surgical planning. The Pangyo Techno Valley cluster concentrates domestic mixed-reality hardware engineering.
Global Metaverse in Healthcare Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with healthcare divisions rather than pure-play immersive specialists. NVIDIA Corporation and Microsoft anchor the infrastructure layer through GPU silicon and cloud computing platforms. Siemens Healthineers and GE Healthcare leverage installed imaging modalities for surgical planning integration. Competitive moves concentrate on strategic partnerships with university hospitals for validation data and ISO 13485 certification acquisition to unlock procurement channels.
Within the technology infrastructure tier, NVIDIA Corporation exemplifies silicon-dependent positioning through GPU architecture dominance in real-time surgical rendering. Siemens Healthineers occupies a position representing deep PACS integration and hospital IT infrastructure anchoring. Meta Platforms sits within the consumer-originated entrant archetype seeking clinical qualification pathways. These three companies illustrate the divergent strategic origins—semiconductor, medical device, and consumer technology—currently contesting platform standardization.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Medtronic |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Microsoft |
| Intuitive Surgical |
| GE Healthcare |
| Meta Platforms |
| XRHealth |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with GPU cloud providers lock in both supply access and price visibility for hospital IT departments navigating volatile silicon markets. These arrangements insulate procurement budgets from spot-price fluctuations while committing buyers to minimum utilization thresholds.
Pricing Analysis
Cost-plus contracts with silicon indexation dominate infrastructure procurement, passing through foundry cost fluctuations to healthcare buyers. Three-tier pricing structure across ISO 13485-certified platforms, qualified-but-unproven entrants, and open-source alternatives separates premium surgical planning suites from commoditized training modules. Pricing pressure stems from open-source rendering engines commoditizing baseline immersive functionality. Mid-tier hospitals exhibit acute price sensitivity, while German university hospitals prioritize certification tier over cost.
Supply Chain Analysis
Just-in-time GPU provisioning from cloud hyperscalers coexists with strategic stockpiling of haptic hardware at Japanese academic centers. Taiwan, South Korea, and the United States anchor GPU silicon supply. Rare earth magnets for haptic actuators and precision optics for passthrough cameras constitute critical input dependencies. Single-source vulnerability in advanced node semiconductor fabrication concentrates risk. Distribution runs through hospital IT procurement committees with GPO-mediated vendor consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time soft-tissue simulation expertise represents the binding constraint on platform differentiation, with fewer than two hundred engineers globally qualified for clinical-grade biomechanics development.
For Market Incumbents: Consolidate ISO 13485 certification portfolios to defend procurement channel access against open-source rendering commoditization. Deepen backward integration into GPU cloud capacity to secure rendering farm availability during silicon supply crunches. Acquire computational biomechanics talent pools before specialist compensation inflates beyond platform economics. For New Entrants and Emerging Players: FDA digital health pre-certification fast-tracks offer the most penetrable regulatory pathway for VR therapeutic applications. Target rehabilitation centers in Germany where reimbursement code development lags acute care, creating first-mover windows. Lead with subscription SaaS pricing to align with US hospital CIO preference for operational expenditure structures. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated platform developers with captive PACS integration capabilities and existing hospital system relationships. Long-term viability hinges on reimbursement code expansion beyond pilot programs into national coverage determinations. Watch FDA 510(k) clearance velocity for mixed-reality surgical devices as the decisive inflection signal for scaled hospital procurement.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acquisition | Unlocks hospital procurement channels filtered by quality management mandates. |
| Hospital System Partnership | Generates validation data and anchors reference site networks for platform adoption. |
| Reimbursement Strategy Development | Shapes coverage code expansion for VR therapy beyond German and Japanese pilots. |
| Software Companion Development | Extends surgical planning platforms into integrated therapeutic delivery workflows. |
| CE Marking Pathway | Accelerates EMA MDR compliance for AI-assisted segmentation modules in Europe. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR submission databases, hospital procurement contract registries, and CMS reimbursement code proposals. Primary interviews engaged hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and immersive platform CTOs. Bottom-up triangulation across vendor revenue disclosures and top-down validation against national health IT expenditure aggregates constrain estimate variance.
Segmentation dimensions modeled span product type, application, end user, and technology layer across the projection horizon. CAGRs derive from curve-fitting historical adoption trajectories against regulatory milestone schedules. Forecast inputs incorporate reimbursement pilot expansion timelines and GPU silicon supply elasticity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained FDA pre-certification throughput or reimbursement code expansion would require recalibration. Forecasts reflect documented assumptions regarding hospital IT consolidation velocity and cloud infrastructure localization requirements. Revision becomes warranted when EU AI Act algorithmic transparency enforcement crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Digital Twins in Healthcare Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
Women Digital Health Solutions Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
AI-Powered Clinical Decision Support Market
Digital Health Solutions
Patient Case Management Software Market
Digital Health Solutions
Global Urgent Care Apps Market
Digital Health Solutions
Vaccine Management Software Market
Digital Health Solutions
Artificial Intelligence in Precision Medicine Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
Patient Engagement Technology Market
Digital Health Solutions
Women Health Applications Market
Digital Health Solutions
Global Behavioral/Mental Health Software Market