
 Vaccine Management Software Market | 2026-2036
Vaccine Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccine Management Software Market Insights
India is tilting toward indigenous vaccine management infrastructure as public health digitization accelerates. IBM Corporation leverages its hybrid cloud architecture to anchor large-scale government immunization platforms across multiple continents. Oracle Corporation sustains competitive positioning through deep integration with existing healthcare ERP ecosystems. Epic Systems dominates the acute care segment in the United States through embedded scheduling and inventory workflows within its dominant EHR install base.
Vaccine management software comprises modular digital platforms that orchestrate cold chain monitoring, dose tracking, patient scheduling, and adverse event reporting through interoperable APIs and HL7 FHIR protocols. Cloud-based solutions lead deployment preferences among mid-sized health systems seeking scalable subscription models without capital infrastructure burdens, while inventory management functionality captures disproportionate R&D investment as supply chain resilience becomes a board-level priority for pharmacy chains and government distributors.
FDA digital health guidance and HIPAA privacy frameworks shape product architecture decisions for vendors targeting United States healthcare providers, while India's CDSCO and BIS standards dictate data localization and cybersecurity certification requirements for platforms serving its national immunization program. Stakeholders must monitor how divergent national data sovereignty rules fragment platform standardization and force modular localization strategies that inflate development overhead.
Market Dynamics
FDA digital health guidance and HIPAA privacy frameworks are compressing product development timelines for vendors targeting United States healthcare providers, forcing modular architecture decisions that prioritize interoperability certification over feature breadth.
Growth Catalysts
- Cloud Migration Mandates:Mid-sized health systems across the United States are abandoning on-premise infrastructure for subscription-based SaaS models that eliminate capital expenditure burdens and accelerate deployment cycles.
- HL7 FHIR Protocol Adoption:Interoperability standards are mandating API-first architecture across hospital networks, enabling seamless electronic health record integration with vaccine inventory modules.
- Cold Chain Resilience Priorities:Pharmacy chains and government distributors are elevating supply chain visibility to board-level governance, directing disproportionate R&D investment toward real-time temperature monitoring and predictive analytics.
Market Restraints
- Data Localization Requirements:India's CDSCO and BIS standards dictate domestic server placement and cybersecurity certification, fragmenting platform standardization and inflating development overhead for multinational vendors.
- Legacy System Entrenchment:Epic Systems' dominant EHR install base in United States acute care creates switching friction that slows competitive displacement and extends sales cycles.
- Cybersecurity Certification Burden:Divergent national data sovereignty rules force redundant compliance pathways that strain engineering resources and delay market entry.
Strategic Opportunities
- Indigenous Infrastructure Buildout:India's national immunization program digitization is creating procurement windows for platforms architected around CDSCO data localization mandates and BIS cybersecurity frameworks.
- Hybrid Cloud Government Contracts:Large-scale immunization platforms across multiple continents are anchoring to hybrid cloud architectures that balance sovereign data control with elastic compute scaling.
- ERP Ecosystem Integration:Deep embedding with existing healthcare enterprise resource planning systems offers defensive positioning against standalone vaccine management specialists.
Industry Challenges
- Interoperability Engineering Talent Scarcity:HL7 FHIR protocol expertise and API architecture skills command premium compensation, constraining vendor scaling velocity.
- Multi-Jurisdiction Compliance Parallelism:Simultaneous FDA digital health guidance, HIPAA privacy rule adherence, and CDSCO localization requirements extend product certification timelines.
- Legacy Workflow Displacement Friction:Embedded scheduling and inventory workflows within dominant EHR platforms create organizational change management burdens that stall implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccine Management Software Market |
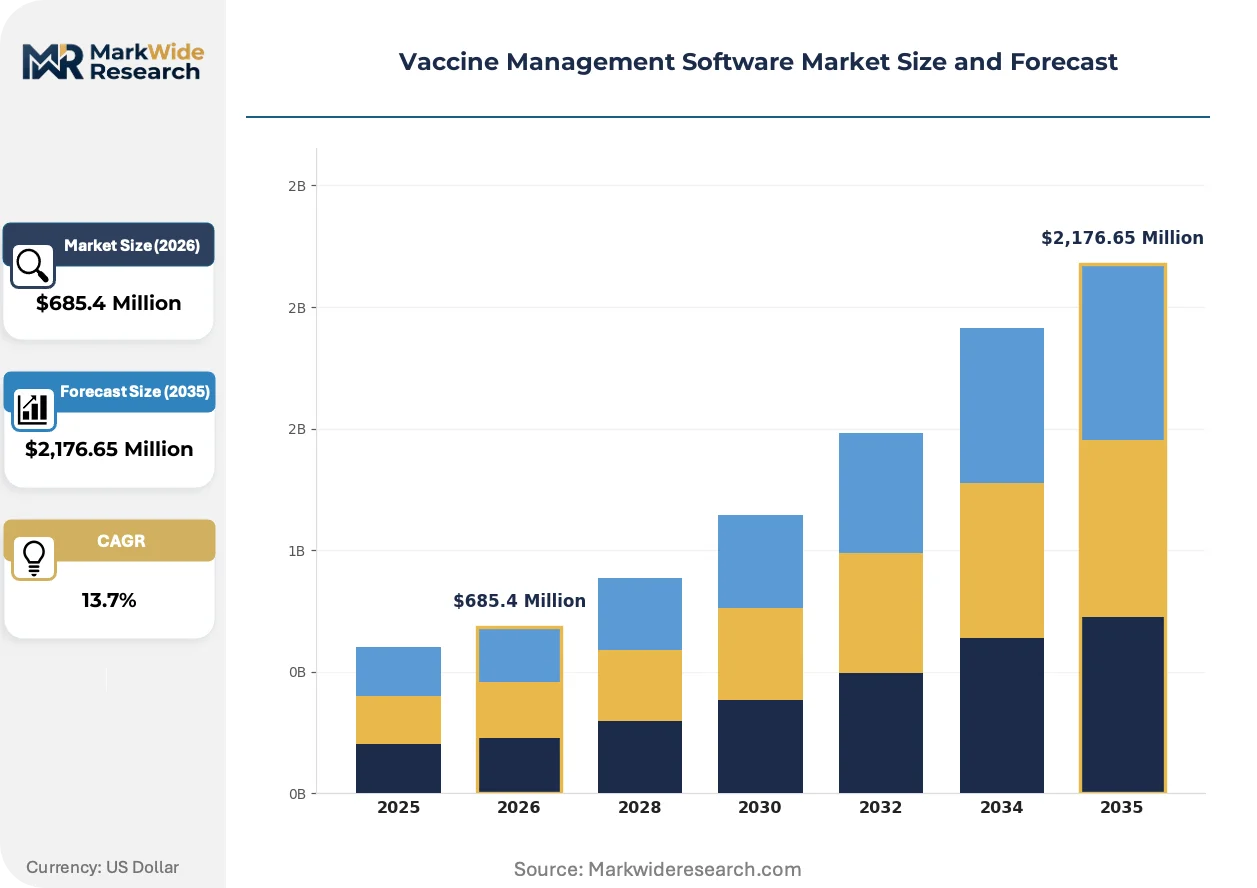
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,176.65 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Solutions, On-premise Solutions, Hybrid Solutions, Legacy Systems End User: Healthcare Providers, Pharmacies, Government Organizations, NGOs Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, SaaS Functionality: Inventory Management, Scheduling, Reporting, Analytics |
| Companies Covered | IBM Corporation, Salesforce, Inc., Oracle Corporation, Accenture, VaxCare Corp, DrFirst, Epic Systems, Cerner, Infosys Public Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccine Management Software Market Trends and Innovations
Real-time sensor networks and predictive analytics are compressing cold chain failure response times from hours to minutes, while regulatory pressure for adverse event reporting automation is accelerating AI adoption across pharmacovigilance workflows.
Blockchain-enabled temperature logging is digitizing custody verification across pharmaceutical distribution networks. Third-party logistics providers serving United States hospital networks are deploying these systems to preempt FDA inspection findings. The technology is digitizing audit trail construction, replacing paper-based chain-of-custody documentation with immutable distributed ledgers that satisfy HIPAA access controls and 21 CFR Part 11 electronic record requirements.
EMA's evolving Medical Device Regulation and In Vitro Diagnostic Regulation frameworks are extending software-as-a-medical-device classification to vaccine management platforms with diagnostic decision-support features. European hospital procurement committees are now requiring CE marking documentation for inventory modules with patient-facing scheduling algorithms. German hospital networks are responding by demanding vendor roadmaps that align with MDR transition timelines and IVDR conformity assessment procedures.
Subscription pricing for vaccine management modules is displacing perpetual license models among United States mid-sized health systems seeking operational expenditure predictability. Chief financial officers at regional hospital networks are negotiating multi-year SaaS agreements that bundle implementation services and ongoing regulatory compliance updates. This shift is most visible in the southeastern United States, where rural health system consolidation is creating aggregated buying power that favors vendor-managed infrastructure over in-house IT capital deployment.
Vaccine Management Software Market Segmentation
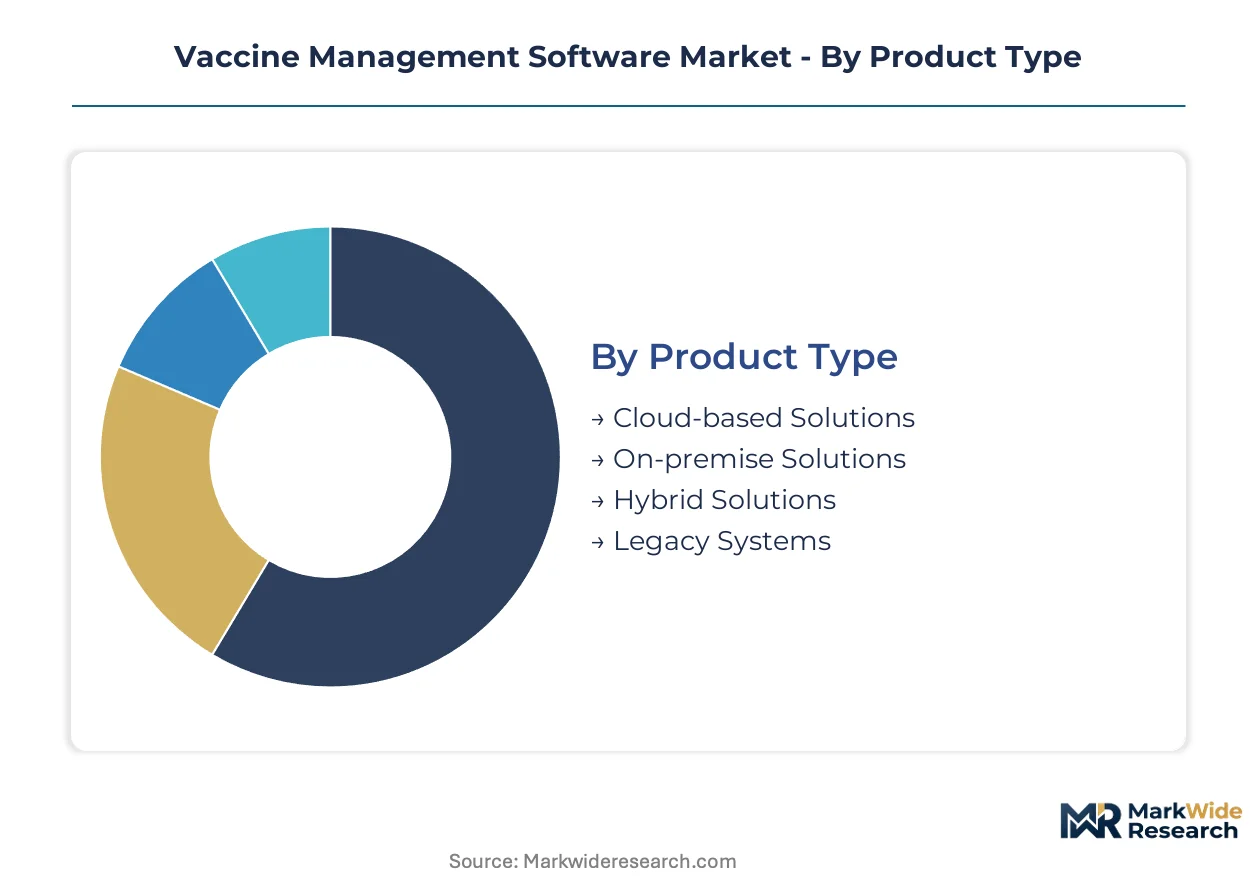
Vaccine management software segments diverge sharply in procurement velocity. Cloud deployments refresh on 12-to-24-month subscription cycles while legacy on-premise installations persist for seven-to-ten years, creating dual-revenue architectures that vendors must simultaneously harvest and displace.
Product Type:
Cloud-based Solutions turn over fastest with annual contract renewals and quarterly feature updates. On-premise Solutions and Legacy Systems lock capital for years. Hybrid Solutions occupy the middle ground with infrastructure refresh cycles stretching three-to-five years.
- Cloud-based Solutions:Multi-tenant architectures deliver automatic updates, API extensibility, and elastic scaling without client-side infrastructure. United States mid-sized health systems are consolidating procurement around these platforms to eliminate data center capital expenditure and accelerate HL7 FHIR interoperability certification.
- Hybrid Solutions:Split architectures keep sensitive patient data on sovereign infrastructure while pushing analytics workloads to elastic cloud compute. India's national immunization program digitization is mandating this configuration to satisfy CDSCO data localization requirements without sacrificing predictive analytics capabilities.
- On-premise Solutions:Single-tenant deployments persist in defense and intelligence healthcare networks with air-gapped security requirements.
- Legacy Systems:Mainframe-era immunization registries still process batch updates in certain government jurisdictions with frozen procurement budgets.
Legacy Systems dominate installed base. Cloud-based Solutions is where expansion concentrates.
End User:
Cost tier structures procurement authority across end users. Government Organizations deploy billion-dollar national platforms with decade-long vendor relationships. Pharmacies and NGOs operate on compressed decision cycles with annual software budgets.
- Government Organizations:Sovereign immunization programs demand modular architectures that segment citizen data by jurisdiction while centralizing analytics dashboards. India's Ministry of Health and Family Welfare is procuring indigenous platforms architected around BIS cybersecurity certification and domestic server placement mandates.
- Healthcare Providers:Hospital networks prioritize EHR-embedded workflows over standalone vaccine modules. Epic Systems' dominant install base in United States acute care creates switching friction that extends sales cycles and elevates implementation service margins.
- Pharmacies:Retail chains favor subscription pricing with bundled cold chain monitoring hardware to convert capital expenditure into predictable operational outflows.
- NGOs:Global health initiatives require offline-capable mobile applications for last-mile immunization campaigns in connectivity-constrained environments.
Healthcare Providers dominate installed base. Government Organizations is where expansion concentrates.
Deployment Model:
Volume concentration separates public multi-tenant infrastructure from private sovereign stacks. SaaS subscriptions are climbing fastest as finance teams mandate operational expenditure predictability.
- SaaS:Subscription pricing bundles implementation, maintenance, and regulatory compliance updates into per-dose or per-provider fees. Regional hospital networks in the southeastern United States are aggregating buying power through consolidation to negotiate multi-year agreements with vendor-managed infrastructure.
- Public Cloud:Shared compute pools deliver lowest unit economics for analytics workloads without patient data residency requirements.
- Private Cloud:Dedicated infrastructure satisfies HIPAA business associate agreement constraints for United States providers handling protected health information.
- Hybrid Cloud:Workload orchestration between sovereign and elastic environments balances data control with burst compute capacity for population-scale immunization campaigns.
Private Cloud dominates installed base. SaaS is where expansion concentrates.
Functionality:
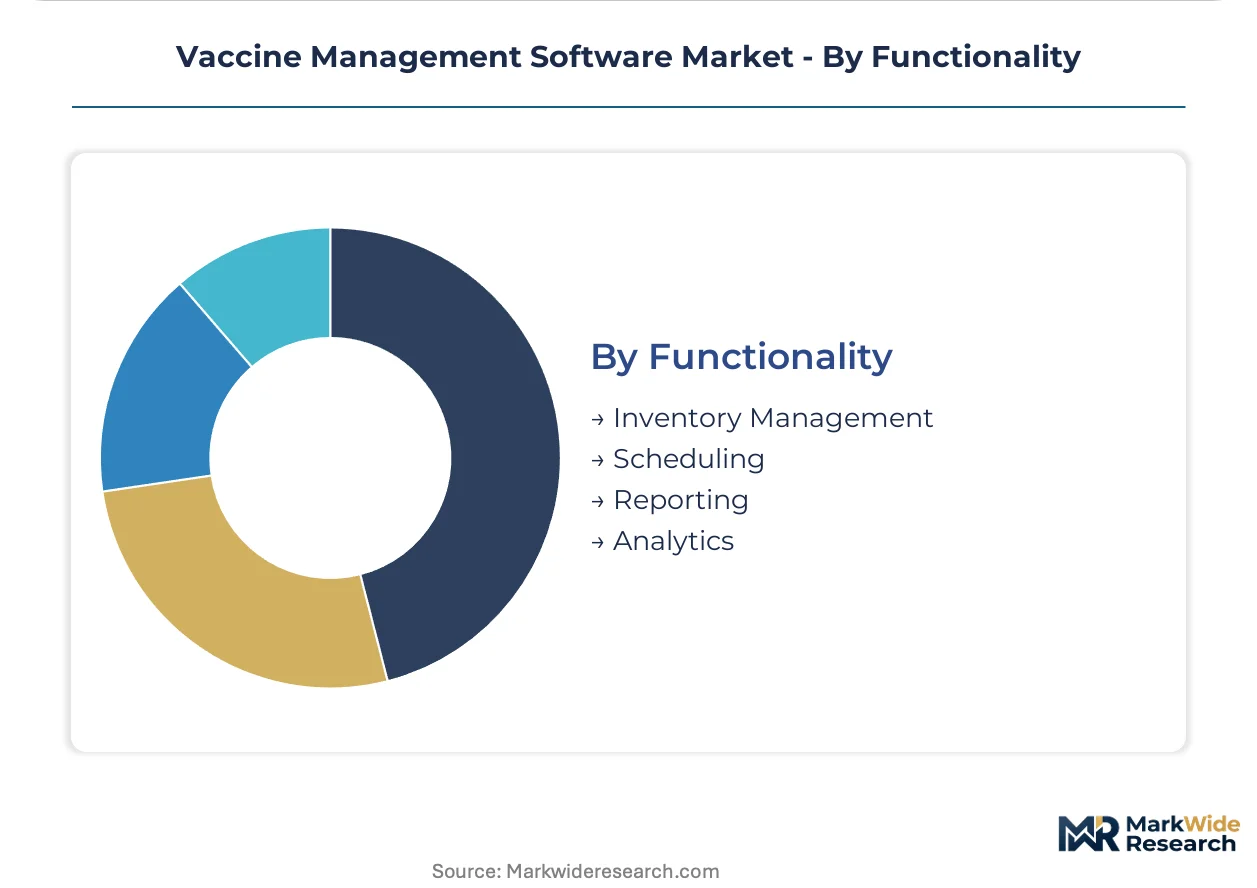
Supply concentration in cold chain logistics is elevating Inventory Management to board-level governance priority. Scheduling and Reporting follow as workflow automation targets.
- Inventory Management:Real-time temperature logging, lot tracking, and expiration alerting integrate with IoT sensor networks and blockchain audit trails. Pharmacy chains are deploying predictive analytics to compress cold chain failure response times from hours to minutes and preempt FDA inspection findings.
- Analytics:Population health dashboards aggregate immunization coverage rates, adverse event clustering, and dose wastage patterns for public health decision support. EMA's MDR and IVDR frameworks are extending software-as-a-medical-device classification to modules with diagnostic decision-support features, forcing CE marking documentation into European procurement requirements.
- Scheduling:Patient-facing appointment algorithms optimize clinic throughput and second-dose recall compliance.
- Reporting:Automated adverse event submission to pharmacovigilance databases replaces manual case intake workflows.
Reporting dominates installed base. Inventory Management is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform engineering resources cluster disproportionately in jurisdictions with mature healthcare IT procurement frameworks and sovereign cloud infrastructure mandates. National immunization program digitization timelines are creating divergent deployment windows across major markets.
United States
Hospital network consolidation in the southeastern states is aggregating procurement authority for subscription-based platforms. FDA digital health guidance and HIPAA privacy frameworks compress vendor certification timelines while elevating interoperability requirements. The Research Triangle in North Carolina anchors hybrid cloud development for government immunization infrastructure.
India
Public health digitization is accelerating indigenous platform procurement for the national immunization program. CDSCO data localization mandates and BIS cybersecurity certification requirements fragment standardization while creating domestic vendor opportunities. Bengaluru's health-tech cluster concentrates engineering talent for modular architectures serving sovereign data requirements.
Germany
Hospital procurement committees are demanding CE marking documentation for inventory modules with patient-facing algorithms under evolving MDR and IVDR frameworks. EMA software-as-a-medical-device classification extends to diagnostic decision-support features. The Munich-Stuttgart corridor hosts ERP-embedded workflow specialists aligning with conformity assessment timelines.
United Kingdom
NHS digital transformation programs are mandating HL7 FHIR protocol adoption across integrated care systems. Procurement frameworks prioritize API-first architectures that interoperate with existing electronic health record installations. London's health informatics cluster concentrates interoperability engineering expertise for European market entry.
Japan
Metropolitan hospital networks are deploying predictive analytics for cold chain resilience as pharmaceutical distribution regulations tighten. PMDA guidance on software-as-a-medical-device shapes platform architecture decisions for vendors targeting acute care segments. The Tokyo-Osaka corridor concentrates deployment resources for hybrid cloud immunization tracking systems.
Vaccine Management Software Market Competitive Landscape
Enterprise technology conglomerates and specialized healthcare IT vendors split the market between platform breadth and workflow depth. Consolidation pressure concentrates around EHR-embedded solutions and sovereign cloud infrastructure contracts. Two strategic archetypes dominate: hybrid cloud infrastructure providers anchoring government-scale deployments, and EHR-centric specialists defending through embedded scheduling and inventory workflows. Competitive moves center on ERP ecosystem integration partnerships and modular localization strategies for multi-jurisdiction compliance.
Within the enterprise technology tier, IBM Corporation and Oracle Corporation represent infrastructure-scale positioning for national immunization platforms. Epic Systems occupies a position exemplifying EHR-embedded defensive strategy through dominant acute care install base in the United States. These three anchors illustrate the market's bifurcation between sovereign cloud mandates and workflow entrenchment.
| Leading Market Players |
|---|
| IBM Corporation |
| Salesforce, Inc. |
| Oracle Corporation |
| Accenture |
| VaxCare Corp |
| DrFirst |
| Epic Systems |
| Cerner |
| Infosys Public Services, Inc. |
| Others |
Pricing and Supply Chain Analysis
Bengaluru's health-tech engineering cluster feeds cloud-native platform capacity into downstream procurement cycles across India's national immunization digitization program. The city's concentration of HL7 FHIR protocol specialists and modular architecture developers translates directly into pricing leverage for vendors serving CDSCO-mandated data localization requirements.
Pricing Analysis
FDA digital health guidance dictates the pricing tier structure across United States deployments, segmenting subscription models by interoperability certification depth rather than feature breadth alone. Three-tier pricing structure across enterprise, mid-market, and rural health system levels reflects divergent HIPAA business associate agreement requirements and implementation service intensity. Cost compression in the mid-market tier is intensifying because regional hospital network consolidation in the southeastern United States aggregates buying power around multi-year SaaS bundles. Government organizations exhibit lowest price sensitivity due to sovereign mandate urgency, while pharmacies operate on annual software budgets with hardware-inclusive subscription preferences.
Supply Chain Analysis
Extended payment terms from cloud infrastructure providers now stretch 90-to-120 days for vaccine management platform vendors serving government-scale deployments. Software engineering talent concentrates in the United States, India, and Germany, with HL7 FHIR protocol expertise commanding premium compensation that feeds into platform development costs. Raw material dependencies center on semiconductor components for IoT cold chain sensors, cryptographic modules for blockchain audit trails, and elastic compute capacity from hyperscaler data centers. Single-source vulnerability runs through concentrated hyperscaler regions for sovereign data residency requirements. Distribution runs through direct enterprise sales teams for hospital networks and systems integrator partnerships for government immunization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated regional hospital networks in the southeastern United States, fragmenting procurement authority away from standalone acute care facilities and toward aggregated purchasing entities with vendor-managed infrastructure preferences.
For Market Incumbents: Pre-empt displacement by embedding inventory workflows deeper into dominant EHR install bases through API-first architecture that accelerates HL7 FHIR certification timelines. Defensive consolidation moves should prioritize hybrid cloud infrastructure partnerships for government immunization contracts and predictive analytics R&D investment for cold chain resilience modules. The threat of standalone vaccine management specialists eroding margin position demands channel control through implementation service bundling. For New Entrants and Emerging Players: Establish a beachhead in India's indigenous platform procurement window by architecting around CDSCO data localization mandates and BIS cybersecurity certification requirements. White-space targets include offline-capable mobile applications for NGO last-mile immunization campaigns and pharmacy chain subscription models with bundled cold chain hardware. The most penetrable segment is mid-sized United States health systems abandoning on-premise infrastructure for SaaS predictability. Go-to-market positioning should emphasize operational expenditure conversion and accelerated deployment cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform vendors with government immunization program contracts and multi-year SaaS agreements bundling regulatory compliance updates. Long-term viability across the analysis window favors vendors with modular localization capabilities for multi-jurisdiction compliance parallelism. Acquisition target archetypes include HL7 FHIR protocol engineering specialists and cold chain IoT sensor network providers. The signal to watch is EMA MDR and IVDR software-as-a-medical-device classification enforcement accelerating CE marking requirements into European procurement criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Government Contracting | Balances CDSCO data localization with elastic compute for India's national immunization program. |
| HL7 FHIR Protocol Certification Investment | Accelerates interoperability compliance for United States hospital network procurement mandates. |
| Blockchain Audit Trail Integration | Digitizes chain-of-custody documentation to preempt FDA inspection findings for pharmacy distributors. |
| Predictive Analytics Module Development | Compresses cold chain failure response times from hours to minutes for board-level governance priorities. |
| ERP Ecosystem Partnership Expansion | Defends positioning against standalone specialists through embedded scheduling and inventory workflows. |
Research Methodology
Operator-level perspectives from hospital CIOs, government immunization program directors, pharmacy chain procurement officers, and HL7 FHIR integration specialists anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FDA digital health guidance filings, CDSCO localization requirement documentation, EMA MDR and IVDR framework updates, and hospital procurement database records. Bottom-up segmentation modeling and top-down market sizing triangulation cross-verified volume and value estimates across deployment models, end-user categories, and functionality modules.
Scenario-bracketing framed analytical outputs across the projection horizon, with conservative and expansion cases reflecting divergent cloud migration velocities and regulatory certification timeline compression. Segmentation dimensions modeled include product type architecture, deployment model infrastructure, end-user procurement authority tier, and functionality module priority. CAGRs derived from installed base turnover analysis and expansion concentration tracking. Forecast inputs incorporated EHR-embedded workflow displacement friction coefficients and sovereign data residency mandate adoption curves.
Stress conditions across hyperscaler infrastructure pricing volatility, HL7 FHIR engineering talent scarcity, and multi-jurisdiction compliance parallelism were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cloud migration mandate acceleration and immunization program digitization timelines. Macroeconomic contraction, regulatory classification expansion beyond current software-as-a-medical-device boundaries, or breakthrough distributed ledger interoperability standards would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
US Real World Evidence Solutions Market
Digital Health Solutions
US Digital Therapeutics Market
Digital Health Solutions
Global Real World Evidence Solutions Market
Digital Health Solutions
Women Digital Health Solutions Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
Electronic Data Capture Systems Market
Digital Health Solutions
North America Digital Health Market
Digital Health Solutions
Distance Health Technologies Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
Europe Digital Health Market