
 Mhealth Apps Market | 2026-2036
Mhealth Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Mhealth Apps Market Intelligence
The direct-to-consumer channel, accessed via smartphone app stores, is rewriting the patient engagement model. Apple Inc. leverages its integrated hardware and software ecosystem, creating a tightly controlled environment for health data. Google Inc. competes through the expansive reach of the Android platform and its health data aggregation services. Specialized telehealth providers like Teladoc Health, Inc. differentiate by focusing on clinical service delivery rather than just data tracking.
Mhealth apps are software programs on mobile devices that support health and wellness goals by collecting user-inputted or sensor-derived data. These applications often utilize device-specific APIs and sensors like accelerometers to track activity and vital signs for remote monitoring or personal insight. Among application types, chronic disease management represents a high-value segment, while fitness tracking commands the largest user base. The monetization model is shifting from one-time purchases towards subscription and freemium structures, which offer more predictable revenue.
Regulatory oversight is a critical variable, with the US FDA's guidance for digital health technologies and Europe's Medical Device Regulation (MDR) setting standards for clinical applications. Compliance with data privacy laws such as HIPAA in the United States and GDPR in Europe is mandatory for apps handling protected health information. Consequently, developers face a strategic choice between pursuing regulated, high-margin clinical tools or competing in the larger, less-regulated consumer wellness segment.
Market Dynamics
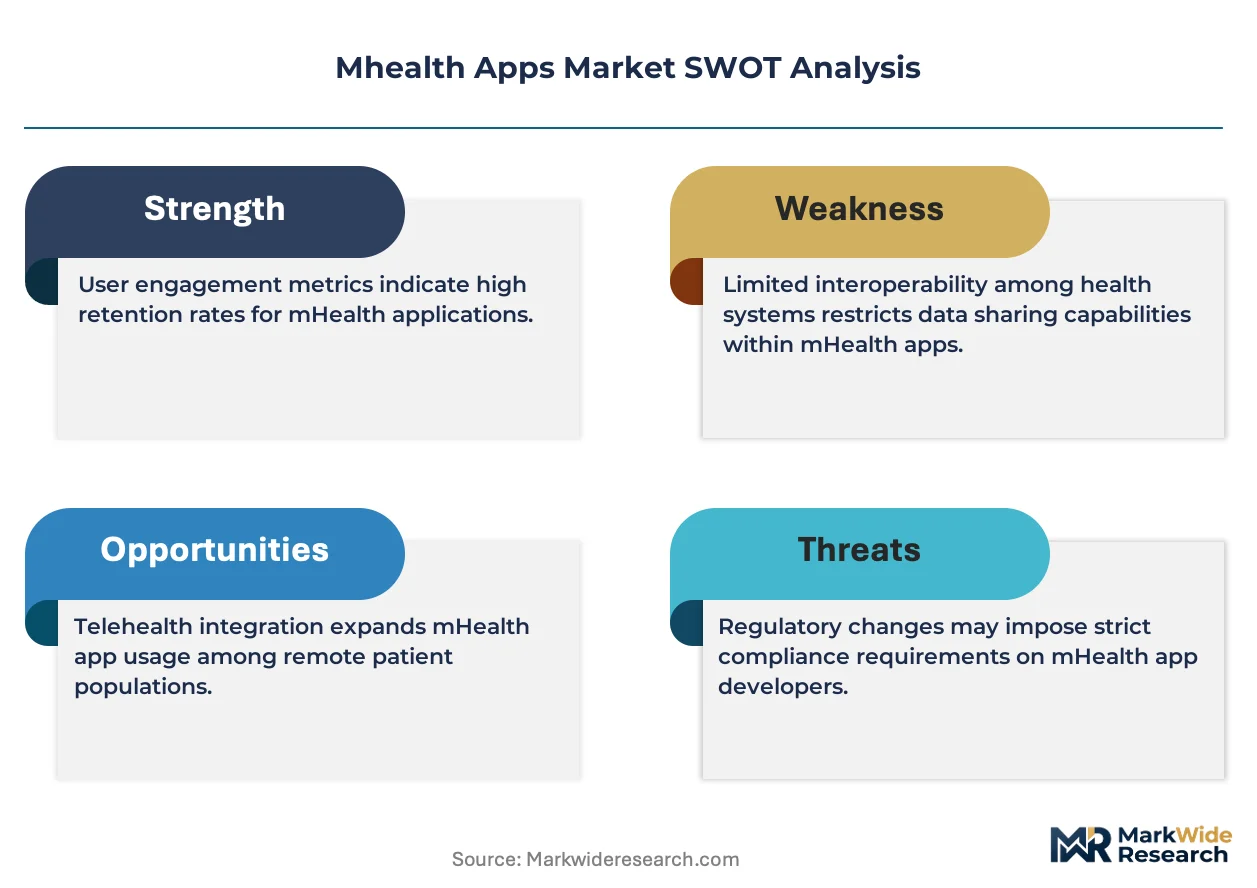
The mhealth app market's structure is defined by the strategic tension between developing for the large-scale, lightly regulated consumer wellness space and targeting the high-value, heavily regulated clinical application segment, a choice dictated by data privacy and medical device laws.
Growth Catalysts
- Government Initiatives:National digital health strategies, such as in China, create structured demand for mhealth in population health management and remote monitoring.
- Sensor Technology:Integrated sensors in smartphones provide a continuous data stream, enabling activity tracking and remote monitoring applications for consumers.
- Chronic Disease Demand:The rising prevalence of chronic conditions fuels demand for apps supporting self-management, adherence, and remote patient monitoring.
Market Restraints
- Regulatory Complexity:Divergent rules from the FDA and Europe's MDR create high compliance costs and delay development of clinical apps.
- Data Interoperability:A lack of standardized formats across EHR systems and mobile platforms prevents the seamless exchange of patient data.
- User Privacy Concerns:Skepticism over how developers collect and secure personal health data is a primary barrier to user adoption.
Strategic Opportunities
- Geriatric Care Applications:Specialized apps for the elderly focusing on fall detection and medication reminders address a large, underserved demographic.
- AI-Powered Diagnostics:Converging machine learning with sensor data creates opportunities for regulated software-as-a-medical-device (SaMD) apps for disease detection.
- Emerging Economies:Expanding into regions like Southeast Asia, where smartphone adoption outpaces mhealth infrastructure, presents a significant growth opportunity.
Industry Challenges
- Clinical Validation:Proving efficacy to satisfy regulators like the FDA and convince clinicians is a costly, time-intensive operational challenge.
- User Retention:Sustaining long-term engagement is a primary hurdle, as high churn rates undermine subscription revenue models and data collection efforts.
- Cybersecurity Threats:Protecting sensitive health data from breaches requires constant investment in security and compliance with laws like HIPAA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mhealth Apps Market |
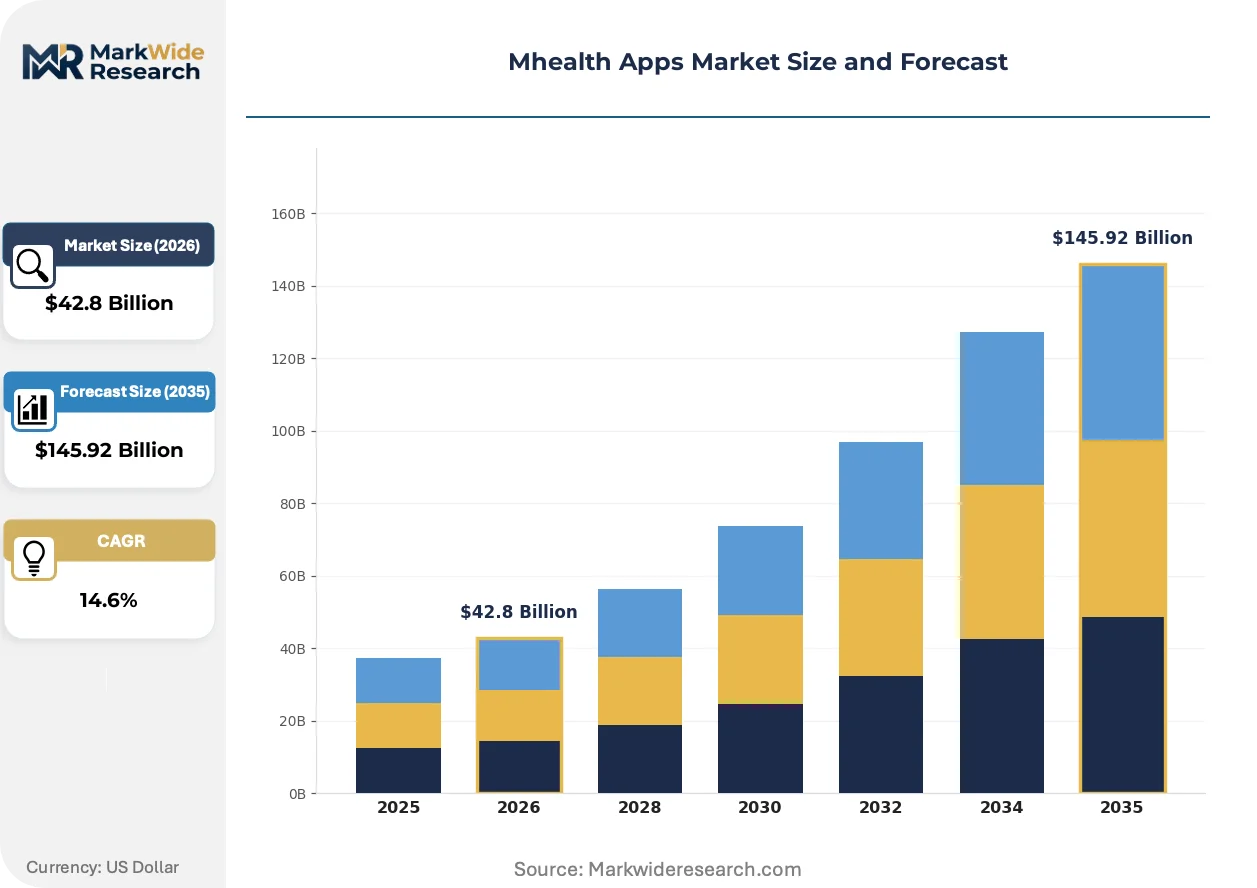
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $145.92 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Remote Monitoring, Fitness Tracking, Medication Management, Chronic Disease Management, Mental Wellness Platform: iOS, Android, Windows, Cross-Platform, Wearable OS End User: Patients, Caregivers, Fitness Enthusiasts, Health Professionals, Corporate Wellness Monetization Model: Subscription, Freemium, One-time Purchase, Advertising, In-App Purchases |
| Companies Covered | Apple Inc., Google Inc., Samsung Electronics Co. Ltd., Teladoc Health, Inc., Fitbit Inc., AirStrip Technologies, Inc., Veradigm LLC, Qualcomm Technologies, Inc., Omada Health, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mhealth Apps Market Strategic Shifts & Innovations
The professionalization of the mhealth sector is driven by a push for clinical validation and integration into healthcare workflows. This evolution shifts development focus from simple tracking towards verifiable health outcomes and regulatory compliance.
Artificial intelligence is a core component of advanced mhealth platforms, processing sensor and user-inputted data. Clinical-grade apps for chronic disease management are adopting this technology for personalized interventions. The value proposition is migrating from basic data collection to delivering predictive health insights that can anticipate adverse events.
Europe's Medical Device Regulation (MDR) is reshaping the landscape for software as a medical device. It mandates stringent clinical evidence and post-market surveillance for apps with a medical purpose. Consequently, developers of diagnostic and therapeutic mhealth tools face higher barriers to entry and must invest more in clinical trial capabilities.
A fundamental shift in monetization is underway, moving from one-time download fees toward recurring revenue models. The direct-to-consumer channel is seeing freemium and subscription-based structures displace the single-purchase model for wellness apps. This pattern is increasingly visible in chronic disease management, where providers and payers value continuous monitoring services.
Mhealth Apps Market Segmentation
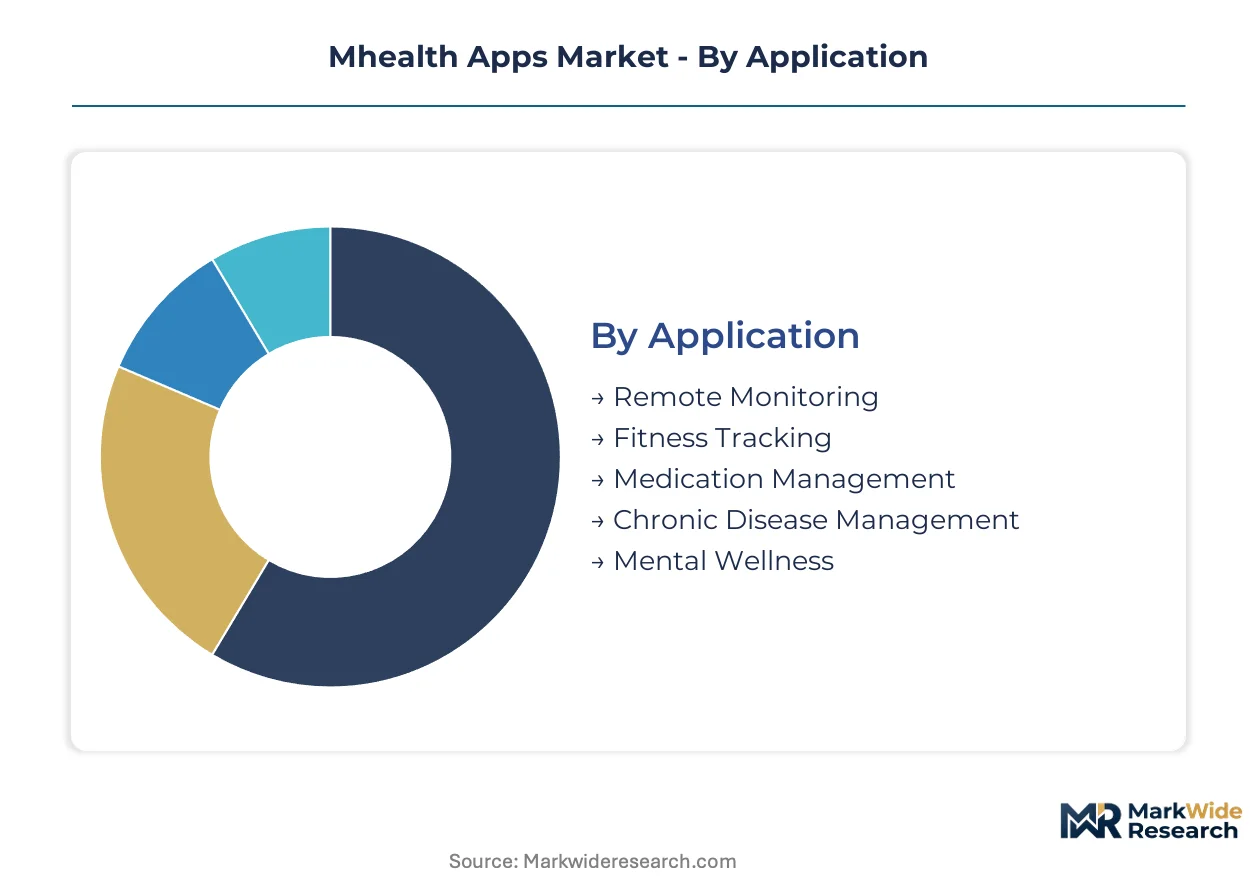
The mhealth apps market features diverse segments, each presenting unique opportunities and challenges for developers and healthcare providers. Understanding these distinctions is critical for strategic product development, market entry, and effective user engagement. Segmentation reveals how different user needs and technological capabilities drive innovation across the ecosystem.
Application:
The application segment spans a wide maturity spectrum, from established fitness tracking solutions to emerging, highly specialized clinical tools for disease management.
- Chronic Disease Management:These applications provide tools for patients to monitor symptoms, track medication adherence, and share data with healthcare providers, crucial for conditions like diabetes or heart disease. Demand is concentrating in countries with aging populations, such as Germany and Japan, driven by the need for remote patient monitoring.
- Fitness Tracking:This category encompasses apps that monitor physical activity, sleep patterns, and calorie intake, often integrating with wearable devices. It commands the largest user base globally, particularly in the United States and China, fueled by a widespread consumer focus on personal wellness.
- Remote Monitoring:These apps enable healthcare professionals to track patient vital signs and health metrics from a distance, supporting post-discharge care or managing chronic conditions.
- Medication Management:Applications in this segment help users remember to take medications, track dosages, and manage prescription refills, reducing non-adherence.
- Mental Wellness:This segment includes apps offering meditation guides, stress reduction exercises, and cognitive behavioral therapy tools to support mental health.
Fitness Tracking retains volume leadership; Chronic Disease Management holds the steepest expansion curve.
Platform:
Platform choice dictates the reach and functionality of mhealth applications, with dominant operating systems capturing the largest user volumes.
- Android:This open-source platform offers extensive reach across diverse smartphone manufacturers and price points, providing a broad user base for mhealth app distribution. Its flexibility allows for deep customization, supporting a wide array of sensor integrations across devices in India and Brazil.
- iOS:Apple's integrated hardware and software ecosystem provides a tightly controlled environment for health data, emphasizing security and a premium user experience. This platform is prevalent in affluent markets like the United States and Western Europe, appealing to users seeking seamless device integration.
- Cross-Platform:These solutions are developed to run on multiple operating systems, reducing development costs and expanding market access for developers.
- Wearable OS:Operating systems specifically designed for smartwatches and fitness trackers enable direct data collection from body sensors for health and activity monitoring.
- Windows:While less dominant in mobile, Windows platforms support enterprise-grade mhealth solutions and integration within specific healthcare IT infrastructures.
These platforms collectively define the accessibility and technical capabilities of mhealth solutions.
End User:
The end-user segment differentiates mhealth app design and features, catering to specific needs across the healthcare continuum.
- Patients:This segment comprises individuals using apps for personal health management, chronic condition monitoring, or general wellness. Patient adoption in China is driven by government healthcare initiatives promoting digital health access.
- Fitness Enthusiasts:Individuals focused on improving physical performance, tracking workouts, and monitoring health metrics fall into this category. This group represents a significant consumer base in developed economies like the United States and Australia.
- Caregivers:Apps designed for caregivers assist in managing appointments, medication schedules, and health records for dependents, often elderly or chronically ill individuals.
- Health Professionals:This segment includes doctors, nurses, and therapists utilizing apps for clinical decision support, patient communication, or remote consultation.
- Corporate Wellness:Companies implementing mhealth apps for employee health programs and incentives target this end-user group, promoting workplace well-being.
Targeting specific end-user groups allows developers to tailor features and user experiences effectively.
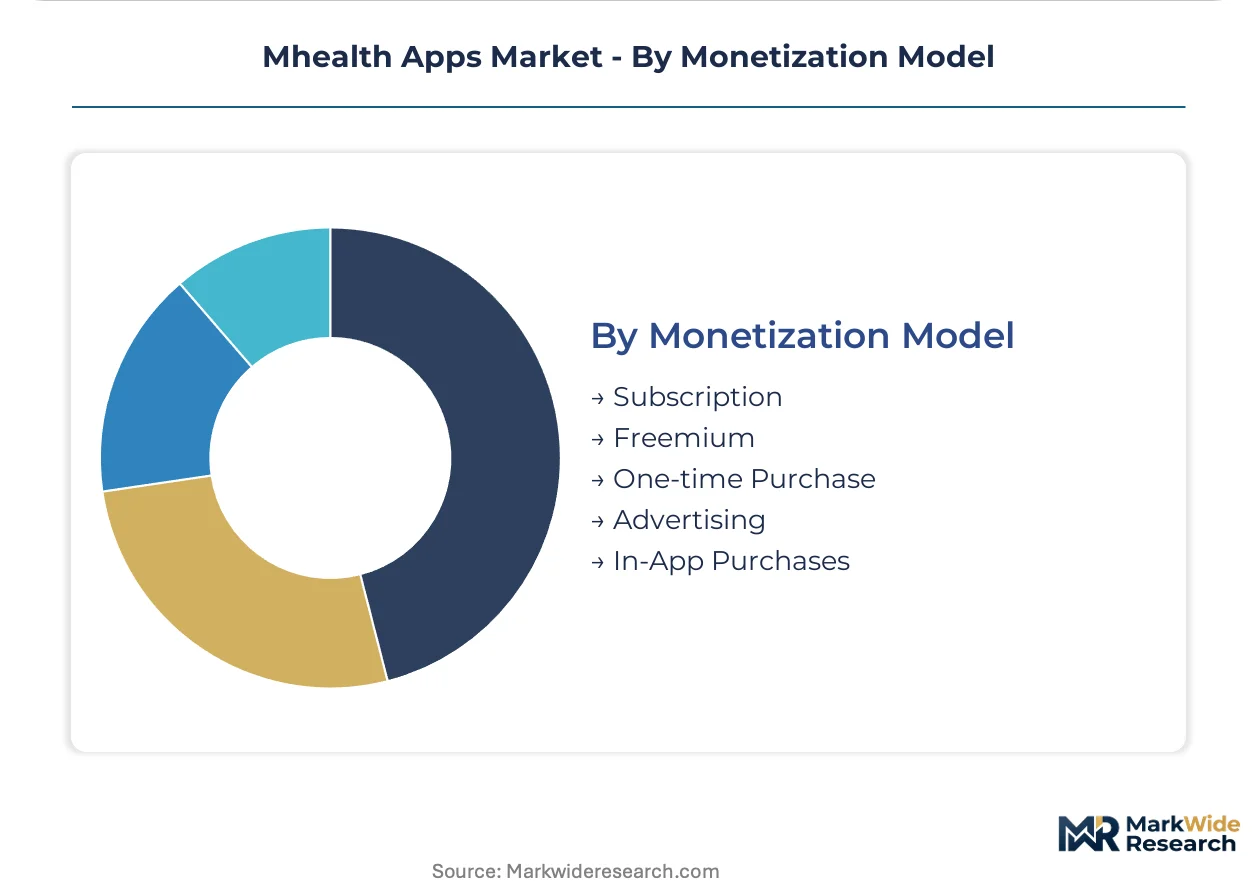
Monetization Model:
The monetization models reflect differing strategies for revenue generation, with recurring revenue streams offering greater margin predictability.
- Subscription:Users pay a recurring fee for continuous access to premium features, personalized content, or ongoing remote monitoring services. This model provides predictable revenue streams, particularly for clinical-grade applications in Europe.
- Freemium:This model offers basic app functionality for free while charging for advanced features, content, or an ad-free experience. Freemium models are effective for user acquisition and upselling in competitive consumer wellness markets like India.
- One-time Purchase:Users pay a single upfront fee to download and access all features of the application, common for niche or specialized tools.
- In-App Purchases:This model allows users to buy virtual goods, additional content, or unlock specific features directly within the application after initial download.
- Advertising:Apps generate revenue by displaying advertisements to users, often found in free-to-use wellness or fitness tracking applications.
The shift towards recurring revenue models reflects a maturing market seeking sustained financial viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National digital health strategies, exemplified by initiatives in China, create structured demand for mhealth applications in population health management. These government-led efforts prioritize remote monitoring and accessible healthcare solutions. Such policies are driving significant market expansion across various geographies.
China
Government healthcare initiatives in China drive substantial demand for mhealth in population health management and remote monitoring. The NMPA regulates digital health software as medical devices, ensuring product safety and efficacy. Digital health hubs in Beijing and Shenzhen foster innovation in AI-powered diagnostic and monitoring solutions.
United States
Consumer focus on personal wellness and chronic disease management fuels demand for mhealth applications. The FDA's guidance for digital health software and HIPAA define critical regulatory compliance pathways. Silicon Valley and Boston are centers for mhealth technology development and clinical validation efforts.
Germany
An aging population and the need for remote patient monitoring drive significant demand for chronic disease management apps. Europe's Medical Device Regulation (MDR) and GDPR shape stringent data privacy standards. Digital health clusters in Berlin and Munich focus on clinical-grade mhealth solutions and regulatory adherence.
India
Widespread smartphone penetration and the expansive reach of the Android platform increase mhealth app distribution across diverse user bases. The PLI scheme supports domestic manufacturing, indirectly benefiting digital health infrastructure and innovation. Technology hubs in Bengaluru and Hyderabad are developing localized mhealth solutions for preventative care.
Japan
Japan's aging demographic drives demand for specialized geriatric care applications and chronic disease management tools. The PMDA oversees medical device approvals, including mhealth software, ensuring product quality. Tokyo and Kyoto are key centers for developing AI-powered diagnostics and remote monitoring tools for the elderly.
Mhealth Apps Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, ranging from large technology conglomerates to specialized clinical solution providers. Three strategic archetypes define this landscape: integrated platform developers, focused telehealth service providers, and niche wellness application creators. Dominant competitive moves include strategic partnerships to expand ecosystem reach and portfolio diversification into clinical-grade offerings.
Integrated platform developers, such as Apple Inc., leverage extensive hardware-software ecosystems to offer health data management. Google Inc. exemplifies a broad platform approach, extending mhealth functionalities across its vast Android user base and health data aggregation services. Specialized telehealth providers like Teladoc Health, Inc. occupy a distinct position by focusing on direct clinical service delivery rather than solely data tracking applications.
| Leading Market Players |
|---|
| Apple Inc. |
| Google Inc. |
| Samsung Electronics Co. Ltd. |
| Teladoc Health, Inc. |
| Fitbit Inc. |
| AirStrip Technologies, Inc. |
| Veradigm LLC |
| Qualcomm Technologies, Inc. |
| Omada Health, Inc. |
| Others |
Cost & Logistics Intelligence
Digital health hubs in Beijing and Shenzhen, fostering innovation in AI-powered solutions, directly influence the pricing power of mhealth applications in the Asian market. Their concentrated development capacity can drive down costs for certain functionalities.
Pricing Analysis
Certification level, particularly compliance with FDA guidance or Europe's MDR, creates the primary spread for mhealth app pricing. Subscription models dominate, providing continuous access to premium features or remote monitoring services; personalized content and integration with clinical workflows further differentiate offerings. Pricing softness stems from intense competition within the consumer wellness segment. Clinical-grade applications command higher, more stable fees from payers and providers, as fitness enthusiasts exhibit the highest price sensitivity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are less prevalent in the mhealth app development ecosystem, which focuses on intellectual property rather than physical goods. Geographic development concentration centers on the United States, China, and Germany, where digital health hubs thrive. Component dependencies largely revolve around smartphone sensor technology and robust cloud infrastructure for data storage. Regulatory divergence across regions presents a structural supply chain risk, while distribution runs through major app stores and enterprise sales to healthcare systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mhealth apps market offers a compelling defensive-moat story for strategic investors, primarily due to significant regulatory entrenchment for clinical-grade applications. Compliance with medical device regulations creates substantial barriers to entry.
For Market Incumbents:Harden existing market positions by investing heavily in clinical validation and regulatory compliance for specialized tools. Integrate deeper into existing healthcare workflows to increase switching costs for providers and patients. This counteracts the threat from emerging specialized entrants focusing on niche clinical areas. Apple Inc. and Google Inc. can leverage their extensive ecosystems to offer comprehensive, integrated health data solutions, further entrenching their platforms.
For New Entrants and Emerging Players:Build out specialized offerings targeting underserved populations or specific chronic conditions, particularly in geriatric care applications. Focus on AI-powered diagnostics for niche disease detection, leveraging sensor data for early insights. The most penetrable segment remains emerging economies like Southeast Asia, where smartphone adoption outpaces mhealth infrastructure. A go-to-market angle focusing on localized preventative care solutions can secure early user adoption.
For Investors and Strategic Acquirers:Carve-out targets emerge from large technology conglomerates or pharmaceutical companies seeking to divest non-core digital health assets. The long-term viability of the mhealth market, spanning the next decade, remains strong, driven by chronic disease prevalence. Specialized clinical SaMD developers and data analytics firms represent prime acquisition archetypes. The signal to watch is successful regulatory approval milestones for AI-powered diagnostic applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | Secures regulatory approval and clinician trust for advanced mhealth solutions. |
| Platform Integration | Enhances user experience and data flow within Apple or Android ecosystems. |
| AI-Powered Diagnostic Development | Creates regulated software-as-a-medical-device for disease detection. |
| Emerging Market Expansion | Captures new user bases in regions with high smartphone penetration. |
| Subscription Model Optimization | Ensures predictable recurring revenue for continuous service delivery. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research validation. Primary engagement included clinicians, mhealth app developers, regulatory experts, and healthcare payers to capture nuanced market perspectives. Secondary data sources comprised FDA filings, Europe's MDR guidance, app store analytics, and academic research. This approach enabled robust bottom-up and top-down triangulation of market data points.
Forecast inputs considered global smartphone penetration rates, chronic disease prevalence, and evolving regulatory landscapes across the analysis window. The analytical framework modeled market dynamics by application type, platform, end-user, monetization model, and regulatory status. Compound annual growth rates were derived through a multi-variable regression analysis. Industry-specific inputs included sensor technology advancements and digital health investment trends.
Stress conditions across regulatory changes, cybersecurity breaches, and user adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. The forecasts reflect assumptions regarding technological progression and healthcare policy stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Asia-Pacific Digital Therapeutic (Dtx) Market
Digital Health Solutions
Cardiac AI Monitoring and Diagnostic Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Telepsychiatry Software Market
Digital Health Solutions
Global Health Kiosk Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Prescribed Health Apps Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
US Patient Engagement Solutions Market
Digital Health Solutions
Global Metaverse in Healthcare Market
Digital Health Solutions
Global Microservices in Healthcare Market