
 Digital Assistants in Healthcare Market | 2026-2036
Digital Assistants in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Assistants in Healthcare Market Analysis
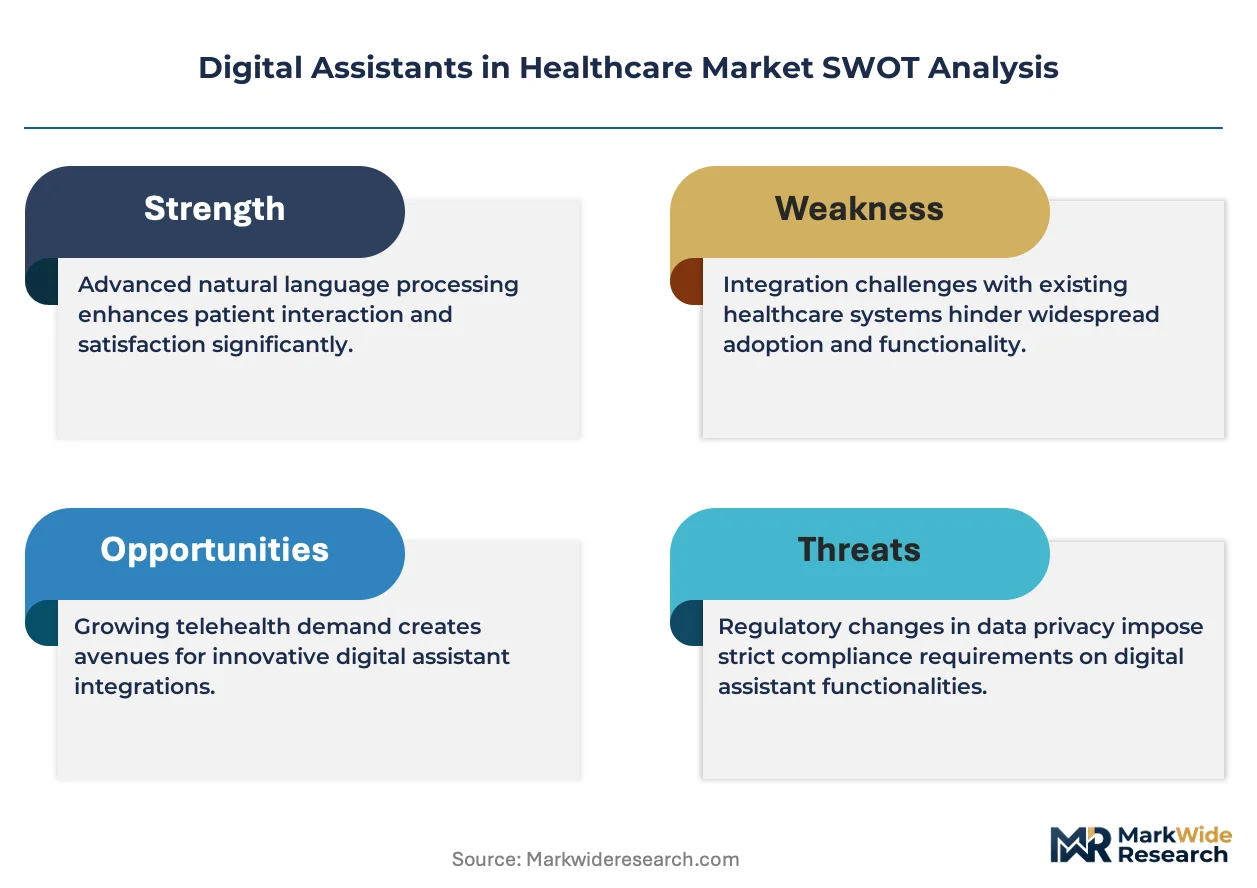
Subscription-based SaaS licensing is fragmenting capital requirements for digital health entrants, enabling smaller vendors to compete without heavy infrastructure spend. Microsoft leverages its cloud infrastructure to anchor enterprise health system deployments. Amazon.com competes through Alexa's ambient listening architecture for senior living and homecare settings. Epic Systems dominates clinical workflow integration, sustaining provider stickiness through embedded EHR connectivity.
Digital assistants in healthcare encompass AI-driven conversational interfaces that process natural language inputs to automate patient interactions, clinical documentation, and care coordination tasks, typically operating through cloud-hosted architectures with sub-second response latency for real-time triage scenarios. These systems serve primarily to reduce administrative burden on clinicians while extending care access beyond traditional facility boundaries. Voice assistants lead current revenue pools due to their integration with smart speakers and hospital room devices, though chatbots represent the fastest-expanding segment as pharmacies and insurers deploy them for scalable first-touch patient engagement. Machine learning underpins differentiation across product tiers, with cloud computing enabling the elastic infrastructure that supports fluctuating patient query volumes during public health events.
FDA oversight of software as a medical device shapes validation requirements for symptom-checking algorithms, while HIPAA mandates govern data exchange architectures between assistants and provider EHR systems. The EU AI Act introduces conformity obligations for high-risk health AI applications, affecting market access for vendors serving European hospitals. Stakeholders must monitor evolving liability frameworks that assign accountability when autonomous assistants guide patient decisions without clinician oversight.
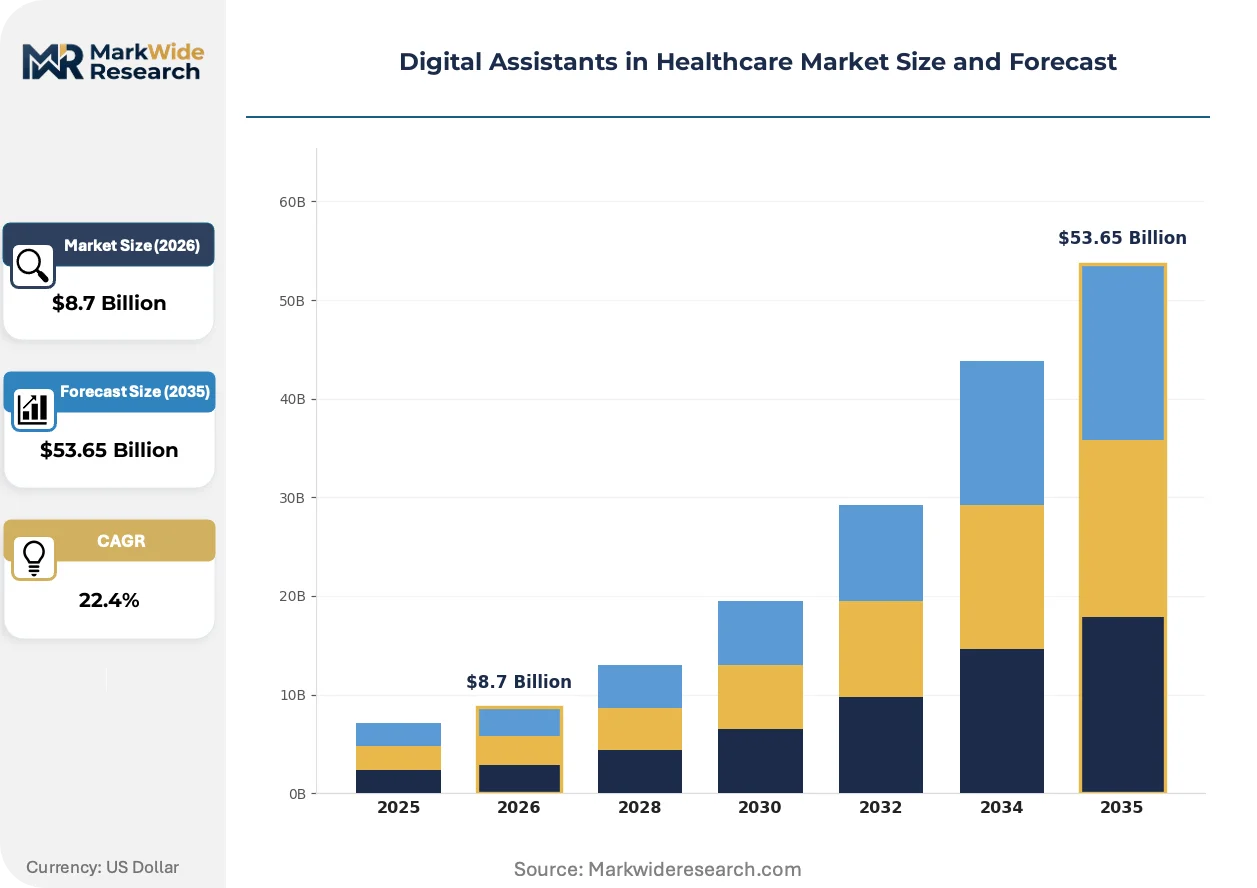
Market Dynamics
Cloud-native architectures are compressing deployment timelines for conversational AI tools, enabling health systems to bypass traditional hardware procurement cycles while embedding assistants directly into existing EHR workflows.
Growth Catalysts
- HIPAA-compliant data exchange frameworks:The US Department of Health and Human Services clarified interoperability rules, accelerating assistant-to-EHR connectivity investments.
- Voice-first triage protocols:Emergency departments deploy ambient listening systems to capture patient intake data without clinician keyboard interaction.
- Germany's Hospital Future Act:Federal digitization funding mandates AI-enabled patient communication tools for reimbursement eligibility.
Market Restraints
- GPU compute cost volatility:Cloud inference pricing for large language models fluctuates with semiconductor supply constraints, squeezing vendor margins.
- FDA validation timelines:Software-as-medical-device classification for diagnostic chatbots extends product launch cycles by 18-24 months.
- Legacy EHR integration complexity:Proprietary data formats from dominant health record vendors create technical lock-in for assistant developers.
Strategic Opportunities
- Japan's aging population clusters:Rural prefectures with 30%+ residents over 65 present unserved demand for medication adherence voice assistants.
- EU AI Act conformity pathways:Early compliance with high-risk AI system requirements creates first-mover positioning for European hospital contracts.
- Convergence of ambient sensors and NLP:Radar-based fall detection combined with conversational interfaces enables proactive senior monitoring without wearable devices.
Industry Challenges
- Clinical informatics talent scarcity:Health systems compete for data scientists who understand both transformer architectures and bedside workflow constraints.
- Multilingual training data gaps:Low-resource languages lack annotated medical dialogue corpora, degrading assistant accuracy in immigrant-serving facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Assistants in Healthcare Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Voice Assistants, Chatbots, Virtual Health Coaches, Telehealth Platforms End User: Hospitals, Clinics, Pharmacies, Homecare Providers Technology: Natural Language Processing, Machine Learning, Cloud Computing, AI Algorithms Application: Patient Engagement, Appointment Scheduling, Medication Management, Remote Monitoring |
| Companies Covered | Microsoft, Teladoc Health, Amazon.com, Google, Amwell, Infermedica, Nuance Communications, Ada Health, Epic Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Assistants in Healthcare Market Emerging Trajectories
Generative models are compressing the gap between scripted chatbot responses and open-domain clinical dialogue, forcing incumbents to retrain or replace rule-based systems deployed since 2018.
Transformer-based clinical documentation engines is rendering obsolete manual note-taking during patient encounters. Large health systems in Texas and Florida pilot ambient scribes that generate structured encounter summaries in real time. This compression of administrative burden is reallocating clinician hours from keyboards to direct patient contact.
The EU AI Act's high-risk health AI classification is mandating conformity assessments for symptom-checking algorithms before European market entry. German university hospitals now require CE-marked documentation for assistant procurement, filtering out vendors without established quality management systems. This regulatory friction favors established medical device manufacturers over pure-play AI startups.
Subscription fatigue among hospital procurement officers is fragmenting purchasing authority away from centralized IT committees toward individual department heads. Chief nursing officers in California and New York now directly evaluate voice assistant pilots for nursing unit deployment, bypassing traditional six-month enterprise software review cycles. This decentralization accelerates pilot-to-production timelines but complicates system-wide standardization.
Digital Assistants in Healthcare Market Segmentation
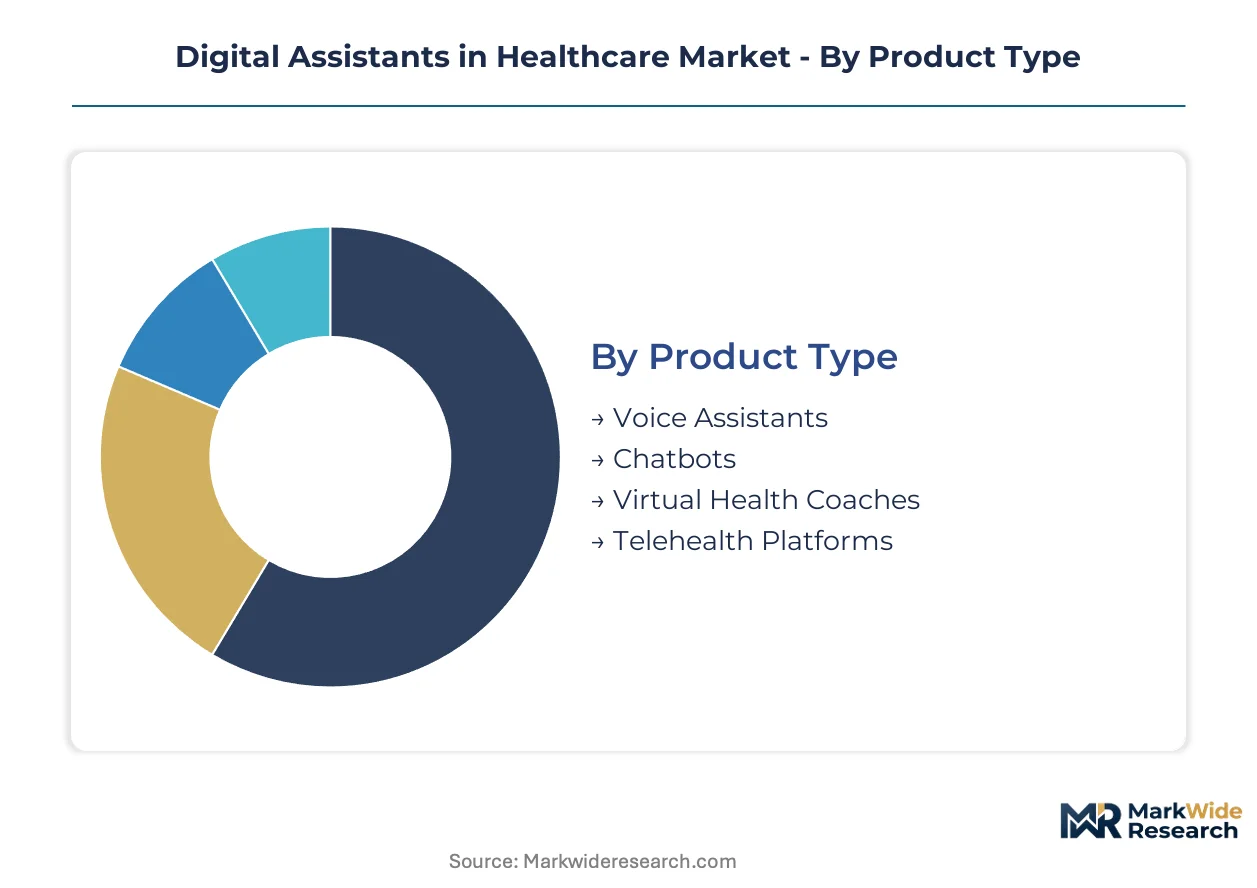
Segmentation reveals how deployment velocity varies across digital assistant modalities. Voice-first architectures cycle through procurement faster than diagnostic algorithms requiring FDA validation. Understanding these turnover differentials helps vendors align R&D investment with revenue recognition timelines.
Product Type:
Voice assistants turn inventory fastest through smart speaker integrations, while virtual health coaches face extended pilot phases for clinical outcome verification. Chatbots occupy the middle ground with rapid pharmacy deployments offset by slower hospital IT committee approvals.
- Voice Assistants:Ambient listening systems process natural language through edge-computing nodes installed in hospital rooms and senior living facilities. Demand concentrates in United States emergency departments seeking hands-free triage documentation, though FDA classification delays for diagnostic voice tools constrain rollout speed.
- Chatbots:Text-based conversational interfaces deploy through web portals and messaging applications for scalable first-touch patient screening. Pharmacies in Germany leverage these for medication interaction checks under the Hospital Future Act digitization mandates, driving faster procurement cycles than clinical settings.
- Virtual Health Coaches:AI-driven behavioral modification programs requiring longitudinal outcome data to prove ROI.
- Telehealth Platforms:Integrated video-consultation suites with embedded assistant functionality for remote diagnostic support.
Voice assistants anchor the volume base while chatbots gain share at the steepest rate.
End User:
Cost tier stratification separates enterprise health system deployments from lean pharmacy implementations. Hospital procurement involves multi-year capital planning, while homecare providers favor monthly SaaS subscriptions with minimal integration overhead.
- Hospitals:Large integrated delivery networks deploy ambient scribing and clinical documentation assistants across hundreds of examination rooms. Epic Systems EHR connectivity dominates United States hospital purchasing criteria, locking out vendors without established interface certifications.
- Clinics:Outpatient facilities prioritize appointment scheduling automation and patient intake streamlining over diagnostic functionality.
- Pharmacies:Retail pharmacy chains deploy symptom-checking chatbots for over-the-counter medication guidance, with Germany's federal digitization subsidies accelerating adoption.
- Homecare Providers:Senior care agencies in Japan's rural prefectures voice-enable medication adherence monitoring for aging populations without wearable device dependencies.
Hospitals command the premium pricing tier while homecare providers expand most quickly.
Technology:
Maturity gradients separate established cloud infrastructure from emerging transformer architectures. Natural language processing foundations enable rapid feature iteration, while machine learning model validation creates bottlenecks for regulated diagnostic applications.
- Natural Language Processing:Core linguistic parsing engines enabling intent recognition and entity extraction from patient utterances.
- Machine Learning:Pattern recognition systems trained on clinical dialogue corpora for predictive health risk stratification.
- Cloud Computing:Elastic compute infrastructure supporting query volume spikes during influenza season surges.
- AI Algorithms:Diagnostic reasoning engines subject to FDA software-as-medical-device validation timelines.
Cloud computing underpins deployment scale while AI algorithms face the steepest regulatory friction.
Application:
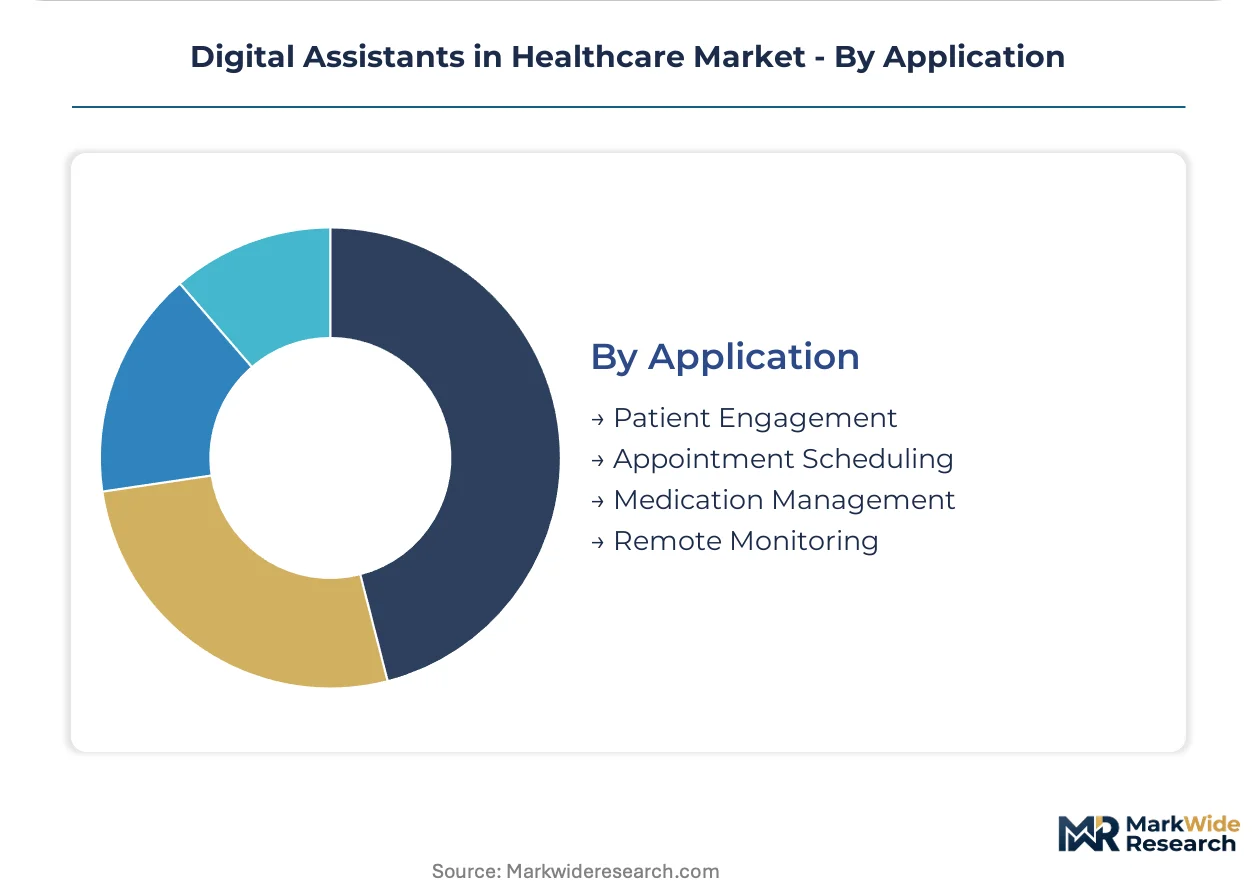
Volume concentration favors administrative automation over clinical decision support. Appointment scheduling and patient engagement generate recurring transaction fees, while remote monitoring requires hardware bundling that complicates margin structures.
- Patient Engagement:Automated outreach for care plan adherence and preventive screening reminders.
- Appointment Scheduling:Calendar integration with EHR systems to reduce no-show rates and optimize provider utilization.
- Medication Management:Voice-enabled adherence tracking and drug interaction alerting for polypharmacy patients.
- Remote Monitoring:Integration of conversational interfaces with biometric sensors for chronic disease surveillance.
Patient engagement delivers the broadest installed base while remote monitoring climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement officers in the United States, Germany, and Japan concentrate purchasing authority for digital assistant deployments, with federal digitization mandates in Germany and acute aging pressures in Japan reshaping vendor prioritization.
United States
Emergency departments in Texas and Florida pilot ambient scribing systems to eliminate clinician keyboard time during patient intake. FDA software-as-medical-device classification timelines extend diagnostic chatbot launches by 18-24 months, compressing vendor margins. Epic Systems EHR connectivity dominates purchasing criteria across large integrated delivery networks, locking out assistants without certified interface protocols.
Germany
University hospitals in Berlin and Munich now require CE-marked documentation for assistant procurement under EU AI Act high-risk health AI classifications. The Hospital Future Act mandates AI-enabled patient communication tools for federal reimbursement eligibility, accelerating pharmacy chatbot deployments. Retail pharmacy chains leverage symptom-checking interfaces for over-the-counter medication guidance.
Japan
Rural prefectures with 30% or more residents over 65 drive unserved demand for medication adherence voice assistants without wearable dependencies. METI digitization subsidies support senior care agency procurement of ambient listening systems. Homecare providers in Kyushu and Hokkaido voice-enable chronic disease monitoring for aging populations.
United Kingdom
NHS trusts in London and Manchester evaluate conversational AI for appointment scheduling automation to reduce no-show rates. MHRA guidance on AI-enabled medical devices shapes validation pathways for symptom-checking algorithms. Procurement fragmentation shifts authority from centralized IT committees toward individual department heads.
India
Telemedicine platforms in Maharashtra and Karnataka integrate chatbot functionality for scalable first-touch patient screening in Tier-2 cities. CDSCO oversight of software medical devices creates compliance bottlenecks for diagnostic algorithm vendors. Health tech clusters in Bengaluru and Hyderabad attract venture capital for multilingual NLP development addressing low-resource language gaps.
Digital Assistants in Healthcare Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Cloud infrastructure providers anchor enterprise health system deployments through subscription-based SaaS licensing that fragments capital requirements. EHR-embedded specialists sustain provider stickiness through workflow integration. Pure-play AI startups face regulatory friction from FDA and EU AI Act validation timelines. Dominant competitive moves include strategic partnerships with hospital networks and technology licensing for ambient sensor convergence.
Within the cloud infrastructure tier, Microsoft and Amazon.com represent channel-controlling archetypes leveraging hyperscale compute resources. Epic Systems occupies a position exemplifying EHR-embedded specialists with dominant clinical workflow integration. Among pure-play health AI entities, Ada Health and Infermedica sit within the diagnostic reasoning segment facing the steepest regulatory validation requirements.
| Leading Market Players |
|---|
| Microsoft |
| Teladoc Health |
| Amazon.com |
| Amwell |
| Infermedica |
| Nuance Communications |
| Ada Health |
| Epic Systems |
| Others |
Supply Flow & Price Mechanics
Bengaluru's health tech cluster anchors GPU cloud compute provisioning for conversational AI inference, with capacity bottlenecks during influenza season surges translating directly into subscription pricing volatility for hospital SaaS contracts.
Pricing Analysis
Cost-plus contracts with NVIDIA H100 indexation dominate enterprise health system procurement, with hyperscaler markups passing through semiconductor supply constraints. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated diagnostic algorithms from administrative automation tools from basic appointment scheduling bots. Pricing pressure stems from GPU compute cost volatility squeezing vendor margins on large language model inference. Pharmacy chains exhibit highest price sensitivity due to thin OTC medication guidance margins, while academic medical centers accept premium tiers for Epic-certified workflow integration.
Supply Chain Analysis
Upstream feedstock for transformer training and inference concentrates on Taiwan Semiconductor Manufacturing for advanced node fabrication, South Korea's SK Hynix for HBM memory stacks, and United States-based NVIDIA for GPU architecture licensing. Cloud infrastructure providers draw from these concentrated sources for elastic compute provisioning to health systems. Single-source vulnerability in advanced semiconductor lithography equipment creates supply chain risk for vendors scaling diagnostic AI deployments. Distribution runs through hyperscaler marketplaces and direct EHR vendor partnerships rather than traditional health IT channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates durable barriers: FDA software-as-medical-device validation timelines and Epic Systems EHR certification requirements lock out unqualified competitors for 18-24 month cycles.
For Market Incumbents: Harden regulatory positioning by accelerating FDA 510(k) submissions for diagnostic voice tools before EU AI Act conformity deadlines compress European access. Deepen backward integration into ambient sensor hardware to control fall-detection and radar-based monitoring convergence points. Vertical integration of edge-computing nodes insulates against hyperscaler pricing volatility threatening SaaS margins.
For New Entrants and Emerging Players: Pursue Japan's rural prefectures with 30% plus senior populations as the most penetrable geography for medication adherence voice assistants without wearable dependencies. Target Germany's retail pharmacy chains benefiting from Hospital Future Act digitization subsidies for symptom-checking chatbot deployments. Go-to-market through GPO contracts managers rather than hospital IT committees to bypass Epic certification bottlenecks.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because FDA and EU AI Act validation moats will widen as diagnostic AI classification tightens. Acquisition target archetype: pure-play diagnostic reasoning vendors with existing CE marking and 510(k) clearances. Signal to watch is FDA guidance expansion on large language model-based clinical decision support as inflection indicator for validation cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Diagnostic voice tools gain 18-24 month competitive lead over unvalidated entrants. |
| Epic Systems EHR Certification | Workflow integration locks out non-certified assistants from United States hospital procurement. |
| EU AI Act Conformity Pathway | CE marking enables German university hospital contracts under high-risk AI classification. |
| Hospital System Partnership | Texas and Florida pilot programs validate ambient scribing for enterprise rollout. |
| Reimbursement Strategy Development | Germany's Hospital Future Act ties federal funding to AI-enabled patient communication tools. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital purchasing committee chairs, clinical informatics officers, GPO contracts managers, and FDA regulatory consultants and refined through secondary validation against CMS Medicare reimbursement databases, FDA 510(k) clearance records, Epic Systems certification registries, and EU AI Act conformity assessment documentation. Bottom-up deployment counts across United States, Germany, and Japan were triangulated with top-down SaaS revenue estimates from hyperscaler health vertical disclosures.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across product type (voice assistants, chatbots, virtual health coaches), end user (hospitals, pharmacies, homecare providers), technology maturity (NLP foundations versus transformer architectures), and application automation depth (administrative versus clinical decision support). CAGRs were derived from elasticity-adjusted adoption curves and hardware procurement cycle analysis. Industry-specific inputs included GPU compute pricing volatility indices and EHR interface certification timelines.
Sensitivities concentrate around FDA guidance revisions on large language model clinical applications and EU AI Act enforcement intensity on high-risk health AI classification. Cross-checking against hospital capital expenditure surveys and health system IT budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Smart Hospital Market
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
US Digital Health Market
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
Connected Health and Wellness Solutions Market
Digital Health Solutions
Global Health Kiosk Market
Digital Health Solutions
Digital Therapeutics Market
Digital Health Solutions
Global Surgical Preoperative Planning Software Market
Digital Health Solutions
Telepsychiatry Software Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Global Patient Portal Market
Digital Health Solutions
Global Metaverse in Healthcare Market
Digital Health Solutions
Virtual Reality (VR) in Healthcare Market
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
Pregnancy Tracking and Postpartum Care Apps Market