
 VR in Healthcare Market | 2026-2036
VR in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
VR in Healthcare Market Outlook
Surgical training is broadening its share of VR healthcare procurement as medical schools replace cadaver-based instruction with repeatable immersive modules. Meta Platforms, Inc. leverages its consumer VR hardware heritage to push enterprise clinical certifications. Siemens Healthineers anchors its position through deep integration with existing imaging and surgical planning workflows. AppliedVR, Inc. specializes in FDA-cleared pain management protocols that differentiate it from general wellness applications.
VR in Healthcare encompasses head-mounted display systems, motion tracking sensors, haptic feedback interfaces, and software platforms engineered to deliver immersive therapeutic, educational, or surgical simulation environments with sub-20 millisecond latency requirements. These systems functionally replicate anatomical structures, procedural sequences, or controlled exposure scenarios to reduce training costs, improve procedural consistency, or deliver non-pharmacological interventions. Surgical simulators lead product type revenue due to high per-unit pricing and institutional procurement cycles, while pain management tools represent the fastest-growing segment as reimbursement codes for digital therapeutics mature. Rehabilitation solutions occupy concentrated margin pools in post-acute settings where bundled payment models incentivize outcome efficiency.
The FDA's digital health pre-certification program and HIPAA security rule collectively shape product development requirements, data architecture investments, and go-to-market timelines for therapeutic VR systems. ISO 13485 quality management standards and IEC 60601 electrical safety specifications further constrain hardware design choices for devices deployed in clinical settings. Stakeholders must monitor evolving reimbursement determinations from CMS and parallel health technology assessment bodies, as coverage decisions will determine whether therapeutic VR shifts from pilot budgets to sustainable operational expenditures.
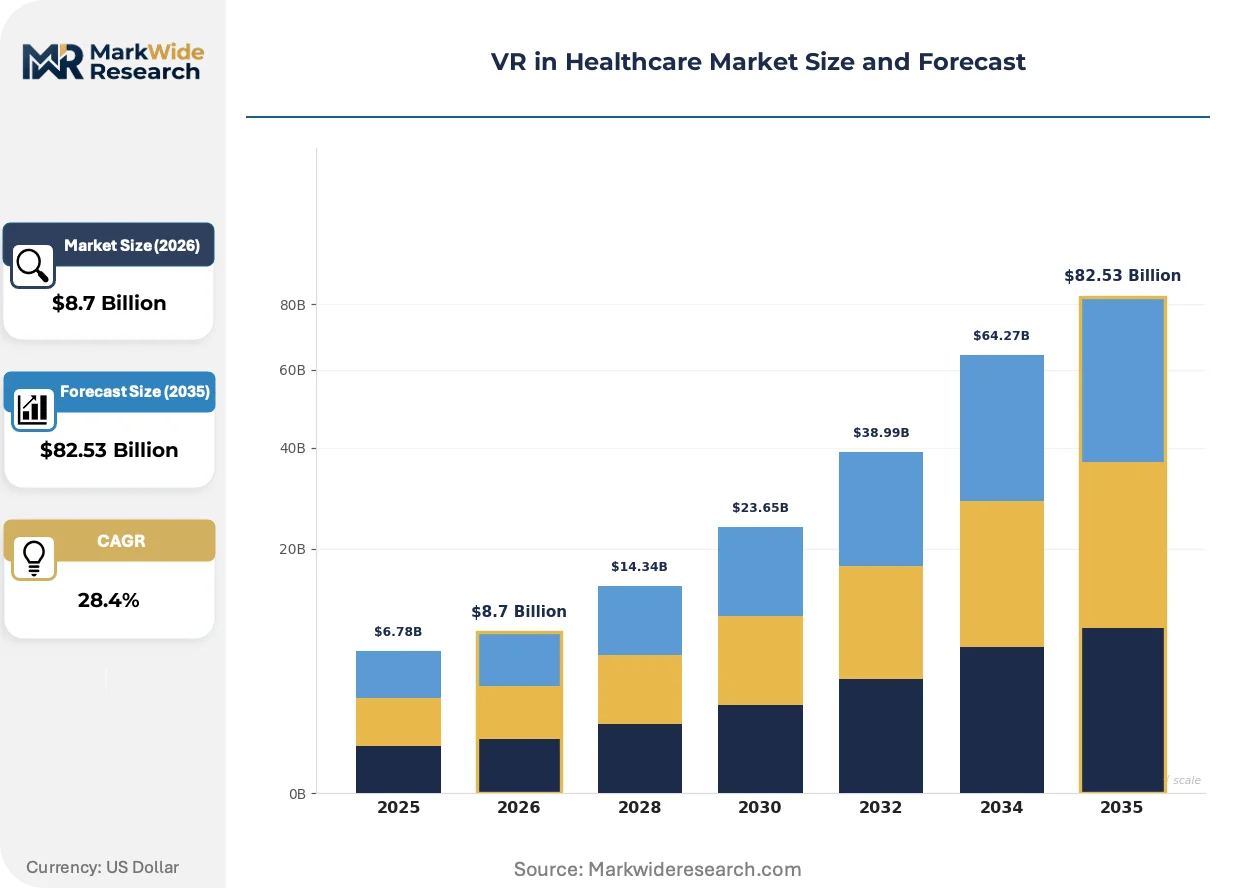
Market Dynamics
FDA's digital health pre-certification pathway is compressing commercialization timelines for therapeutic VR devices while academic medical centers anchor early deployment of validated surgical platforms.
Growth Catalysts
- Reimbursement code maturation:CMS determinations for digital therapeutics are converting pilot budgets into sustainable operational expenditures for pain management protocols.
- Surgical training substitution:Medical schools are replacing cadaver-based instruction with repeatable immersive modules that reduce per-procedure training costs.
- Hardware latency improvements:Sub-20 millisecond response thresholds now enable haptic feedback interfaces that replicate anatomical structures with clinical fidelity.
Market Restraints
- ISO 13485 compliance burden:Quality management certification requirements extend hardware design cycles and inflate development overhead for clinical-grade devices.
- HIPAA security architecture:Data protection rule mandates force substantial investments in encrypted transmission infrastructure and audit-capable storage systems.
- Electrical safety certification:IEC 60601 specifications constrain component sourcing and manufacturing location choices for devices deployed in patient care settings.
Strategic Opportunities
- Post-acute rehabilitation penetration:Bundled payment models in skilled nursing facilities create margin pools for outcome-efficient VR therapy solutions.
- FDA breakthrough device designation:Expedited review pathways for therapeutic VR accelerate time-to-revenue for novel non-pharmacological interventions.
- Haptic-EMR convergence:Integration between force-feedback interfaces and electronic medical record systems enables procedure documentation automation.
Industry Challenges
- Clinical validation timelines:Randomized controlled trial requirements for FDA clearance extend capital lock-up periods before commercial launch.
- Legacy system interoperability:PACS and surgical planning software integration demands custom API development for each hospital network deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR in Healthcare Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VR Training Simulators, Surgical Simulators, Rehabilitation Solutions, Pain Management Tools End User: Hospitals, Clinics, Medical Schools, Rehabilitation Centers Application: Patient Treatment, Surgical Training, Medical Education, Anxiety Reduction Technology: Head-Mounted Displays, Motion Tracking, Haptic Feedback, Software Platforms |
| Companies Covered | Meta Platforms, Inc., Microsoft Corporation, HTC Corporation, Siemens Healthineers, Koninklijke Philips N.V., Samsung Electronics Co. Ltd., GE Healthcare, Sony Corporation, AppliedVR, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR in Healthcare Market Strategic Shifts
Immersive simulation systems are overtaking traditional training modalities across medical education and therapeutic delivery, with regulatory frameworks adapting to accommodate software-as-medical-device classifications.
Standalone wireless headsets are overtaking tethered systems in surgical training environments. Medical schools in the United States are adopting untethered devices for multi-station simulation labs. This shift is overtaking infrastructure-heavy deployments that required dedicated computer suites and technical support staff.
EMA's Medical Device Regulation is tightening clinical evidence requirements for VR therapeutic claims in the European Union. Manufacturers must now submit prospective trial data rather than retrospective real-world evidence for Class IIa and above classifications. Rehabilitation device categories face the steepest compliance burden as notified bodies apply stricter scrutiny to software-driven interventions.
Subscription licensing is displacing perpetual purchase models in institutional VR procurement. Hospital systems are negotiating enterprise-wide access agreements rather than per-unit capital expenditures. Academic medical centers in Germany and the Netherlands are piloting usage-based billing structures that align vendor revenue with actual training session completion rates.
VR in Healthcare Market Segmentation
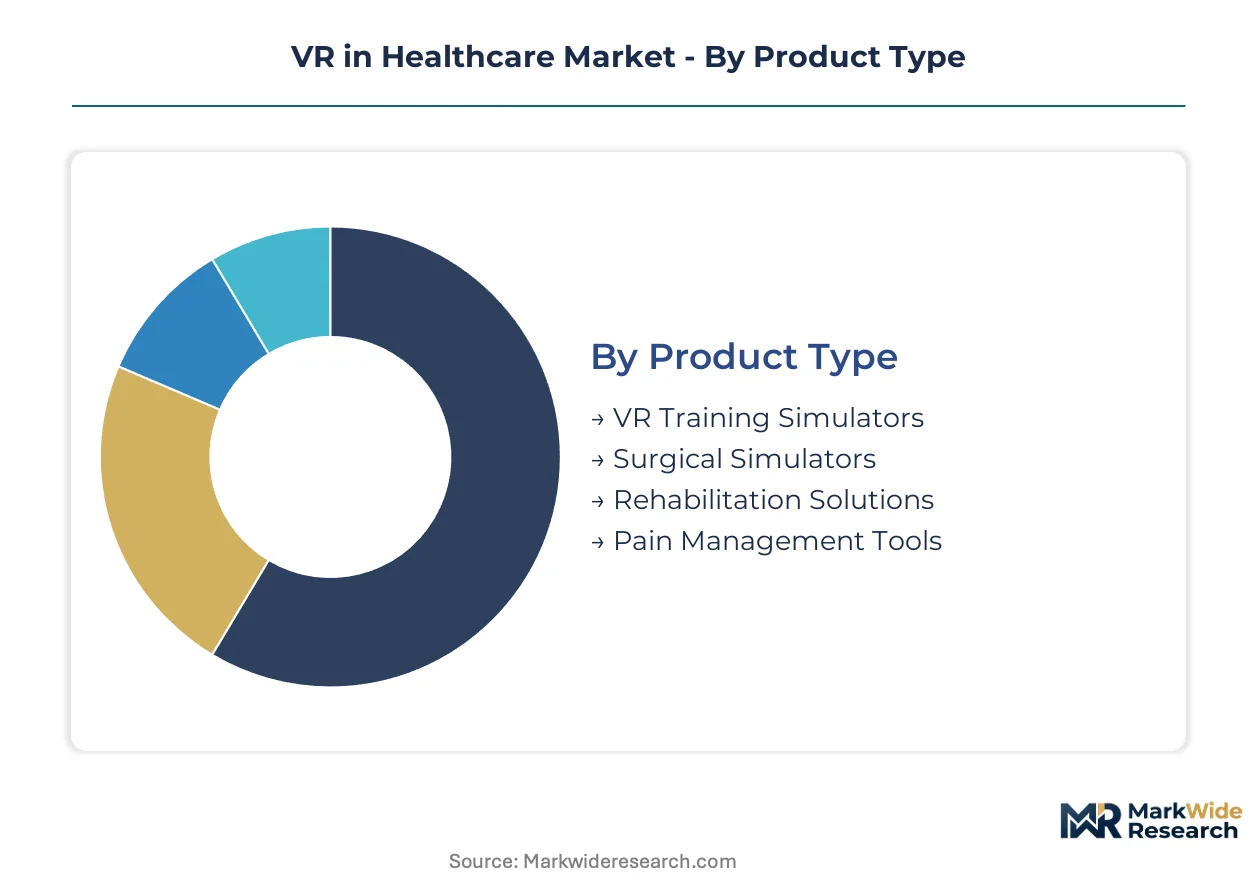
VR in Healthcare Market segmentation reveals how procurement priorities diverge between capital-intensive surgical platforms and scalable therapeutic applications. Understanding these category boundaries clarifies why reimbursement pathways, regulatory requirements, and hardware specifications vary dramatically across customer types.
Product Type:
Replacement cycles for legacy simulation hardware are accelerating as medical schools phase out cadaver-based instruction and tethered computer suites.
- VR Training Simulators:These systems replicate anatomical procedures with sub-20 millisecond latency for repeatable skill acquisition. Demand concentrates in United States academic medical centers replacing infrastructure-heavy deployments with standalone wireless configurations.
- Surgical Simulators:High per-unit pricing and institutional procurement cycles anchor revenue concentration here. FDA digital health pre-certification compresses commercialization timelines for vendors integrating with existing PACS and surgical planning workflows.
- Rehabilitation Solutions:Post-acute settings in skilled nursing facilities drive procurement under bundled payment models that reward outcome efficiency.
- Pain Management Tools:CMS reimbursement determinations for digital therapeutics are converting pilot budgets into sustainable operational expenditures.
Surgical Simulators sits at the top of the volume ranking, with Pain Management Tools climbing the fastest.
End User:
Customer procurement authority determines pricing structure and contract duration across institutional healthcare settings.
- Hospitals:Enterprise-wide access agreements are displacing perpetual purchase models as health systems negotiate subscription licensing for multi-department deployment.
- Clinics:Smaller footprint requirements favor untethered devices with reduced technical support demands.
- Medical Schools:Multi-station simulation labs in the United States are adopting wireless headsets for cadaver replacement curricula.
- Rehabilitation Centers:Bundled payment incentives in post-acute care create concentrated margin pools for outcome-efficient therapy solutions.
Hospitals command the largest installed base, with Rehabilitation Centers expanding most quickly under value-based care mandates.
Application:
Functional use cases determine regulatory pathway complexity and clinical evidence requirements for market access.
- Patient Treatment:FDA-cleared therapeutic protocols for non-pharmacological interventions require randomized controlled trial data extending capital lock-up periods before commercial launch.
- Surgical Training:Repeatable immersive modules reduce per-procedure training costs while improving procedural consistency across residency programs.
- Medical Education:Academic medical centers in Germany and the Netherlands are piloting usage-based billing structures that align vendor revenue with actual training session completion rates.
- Anxiety Reduction:Controlled exposure scenarios for phobia and PTSD treatment face EMA Medical Device Regulation scrutiny requiring prospective trial data rather than retrospective real-world evidence.
Surgical Training holds the deepest penetration, with Patient Treatment gaining share fastest as reimbursement codes mature.
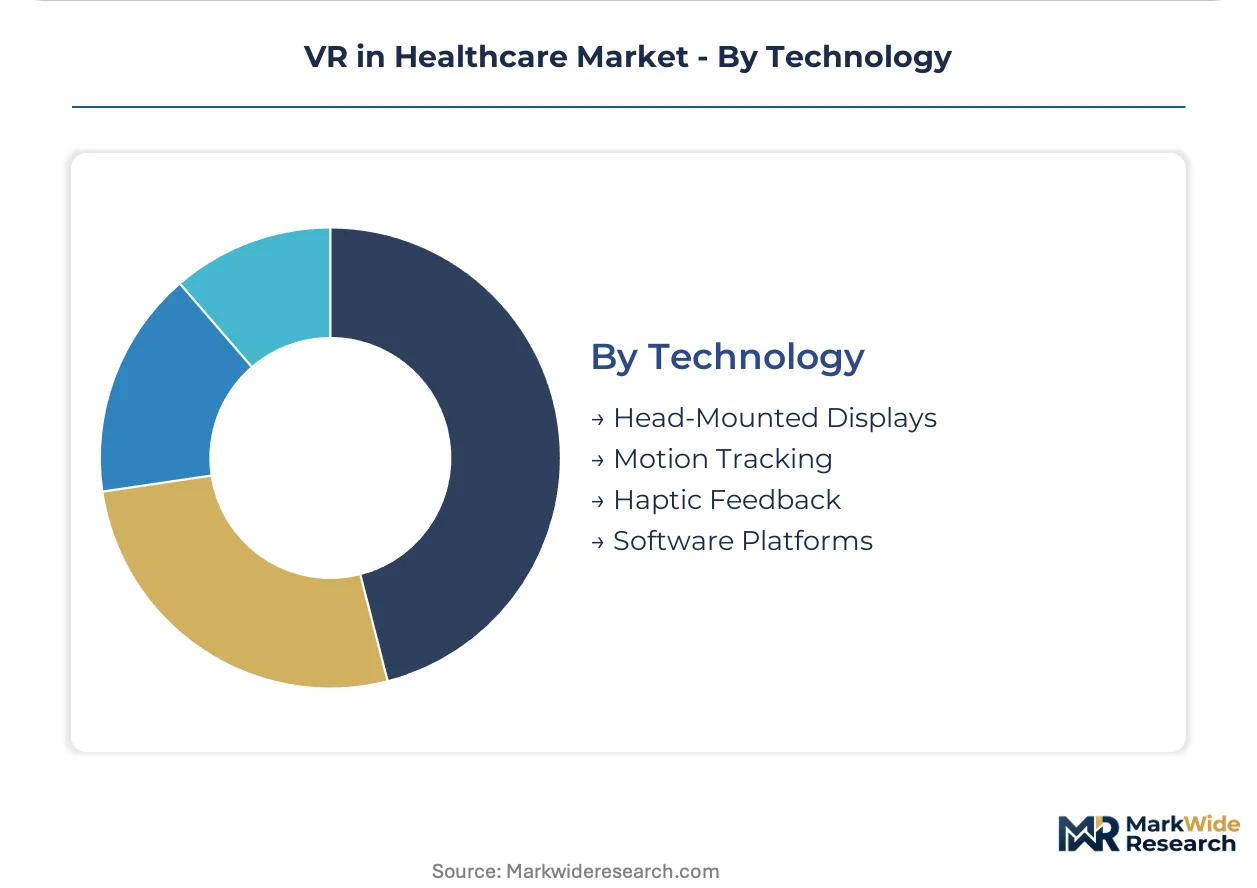
Technology:
Component-level specifications determine latency thresholds, integration complexity, and electrical safety certification requirements.
- Head-Mounted Displays:Standalone wireless configurations are overtaking tethered systems in surgical training environments, eliminating dedicated computer suite requirements.
- Motion Tracking:Sub-20 millisecond response thresholds enable spatial precision for anatomical replication in procedural sequences.
- Haptic Feedback:Force-feedback interfaces integrated with electronic medical record systems enable procedure documentation automation.
- Software Platforms:ISO 13485 quality management certification and HIPAA security architecture mandates force substantial investments in encrypted transmission infrastructure.
Head-Mounted Displays dominate procurement volumes, with Haptic Feedback showing the steepest expansion trajectory as EMR convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor location decisions as manufacturers weigh FDA pre-certification timelines against EMA Medical Device Regulation compliance costs. Production and clinical trial investments concentrate where reimbursement pathways offer the clearest commercialization trajectory.
United States
Academic medical centers in Boston and the Research Triangle anchor early-stage deployment of validated surgical platforms. FDA's digital health pre-certification pathway compresses commercialization timelines for therapeutic VR devices. The Mayo Clinic cluster in Rochester, Minnesota pilots usage-based billing structures that align vendor revenue with training session completion rates.
Germany
Siemens Healthineers leverages deep imaging workflow integration to capture institutional procurement cycles. EMA Medical Device Regulation tightening on Class IIa software devices demands prospective trial data rather than retrospective evidence. The Baden-Württemberg medical technology corridor concentrates haptic-EMR convergence development for procedure documentation automation.
China
NMPA regulatory pathways for innovative medical devices accelerate domestic therapeutic VR commercialization. Domestic hardware manufacturers exploit cost advantages in motion tracking component production. The Yangtze River Delta medical device cluster scales standalone wireless headset manufacturing for export markets.
United Kingdom
NHS England digital therapeutics reimbursement pilots convert pain management protocols from pilot budgets to operational expenditures. MHRA post-Brexit regulatory autonomy creates parallel submission requirements for UK market access. The London-Oxford-Cambridge golden triangle concentrates surgical simulation research partnerships between medical schools and VR vendors.
Japan
PMDA breakthrough designation pathways expedite review for novel non-pharmacological interventions. METI funding programs support haptic feedback interface development for aging population rehabilitation applications. The Kansai medical device cluster in Osaka-Kobe anchors post-acute VR therapy solution deployment under bundled payment models.
VR in Healthcare Market Competitive Environment
Strategic partnerships dominate the current landscape as hardware specialists ally with clinical workflow incumbents to bypass legacy system interoperability barriers. The vendor base fragments across consumer technology heritage players, dedicated medical device manufacturers, and emerging digital therapeutics pure-plays. Three archetypes define positioning: imaging-integrated platform vendors, FDA-cleared therapeutic protocol specialists, and untethered hardware scale producers. M&A activity concentrates on haptic feedback technology acquisitions and digital health pre-certification capability purchases.
Among consumer-platform heritage players, Meta Platforms, Inc. and Microsoft Corporation occupy positions exemplifying the hardware-certification bridge archetype. AppliedVR, Inc. represents the FDA-cleared therapeutic specialist tier. Siemens Healthineers anchors the imaging-integrated platform category through enterprise workflow embedding.
| Leading Market Players |
|---|
| Meta Platforms, Inc. |
| Microsoft Corporation |
| HTC Corporation |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Samsung Electronics Co. Ltd. |
| GE Healthcare |
| Sony Corporation |
| AppliedVR, Inc. |
| Others |
Value Chain & Pricing Dynamics
Medical school procurement committees demanding standalone wireless configurations are forcing component suppliers to retool for untethered headset production, compressing margins on legacy tethered systems while opening premium pricing tiers for sub-20 millisecond latency modules.
Pricing Analysis
Distributor margins for clinical-grade VR hardware sit at 15-25 percent above consumer equivalents, reflecting ISO 13485 certification premiums and FDA pre-certification investment recovery. Three-tier pricing structure across FDA-cleared therapeutic, CE-marked clinical training, and uncertified wellness applications anchors differentiation. Pricing pressure stems from academic medical centers consolidating vendor lists under enterprise subscription agreements. Hospital systems show lowest price sensitivity for surgical simulators with PACS integration, while standalone pain management tools face acute budget scrutiny from clinic procurement officers.
Supply Chain Analysis
Dual-sourcing mandates from United States health systems are pushing headset manufacturers to qualify secondary motion tracking sensor suppliers beyond dominant Yangtze River Delta producers. Component sourcing draws from Taiwan for display panels, South Korea for haptic feedback actuators, and China for final assembly. Single-source vulnerability concentrates in specialized surgical planning software licenses. Distribution runs through regional medical device distributors with GPO contracting relationships, bypassing consumer electronics retail channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VR in Healthcare has entered a late-cycle quality phase where FDA clearance and haptic-EMR integration capabilities command decisive procurement preference over raw hardware specifications.
For Market Incumbents: Hedge against standalone wireless commoditization by deepening software platform stickiness through electronic medical record integration investments. Acquire haptic feedback specialists to defend margin pools in surgical simulation against consumer-platform heritage entrants. Prioritize ISO 13485-certified manufacturing capacity in Germany and the United States to mitigate EMA Medical Device Regulation compliance risk. For New Entrants and Emerging Players: Capture post-acute rehabilitation whitespace in United States skilled nursing facilities where bundled payment models reward outcome-efficient therapy solutions. Target pain management protocols with CMS reimbursement code alignment as the most penetrable therapeutic segment. Lead with usage-based billing structures that reduce hospital capital expenditure friction. For Investors and Strategic Acquirers: Asymmetric upside sits with digital therapeutics pure-plays holding FDA breakthrough device designations for non-pharmacological interventions. Five-to-ten year viability hinges on reimbursement code maturation converting pilot budgets to sustainable operational expenditures. Monitor CMS national coverage determinations for digital therapeutics as the decisive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Compresses commercialization timelines for therapeutic VR devices seeking 510(k) pathways. |
| Hospital System Partnership | Secures enterprise subscription agreements that displace perpetual purchase procurement models. |
| Haptic-EMR Integration Development | Enables procedure documentation automation that differentiates surgical simulation offerings. |
| Reimbursement Strategy Investment | Aligns pain management protocols with CMS determinations for sustainable operational expenditure. |
| CE Marking Pathway Execution | Addresses EMA Medical Device Regulation prospective trial data requirements for EU market access. |
Study Parameters
Direct dialogue with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and digital health regulatory consultants grounded the qualitative foundation. Secondary validation drew from FDA 510(k) database filings, CMS Medicare reimbursement determinations, hospital procurement databases, and GPO contract award disclosures. Bottom-up unit economics modeling triangulated against top-down market sizing across the analysis window.
Segment-level outputs reflect product type, end user institution scale, application use case, and technology component specifications modeled across the projection horizon. CAGRs derived from procedure volume growth trajectories, medical school enrollment expansion, and reimbursement code adoption curves. Forecast inputs incorporated surgical training substitution rates for cadaver-based instruction and standalone wireless headset replacement cycles for tethered legacy systems.
FDA pre-certification pathway delays, EMA Medical Device Regulation evidence requirement tightening, and CMS reimbursement determination reversals are the dominant revision risks. Deviation in CMS national coverage determinations for digital therapeutics would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Mhealth Applications Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
North America Virtual Reality (VR) Health Market
Digital Health Solutions
Care Coordination Software Market
Digital Health Solutions
Global Patient Engagement Solution Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Digital Therapeutics Market
Digital Health Solutions
Econsent in Healthcare Market
Digital Health Solutions
Medical Animation Market
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Electronic Data Capture Systems Market
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
US Digital Therapeutics Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Distance Health Technologies Market