
 Digital Health Market | 2026-2036
Digital Health Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Health Market Intelligence
MedTech manufacturing corridors in Ireland is broadening the European supply base for connected diagnostic hardware. Koninklijke Philips NV leverages its imaging heritage to dominate hospital-grade remote monitoring systems. Medtronic Plc anchors its position through deep vertical integration into sensor fabrication and algorithm development. Teladoc Health, Inc. competes on virtual-first care delivery models that bypass traditional facility dependencies.
Digital health encompasses software-enabled medical interventions, biometric sensors, and data analytics platforms that collect, transmit, and process physiological information for clinical decision-making or consumer wellness management. These systems typically integrate FDA-cleared algorithms, cloud-native architectures, and interoperable data standards to enable continuous care outside conventional facilities. Telemedicine and wearable devices command the largest revenue pools, with AI-enabled applications representing the fastest-expanding margin segment as diagnostic accuracy thresholds improve. EHR integration remains structurally mature, while mHealth consumer applications face margin compression from platform commoditization.
FDA digital health pre-certification programs and CMS remote therapeutic monitoring reimbursement codes are tightening quality benchmarks and expanding addressable demand for validated solutions. The EU AI Act and MDR cybersecurity requirements are adding compliance layers for cross-border platform deployment. Stakeholders must monitor evolving payer evidence requirements and algorithm bias audit standards to sustain market access across jurisdictions.
Market Dynamics
FDA pre-certification pathways and CMS reimbursement expansion for remote therapeutic monitoring are compressing product development cycles while simultaneously raising validation thresholds for algorithmic clinical tools.
Growth Catalysts
- CMS Remote Therapeutic Monitoring Codes:Reimbursement parity for physiologic data collection outside hospital walls unlocks budget allocation for health system IT departments.
- Rural hospital network consolidation:Telemedicine platforms capture volume from facility closures in the United States, creating captive demand for virtual-first infrastructure.
- Continuous glucose monitoring:Sensor miniaturization and factory calibration eliminate fingerstick requirements, expanding the addressable population for diabetes management.
Market Restraints
- EU MDR cybersecurity annexes:Technical documentation requirements for connected devices extend approval timelines by 12-18 months for cross-border deployment.
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud dominate health data hosting, creating single-point-of-failure exposure for platform operators.
- Algorithm bias audit mandates:New York City Local Law 144 and emerging state frameworks impose compliance costs on AI-enabled diagnostic tools.
Strategic Opportunities
- Chronic disease management in India:CDSCO fast-track pathways for Software as Medical Device create first-mover advantage for cardiovascular risk algorithms.
- Interoperability mandates:ONC 21st Century Cures Act information blocking rules compel EHR vendors to open APIs, reducing integration friction for point solutions.
- Wearable-implant convergence:Combination products that merge consumer biometric sensors with therapeutic delivery systems open neurology and pain management categories.
Industry Challenges
- Clinical validation workforce scarcity:Biostatisticians with FDA submission experience command premium compensation, constraining startup hiring pipelines.
- Legacy EHR integration complexity:Epic and Cerner proprietary data formats require custom middleware development, inflating implementation costs for third-party applications.
- Multi-jurisdiction quality management:Simultaneous ISO 13485, FDA QSR, and EU MDR compliance demands redundant documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Health Market |
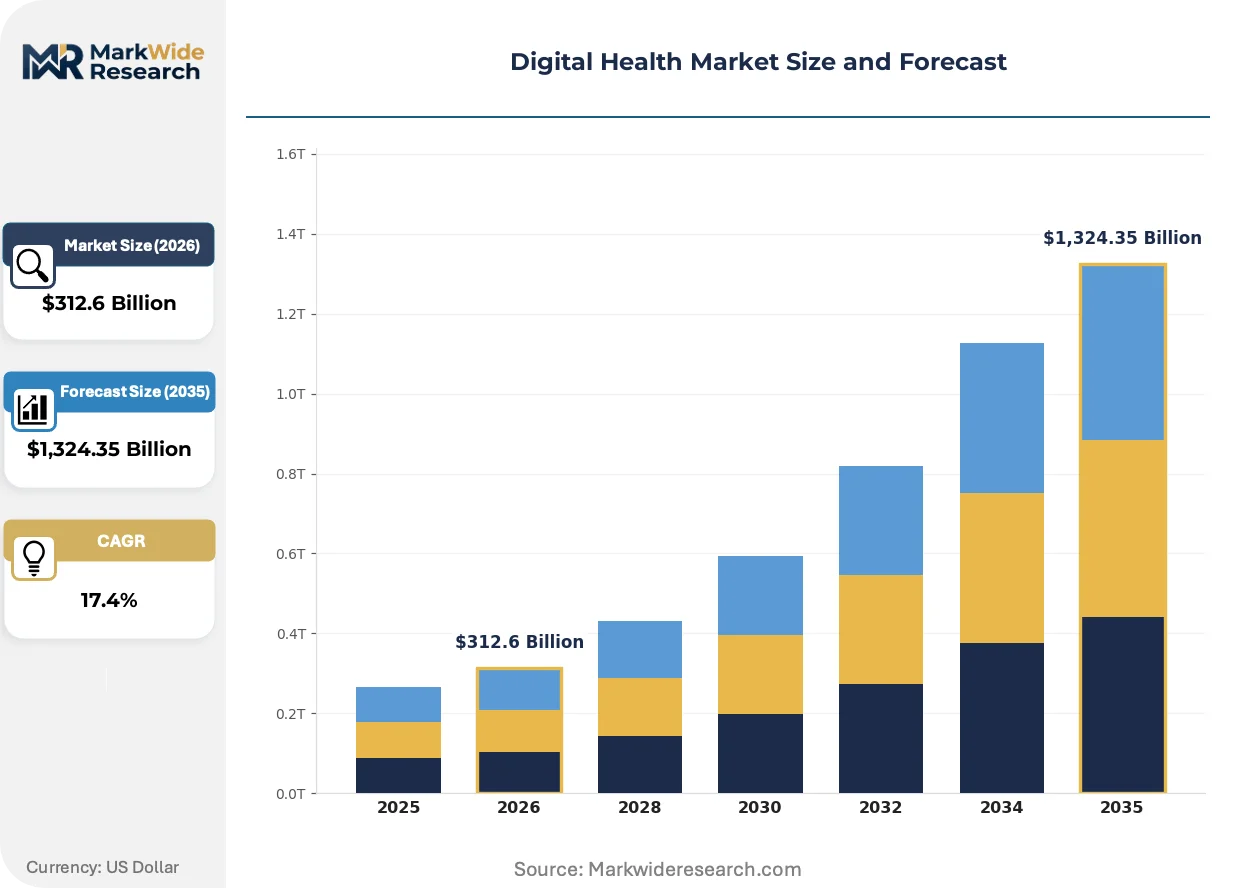
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $1,324.35 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telemedicine, mHealth, EHR, Wearable Devices End User: Hospitals, Clinics, Pharmaceuticals, Consumers Technology: AI, IoT, Blockchain, Cloud Computing Application: Chronic Disease Management, Wellness Monitoring, Patient Engagement, Remote Diagnostics |
| Companies Covered | Koninklijke Philips NV, Medtronic Plc, GE HealthCare Technologies Inc, Abbott Laboratories, OMRON Corp, Johnson & Johnson, Siemens Healthineers AG, Teladoc Health, Inc., Apple Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Health Market Strategic Shifts & Innovations
Algorithmic diagnostic tools are migrating from decision-support to autonomous screening, while hardware form factors shrink toward invisible physiological monitoring.
Multimodal AI architectures that fuse voice biomarkers, facial analysis, and natural language processing are integrating into mental health triage workflows. Large health systems in California and Texas deploy these tools for emergency department intake. The technology is integrating depression and anxiety screening into primary care encounters without clinician time expansion.
The EU AI Act risk-classification framework places most diagnostic algorithms in the high-risk category, triggering conformity assessment requirements that mirror medical device pathways. Manufacturers must maintain post-market monitoring systems and algorithm change control protocols. European hospital procurement committees now require CE marking under the AI Act before contract execution.
Employer-sponsored virtual care contracts are displacing traditional occupational health clinic relationships, with self-insured corporations contracting directly with telemedicine platforms for primary and behavioral services. This channel bypasses payer intermediaries and captures utilization data for population health management. The shift is most visible among technology and financial services employers in the United States with concentrated workforces in urban corridors.
Digital Health Market Segmentation
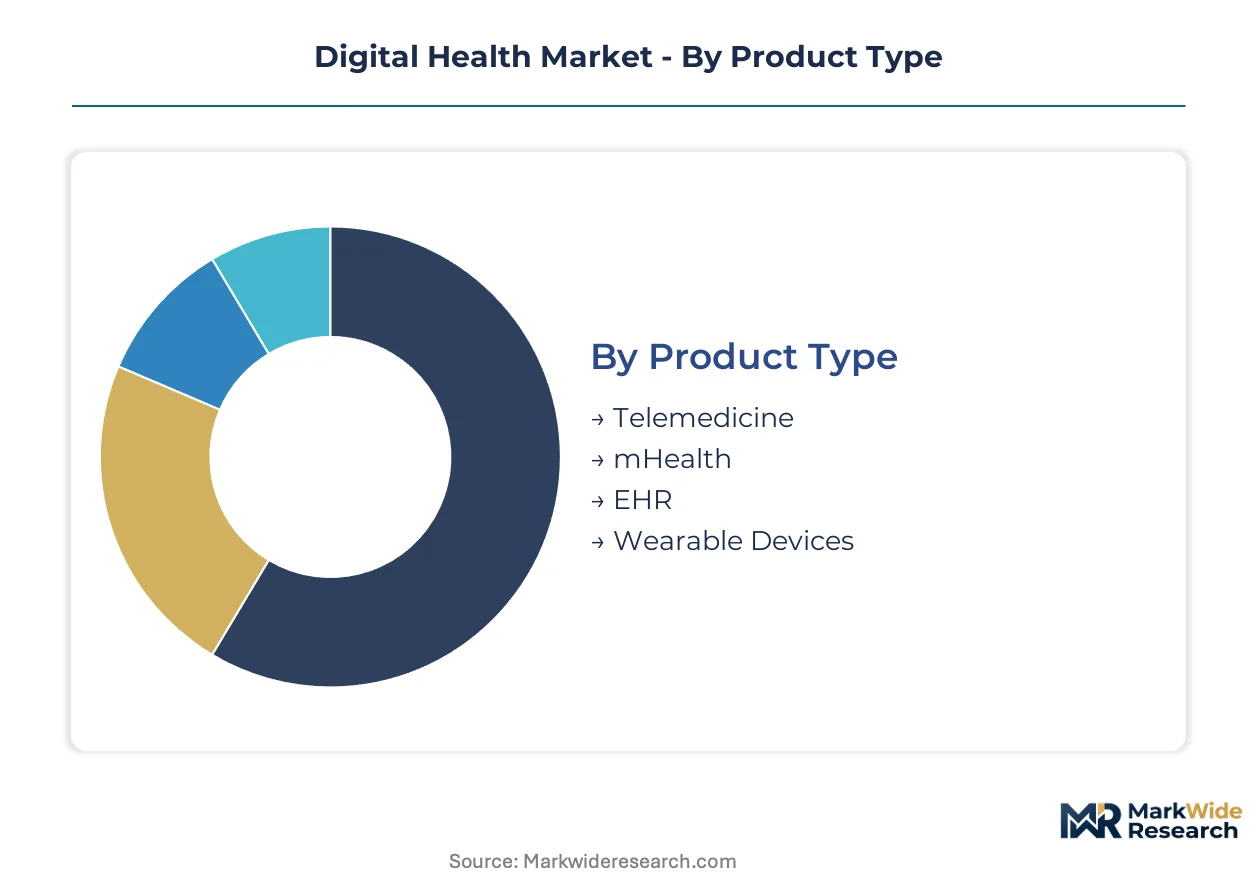
Segmentation in digital health reveals how technology maturity, reimbursement pathways, and clinical validation requirements create divergent margin structures across product categories. Understanding these divisions helps stakeholders allocate R&D resources toward segments with sustainable competitive moats.
Product Type:
Replacement cycles vary sharply across hardware and software categories, with sensor-based devices demanding 18-36 month refresh schedules versus decade-long EHR installations.
- Telemedicine:Real-time video consultation platforms with integrated scheduling, billing, and clinical documentation modules. United States health systems concentrate procurement here as rural hospital closures accelerate virtual-first infrastructure mandates. CMS reimbursement parity for remote visits sustains enterprise budget allocation.
- Wearable Devices:Biometric sensors capturing continuous physiologic data through wrist-worn, patch, or implantable form factors. Factory-calibrated glucose monitors and cardiac event recorders command premium pricing in diabetes and arrhythmia management. Sensor miniaturization is compressing power consumption requirements.
- mHealth:Consumer-facing mobile applications for wellness tracking, medication adherence, and symptom logging. Platform commoditization pressures margins as app store distribution lowers entry barriers.
- EHR:Electronic health record systems with clinical decision support, interoperability modules, and population health analytics. Epic and Cerner dominance creates vendor lock-in that slows third-party integration timelines.
Telemedicine sits at the top of the volume ranking, with Wearable Devices climbing the fastest.
End User:
Procurement authority and validation requirements shape how solution architectures adapt to distinct buyer workflows and risk tolerances.
- Hospitals:Integrated delivery networks with enterprise IT governance, cybersecurity mandates, and FDA-cleared algorithm requirements. Academic medical centers drive adoption of AI-enabled diagnostic tools for emergency department triage.
- Clinics:Ambulatory settings with lighter technical infrastructure and faster procurement cycles. Federally qualified health centers leverage HRSA funding for telemedicine expansion in underserved geographies.
- Pharmaceuticals:Drug developers deploying digital therapeutics and remote monitoring for clinical trial decentralization. Real-world evidence collection requirements reshape vendor selection criteria.
- Consumers:Direct-pay individuals purchasing wellness applications and fitness trackers outside reimbursement pathways. Employer-sponsored virtual care contracts increasingly intermediate this channel.
Hospitals capture the largest revenue share, though Pharmaceuticals is expanding most quickly as trial digitization accelerates.
Technology:
Patent thickets and talent scarcity concentrate competitive advantage in foundational technology layers.
- AI:Machine learning algorithms for diagnostic imaging, natural language processing, and predictive risk stratification. FDA pre-certification pathways and EU AI Act conformity assessments impose validation overhead that favors well-capitalized developers.
- IoT:Networked sensor ecosystems with edge computing capabilities and low-power wide-area connectivity. Continuous glucose monitors and cardiac implantables rely on proprietary radio protocols.
- Cloud Computing:Scalable infrastructure for health data storage, processing, and API-enabled interoperability. AWS, Azure, and Google Cloud concentration creates single-point-of-failure exposure.
- Blockchain:Distributed ledger architectures for credential verification, supply chain provenance, and patient consent management. Clinical utility remains nascent relative to pilot deployment volume.
AI dominates current investment flows, with IoT demonstrating the steepest expansion trajectory in connected diagnostic hardware.
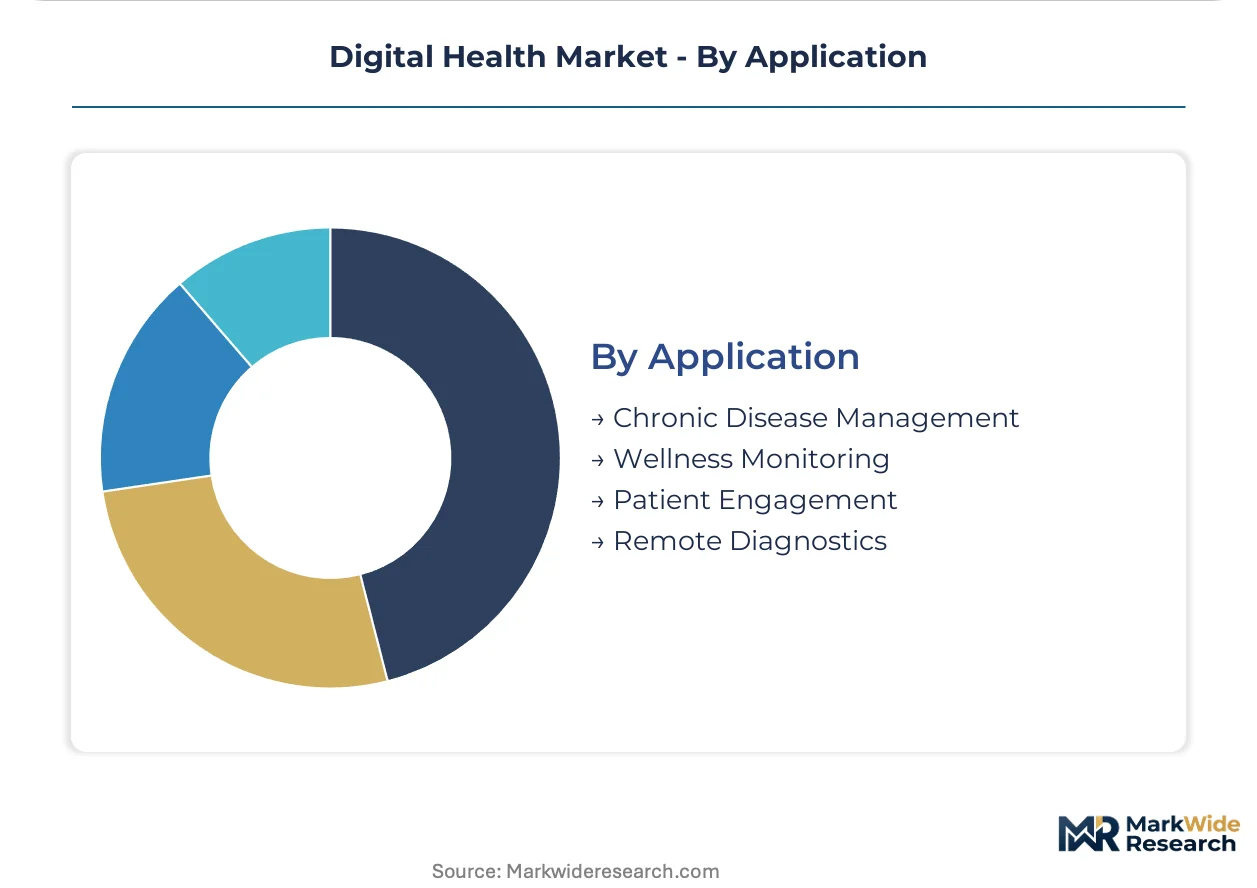
Application:
Clinical outcome measurability determines reimbursement eligibility and thus addressable market size.
- Chronic Disease Management:Longitudinal care programs for diabetes, heart failure, and COPD with remote physiologic monitoring and medication optimization. United States Medicare Advantage plans expand risk-based contracting for these services.
- Remote Diagnostics:Asynchronous and synchronous evaluation of acute symptoms outside traditional facilities. Teleradiology and teledermatology platforms capture volume from specialist shortages.
- Wellness Monitoring:Preventive health tracking for fitness, sleep, and nutrition without disease-specific clinical claims. Consumer subscription models face churn pressure.
- Patient Engagement:Portals, messaging platforms, and educational content designed to activate self-management behaviors. ONC information blocking rules mandate API accessibility.
Chronic Disease Management leads by revenue, while Remote Diagnostics is gaining share fastest on specialist access constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance arbitrage is redirecting digital health software development toward jurisdictions with streamlined medical device pathways, while hardware manufacturing clusters concentrate where sensor fabrication ecosystems already exist.
United States
Medicare Advantage risk-based contracting and CMS remote therapeutic monitoring reimbursement codes are accelerating health system procurement of virtual care infrastructure. FDA digital health pre-certification programs compress algorithm validation timelines for qualifying developers. The Boston-Cambridge corridor anchors clinical AI validation work, while Silicon Valley concentrates consumer-facing wellness platform engineering.
Germany
Sickness fund reimbursement for digital health applications (DiGA) creates predictable revenue streams for validated therapeutics. BfArM fast-track assessment pathways compress time-to-reimbursement for mental health and chronic disease modules. The Berlin-Brandenburg metro hosts startup density in prescription digital therapeutics, with Munich anchoring hospital-grade remote monitoring system integration.
China
NMPA regulatory reform for AI-enabled diagnostic software is expanding the addressable market for domestic algorithm developers. The Healthy China 2030 initiative channels public investment toward chronic disease management platforms. Shenzhen's hardware ecosystem supplies biometric sensor components, while Beijing concentrates clinical validation partnerships with tier-one hospitals.
India
CDSCO Software as Medical Device fast-track pathways attract cardiovascular and diabetes algorithm developers seeking earlier market entry. The National Digital Health Mission's health ID infrastructure reduces patient onboarding friction for remote monitoring platforms. Hyderabad and Bengaluru clusters concentrate engineering talent for telemedicine platform development, with Mumbai anchoring pharmaceutical trial digitization services.
United Kingdom
NICE evidence standards for digital therapeutics are tightening reimbursement eligibility criteria while validating outcome-based contracting models. NHS England's digital-first primary care mandates accelerate procurement of asynchronous consultation platforms. London's health tech corridor concentrates AI diagnostic validation partnerships with academic medical centers, while Manchester anchors wearable device integration pilots.
Digital Health Market Key Industry Players
United States producers anchor the software and platform tier; European and Asian specialists hold hardware and sensor manufacturing positions. Market structure concentrates around conglomerate health technology divisions with imaging heritage, diversified medtech groups with therapeutic delivery expertise, and pure-play virtual care operators. Three archetypes dominate: integrated diagnostic-imaging-platform hybrids, sensor-algorithm vertical specialists, and virtual-first care delivery networks. Competitive moves center on algorithm validation portfolio expansion and health system IT department direct contracting relationships.
Within the integrated diagnostic tier, Koninklijke Philips NV and Siemens Healthineers AG exemplify the imaging-to-remote-monitoring extension strategy. Medtronic Plc occupies a position among therapeutic device manufacturers deepening sensor and algorithm capabilities. Teladoc Health, Inc. anchors the virtual-first network archetype. These three represent distinct competitive vectors: hardware-originated platform expansion, therapeutic delivery integration, and facility-independent care model development.
| Leading Market Players |
|---|
| Koninklijke Philips NV |
| Medtronic Plc |
| GE HealthCare Technologies Inc |
| Abbott Laboratories |
| OMRON Corp |
| Johnson & Johnson |
| Siemens Healthineers AG |
| Teladoc Health, Inc. |
| Apple Inc |
| Others |
Cost & Logistics Intelligence
EU MDR cybersecurity annexes and FDA pre-certification programs gate qualified supply access for hospital-grade remote monitoring systems, with premium-tier pricing reserved for vendors bearing full ISO 13485 and FDA QSR documentation. Health system procurement committees in the United States and Germany demand these certifications as table stakes, compressing margins for underqualified entrants while sustaining price premiums for validated platforms.
Pricing Analysis
Direct-to-hospital contracting eliminates distributor markups for enterprise telemedicine platforms, though third-party implementation partners capture 15-25% service fees for EHR integration. Pricing stratifies across FDA-cleared diagnostic algorithms, CE-marked wellness devices, and unregulated consumer applications, with certification tier as the primary differentiation driver. Cost compression in mHealth consumer subscriptions intensifies as platform commoditization erodes recurring revenue. Federally qualified health centers exhibit highest price sensitivity, while self-insured employers in technology and financial services demonstrate lowest sensitivity for virtual-first care bundles.
Supply Chain Analysis
Biometric sensor fabrication rests on Taiwan and South Korea for MEMS foundry capacity, with China supplying discrete components and Ireland anchoring European final assembly for connected diagnostic hardware. Cloud infrastructure draws from AWS, Azure, and Google Cloud data centers concentrated in the United States and Western Europe, creating single-source vulnerability for platform operators. Single-point-of-failure exposure in hyperscaler concentration represents the dominant structural risk. Distribution runs through health system IT procurement committees and GPO contracts for hospital networks, with direct employer contracting emerging as an alternative channel for virtual care.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital health software development arbitrages toward India and Germany, where CDSCO fast-track pathways and BfArM DiGA assessment compress validation costs versus FDA pre-certification timelines in the United States.
For Market Incumbents: Lock in hospital system direct contracting relationships before ONC interoperability mandates fully commoditize EHR integration. Defend algorithm validation portfolios against emerging AI-native entrants by deepening backward integration into sensor fabrication. Vertical control over MEMS supply insulates against Taiwan foundry capacity constraints. For New Entrants and Emerging Players: Rural hospital networks in the United States present the most penetrable buyer archetype, as facility closures create captive demand for virtual-first infrastructure. Federally qualified health centers offer a secondary white-space target through HRSA-funded telemedicine expansion. A reimbursement-first go-to-market angle, leading with CMS remote therapeutic monitoring codes, accelerates health system budget access. For Investors and Strategic Acquirers: Roll-up economics work for point-solution AI diagnostic developers because FDA pre-certification overhead and clinical validation workforce scarcity prevent organic scaling. Five-to-ten year viability hinges on algorithm change control protocols that satisfy EU AI Act post-market monitoring. The signal to watch is NICE evidence standard tightening in the United Kingdom, which will filter acquisition targets toward outcome-based contracting capability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Compresses algorithm validation timelines for qualifying developers against standard 510(k) routes. |
| CE Marking Under EU AI Act | Unlocks European hospital procurement committee contracts requiring high-risk conformity assessment. |
| Hospital System Partnership | Captures enterprise IT budget allocation for virtual care infrastructure in integrated delivery networks. |
| Software Companion Development | Enables therapeutic device manufacturers to capture recurring revenue from algorithm updates. |
| Reimbursement Strategy | Aligns product architecture with CMS remote therapeutic monitoring codes and Medicare Advantage risk contracting. |
Research Approach
Multiple input streams — hospital procurement database analysis, GPO contract reviews, and CMS reimbursement code tracking — were reconciled against primary interviews with biomedical engineers, health system IT directors, and FDA regulatory consultants. Secondary validation drew from FDA 510(k) filings, BfArM DiGA registry entries, and hospital capital expenditure disclosures. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across telemedicine, wearable device, and AI diagnostic categories.
Data-stream reconciliation fed analytical frameworks spanning product type, end user, technology layer, and application across the projection horizon. Deployment model, organization size, and regional regulatory cluster dimensions segmented the forecast. CAGRs derived from logistic adoption curves and reimbursement pathway maturation. Algorithm validation pipeline depth and health system IT budget cycles served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; FDA-cleared diagnostic algorithms and CMS-reimbursed remote monitoring carry tighter precision than unregulated wellness applications. Forecasts reflect assumptions on reimbursement code expansion and regulatory pathway streamlining. Algorithm bias audit mandates, EU MDR cybersecurity timeline extensions, and cloud infrastructure concentration represent specific risk factors that could revise projections. A small set of named triggers — NICE evidence standard revisions, CDSCO pathway modifications, and ONC enforcement patterns — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Digital Therapeutics and Wellness Market
Digital Health Solutions
Artificial Intelligence in Precision Medicine Market
Digital Health Solutions
Global Preventive Healthcare Technologies and Services Market
Digital Health Solutions
United Kingdom Digital Health Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Smart Cards in Healthcare Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
Digital Brain Health Market