
 Veterinary Glucometers Market | 2026-2036
Veterinary Glucometers Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Glucometers Market Analytics
Companion animal owners are reorganizing procurement patterns for at-home glucose monitoring, shifting volume from clinical settings toward retail and direct channels. Zoetis leverages its animal health infrastructure to sustain channel breadth across veterinary and consumer segments. Abbott competes through human-diagnostic technology extension into veterinary applications. IDEXX Laboratories anchors its position with clinic-integrated diagnostic platforms that bundle glucose data into broader patient management workflows.
Veterinary glucometers are electrochemical or optical devices calibrated for non-human blood matrices, typically measuring glucose in capillary samples across species-specific hematocrit ranges and temperature conditions. Portable glucometers dominate unit volume due to low cost and field-deployment convenience, while continuous glucose monitors capture expanding margin pools from diabetic pet management protocols. Handheld glucometers retain stronghold positions in equine and large-animal practice where barn-side immediacy outweighs connectivity features.
FDA Center for Veterinary Medicine oversees device clearance, while ISO 15197 performance standards shape accuracy benchmarks that manufacturers must meet for clinical credibility. The EU MDR and CE marking framework govern European market access, with EMA guidelines on veterinary medical devices creating additional conformity requirements. Stakeholders must monitor regulatory divergence between human and veterinary device pathways as jurisdictions tighten species-specific validation protocols.
Market Dynamics
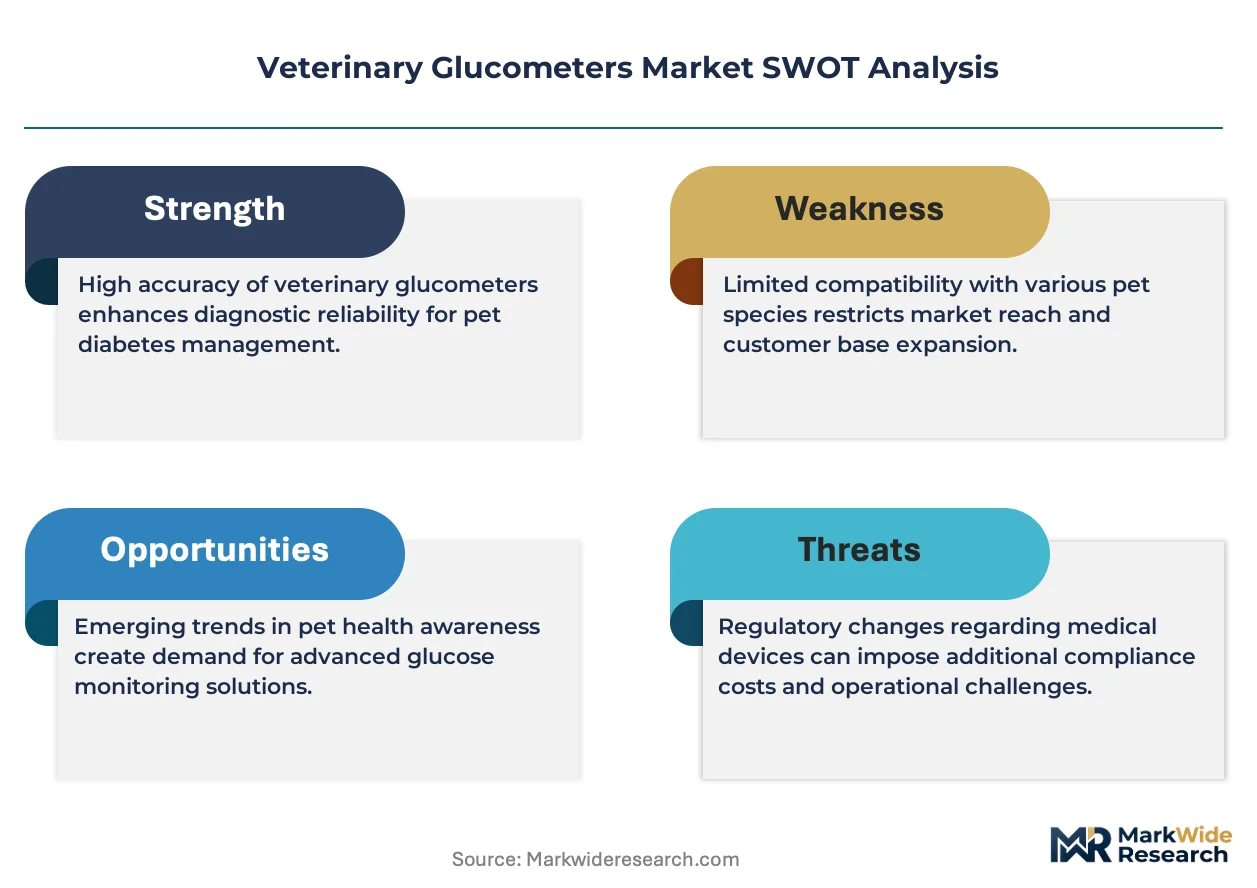
Companion animal diabetes incidence is climbing across developed veterinary networks, pulling glucose monitoring from episodic clinic visits toward continuous home-based management protocols that demand simpler calibration, species-specific algorithms, and direct-to-consumer distribution infrastructure.
Growth Catalysts
- ISO 15197 Performance Standards:International accuracy benchmarks for point-of-care glucose testing are elevating clinical credibility for veterinary-specific devices, accelerating adoption in metropolitan veterinary networks across Germany, the United Kingdom, and Japan.
- Home Monitoring Infrastructure:Pet owners in North American metropolitan areas are building at-home diagnostic capabilities that parallel human diabetes management, creating pull-through demand for portable glucometers with simplified user interfaces.
- Equine Metabolic Syndrome Protocols:Large-animal veterinary practices are institutionalizing glucose surveillance for insulin-dysregulated horses, expanding addressable volume beyond traditional small-animal diabetes cases.
Market Restraints
- Species-Specific Calibration Costs:Validation across canine, feline, and equine hematocrit ranges demands redundant clinical trials, inflating development timelines for multi-species device platforms.
- Human Diagnostic Substitution:Off-label use of human glucometers in veterinary settings persists in price-sensitive clinics, compressing margins for purpose-built veterinary devices and eroding manufacturer incentive to invest in species-specific form factors.
- Reimbursement Fragmentation:Pet insurance policies vary dramatically in glucose monitoring coverage across national veterinary markets, creating demand uncertainty that constrains distributor inventory commitments.
Strategic Opportunities
- Continuous Glucose Monitor Convergence:Integration of subcutaneous sensor technology with smartphone telemetry is opening subscription-based revenue models for diabetic pet management protocols in Australian and Canadian metropolitan markets.
- Veterinary Telehealth Integration:Remote consultation platforms are creating demand for cloud-connected glucometers that feed real-time glucose data into asynchronous veterinary workflows, particularly in United Kingdom urban networks.
- EMA Veterinary Medical Device Pathways:Streamlined CE marking procedures for species-specific glucose monitors are reducing European market entry friction relative to human-device reclassification requirements.
Industry Challenges
- Cross-Species Algorithm Development:Engineering teams face compression in recruiting veterinary clinical pathologists capable of validating glucose conversion factors across divergent mammalian blood matrices.
- Legacy Practice Management Integration:Clinic-software vendors maintain proprietary data architectures that resist standardized glucose data import, forcing device manufacturers to maintain multiple API configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Glucometers Market |
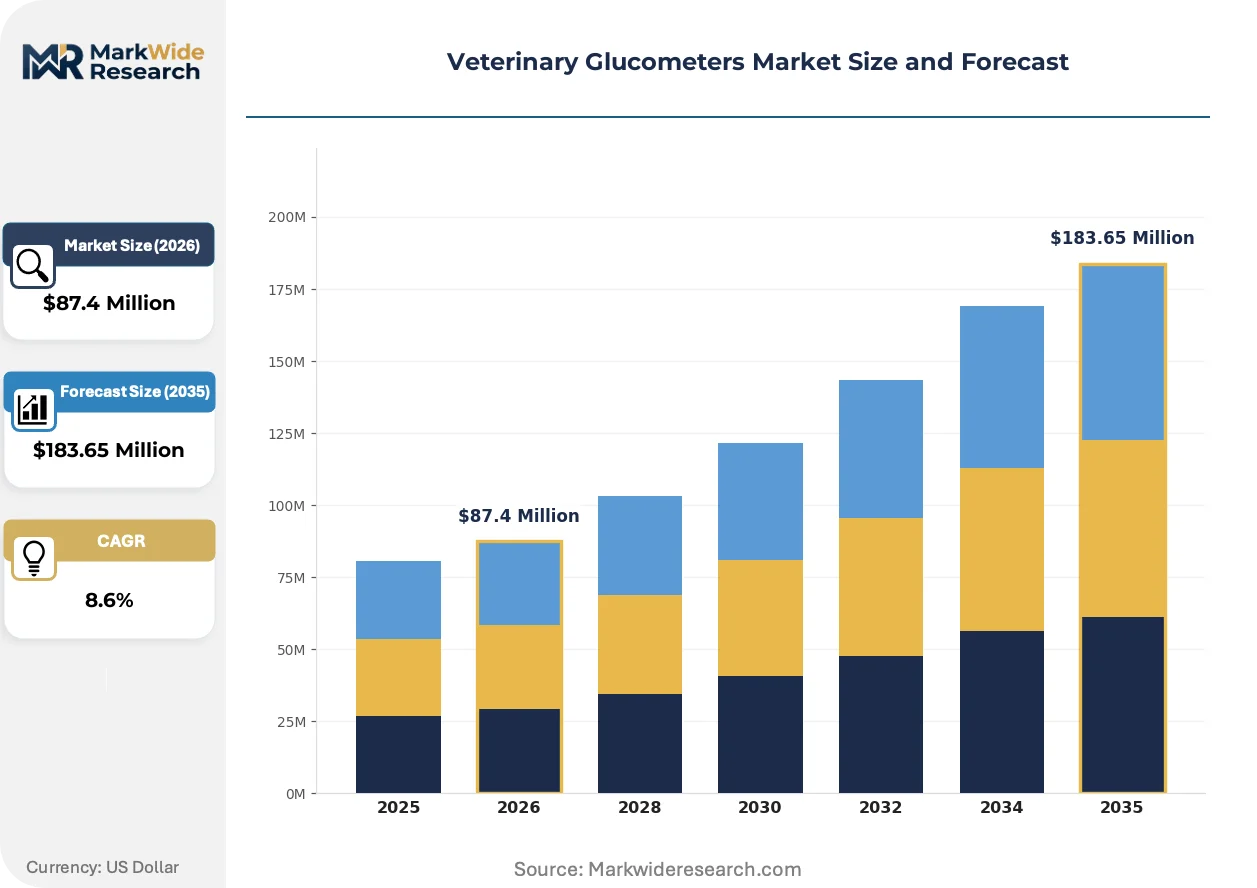
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $183.65 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Glucometers, Continuous Glucose Monitors, Handheld Glucometers, Desktop Glucometers Animal Type: Dogs, Cats, Horses, Exotic Pets End User: Veterinary Clinics, Animal Hospitals, Mobile Veterinary Services, Research Laboratories Technology: Electrochemical Sensors, Optical Sensors, Reflectance Meters, Biosensors |
| Companies Covered | Nova Biomedical, Zoetis, Abbott, IDEXX Laboratories, TaiDoc Technology Corporation, BioNote Inc, Woodley Equipment Company Ltd, i-SENS, Inc., UltiMed, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Glucometers Market Evolving Landscape
Silicon photonics and electrochemical miniaturization are converging to shrink sensor form factors while expanding species compatibility, enabling device architectures that serve both clinical precision requirements and consumer convenience expectations.
Optical glucose sensing is displacing traditional electrochemical strip-based measurement in premium veterinary segments. Specialty and emergency clinics in the United States are adopting non-invasive transdermal monitors for anesthetic glucose surveillance during prolonged surgical procedures. This displacement is compressing the addressable market for conventional handheld glucometers in high-acuity settings while opening margin pools in perioperative monitoring.
EU MDR recertification deadlines are forcing veterinary device manufacturers to resubmit technical documentation under stricter biocompatibility and clinical evidence requirements. The regulatory burden is falling most heavily on small-device portfolios that previously relied on equivalence arguments to human diagnostic predicates. German and French notified bodies are extending review timelines, pushing market access delays into 2025-2026 for several legacy product lines.
Subscription-based consumable replenishment is capturing diabetic pet owner loyalty through automated strip and sensor delivery. Direct-to-consumer channels in United States metropolitan markets are disintermediating traditional veterinary distributor relationships, with pet owners initiating purchases through manufacturer portals rather than clinic recommendations. This behavioral pivot is most pronounced in households managing multiple diabetic animals where consumption volume justifies bulk procurement economics.
Veterinary Glucometers Market Segmentation
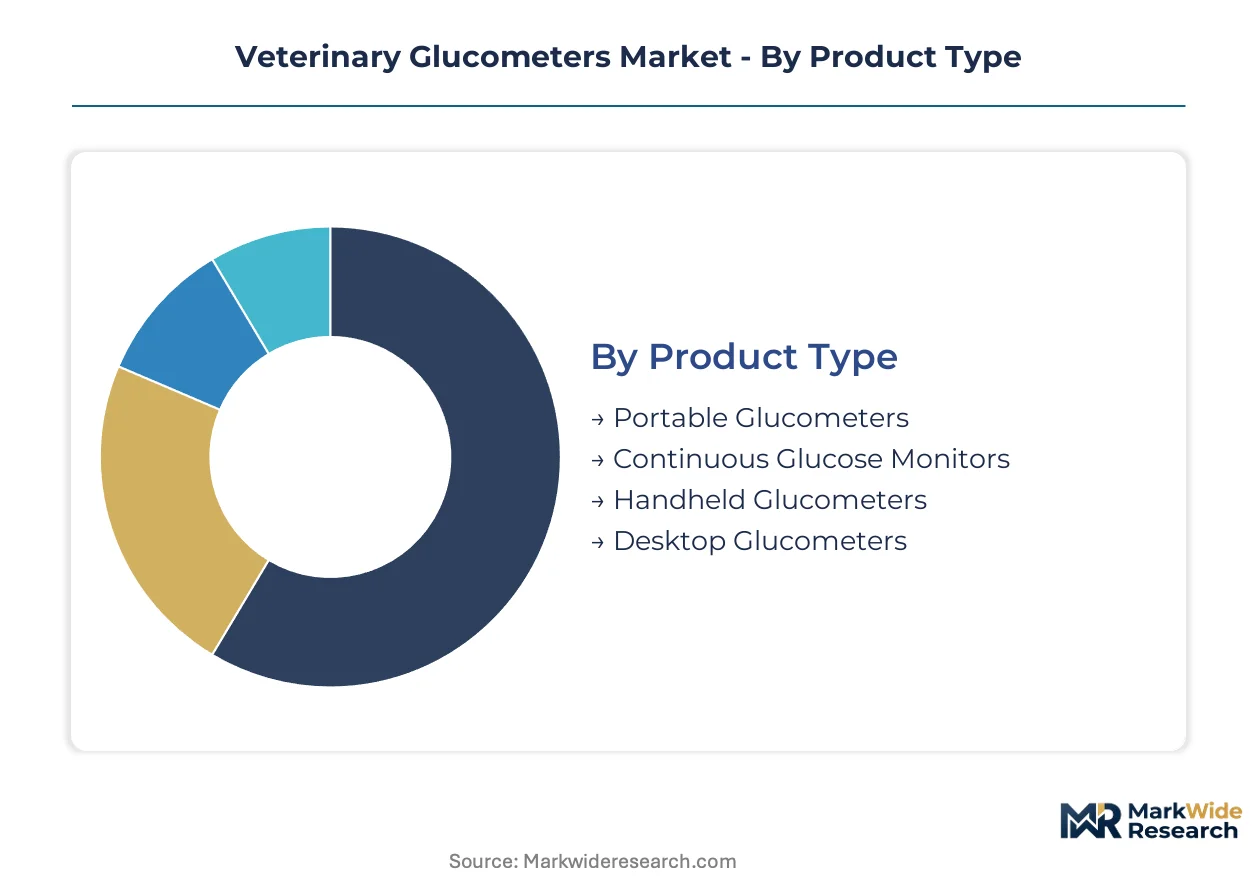
Veterinary glucometer manufacturers configure product portfolios around species-specific hematocrit ranges and deployment contexts. Segment boundaries reflect divergent calibration requirements between companion animal home monitoring and large-animal field diagnostics.
Product Type:
Domestic demand concentrates in portable formats for at-home pet management, while export volumes favor clinic-integrated systems with multi-species calibration capabilities.
- Portable Glucometers:Battery-operated electrochemical devices with single-species calibration presets dominate North American retail channels. Metropolitan pet owners in the United States and Canada purchase these units for twice-daily glucose curves in diabetic cats and dogs, pulling volume from clinic-based testing.
- Continuous Glucose Monitors:Subcutaneous sensor arrays with smartphone telemetry are capturing margin pools in Australian and Canadian metropolitan markets. Subscription-based consumable replenishment models are emerging for multi-pet households managing chronic diabetes protocols.
- Handheld Glucometers:Ruggedized units with expanded temperature tolerances serve equine practitioners in barn-side deployments.
- Desktop Glucometers:Laboratory-grade precision instruments with automated sample handling anchor hospital laboratory workflows.
Portable glucometers command the established base. The steepest expansion runs through continuous glucose monitors.
Animal Type:
Calibration complexity escalates with body mass and hematocrit divergence, driving specialized algorithm development for each species cluster.
- Dogs:Canine-specific glucose conversion factors require validation across breed-specific hematocrit ranges from greyhounds to toy breeds. German and Japanese veterinary networks are standardizing home monitoring protocols for diabetic dog populations.
- Cats:Stress-induced hyperglycemia in feline patients demands calibration stability across capillary sampling conditions. United Kingdom specialty clinics are adopting non-invasive transdermal alternatives for fractile patients resistant to ear-prick sampling.
- Horses:Insulin dysregulation surveillance in equine metabolic syndrome protocols expands addressable volume beyond traditional small-animal cases.
- Exotic Pets:Avian and reptilian glucose monitoring requires species-specific strip chemistries with extended measurement ranges.
Canine applications command the established base. Feline monitoring is climbing the fastest as stress-free sampling protocols gain veterinary endorsement.
End User:
Procurement authority is fragmenting between clinic-directed recommendations and direct-to-consumer purchasing decisions.
- Veterinary Clinics:Point-of-care integration with practice management software drives purchasing for metropolitan networks in France and the United States. Bundled diagnostic platforms that incorporate glucose data into patient records are displacing standalone devices.
- Animal Hospitals:Emergency and specialty centers require multi-parameter monitors with anesthetic glucose surveillance capabilities for prolonged surgical procedures.
- Mobile Veterinary Services:Field-deployable units with extended battery life serve rural and ambulatory practice models.
- Research Laboratories:GLP-compliant validation and data integrity features support pharmaceutical toxicology studies.
Veterinary clinics command the established base. Home-based purchasing through manufacturer portals is gaining share fastest.
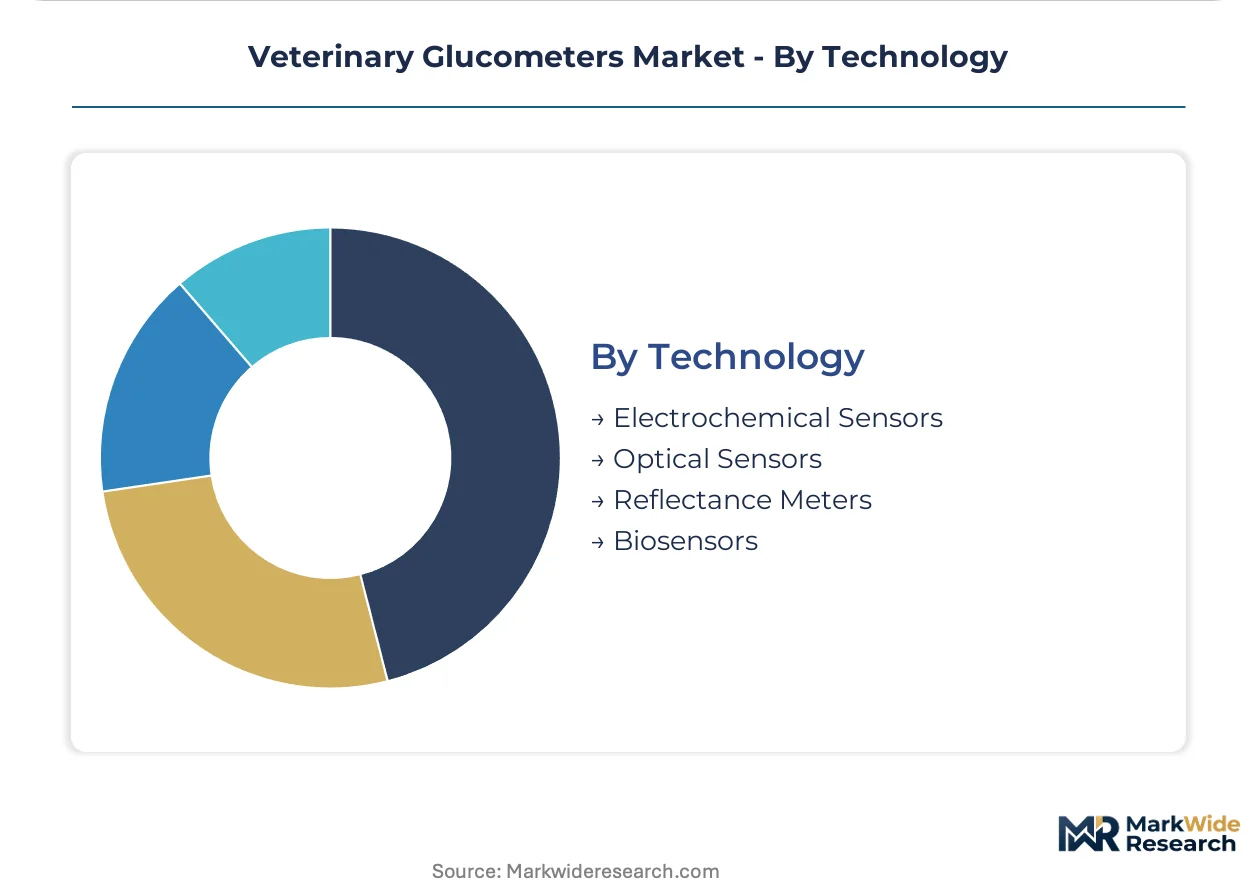
Technology:
Sensor architecture selection trades accuracy against calibration burden and consumable cost structure.
- Electrochemical Sensors:Amperometric glucose oxidase strips dominate unit economics across price-sensitive clinic segments. German and United States manufacturers are refining species-specific enzyme formulations to reduce hematocrit interference.
- Optical Sensors:Silicon photonics and near-infrared transdermal detection are displacing strip-based methods in premium perioperative monitoring. Specialty clinics in the United States are adopting these for anesthetic glucose surveillance during prolonged procedures.
- Reflectance Meters:Colorimetric strip reading technology persists in legacy installed bases and developing market price tiers.
- Biosensors:Enzyme-immobilized continuous monitoring platforms are emerging for implantable long-term glucose tracking.
Electrochemical sensors command the established base. Optical sensing platforms are expanding most quickly in high-acuity settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters in the United States and Germany concentrate supply for veterinary glucose monitoring platforms. Metropolitan veterinary networks in North America and Western Europe pull the highest per-capita consumption volumes. Regulatory divergence between FDA and EMA pathways shapes divergent market entry strategies across these jurisdictions.
United States
Companion animal diabetes protocols are expanding home-monitoring adoption among metropolitan pet owners in California and New York. FDA Center for Veterinary Medicine clearance pathways are streamlining product entry for species-specific glucose monitors. Boston-area veterinary networks are piloting continuous glucose monitor integration with telehealth platforms.
Germany
Equine metabolic syndrome surveillance is institutionalizing glucose monitoring in Baden-Württemberg veterinary practices. EU MDR recertification deadlines are extending review timelines for legacy device portfolios through 2025. Munich and Stuttgart metropolitan clinics are standardizing ISO 15197-compliant point-of-care diagnostics.
United Kingdom
Feline stress-free sampling protocols are accelerating non-invasive transdermal monitor adoption in London specialty clinics. EMA veterinary medical device guidelines are creating additional conformity requirements for glucose monitor market access. Southeast England veterinary networks are bundling glucose data into cloud-connected patient management workflows.
Japan
Canine breed-specific calibration demands are driving algorithm development for hematocrit ranges from greyhounds to toy breeds. PMDA oversight of veterinary medical devices is aligning with international ISO accuracy benchmarks. Tokyo and Osaka metropolitan areas are expanding home-based diabetic pet management protocols.
Australia
Subscription-based consumable replenishment models are capturing diabetic pet owner loyalty in Sydney and Melbourne. TGA veterinary device regulations are maintaining alignment with ISO 15197 performance standards. Australian metropolitan markets are pioneering smartphone-telemetry integration for subcutaneous glucose sensors.
Veterinary Glucometers Market Competitive Landscape
Concentration sits with diversified animal health conglomerates that leverage cross-species diagnostic platforms. The competitive structure spans three tiers: vertically integrated life science majors, specialized veterinary diagnostics firms, and regional contract manufacturers. Strategic moves center on technology licensing for species-specific algorithm development and backward integration into sensor component production.
Among the diversified animal health majors, Zoetis and Abbott exemplify divergent market entry strategies—Zoetis through dedicated veterinary infrastructure and Abbott through human-diagnostic technology extension. IDEXX Laboratories anchors the clinic-integrated diagnostics tier with bundled patient management platforms. These three firms represent the dominant archetypes shaping competitive positioning across North American and European metropolitan veterinary networks.
| Leading Market Players |
|---|
| Nova Biomedical |
| Zoetis |
| Abbott |
| IDEXX Laboratories |
| TaiDoc Technology Corporation |
| BioNote Inc |
| Woodley Equipment Company Ltd |
| i-SENS, Inc. |
| UltiMed, Inc. |
| Others |
Value Network & Pricing Analysis
Component-scale economies in electrochemical sensor manufacturing concentrate production among German and United States-based device makers, compressing unit costs for glucose oxidase strips while elevating price floors for species-specific calibration firmware. This scale dynamic simultaneously locks in supply relationships with enzyme suppliers and creates tiered procurement power across veterinary clinic networks and direct-to-consumer channels.
Pricing Analysis
Volume-discount tiering structures separate clinic-procurement contracts from direct-to-consumer retail pricing, with three-tier pricing stratification across premium continuous monitors, standard portable devices, and economy strip-based systems. Price differentiation centers on ISO 15197 certification grade and bundled software integration depth. Pricing pressure stems from off-label human glucometer substitution in price-sensitive rural clinics. Home-monitoring pet owners exhibit lowest price sensitivity, while mobile veterinary services face acute margin compression.
Supply Chain Analysis
Silicon photonics foundry capacity in Taiwan and Germany underwrites sensor miniaturization for optical glucose platforms, creating single-source vulnerability for transdermal monitor producers. Electrochemical strip manufacturing draws from glucose oxidase enzyme suppliers in Denmark and Japan, with polymer substrate sourcing concentrated in United States specialty chemical producers. Tariff exposure on Chinese-sourced electronic components elevates landed costs for portable device assemblers. Distribution runs through veterinary distributor networks in metropolitan North American markets and direct-to-consumer portals for subscription-based sensor replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion animal diabetes management is entering a cyclical upswing as post-pandemic pet ownership retention sustains chronic disease caseloads and home-monitoring infrastructure investments mature.
For Market Incumbents: Compound defensive moats through backward integration into species-specific algorithm development and captive sensor component production. Lock in clinic-procurement relationships via practice management software API standardization before cloud-native competitors disintermediate veterinary distributor channels. Human-diagnostic technology extension from Abbott and similar players threatens margin compression in portable device tiers. For New Entrants and Emerging Players: Lead with feline stress-free sampling protocols as the most penetrable white-space segment, where non-invasive transdermal alternatives command premium positioning and veterinary endorsement gaps persist. Target Australian and Canadian metropolitan markets for subscription-based continuous glucose monitor launches, leveraging smartphone telemetry integration as the primary go-to-market angle. Equine metabolic syndrome surveillance represents underdeveloped large-animal volume. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive enzyme formulation capabilities and multi-species calibration IP libraries. Five-to-ten year viability hinges on regulatory navigation capacity across FDA Center for Veterinary Medicine and EU MDR recertification pathways. Watch EMA veterinary medical device guideline harmonization progress as the signal for European market entry friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Species-Specific Algorithm Development | Proprietary calibration IP for canine, feline, and equine hematocrit ranges differentiates against human-diagnostic substitutes. |
| Cloud-Connected Platform Integration | Telehealth workflow compatibility with IDEXX and Zoetis practice management systems secures clinic channel access. |
| Subscription Consumable Replenishment | Automated strip and sensor delivery captures multi-pet household loyalty in United States metropolitan direct-to-consumer channels. |
| Optical Sensor Miniaturization | Silicon photonics convergence enables non-invasive perioperative monitoring adoption in specialty and emergency clinics. |
| EMA Regulatory Pathway Navigation | Streamlined CE marking for veterinary-specific devices reduces European market entry friction relative to human-device reclassification. |
Research Methodology
Initial hypotheses were tested against primary input from veterinary practice owners, point-of-care diagnostics product managers, biomedical engineers at device manufacturers, and pet insurance underwriting leads, then refined against secondary validation from FDA 510(k) veterinary device filings, EU MDR technical documentation databases, ISO 15197 performance standard audits, and veterinary clinic procurement records. Bottom-up segment sizing triangulated with top-down market reconstruction across product type, animal species, and end-user channel dimensions.
Variance-decomposition analysis isolated volume and value drivers across portable glucometers, continuous glucose monitors, handheld field units, and desktop laboratory systems, with species-specific calibration complexity and home-monitoring adoption intensity as cross-cutting forecast inputs. CAGRs were derived from logistic diffusion modeling of technology substitution patterns and elasticity-adjusted price trajectory assumptions across the projection horizon.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine clearance pathways and EU MDR enforcement timelines; material policy shifts in either jurisdiction would require re-modeling. Practitioners should keep alternative scenarios live as pet insurance reimbursement standardization and telehealth platform integration depth evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Biosurgery Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Passive Prosthetics Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Global Nerve Monitoring System Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Vortex Mixer Market
Medical Devices
Prefilled Glass Syringes Market
Medical Devices
Contact Thermometer Market
Medical Devices
Portable Medical Devices Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market