
 Digital Therapeutics Market | 2026-2036
Digital Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Therapeutics Market Intelligence
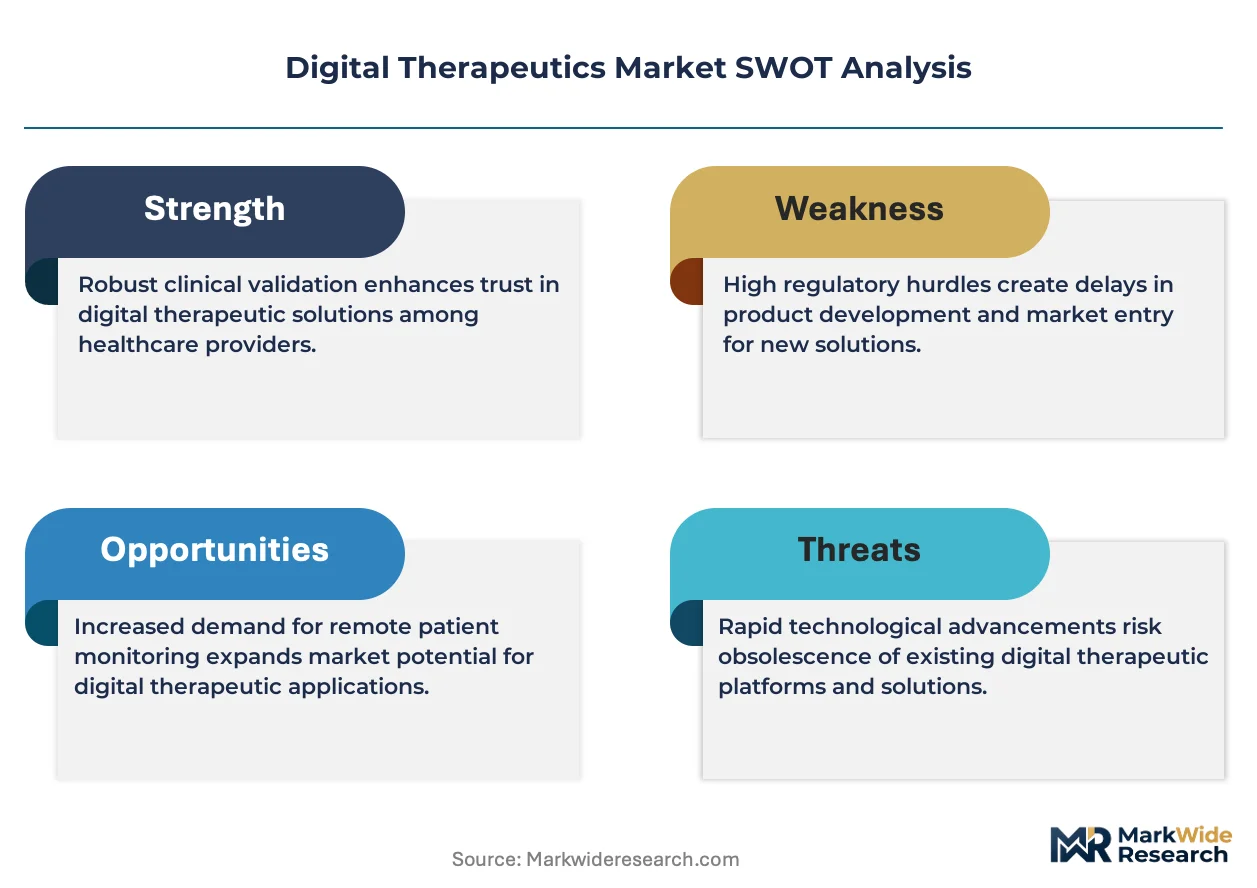
Platform licensing revenue is reshaping competitive economics in digital therapeutics, pulling margin pools away from per-prescription fees toward recurring enterprise contracts. Pear Therapeutics leverages its FDA-cleared prescription digital therapeutic portfolio to anchor payer relationships. Omada Health sustains growth through employer-sponsored chronic disease management programs. Teladoc Health competes by integrating digital therapeutics into its broader virtual care infrastructure.
Digital therapeutics are evidence-based software interventions delivered to patients to prevent, manage, or treat medical conditions, typically requiring clinical trials demonstrating efficacy comparable to pharmaceutical or device standards. Their primary commercial purpose centers on reducing total cost of care for chronic conditions while enabling remote patient monitoring and behavioral modification at scale. Management Platforms currently occupy the largest margin pool by consolidating multiple therapy areas into single-payer contracts, while Mental Health applications represent the fastest-expanding therapy area as workforce behavioral health benefits expand. Mobile Applications dominate delivery mode volume, though Virtual Reality segments show concentrated R&D investment for neurological rehabilitation.
The FDA's digital health pre-certification program and the EU MDR framework collectively shape product development timelines, clinical evidence requirements, and market access pathways for software-based interventions. HIPAA compliance obligations and state-level telehealth prescribing rules further fragment go-to-market complexity for multi-state deployments. Stakeholders must monitor evolving payer coverage determinations and prescription digital therapeutic billing codes as these decisions will separate reimbursable platforms from consumer wellness applications.
Market Dynamics
Platform licensing economics are compressing per-prescription revenue models into recurring enterprise contracts, forcing developers to restructure commercial relationships around multi-therapy payer deals rather than single-product prescriptions.
Growth Catalysts
- FDA Prescription Drug Use Fee Act:The framework establishes reimbursement pathways that accelerate provider adoption of software-based interventions by creating billing code clarity for integrated delivery networks.
- Commercial payer coverage expansion:Health insurers embed digital therapeutics into benefit plans as a cost-containment strategy for chronic disease populations, pulling volume through prior authorization reform.
- Mobile application infrastructure:Smartphone penetration and cellular bandwidth expansion enable scalable delivery of behavioral modification protocols without hardware dependencies.
Market Restraints
- Clinical evidence generation costs:Randomized controlled trial requirements for FDA clearance impose capital intensity comparable to pharmaceutical development timelines.
- State-level telehealth prescribing fragmentation:HIPAA compliance obligations and varying state medical board rules create deployment complexity for multi-state provider networks.
- Consumer wellness application substitution:Unregulated mental health and chronic disease apps compete for patient attention without clinical validation requirements.
Strategic Opportunities
- Neurological rehabilitation via VR:Virtual reality segments show concentrated R&D investment for stroke recovery and cognitive training applications with limited incumbent competition.
- EU MDR framework harmonization:The Medical Device Regulation creates a unified conformity assessment pathway for software-based interventions across member states.
- Workforce behavioral health benefits:Employer-sponsored programs expand coverage for mental health applications as absence management costs drive procurement.
Industry Challenges
- Interoperability with electronic health records:Integration complexity with legacy hospital systems delays deployment and increases implementation costs for health system customers.
- Specialized regulatory affairs talent:Scarcity of professionals experienced in FDA digital health pre-certification and EU MDR technical documentation slows product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Therapeutics Market |
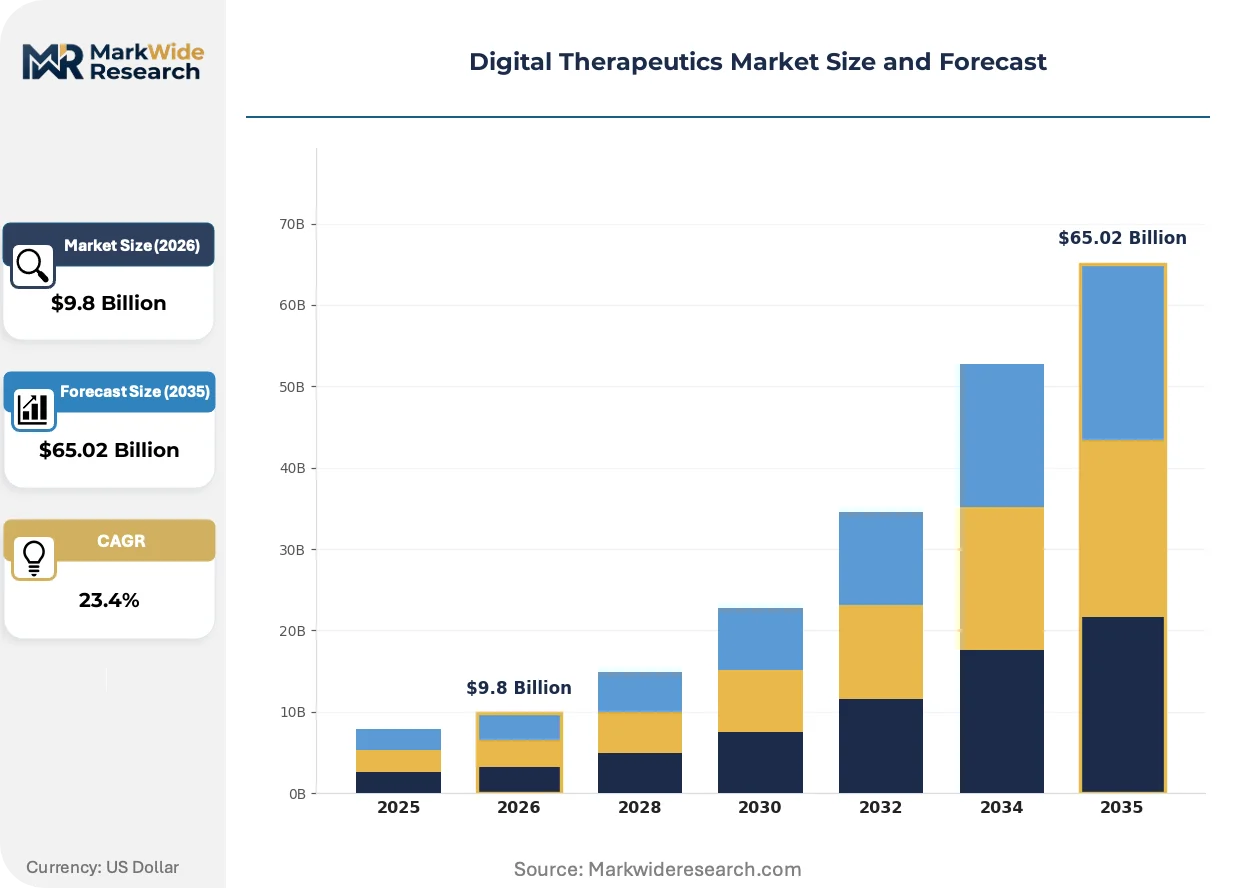
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $65.02 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preventive Solutions, Management Platforms, Rehabilitation Software, Diagnostic Tools Therapy Area: Diabetes, Mental Health, Cardiovascular Disorders, Respiratory Conditions, Neurological Disorders End User: Hospitals, Specialty Clinics, Telehealth Providers, Health Insurers, Research Institutes Delivery Mode: Mobile Applications, Web-Based Platforms, Wearable Devices, Virtual Reality, Chatbots |
| Companies Covered | Pear Therapeutics, Omada Health, Teladoc Health, Welldoc, 2Morrow, Propeller Health, Akili Interactive Labs, Big Health, CureApp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Therapeutics Market Strategic Shifts & Innovations
Evidence generation protocols and delivery infrastructure are converging to separate reimbursable clinical tools from consumer wellness applications, with regulatory clarity becoming the primary competitive differentiator.
Artificial intelligence is digitizing personalized intervention adaptation by analyzing real-time patient response data to modify therapy intensity. Health systems deploying these platforms report reduced nursing touchpoints for chronic disease cohorts. The technology is digitizing the traditional care team role in behavioral modification, compressing labor costs while maintaining clinical fidelity.
The FDA digital health pre-certification program is accelerating market access for developers with established quality management systems by permitting iterative software updates without supplemental review. Manufacturers with predicate device experience leverage this pathway to compress time-to-revenue for new therapy areas. Mental health applications face the steepest evidence requirements under this framework due to suicide risk monitoring obligations.
Employer procurement of chronic disease management is consolidating around platforms offering multiple therapy areas under single contracts, displacing point solutions. Benefits administrators at Fortune 500 companies negotiate enterprise licenses covering diabetes prevention, hypertension management, and behavioral health simultaneously. This pattern concentrates most visibly in the United States where self-insured employers directly bear medical cost risk.
Digital Therapeutics Market Segmentation
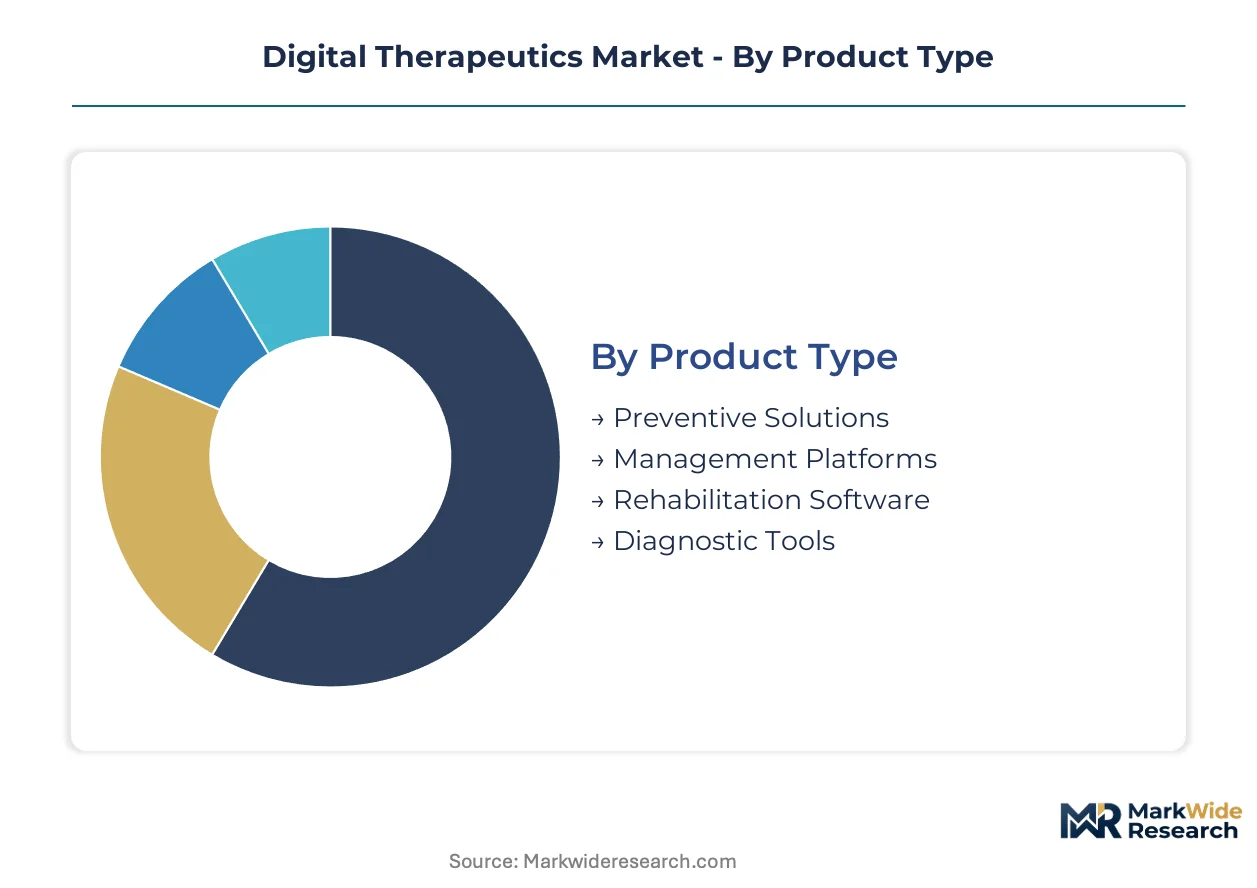
Segmentation in digital therapeutics reveals how reimbursement pathways and clinical evidence requirements stratify commercial opportunity. Developers must align product architecture with specific payer contracts and regulatory frameworks governing each category.
Product Type:
Mature enterprise platforms dominate revenue concentration, while emerging diagnostic modules attract venture funding for novel biomarker integration.
- Preventive Solutions:Software interventions targeting prediabetes and hypertension progression through behavioral modification protocols. Employer-sponsored wellness programs in the United States drive procurement for these applications as self-insured plans seek to compress medical cost trends.
- Management Platforms:Consolidated systems integrating multiple chronic disease modules under single-payer contracts. These platforms anchor health insurer benefit designs by enabling prior authorization streamlining and population-level outcome tracking.
- Rehabilitation Software:Post-acute care protocols for orthopedic and cardiac recovery delivered through prescribed home exercise programs.
- Diagnostic Tools:Algorithm-based screening applications for cognitive decline and respiratory function monitoring.
Management Platforms handle the majority of throughput; Preventive Solutions are expanding most quickly on share.
Therapy Area:
Cost tier stratification separates high-acuity conditions requiring intensive clinical validation from lower-barrier wellness applications.
- Diabetes:Continuous glucose monitoring integration with insulin dosing algorithms and lifestyle coaching modules. Medicare Advantage plans in the United States prioritize coverage for these interventions given the disease's prevalence in aging populations.
- Mental Health:Cognitive behavioral therapy applications for depression, anxiety, and substance use disorders. Workforce benefits administrators expand procurement here as absence management costs climb and FDA suicide risk monitoring requirements create regulatory moats.
- Cardiovascular Disorders:Hypertension management and post-myocardial infarction rehabilitation protocols.
- Respiratory Conditions:Asthma control and chronic obstructive pulmonary disease monitoring through symptom tracking.
- Neurological Disorders:Stroke recovery and cognitive training applications with concentrated R&D investment in virtual reality delivery.
Mental Health commands the steepest evidence requirements; Neurological Disorders show the fastest share gains.
End User:
Customer type determines contracting complexity, with integrated delivery networks demanding interoperability while telehealth platforms prioritize rapid deployment.
- Hospitals:Epic and Cerner EHR integration requirements dominate procurement criteria for these health system customers. Implementation timelines stretch 12-18 months due to legacy system complexity and information security reviews.
- Specialty Clinics:Cardiology and endocrinology practices seeking point solutions for specific chronic disease cohorts. These buyers favor standalone applications with minimal IT infrastructure demands.
- Telehealth Providers:Teladoc Health and competing virtual care platforms embedding digital therapeutics into broader service bundles.
- Health Insurers:CVS Health and UnitedHealth Group designing benefit structures that steer members toward validated interventions.
- Research Institutes:Academic medical centers conducting real-world evidence studies to support FDA pre-certification pathways.
Health Insurers concentrate the largest contract values; Telehealth Providers are climbing the fastest on volume.
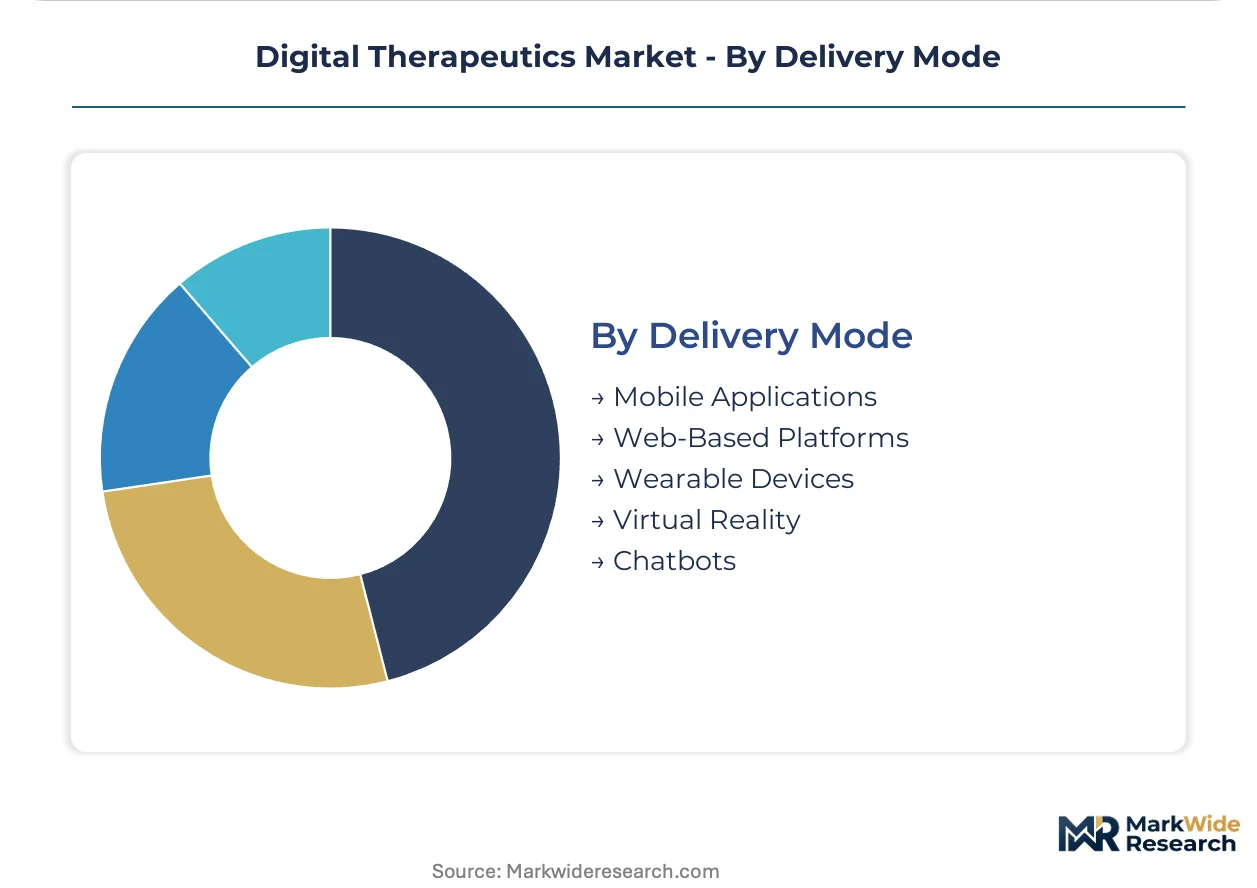
Delivery Mode:
Volume distribution skews toward smartphone-accessible formats, though hardware-dependent modalities capture premium pricing for neurological applications.
- Mobile Applications:Native iOS and Android software delivering behavioral modification protocols without peripheral dependencies. Smartphone penetration rates above 85% in developed markets enable scalable deployment across chronic disease populations.
- Web-Based Platforms:Browser-accessible interventions for employer wellness programs and health system patient portals. These solutions accommodate older patient demographics less comfortable with app installation.
- Wearable Devices:Apple Watch and dedicated biosensor integration for continuous physiological monitoring.
- Virtual Reality:Headset-based immersive environments for stroke rehabilitation and pain management.
- Chatbots:Conversational AI interfaces for mental health screening and medication adherence prompting.
Mobile Applications handle the majority of throughput; Virtual Reality shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes digital therapeutics through employer-sponsored benefit structures and integrated delivery networks, while Germany and Japan emphasize statutory health insurance reimbursement pathways with stricter clinical evidence thresholds.
United States
Commercial payers at CVS Health and UnitedHealth Group embed prescription digital therapeutics into benefit designs as medical cost containment tools. The FDA's Prescription Drug Use Fee Act framework establishes billing code clarity that accelerates provider adoption across integrated delivery networks. The Boston-Cambridge corridor anchors venture funding concentration for FDA pre-certification pathway developers.
Germany
Statutory health insurance funds drive procurement through the DiGA fast-track pathway for digital health applications with proven clinical benefit. The EU MDR framework harmonizes conformity assessment requirements across member states while maintaining BfArM oversight for national reimbursement listing. Berlin and Munich host the densest clusters of regulatory affairs specialists navigating technical documentation requirements.
United Kingdom
NHS England's digital technology assessment criteria steer procurement toward interventions demonstrating cost-effectiveness against standard care. The MHRA operates recognition routes with the FDA and Health Canada to streamline market access for developers with prior regulatory clearance. London's health tech corridor concentrates health economics modeling capabilities supporting NICE submissions.
Japan
PMDA's SaMD guidance creates structured pathways for software-based interventions targeting aging-related chronic disease burdens. The Ministry of Health, Labour and Welfare's reimbursement pricing methodology for digital therapeutics remains under pilot expansion for diabetes and hypertension management. Tokyo and Osaka anchor pharmaceutical-digital therapeutic partnership activity for co-development models.
France
HAS evaluation criteria for digital medical devices prioritize clinical benefit demonstration over cost containment alone in reimbursement decisions. The ANSM's software medical device guidance aligns with MDR implementation timelines while maintaining national specificities for post-market surveillance. The Paris-Saclay cluster concentrates health data infrastructure projects enabling real-world evidence generation for digital therapeutic validation.
Digital Therapeutics Market Key Industry Players
Capability concentration sits with FDA-cleared developers possessing predicate device experience; scale advantage sits with virtual care platforms integrating multiple therapy modules. The competitive structure organizes around three archetypes: prescription digital therapeutic specialists, chronic disease management platforms, and telehealth infrastructure integrators. Dominant competitive moves include payer contract consolidation around multi-therapy enterprise licenses and strategic partnerships with EHR vendors to compress implementation timelines.
Among FDA-cleared specialists, Pear Therapeutics and Akili Interactive Labs exemplify the regulatory-first archetype, anchoring their market positions through prescription-grade clinical evidence generation. Omada Health occupies a position within the employer-sponsored platform tier, representing the chronic disease management consolidation pattern. Teladoc Health sits within the virtual care integration archetype, embedding digital therapeutics into broader telehealth service bundles.
| Leading Market Players |
|---|
| Pear Therapeutics |
| Omada Health |
| Teladoc Health |
| Welldoc |
| 2Morrow |
| Propeller Health |
| Akili Interactive Labs |
| Big Health |
| CureApp |
| Others |
Cost & Logistics Intelligence
Overcapacity in consumer wellness applications is compressing margins for clinical-grade developers, forcing FDA-cleared platforms to differentiate through enterprise licensing structures that tether pricing power to proven outcomes. This utilization imbalance shapes supplier behavior toward multi-therapy consolidation and buyer posture toward value-based contracting.
Pricing Analysis
Long-term enterprise contracts anchor pricing structures for management platforms, displacing per-prescription transactional models as employers and health insurers consolidate procurement. Price differentiation separates FDA-cleared prescription digital therapeutics from unregulated wellness applications through clinical validation tiers and EHR integration depth. Cost compression in the consumer wellness tier is intensifying because unregulated applications compete without evidence generation burdens. Self-insured employers show the least price sensitivity given direct medical cost risk bearing, while individual consumers through app stores demonstrate the highest sensitivity to subscription fees.
Supply Chain Analysis
Upstream cloud infrastructure feeds from hyperscaler concentration in the United States, Ireland, and Singapore, with AWS, Azure, and Google Cloud hosting the majority of digital therapeutic deployments. Raw material dependencies center on semiconductor components for VR headsets, specialized biosensors for continuous monitoring, and licensed clinical content libraries for cognitive behavioral therapy protocols. Single-source vulnerability in FDA regulatory affairs talent pools creates bottlenecks for pre-certification pathway navigation. Distribution runs through direct sales teams to health insurers and employer benefits administrators, with channel partners handling EHR integration implementation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from unregulated wellness applications that erode patient acquisition economics without comparable clinical validation investments. This defensive posture requires structural moves that widen the regulatory moat between reimbursable platforms and consumer-grade alternatives.
For Market Incumbents: Entrench FDA predicate device experience through accelerated pre-certification pathway utilization, compressing competitor time-to-market. Deepen vertical integration into EHR vendor partnerships with Epic and Cerner to lock out point-solution competitors through interoperability contracts. The wellness application substitution threat demands clinical evidence generation at pharmaceutical-grade scale to maintain payer differentiation.
For New Entrants and Emerging Players: Neurological rehabilitation via virtual reality in Japan and Germany represents the most penetrable entry point given limited incumbent competition and concentrated R&D investment gaps. Employer-sponsored behavioral health benefits in mid-market United States companies offer secondary white-space with lower FDA evidence requirements than suicide-risk-monitored applications. A direct-to-employer sales model bypasses health system implementation complexity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across FDA pre-certification pathway developers as clinical trial requirements approach pharmaceutical timelines. Long-term viability favors platforms with multi-therapy enterprise contracts rather than single-product prescriptions. The acquisition target archetype is chronic disease management platforms with established payer relationships. The signal to watch is CMS reimbursement pricing methodology pilot expansion for digital therapeutics.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway Utilization | Accelerates iterative software updates without supplemental review for predicate device developers. |
| EHR Vendor Partnership | Compresses 12-18 month implementation timelines through Epic and Cerner integration contracts. |
| Multi-Therapy Enterprise Licensing | Captures employer procurement consolidation across diabetes, hypertension, and behavioral health modules. |
| EU MDR Technical Documentation Investment | Enables DiGA fast-track access in Germany and harmonized conformity assessment across member states. |
| Real-World Evidence Generation | Supports NICE submissions in the United Kingdom and NHS England technology assessment criteria compliance. |
Research Approach
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Conversations with FDA regulatory affairs specialists, health insurer benefits administrators, employer procurement directors, and hospital biomedical engineers inform the competitive dynamics assessment. Secondary sources include FDA 510(k) clearance databases, CMS Medicare coverage determinations, DiGA directory listings from BfArM, and NHS England digital technology assessment publications. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across the analysis window.
Calibration against historical FDA clearance timelines and payer coverage expansion patterns validates the projection framework. Segmentation dimensions modeled include product type, therapy area, end user, and delivery mode, with regulatory pathway complexity as an additional cross-cutting variable. CAGRs derive from fitted growth curves adjusted for reimbursement policy inflection points. Forecast inputs incorporate health insurer medical cost trend targets and employer wellness program budget allocations.
Practitioners should monitor FDA digital health guidance revisions and CMS national coverage determination updates for early signals of forecast deviation. Cross-checking against health insurer annual benefit design disclosures and employer wellness program vendor selection announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Women Digital Health Solutions Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
US Real World Evidence Solutions Market
Digital Health Solutions
Cardiac AI Monitoring and Diagnostic Market
Digital Health Solutions
GCC E-Health Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Global Real World Evidence Solutions Market
Digital Health Solutions
Asia-Pacific Heart Failure Software Market
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
Patient Engagement Platforms Market