
 Digital Patient Engagement Solutions Market | 2026-2036
Digital Patient Engagement Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Patient Engagement Solutions Market Analysis
Buyer concentration among integrated delivery networks is realigning procurement priorities across the Digital Patient Engagement Solutions landscape. Epic Systems Corporation dominates the inpatient segment with deeply embedded EHR-native engagement modules that lock in hospital system loyalty. Oracle leverages its Cerner acquisition to extend cloud infrastructure across ambulatory settings, while Microsoft Corporation anchors enterprise-scale deployments through Azure health data services and Teams-integrated care coordination.
Digital patient engagement solutions encompass software platforms and connected services that enable two-way interaction between patients and care teams through secure messaging, appointment scheduling, medication adherence tracking, and personalized health education content delivered via HIPAA-compliant architectures. Mobile Apps and Telehealth Platforms represent the fastest-expanding technology pair, with AI-Based Solutions capturing disproportionate R&D investment as health systems automate triage and outreach at scale. Cloud Solutions sustain the dominant delivery position by reducing capital expenditure for mid-size clinics, while On-Premise deployments retain share among institutions with restrictive data residency requirements.
FDA software-as-a-medical-device oversight and HIPAA security rule enforcement jointly determine product validation pathways and liability exposure for vendors serving US health systems. The EU AI Act and MDR framework impose additional conformity requirements on algorithmic patient-facing tools marketed in Europe, creating divergent compliance cost structures. Stakeholders must monitor how CMS reimbursement policy for remote patient monitoring reshapes provider willingness to subsidize patient-facing platform costs.
Market Dynamics
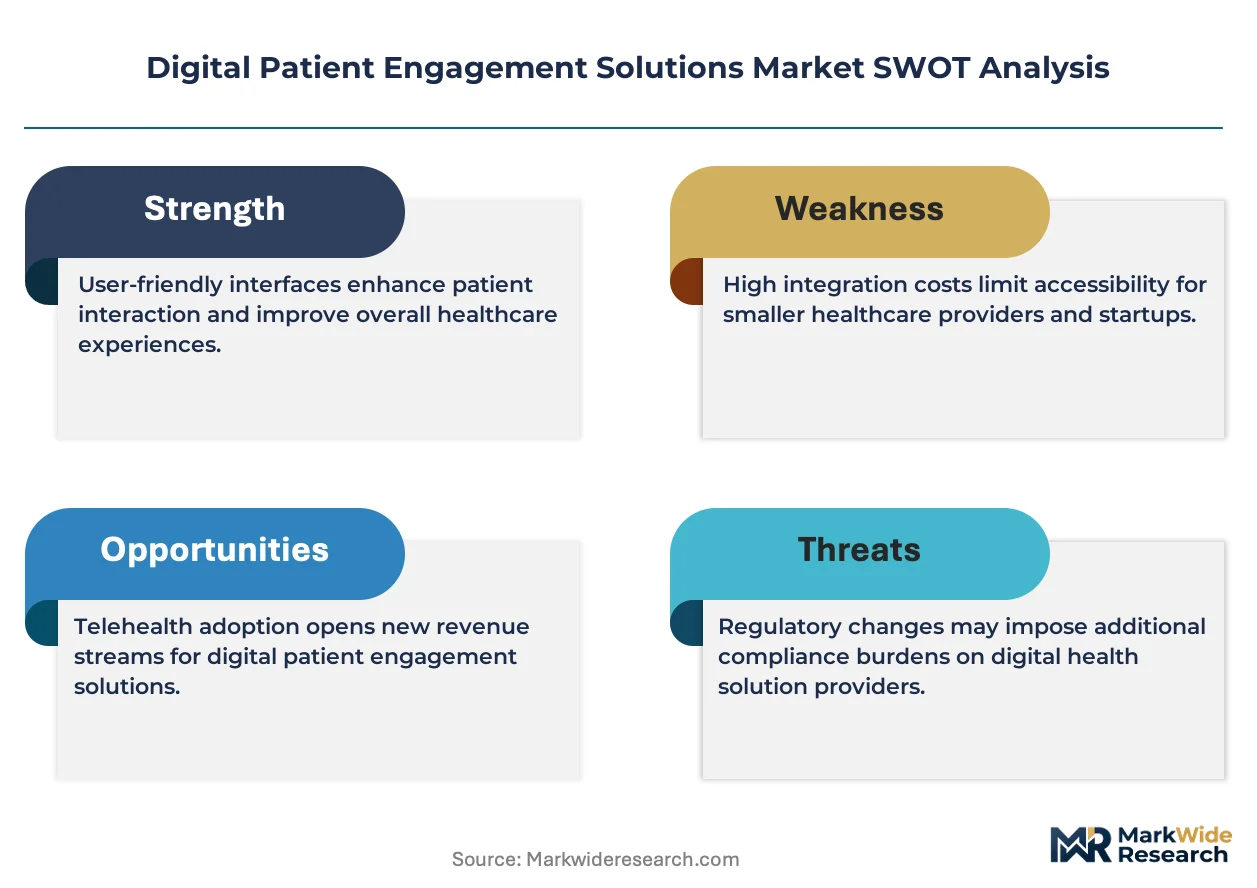
Consolidation among US integrated delivery networks is concentrating procurement power into fewer hands, forcing vendors to restructure pricing and integration roadmaps around value-based care contract requirements rather than standalone software sales.
Growth Catalysts
- FDA software-as-a-medical-device framework:The validation pathway creates regulatory clarity for algorithmic triage tools, accelerating hospital system adoption of AI-enabled patient outreach platforms.
- Germany's interoperable EHR mandate:Federal requirements for hospital network connectivity are generating concentrated demand for standardized engagement modules that integrate with national health infrastructure.
- Cloud infrastructure maturation:HIPAA-compliant Azure and AWS architectures reduce capital barriers for mid-size ambulatory clinics, expanding addressable market penetration beyond academic medical centers.
Market Restraints
- EU AI Act compliance costs:Algorithmic patient-facing tools marketed in Europe face divergent conformity assessment requirements, fragmenting vendor R&D budgets across multiple regulatory pathways.
- Legacy EHR lock-in:Deep embedding of Epic-native engagement modules creates switching friction that suppresses competitive displacement and extends replacement cycles.
- Cybersecurity insurance escalation:Breach liability exposure under HIPAA security rule enforcement is driving premium increases that squeeze vendor margins and delay SMB market entry.
Strategic Opportunities
- Remote patient monitoring reimbursement:CMS policy expansion creates direct revenue streams enabling providers to subsidize patient-facing platform deployment costs.
- Chronic disease management convergence:Integration of continuous glucose monitors with engagement platforms opens diabetes and cardiovascular verticals previously served by disconnected point solutions.
- Latin American telehealth infrastructure:Underpenetrated markets in Brazil and Mexico present first-mover advantages for cloud-native vendors with Portuguese and Spanish localization capabilities.
Industry Challenges
- Interoperability engineer scarcity:Shortage of FHIR-standard specialists delays integration timelines and inflates implementation costs for health systems pursuing best-of-breed strategies.
- Clinical workflow reconfiguration:Care teams resist adoption when engagement tools generate alert fatigue or duplicate documentation burdens without EHR-native workflow embedding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Patient Engagement Solutions Market |
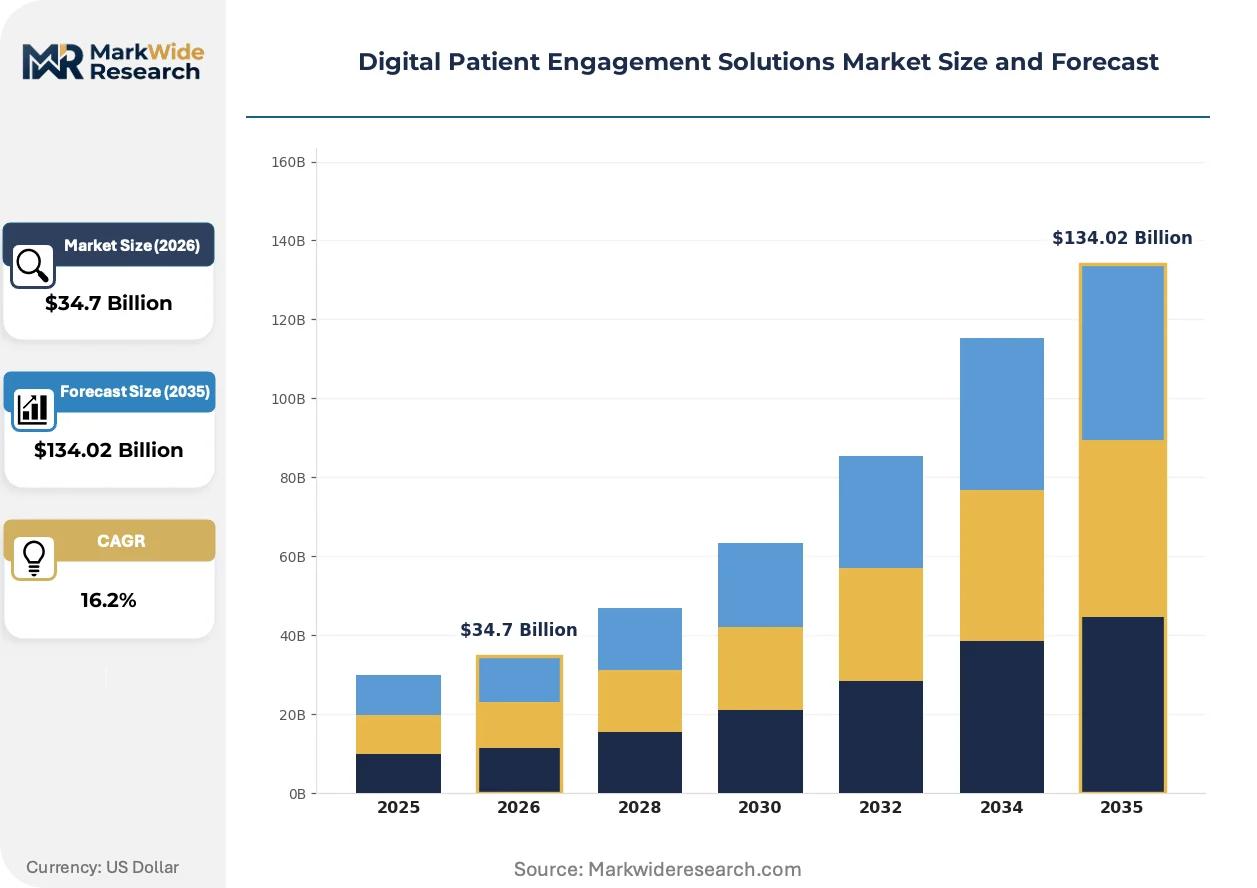
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $134.02 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Communication Tools, Remote Monitoring, Education Portals Technology: AI-Based Solutions, Cloud Solutions, Chatbots, Telehealth Platforms End User: Clinics, Hospitals, Pharmacies, Health Insurance Providers Delivery Mode: Web-Based, Mobile-Based, On-Premise, Hybrid |
| Companies Covered | McKesson Corporation, Oracle, Veradigm LLC, athenahealth, Health Catalyst, IBM Corporation, Microsoft Corporation, Accenture, Epic Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Patient Engagement Solutions Market Emerging Trajectories
Artificial intelligence is compressing the gap between patient-generated data and clinical action, reshaping how health systems prioritize automation investments across triage, outreach, and adherence monitoring functions.
Edge computing architectures for patient monitoring devices are decentralizing data processing away from centralized cloud repositories. Rural health systems and home-based care providers are adopting these distributed models to reduce latency in critical alert generation. This shift is decentralizing vendor competitive advantage from scale economies toward localized reliability guarantees and offline functionality.
The EU AI Act's risk classification system for biometric and health-related algorithms imposes conformity documentation burdens on patient-facing diagnostic tools. Vendors must now maintain technical file repositories and post-market surveillance systems previously unnecessary for wellness applications. European hospital procurement committees are prioritizing suppliers with established notified body relationships, compressing competitive windows for new entrants.
Subscription-based platform licensing is displacing perpetual software purchases across US ambulatory networks. Specialty clinics and federally qualified health centers now demand usage-scaled pricing tied to patient panel size rather than fixed seat counts. This behavioral shift is most visible in Medicaid-dependent markets where cash flow constraints favor operational expenditure structures over capital deployment.
Digital Patient Engagement Solutions Market Segmentation
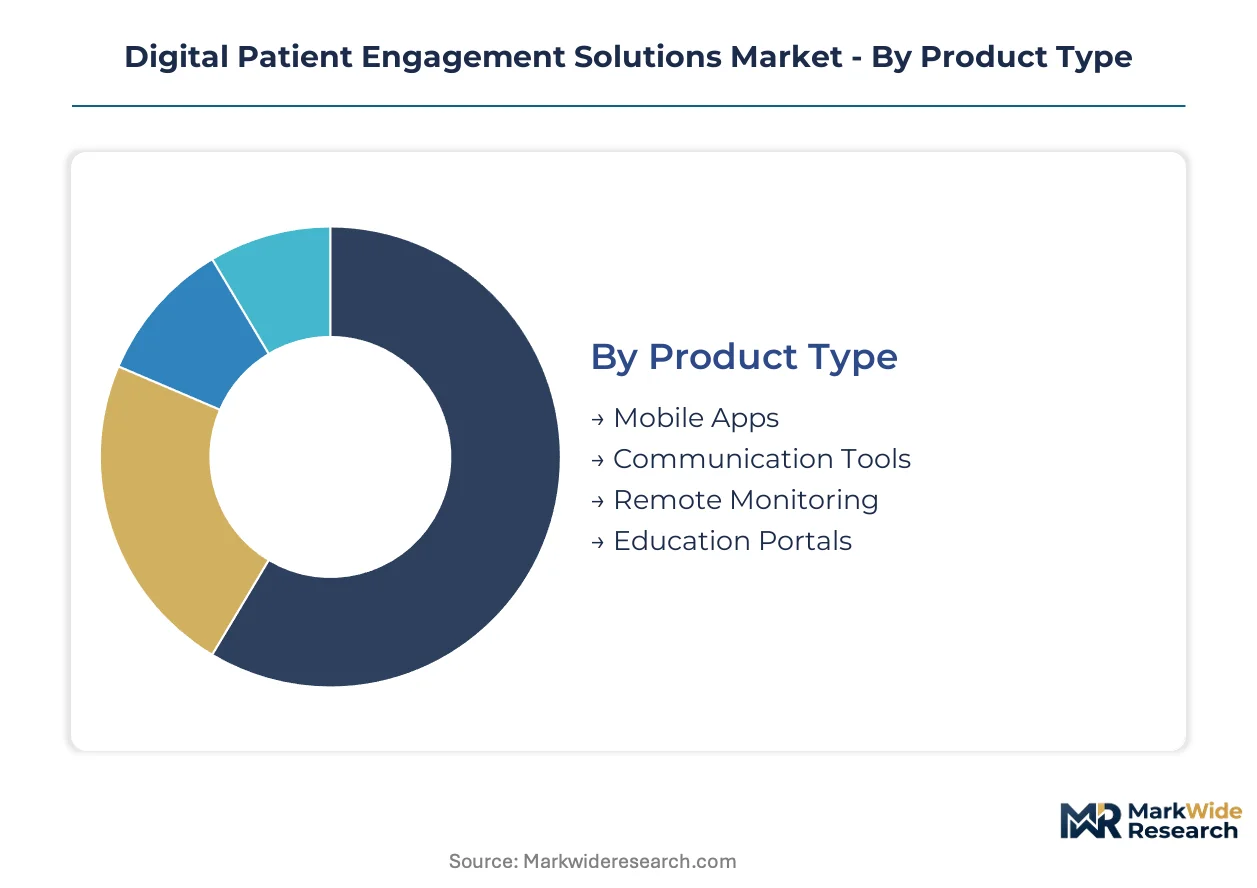
Patient engagement platforms fragment across interaction modalities, infrastructure requirements, and care settings. Vendors must align development roadmaps with the specific workflow constraints and reimbursement structures governing each segment.
Product Type:
Standardized modules dominate high-volume deployments while custom configurations persist in academic medical centers with unique EHR architectures.
- Mobile Apps:Native iOS and Android applications deliver appointment scheduling, secure messaging, and medication reminders through HIPAA-compliant APIs. Demand concentrates in US ambulatory networks where CMS reimbursement for remote patient monitoring subsidizes patient-facing technology investments.
- Communication Tools:Two-way messaging platforms integrate with EHR inboxes and nurse call systems to reduce phone tag and no-show rates. Health systems in Germany prioritize these modules to meet federal interoperability mandates for hospital network connectivity.
- Remote Monitoring:Continuous data ingestion from connected devices enables asynchronous chronic disease management.
- Education Portals:Personalized health content libraries reduce readmissions through condition-specific discharge instructions.
Most installed capacity flows through Communication Tools. Expansion is steepest in Remote Monitoring.
Technology:
Cloud-native architectures reduce capital barriers for mid-size providers while on-premise AI deployments retain favor among institutions with restrictive data residency requirements.
- AI-Based Solutions:Natural language processing engines automate triage, sentiment analysis, and predictive risk stratification from unstructured patient messages. US health systems under value-based care contracts drive adoption to reduce manual outreach labor.
- Cloud Solutions:Multi-tenant SaaS platforms on Azure and AWS infrastructure eliminate server maintenance burdens. Clinics in Brazil and Mexico favor these deployments for rapid scaling without dedicated IT staff.
- Chatbots:Rules-based and large language model interfaces handle routine scheduling and billing inquiries.
- Telehealth Platforms:Synchronous video consultation systems with integrated payment processing.
Cloud Solutions carry the majority of current deployments. AI-Based Solutions are gaining share fastest.
End User:
Purchasing sophistication varies sharply across settings, with hospitals demanding EHR-native integration and pharmacies prioritizing standalone medication adherence modules.
- Clinics:Federally qualified health centers and specialty practices require usage-scaled pricing tied to patient panel size rather than fixed licensing.
- Hospitals:Integrated delivery networks consolidate procurement across inpatient and ambulatory footprints, favoring vendors with proven Epic or Oracle Cerner integration.
- Pharmacies:Retail chains deploy patient engagement tools to drive medication adherence and vaccination scheduling.
- Health Insurance Providers:Payers subsidize member-facing platforms to reduce emergency department utilization and improve HEDIS quality scores.
Hospitals account for the largest installed base. Health Insurance Providers show the steepest expansion trajectory.
Delivery Mode:
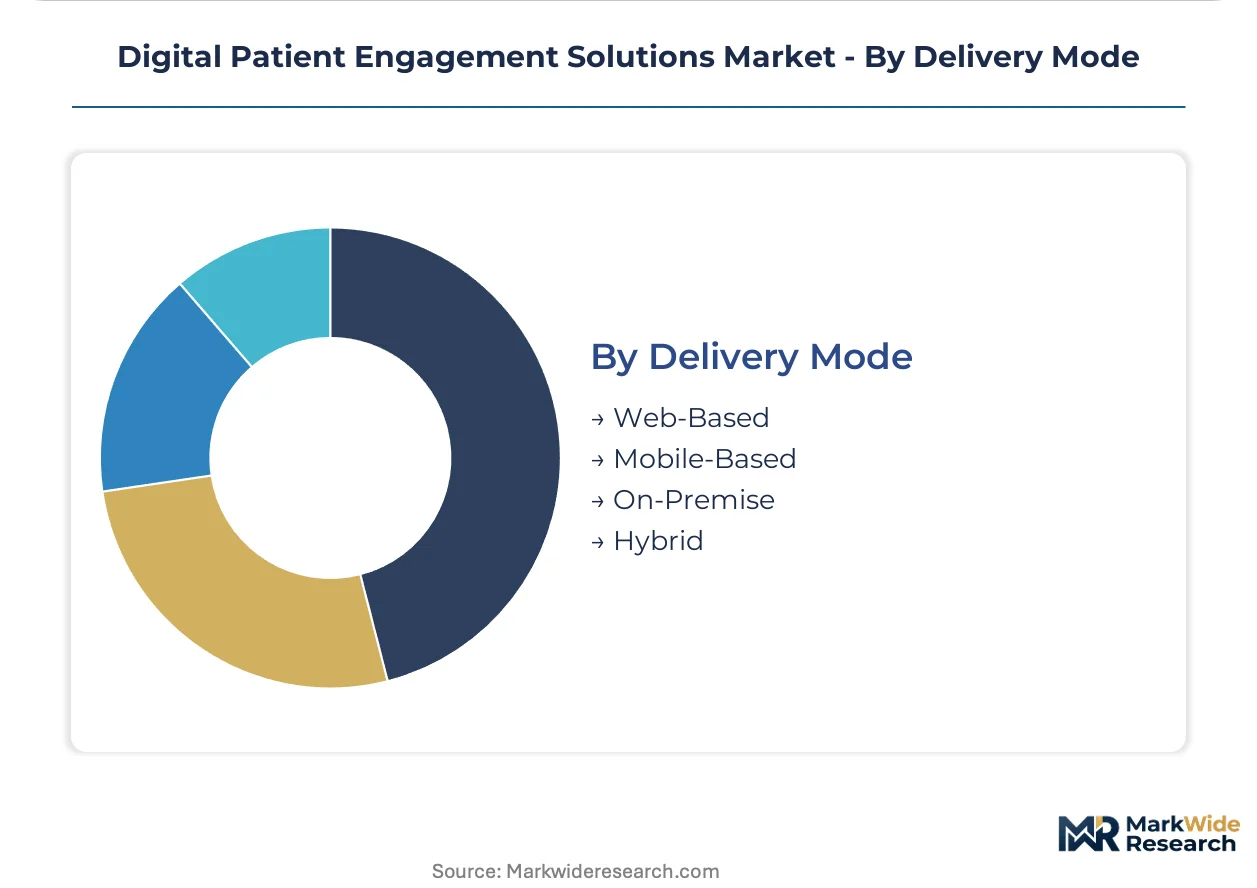
Hybrid architectures are displacing pure cloud or on-premise approaches as health systems seek edge resilience without sacrificing centralized analytics.
- Web-Based:Browser-accessible portals require no app installation, maximizing reach among elderly populations with limited smartphone comfort.
- Mobile-Based:Native applications leverage push notifications and biometric authentication for higher engagement intensity among chronic disease cohorts.
- On-Premise:Self-hosted deployments satisfy data residency requirements in German hospital networks and US Department of Veterans Affairs facilities.
- Hybrid:Edge-computing nodes process critical alerts locally while syncing non-urgent data to cloud repositories for population analytics.
Web-Based systems retain the broadest footprint. Hybrid deployments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent clusters in the United States anchor the industry's innovation pipeline, with specialized FHIR developers and health informaticists concentrated in metropolitan health technology corridors driving platform differentiation.
United States
Integrated delivery networks in Texas and California consolidate procurement power under value-based care contracts, demanding EHR-native engagement modules. FDA software-as-a-medical-device oversight creates regulatory clarity for algorithmic triage tools, accelerating hospital system adoption. The Boston-Cambridge corridor hosts concentrated health informatics talent developing AI-enabled patient outreach platforms for academic medical centers.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia face federally mandated interoperability deadlines for electronic health records, generating concentrated demand for standardized engagement modules. The EU AI Act's risk classification system imposes conformity documentation burdens on patient-facing diagnostic tools. Berlin's digital health cluster attracts vendors establishing notified body relationships for European market access.
United Kingdom
NHS Integrated Care Systems in England consolidate commissioning for patient-facing platforms, favoring vendors with proven interoperability across regional health records. GDPR compliance requirements shape data residency architectures for cloud deployments. London's health technology district hosts established players and emerging specialists competing for national framework contracts.
Brazil
Ambulatory networks in São Paulo and Rio de Janeiro adopt cloud-native engagement platforms to bypass dedicated IT infrastructure requirements. ANVISA's digital health regulatory pathway matures, creating clearer validation routes for software-as-a-medical-device products. The São Paulo health technology corridor attracts Portuguese-localized solutions targeting underpenetrated private insurance markets.
India
Hospital chains in Maharashtra and Karnataka deploy patient engagement modules to differentiate in competitive metropolitan healthcare markets. CDSCO's evolving software medical device framework creates regulatory navigation challenges for algorithmic tools. Bangalore's health technology ecosystem produces specialized engineering talent for FHIR-standard integration development serving domestic and export markets.
Digital Patient Engagement Solutions Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered competitive positions. Enterprise technology conglomerates leverage cloud infrastructure and existing health system relationships to anchor platform deployments. EHR-native specialists retain loyalty through deeply embedded workflow integration. Health informatics consultancies bridge implementation gaps. M&A activity concentrates procurement power while strategic partnerships accelerate interoperability certification timelines.
Within the enterprise technology tier, Oracle and Microsoft Corporation occupy positions leveraging cloud infrastructure scale. Epic Systems Corporation exemplifies the EHR-native specialist archetype with deeply embedded hospital system relationships. McKesson Corporation anchors the healthcare-diversified conglomerate position spanning distribution and technology services. These three represent distinct strategic postures rather than directly comparable competitive positioning.
| Leading Market Players |
|---|
| McKesson Corporation |
| Oracle |
| Veradigm LLC |
| athenahealth |
| Health Catalyst |
| IBM Corporation |
| Microsoft Corporation |
| Accenture |
| Epic Systems Corporation |
| Others |
Supply Flow & Price Mechanics
FHIR engineering labor costs in Bangalore and Boston flow downstream through subscription pricing tiers, with specialized integration talent scarcity compressing margins for mid-size vendors serving US ambulatory networks while cloud infrastructure economies of scale subsidize entry-level SaaS offerings.
Pricing Analysis
Bundled platform subscriptions encompassing EHR integration, patient messaging, and analytics modules command premium positioning against unbundled point solutions for scheduling or telehealth alone. Pricing stratifies across enterprise, mid-market, and clinic tiers based on patient panel volume and Epic-native certification status. Cost compression in the mid-market segment is intensifying because Oracle and Microsoft are absorbing integration labor into cloud infrastructure bundles. Federally qualified health centers exhibit highest price sensitivity due to Medicaid reimbursement constraints, while academic medical centers prioritize workflow embedding over cost.
Supply Chain Analysis
Specialized health informatics talent availability in India, the United States, and Germany determines development velocity for FHIR-standard integration modules. Cloud infrastructure draws from AWS, Azure, and Google data center networks, while algorithmic components rest on NVIDIA GPU clusters and open-source machine learning frameworks. Single-source vulnerability concentrates in Epic's proprietary APIs, which gate patient data access for third-party engagement tools. Distribution runs through direct enterprise sales teams for hospital networks and channel partnerships with EHR consultants for ambulatory clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA software-as-a-medical-device validation and CMS remote patient monitoring reimbursement expansion create successive demand waves for compliant platform investments.
For Market Incumbents: Deepen EHR-native workflow embedding to raise switching costs against best-of-breed challengers. Acquire FHIR-specialist consultancies to internalize scarce integration engineering capacity. Expand cloud infrastructure partnerships with Microsoft Azure to defend margin position against Oracle's Cerner-anchored bundling strategy.
For New Entrants and Emerging Players: Direct-to-clinic SaaS routes bypassing hospital IT procurement committees offer lowest-friction customer acquisition. Target Latin American ambulatory networks in São Paulo and Mexico City where ANVISA regulatory pathways are maturing and Epic lock-in remains shallow. Localize Portuguese and Spanish interfaces to capture first-mover premiums in underpenetrated private insurance markets.
For Investors and Strategic Acquirers: Roll-up economics work for vertical-specific engagement platforms because chronic disease management reimbursement is fragmenting procurement across diabetes, cardiovascular, and respiratory point solutions. Target specialist vendors with established FDA 510(k) clearances and hospital pilot contracts. Watch CMS remote patient monitoring code expansion as the inflection signal for platform subsidy viability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Regulatory clearance unlocks hospital procurement for algorithmic triage tools under value-based contracts. |
| Epic Integration Partnership | Native EHR embedding reduces implementation friction and extends replacement cycles for incumbent vendors. |
| Remote Patient Monitoring Reimbursement Strategy | CMS code capture enables providers to subsidize patient-facing platform deployment costs. |
| Cloud Infrastructure Partnership | Azure or AWS co-selling arrangements reduce capital barriers for mid-size clinic market penetration. |
| Vertical Disease Management Acquisition | Diabetes and cardiovascular specialization captures chronic care reimbursement convergence opportunities. |
Methodological Framework
Direct dialogue with hospital CIOs, ambulatory clinic practice managers, EHR integration specialists, and FDA regulatory consultants anchored qualitative findings, cross-validated against CMS reimbursement databases, hospital procurement records, SEC 10-K software segment disclosures, and hyperscaler health cloud revenue reports. Bottom-up patient engagement platform deployment counts triangulated with top-down health system IT spending estimates across the analysis window.
Segment-level projections for mobile apps, telehealth platforms, AI-based solutions, and remote monitoring devices incorporated deployment model, organization size, care setting integration complexity, and regional regulatory cluster dimensions. CAGRs were derived from patient panel growth assumptions, value-based care contract penetration curves, and cloud infrastructure adoption elasticities calibrated to historical EHR replacement cycles.
The model assumes a particular technology adoption path; alternative pathways for edge computing architectures in rural health systems would alter the outlook. Forecasts reflect assumptions about FDA enforcement consistency, CMS reimbursement stability, and FHIR standard maturation timelines. Material deviation in regulatory clarity or interoperability mandate deadlines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Europe Digital Health Market
Digital Health Solutions
Asia-Pacific Heart Failure Software Market
Digital Health Solutions
Pregnancy Tracking and Postpartum Care Apps Market
Digital Health Solutions
Advanced Clinical Decision Support Platforms Market
Digital Health Solutions
Global Health Kiosk Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
Econsent in Healthcare Market
Digital Health Solutions
US Patient Engagement Solutions Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
Global Preventive Healthcare Technologies and Services Market
Digital Health Solutions
Smart Cards in Healthcare Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
US Digital Health Market
Digital Health Solutions
Digital Health Market