
 Pregnancy Management Software Market | 2026-2036
Pregnancy Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Pregnancy Management Software Market Insights
Cloud-native interoperability is rewriting how pregnancy management platforms exchange data across care settings. Cerner Corporation leverages its established EHR footprint to anchor enterprise maternity workflows inside hospital networks. Epic Systems Corporation sustains R&D intensity in native obstetrics modules that integrate scheduling, risk stratification, and fetal monitoring. Philips Healthcare differentiates through connected device ecosystems that feed biometric streams directly into clinical dashboards.
Pregnancy management software encompasses digital platforms that capture, analyze, and communicate maternal-fetal health data across gestation, typically integrating HL7 FHIR protocols for EHR compatibility and supporting remote physiological parameter transmission. These systems serve primarily to coordinate prenatal through postpartum care, reduce preventable complications, and enable risk-adjusted intervention timing. Cloud-based deployments now lead product type adoption because subscription economics lower capital barriers for mid-sized clinics, while AI-driven technology segments attract the fastest investment as vendors embed predictive algorithms for preeclampsia and preterm birth risk scoring. Wearable devices remain a smaller but structurally critical segment because hardware-generated biometric streams create recurring data subscription revenue that software-only models cannot replicate.
The FDA's SaMD framework and HIPAA security rule jointly shape product architecture by mandating clinical validation thresholds and encryption standards before platforms enter reimbursable care pathways. State-level Medicaid expansion of remote maternal health services, particularly across the American South and Midwest, creates patchwork reimbursement conditions that vendors must navigate for market access. Stakeholders should monitor how CMS maternity care episode payment pilots alter procurement criteria for integrated platforms versus point solutions.
Market Dynamics
Hospital procurement teams now mandate bidirectional HL7 FHIR interoperability as a baseline requirement, forcing vendors to rebuild legacy architectures around open API standards rather than proprietary data silos. This technical pivot is compressing competitive differentiation toward predictive analytics capabilities and wearable device integration depth.
Growth Catalysts
- Medicaid Expansion:State-level remote maternal health reimbursement policies across the American South and Midwest are opening reimbursable care pathways for cloud-based monitoring platforms.
- FDA SaMD Framework:Clearer clinical validation thresholds for maternal-fetal monitoring software are reducing regulatory uncertainty and accelerating product commercialization timelines.
- AI Risk Scoring:Machine learning algorithms for preeclampsia and preterm birth prediction are embedding into enterprise EHR workflows, creating new subscription revenue tiers.
Market Restraints
- Cybersecurity Infrastructure:HIPAA security rule compliance and end-to-end encryption requirements add substantial development cost and certification timeline risk for smaller vendors.
- Reimbursement Fragmentation:Patchwork state-level Medicaid policies create uneven market access conditions that complicate national rollout strategies for platform developers.
- Clinical Validation Burden:FDA's expanding oversight of Software as a Medical Device demands prospective studies that extend time-to-revenue for novel predictive features.
Strategic Opportunities
- Postpartum Extension:The twelve-month postpartum care window recently emphasized by CMS creates new monitoring revenue streams beyond traditional gestation-limited contracts.
- Rural Health Networks:Federally Qualified Health Centers in underserved counties present underpenetrated deployment opportunities for asynchronous telehealth modules.
- Wearable Data Subscriptions:Hardware-generated biometric streams from connected devices enable recurring revenue models that pure software licensing cannot replicate.
Industry Challenges
- Interoperability Engineering:Mapping proprietary device data formats to standardized FHIR resources consumes specialized health informatics talent that vendors struggle to recruit.
- Legacy EHR Integration:Custom interface development for fragmented hospital IT environments extends implementation timelines and strains professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pregnancy Management Software Market |
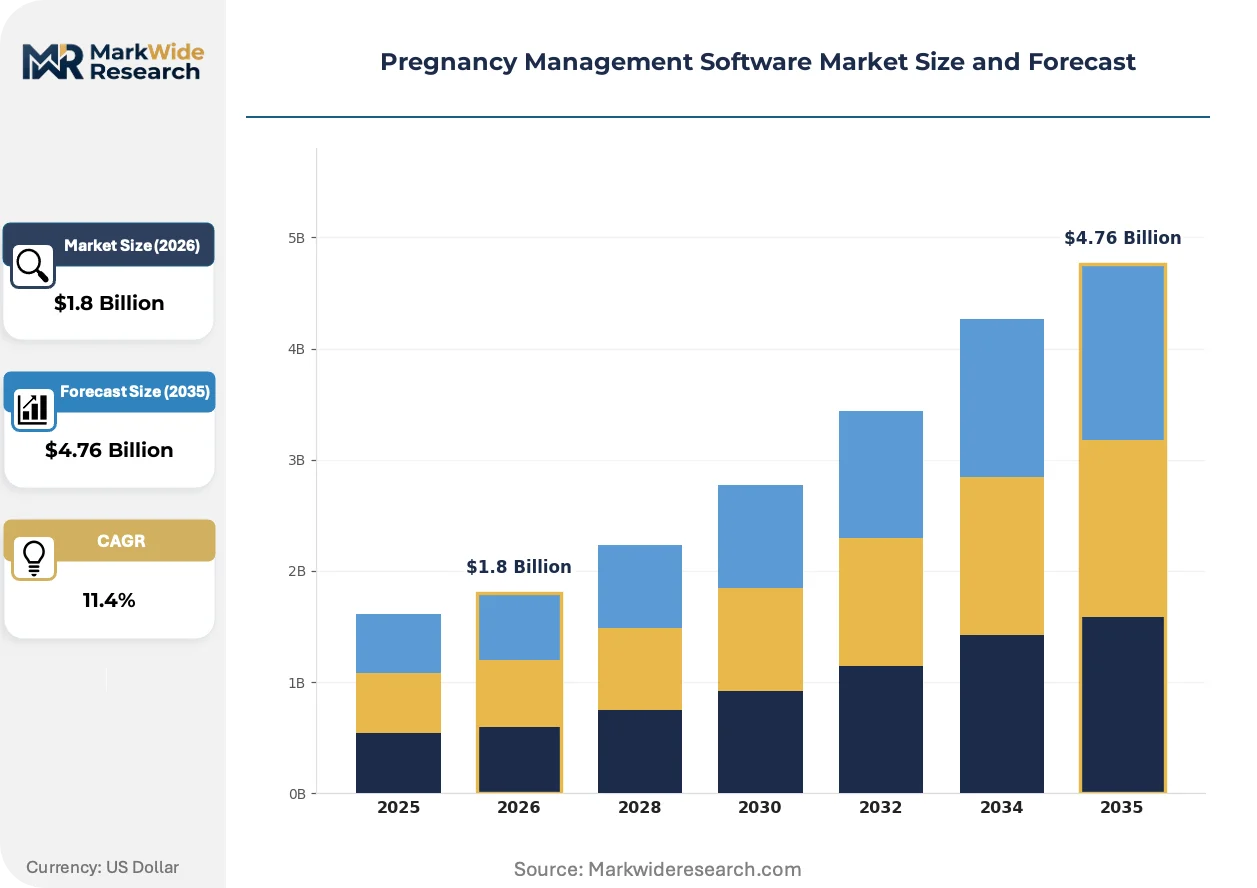
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Web Portals, Desktop Software, Wearable Devices End User: Clinics, Hospitals, Home Users, Healthcare Providers Functionality: Tracking, Education, Health Monitoring, Communication Technology: Cloud-Based, AI-Driven, Machine Learning, Data Analytics |
| Companies Covered | Cerner Corporation, Epic Systems Corporation, GE Healthcare, Philips Healthcare, Allscripts Healthcare Solutions, Athenahealth, PeriGen, Clinical Computer Systems, McKesson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pregnancy Management Software Market Trends and Innovations
Continuous glucose monitoring and non-invasive fetal electrocardiography hardware are generating real-time data streams that demand new cloud-native processing architectures. Vendors that capture and normalize these heterogeneous signals into actionable clinical intelligence are securing preferred vendor status in enterprise procurement cycles.
Artificial intelligence is digitizing maternal risk stratification by ingesting multi-parameter physiological data streams and surfacing early warning indicators hours or days before symptomatic presentation. Hospital systems with value-based maternity care contracts are adopting these predictive modules fastest, as risk-adjusted reimbursement directly rewards complication reduction. The technology is digitizing clinical decision support by compressing the interval between biometric anomaly detection and care team intervention.
The FDA's Software as a Medical Device guidance is tightening clinical validation requirements for algorithms that drive diagnostic or treatment decisions. Developers must now conduct prospective studies demonstrating analytical and clinical validity before entering commercial distribution. Maternal-fetal monitoring platforms with predictive capabilities face the steepest compliance burden, as these features trigger higher-risk classification thresholds.
Hospital procurement committees now bundle remote patient monitoring with enterprise EHR contracts, displacing standalone point solutions from vendor shortlists. Mid-sized clinics lacking internal IT integration capacity are consolidating purchasing around platforms with pre-built Epic or Cerner connectors. This concentration is most visible in the United States, where health system consolidation has reduced the number of independent purchasing entities by nearly half over the past decade.
Pregnancy Management Software Market Segmentation
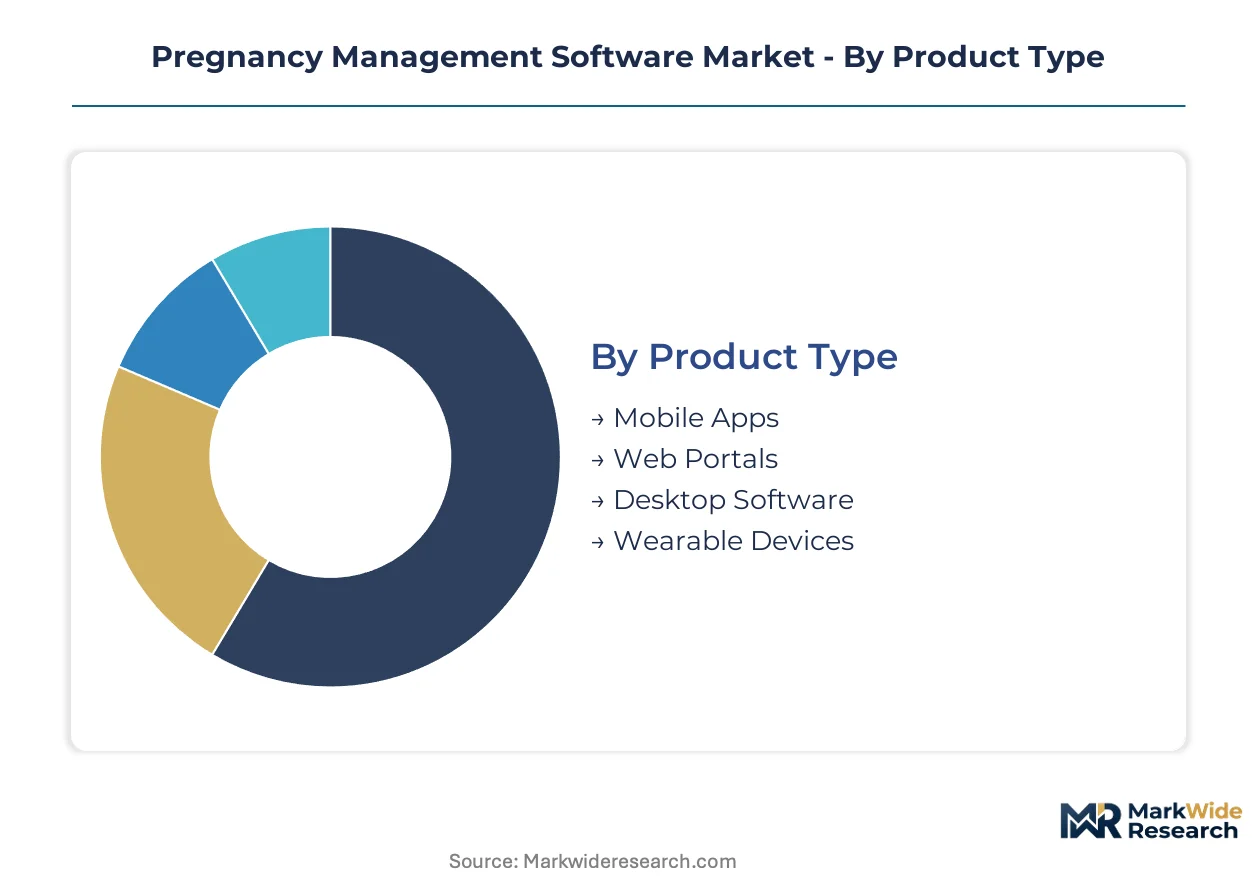
Pregnancy management software vendors architect go-to-market strategies around distinct deployment modes and user workflows. Segmentation reveals where subscription economics, clinical validation burdens, and integration complexity concentrate differentially across product categories.
Product Type:
After-sales service intensity varies sharply across product types, with hardware-enabled segments demanding field engineering support that software-only offerings avoid entirely.
- Cloud-Based:Subscription licensing models with automatic feature updates dominate hospital procurement cycles. United States health systems with value-based maternity contracts prioritize these deployments for remote patient monitoring integration.
- Wearable Devices:Connected hardware generating continuous biometric streams requires calibration, replacement logistics, and technical support infrastructure. Recurring data subscription revenue from these devices outperforms pure software licensing in customer lifetime value metrics.
- Mobile Apps:Consumer-facing interfaces with limited clinical validation requirements serve home users directly.
- Web Portals:Browser-based access accommodates mixed device environments in smaller clinic settings.
- Desktop Software:On-premise installations persist in security-sensitive hospital IT environments with restricted cloud connectivity.
By volume, Mobile Apps lead. By growth pace, Wearable Devices are climbing the fastest.
End User:
Customer procurement sophistication determines pricing tolerance and integration complexity, with enterprise buyers commanding bespoke professional services engagements.
- Hospitals:Enterprise EHR integration mandates consume vendor implementation capacity. Hospital systems in the United States bundle maternity platform procurement with existing Cerner or Epic contracts, displacing standalone vendors from shortlists.
- Clinics:Mid-sized obstetric practices lacking internal IT resources consolidate purchasing around pre-built interoperability connectors.
- Healthcare Providers:Individual physician practices prioritize mobile-first solutions with minimal training requirements.
- Home Users:Direct-to-consumer segments drive volume through app store distribution with limited clinical oversight.
By revenue concentration, Hospitals dominate. By expansion trajectory, Clinics are gaining share fastest.
Functionality:
Feature depth correlates directly with FDA SaMD classification risk, separating wellness-adjacent tools from regulated clinical decision support.
- Health Monitoring:Real-time physiological parameter tracking with predictive alerting triggers higher-risk regulatory classification. These modules attract premium pricing in value-based reimbursement environments.
- Tracking:Gestational milestone logging and appointment scheduling serve baseline coordination needs across all user segments.
- Education:Content libraries with limited diagnostic claims avoid clinical validation burdens entirely.
- Communication:Asynchronous messaging between patients and care teams enables scalable care coordination without continuous monitoring infrastructure.
By deployment frequency, Tracking leads. By investment intensity, Health Monitoring shows the steepest expansion trajectory.
Technology:
Underlying architecture choices determine scalability boundaries and regulatory compliance scope for platform developers.
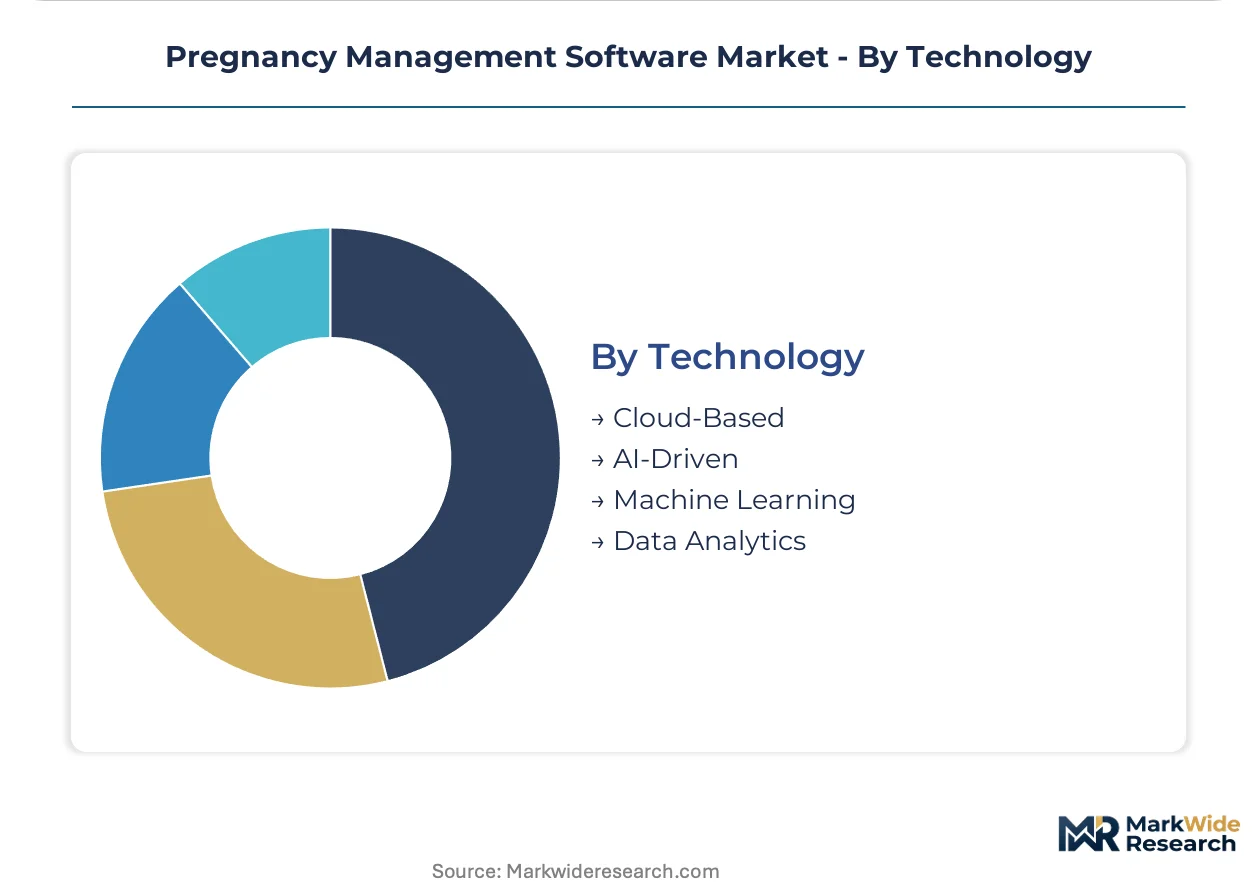
- AI-Driven:Machine learning algorithms for preeclampsia and preterm birth risk prediction embed into enterprise EHR workflows. FDA prospective study requirements for these features extend commercialization timelines but command premium subscription tiers.
- Machine Learning:Pattern recognition capabilities for fetal heart rate variability analysis require specialized training datasets and clinical validation protocols.
- Cloud-Based:Elastic infrastructure supports variable patient volumes without capital expenditure requirements.
- Data Analytics:Retrospective population health reporting serves quality improvement initiatives without real-time processing demands.
By current installed base, Cloud-Based deployments lead. By capital allocation, AI-Driven segments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade in pregnancy management software flows predominantly from the United States toward Europe and Asia-Pacific markets, with net exports concentrated in cloud-native platforms and AI-driven risk scoring modules. Import demand concentrates in jurisdictions building maternal health infrastructure where domestic development capacity remains limited.
United States
Hospital system consolidation and value-based maternity care contracts drive procurement of integrated EHR-native platforms. FDA Software as a Medical Device oversight tightens clinical validation requirements for predictive algorithms. The Boston-Cambridge corridor anchors venture capital flows into AI-driven maternal-fetal monitoring startups.
Germany
Digital Health Act reimbursement pathways accelerate adoption of remote patient monitoring for high-risk pregnancies. EMA medical device regulations align with FDA SaMD frameworks for cross-border platform certification. The Berlin-Brandenburg health tech cluster concentrates middleware development for HL7 FHIR interoperability.
United Kingdom
NHS Long Term Plan targets for reducing maternal health disparities expand procurement of risk stratification software. MHRA post-Brexit regulatory autonomy creates parallel validation requirements for US-developed platforms. London's digital health accelerators host European headquarters for North American maternity software vendors.
India
CDSCO medical device registration requirements for software-based maternal monitors create compliance barriers for imported platforms. National Health Mission digitization initiatives drive demand for low-cost mobile-first pregnancy tracking solutions. Bengaluru's health tech ecosystem produces indigenous cloud-based maternal care platforms for domestic and African export markets.
Japan
PMDA software medical device classification rules extend approval timelines for foreign pregnancy management platforms. METI subsidies for aging society healthcare technology support domestic development of remote maternal monitoring systems. Tokyo-Osaka hospital networks pilot AI-integrated obstetrics modules within existing EHR infrastructure.
Pregnancy Management Software Market Competitive Landscape
On the supply side, the industry is consolidating around enterprise EHR vendors with established hospital footprints, while specialized maternal-fetal monitoring developers occupy niche positions requiring deep clinical validation. Three strategic archetypes dominate: health record platform extenders leveraging existing EHR relationships, connected device manufacturers integrating biometric hardware with cloud analytics, and pure-play AI developers focusing on predictive risk algorithms. M&A activity concentrates on acquiring FDA-cleared algorithms and pre-built interoperability connectors, while strategic partnerships between device makers and cloud infrastructure providers accelerate platform deployment timelines.
Within the enterprise EHR extender tier, Cerner Corporation and Epic Systems Corporation occupy positions that exemplify platform consolidation dynamics, anchoring maternity workflow modules inside hospital procurement cycles. Philips Healthcare represents the connected device ecosystem archetype, bridging hardware-generated biometric streams with clinical dashboard integration. PeriGen exemplifies the specialized clinical decision support developer, sitting within the risk stratification niche where FDA SaMD compliance creates defensible competitive moats.
| Leading Market Players |
|---|
| Cerner Corporation |
| Epic Systems Corporation |
| GE Healthcare |
| Philips Healthcare |
| Allscripts Healthcare Solutions |
| Athenahealth |
| PeriGen |
| Clinical Computer Systems |
| McKesson Corporation |
| Others |
Pricing and Supply Chain Analysis
The San Francisco-Singapore transpacific data corridor carries cloud infrastructure costs that cascade through maternal-fetal monitoring platform pricing, concentrating margin pressure on vendors without captive server capacity while enabling premium subscription tiers for AI-validated risk scoring modules.
Pricing Analysis
Hospital procurement committees anchor pricing structure around three-tier SaaS subscription models across enterprise, mid-market, and clinic tiers. Price differentiation hinges on FDA SaMD certification grade and depth of Epic or Cerner pre-built integration. Cost compression in the mid-market tier is intensifying because Medicaid reimbursement rate variability forces vendors to absorb implementation risk. Federally Qualified Health Centers exhibit highest price sensitivity, while integrated delivery networks with value-based maternity contracts demonstrate lowest.
Supply Chain Analysis
Export control restrictions on GPU-accelerated cloud instances limit AI training capacity flows to certain jurisdictions, compressing supply availability for algorithm development. Hardware component sourcing concentrates in Taiwan, South Korea, and the United States for semiconductor fabrication. Raw material dependencies include specialized fetal monitoring sensors, medical-grade wearables substrates, and encrypted data transmission modules. Single-source vulnerability runs through Taiwan-based foundry capacity for edge-computing chips. Distribution runs through direct enterprise sales teams with professional services bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital systems that bundle maternity platform procurement with enterprise EHR contracts, squeezing standalone vendors from competitive shortlists.
For Market Incumbents: Build regulatory moats through prospective FDA SaMD clinical validation studies for preeclampsia prediction algorithms. Deepen backward integration into wearable device manufacturing to capture recurring data subscription revenue streams. Counter emerging AI-native entrants by accelerating Epic and Cerner connector certification timelines. Anchor professional services capacity in American South and Midwest regions where Medicaid expansion creates implementation backlogs. For New Entrants and Emerging Players: Pursue asynchronous telehealth modules for rural Federally Qualified Health Centers as the most penetrable white-space target. Target Federally Qualified Health Center networks in underserved American counties lacking internal IT integration resources. Develop lightweight mobile-first platforms with minimal EHR integration requirements. Capture initial revenue through direct-to-consumer channels before pursuing hospital procurement cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-sized AI developers holding FDA-cleared maternal-fetal monitoring algorithms but lacking enterprise distribution. Long-term viability centers on platforms with demonstrated outcome validation in value-based reimbursement environments. Monitor CMS maternity care episode payment pilot expansion as the critical inflection signal for integrated platform demand versus point solutions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA SaMD Submission | Prospective clinical validation unlocks reimbursable care pathways in hospital systems. |
| Epic Integration Partnership | Pre-built connector certification secures preferred vendor status in enterprise procurement. |
| Wearable Device Acquisition | Hardware-generated biometric streams enable recurring subscription revenue models. |
| Postpartum Module Extension | Twelve-month CMS monitoring window expands addressable contract duration beyond gestation. |
| Rural Health Network Deployment | Federally Qualified Health Center partnerships penetrate underrepresented geographic markets. |
Research Methodology
The analysis maps cloud-based deployments, wearable-enabled platforms, and AI-driven risk scoring modules, each validated through hospital procurement officers, biomedical informaticists, GPO contracts managers, and maternal-fetal medicine specialists. Primary intelligence combines structured interviews with secondary triangulation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and HL7 FHIR implementation guides. Bottom-up platform deployment estimates cross-validate against top-down health system IT spending aggregates.
Assumptions hold cloud infrastructure cost curves and state-level Medicaid remote monitoring reimbursement policies fixed across the projection horizon, while varying AI algorithm accuracy improvement rates and hospital consolidation trajectories. Segmentation dimensions include deployment architecture, end-user organization scale, functionality depth, and underlying technology type. CAGRs derive from logistic diffusion modeling of EHR-native platform adoption curves, calibrated against historical remote patient monitoring penetration patterns and FDA SaMD clearance velocity trends.
Macroeconomic conditions sit as an overlay; deviation in cloud computing input costs, healthcare labor availability, or federal maternity care reimbursement policy would shift the trajectory. Forecasts reflect these documented assumptions with acknowledged sensitivity to cybersecurity incident frequency and interoperability standard evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Medical Animation Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Cardiovascular Digital Solutions Market
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
VR in Healthcare Market
Digital Health Solutions
Smart Cards in Healthcare Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
Global Smart Hospital Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Mobile Tablets in Healthcare Market
Digital Health Solutions
Global Behavioral/Mental Health Software Market