
 Bariatric Lifts Market | 2026-2036
Bariatric Lifts Market Size, Share, and Industry Trends Forecast 2026-2036
Bariatric Lifts Market Outlook
Heavy-duty 600-lb to 1000-lb weight capacity tiers is rotating toward the center of procurement decisions in acute and post-acute settings. Stryker Corporation leverages its integrated bed-to-lift workflow systems to anchor premium positioning in hospital accounts. Invacare Corporation competes through specialized home care distribution networks that sustain recurring revenue streams. V. Guldmann A/S differentiates via ceiling-mounted track architecture that dominates European retrofit installations and extends into North American long-term care builds.
Bariatric lifts are powered or manually operated patient transfer devices engineered with reinforced chassis structures, extended sling attachment points, and dual-motor drive systems to safely mobilize patients exceeding standard weight thresholds, primarily serving injury prevention and dignity-preserving care protocols. Ceiling lifts command the largest installed base among product types due to permanent infrastructure attachment and reduced floor-space encumbrance, while mobile lifts represent the fastest-growing configuration for home care and rehabilitation center flexibility. Electric deployment models lead revenue contribution where staffing shortages amplify demand for single-caregiver operation, though hybrid units are gaining traction in budget-constrained long-term care facilities seeking pneumatic backup during power events.
FDA 510(k) premarket notification requirements govern powered lift safety validation in the United States, while IEC 60601-1 electrical safety standards and ISO 10535 sling integrity protocols shape international product acceptance and cross-border procurement eligibility. OSHA safe patient handling directives in US states and EU Machinery Directive 2006/42/EC compliance obligations in Europe collectively elevate replacement cycles and specification stringency. Stakeholders must monitor evolving reimbursement coding for bariatric-specific handling equipment across Medicare state plans and European national health technology assessment frameworks to anticipate demand inflection points.
Market Dynamics
Staffing shortages across acute and post-acute care settings are forcing facilities toward single-caregiver lift protocols, compressing procurement criteria toward electric deployment models with intuitive controls and fail-safe braking systems. This workforce pressure is restructuring competitive advantage around operational simplicity rather than raw lifting capacity.
Growth Catalysts
- OSHA Safe Patient Handling Directives:State-level mandates in California, New York, and Washington require comprehensive mechanical lift programs in hospitals, accelerating replacement of manual transfer methods with powered systems.
- Home Care Infrastructure:Medicaid waiver programs for aging-in-place services are expanding reimbursement eligibility for residential bariatric equipment, opening new addressable demand outside institutional settings.
- Dual-Motor Architecture:Redundant drive systems with independent left-right motors enable safer patient rotation and level lifting, becoming a non-negotiable specification in 600-lb plus capacity tiers.
Market Restraints
- Steel and Aluminum Input Volatility:Reinforced chassis fabrication depends on commodity metals whose price swings compress margin visibility for manufacturers operating on fixed hospital contract terms.
- Ceiling Track Retrofit Friction:Existing acute care facilities face structural engineering assessments and infection-control downtime that extend installation timelines beyond capital budget cycles.
- Manual Lift Substitution:Budget-constrained long-term care operators in rural markets continue deploying gait belts and slide boards for sub-400-lb patients, limiting addressable market penetration.
Strategic Opportunities
- Hybrid Power Systems:Pneumatic-electric backup configurations address grid reliability concerns in hurricane-prone Gulf Coast states and remote Mountain West facilities.
- Telehealth-Integrated Monitoring:Load cell sensors with wireless connectivity enable remote usage tracking and predictive maintenance contracts, shifting revenue toward recurring service models.
- Indian Long-Term Care Buildout:National Health Mission investments in tier-2 and tier-3 city geriatric facilities create first-mover positioning for mobile lift suppliers establishing local distribution.
Industry Challenges
- Biomechanical Specialist Shortage:Safe patient handling program implementation requires certified ergonomists whose training pipeline has not scaled with facility demand, delaying protocol rollout.
- Legacy Sling Inventory Stranding:Proprietary attachment geometries from 1990s-era installations create compatibility barriers that complicate upgrade paths and inflate total replacement costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bariatric Lifts Market |
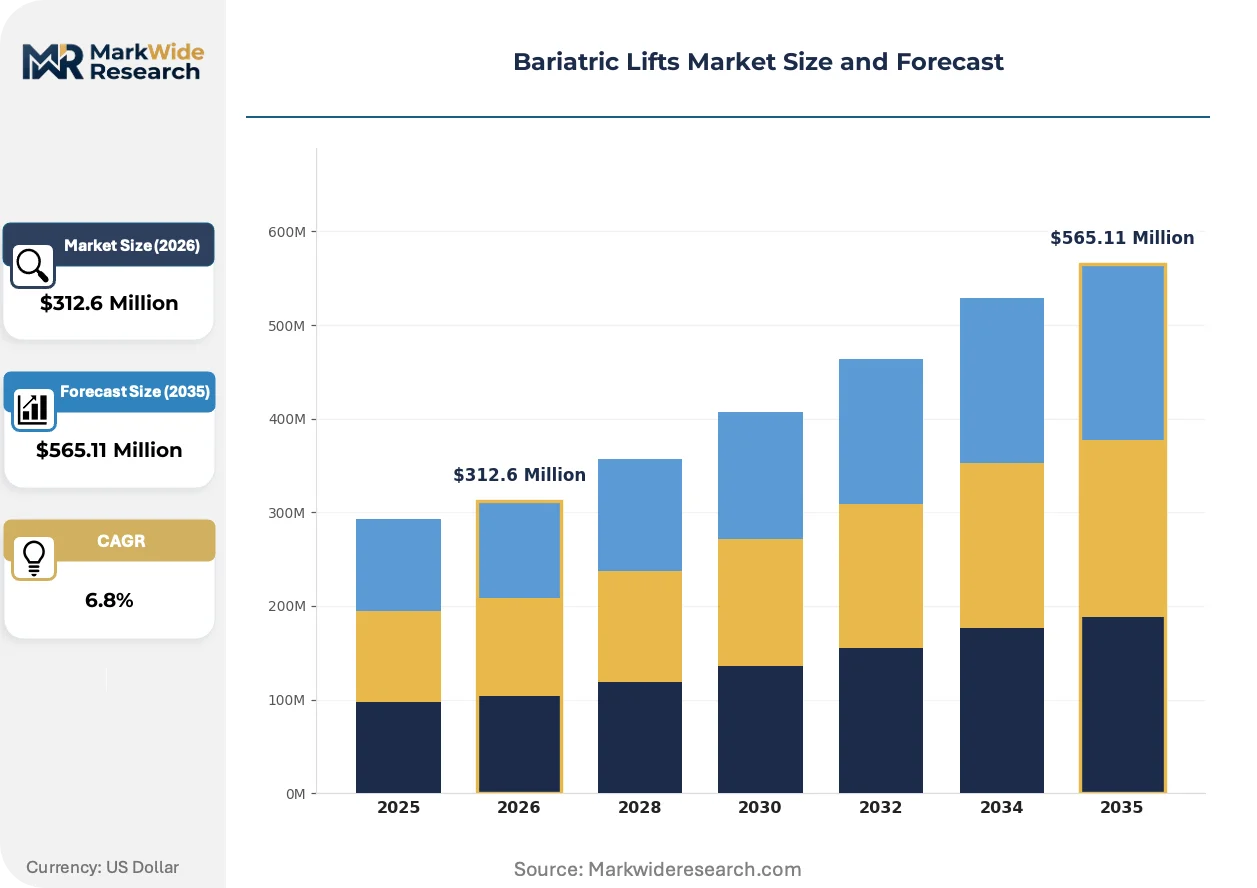
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceiling Lifts, Mobile Lifts, Floor Lifts, Stand-Up Lifts End User: Hospitals, Home Care, Rehabilitation Centers, Long-Term Care Facilities Weight Capacity: 400 lbs, 600 lbs, 800 lbs, 1000 lbs Deployment Model: Manual, Electric, Hybrid, Pneumatic |
| Companies Covered | Stryker Corporation, Invacare Corporation, Arjo, Hillrom, Joerns Healthcare, Savaria Corporation, Drive DeVilbiss Healthcare, V. Guldmann A/S, Human Care Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bariatric Lifts Market Strategic Shifts
Intelligent load-sensing and predictive maintenance capabilities are redefining equipment lifecycle economics, compressing the traditional ten-year replacement cycle and opening subscription-based revenue streams for manufacturers willing to restructure around uptime guarantees rather than unit sales.
Lithium iron phosphate battery chemistry is supplanting sealed lead-acid power systems in mobile lift configurations. Home health agencies and outpatient rehabilitation centers are adopting these lighter, faster-charging units to enable same-day multi-patient deployment without mid-shift charging interruptions. The technology is supplanting legacy power architectures that required dedicated charging stations and extended downtime, collapsing facility infrastructure requirements and expanding addressable use cases to community-based settings without permanent electrical upgrades.
EU Machinery Directive 2006/42/EC compliance deadlines are forcing recertification of legacy installations across German, French, and Italian acute care networks. The regulation mandates updated emergency-stop functionality and obstacle-detection sensors that trigger automatic halt protocols. Ceiling lift systems with permanent infrastructure attachment face the most concentrated compliance burden, driving replacement demand in European retrofit markets while creating specification divergence between EU-certified and North American product lines.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships for independent nursing homes and assisted living operators. Multi-facility health systems in Texas, Florida, and Pennsylvania are centralizing bariatric equipment decisions under supply chain executives who prioritize standardization and volume leverage over site-specific customization. The purchasing pattern is most visible in for-profit post-acute chains where CFO oversight of capital equipment has intensified following reimbursement compression in skilled nursing facility payment models.
Bariatric Lifts Market Segmentation
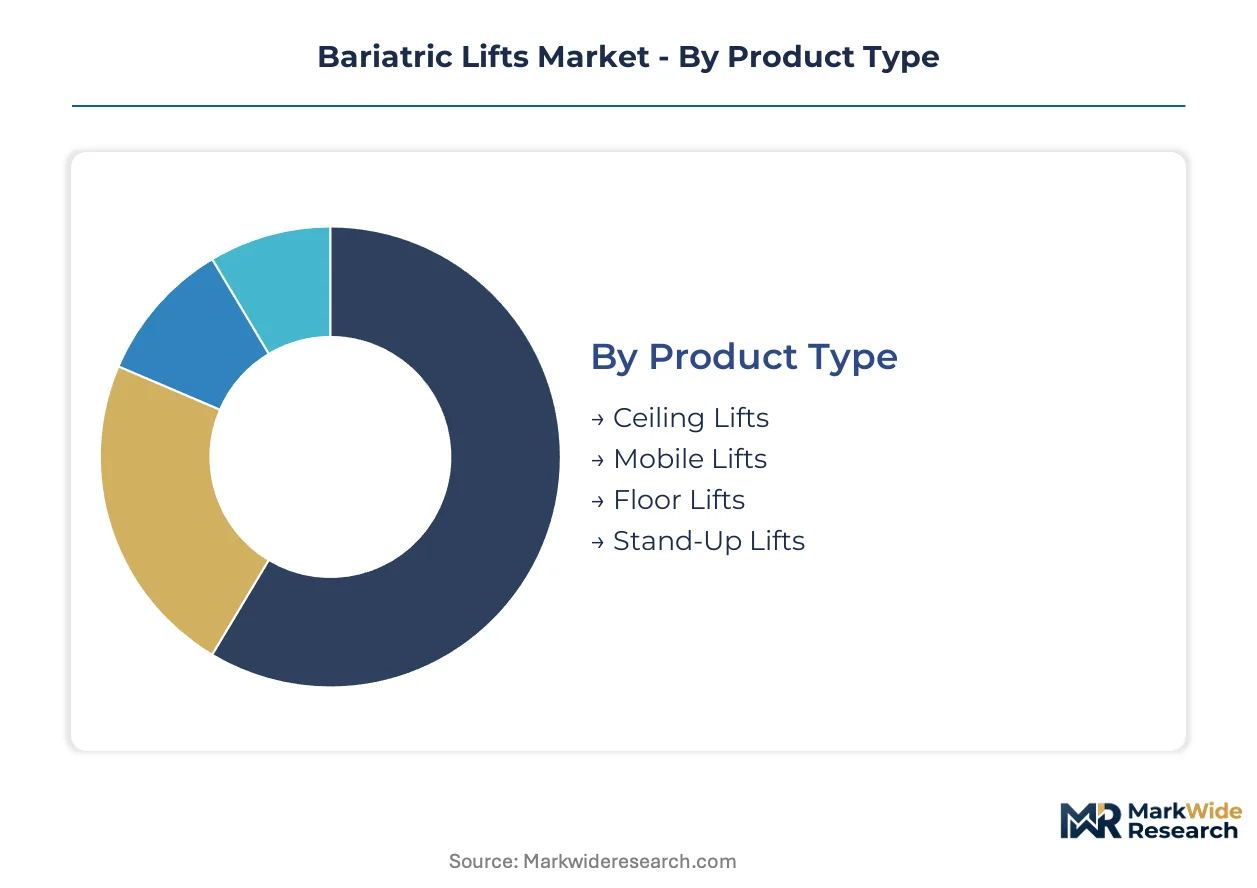
Bariatric lift procurement follows distinct technical and economic logics across facility types. Specification divergence between acute care infrastructure investments and home care mobility requirements creates tiered margin pools that reward targeted portfolio architecture.
Product Type:
Ceiling-mounted systems command premium pricing through permanent structural integration, while mobile configurations compete on flexibility economics.
- Ceiling Lifts:Permanent track systems with overhead motor housings eliminate floor obstruction and enable full-room coverage. German, French, and Italian acute care networks are replacing legacy installations under EU Machinery Directive recertification deadlines, concentrating demand in European retrofit markets.
- Mobile Lifts:Wheeled chassis with rechargeable power systems enable deployment across multiple patient rooms. Home health agencies in Texas, Florida, and Pennsylvania are adopting lithium iron phosphate battery units for same-day multi-patient routing without charging downtime.
- Floor Lifts:Stationary base-plate designs anchor to structural floor points for high-capacity lifting in bariatric surgery recovery units.
- Stand-Up Lifts:Sling-to-vest transfer mechanisms support partial-weight-bearing rehabilitation protocols in outpatient settings.
Ceiling Lifts holds installed capacity. Mobile Lifts is rotating up the share rankings.
End User:
Reimbursement coding and capital budget cycles create divergent purchasing rhythms across care settings.
- Hospitals:Integrated bed-to-lift workflow systems with centralized nurse station controls dominate capital planning. OSHA safe patient handling directives in California, New York, and Washington mandate comprehensive mechanical lift programs, accelerating replacement of manual transfer methods.
- Long-Term Care Facilities:For-profit post-acute chains in Texas and Pennsylvania are consolidating procurement through group purchasing organizations, prioritizing standardization over site-specific customization.
- Home Care:Medicaid waiver programs for aging-in-place services are expanding reimbursement eligibility for residential equipment, opening addressable demand outside institutional settings.
- Rehabilitation Centers:Outpatient facilities require rapid deployment capabilities for variable patient census without permanent infrastructure commitment.
Hospitals anchor premium specification. Home Care is climbing the fastest.
Weight Capacity:
Capacity tier selection reflects patient acuity trajectories and liability exposure calculus.
- 600 lbs:Dual-motor architecture with independent left-right drive systems has become standard specification in acute and post-acute settings. Redundant motors enable safer patient rotation and level lifting under uneven load distribution.
- 1000 lbs:Reinforced chassis fabrication with extended sling attachment points serves bariatric surgery units and specialized wound care centers. Steel and aluminum input volatility compresses margin visibility for manufacturers on fixed hospital contract terms.
- 400 lbs:Entry-tier capacity serves budget-constrained rural long-term care operators who continue deploying gait belts for sub-threshold patients.
- 800 lbs:Mid-tier specification bridges standard bariatric and extreme-morbidity patient populations in tertiary referral centers.
600 lbs holds installed capacity. 1000 lbs is rotating up the share rankings.
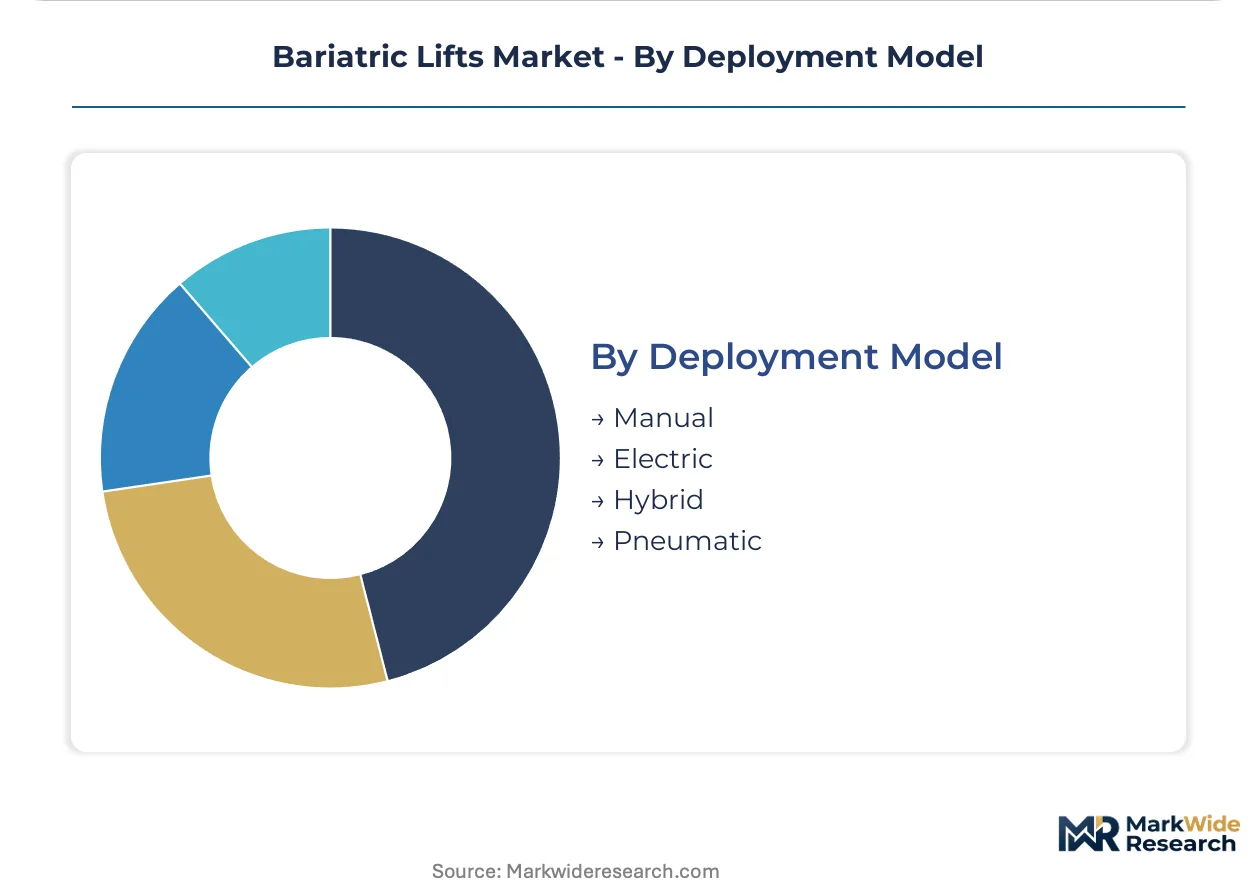
Deployment Model:
Power architecture selection tracks staffing availability and grid reliability risk profiles.
- Electric:Intuitive single-caregiver controls with fail-safe braking systems dominate where workforce shortages compress staffing ratios. Lithium iron phosphate battery chemistry is supplanting sealed lead-acid systems in mobile configurations for faster charging and lighter weight.
- Hybrid:Pneumatic-electric backup configurations address grid reliability concerns in hurricane-prone Gulf Coast states and remote Mountain West facilities. Budget-constrained long-term care operators value redundancy without full dual-system cost.
- Manual:Hydraulic pump mechanisms persist in low-utilization settings with predictable patient census and available staff assistance.
- Pneumatic:Compressed-air drive systems serve facilities with existing medical gas infrastructure and specific infection-control requirements.
Electric holds installed capacity. Hybrid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of powered patient handling equipment clusters in the United States, Germany, and Denmark, with assembly operations concentrated near major medical device regulatory hubs. Facility investment patterns track reimbursement policy divergence across national health systems.
United States
Medicare reimbursement for safe patient handling programs drives hospital capital expenditure in Texas, Florida, and Pennsylvania. OSHA state-level mandates in California, New York, and Washington require comprehensive mechanical lift programs. The Gulf Coast corridor sees hybrid power system adoption addressing hurricane-season grid reliability.
Germany
EU Machinery Directive 2006/42/EC recertification deadlines force replacement of legacy ceiling installations in acute care networks. BSI standards alignment shapes procurement specifications for reinforced chassis fabrication. The North Rhine-Westphalia medical technology cluster anchors retrofit demand concentration.
Denmark
Ceiling-mounted track architecture dominates European long-term care builds, with design engineering concentrated in Copenhagen-area facilities. IEC 60601-1 electrical safety compliance shapes export eligibility to German and French markets. Nordic welfare state procurement standardization accelerates replacement cycles.
Japan
Aging demographics compress staffing ratios in Tokyo and Osaka metropolitan hospitals toward single-caregiver electric protocols. METI industrial standards govern lithium iron phosphate battery integration in mobile configurations. The Chubu region medical device manufacturing base supplies domestic rehabilitation center expansion.
India
National Health Mission investments in tier-2 and tier-3 city geriatric facilities create first-mover positioning for mobile lift distribution. CDSCO medical device regulation harmonization with ISO 10535 sling integrity protocols shapes import eligibility. Maharashtra and Karnataka hospital buildouts concentrate procurement activity.
Bariatric Lifts Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the bariatric lifts landscape. Integrated bed-to-lift workflow specialists command premium positioning in hospital accounts, while specialized home care distributors sustain recurring revenue through service network density. The market structure rewards three strategic archetypes: infrastructure-anchored ceiling system providers, flexible mobile configuration specialists, and full-line patient handling conglomerates. Competitive moves concentrate on regulatory pre-certification investments and GPO consolidation capture.
Among North American full-line providers, Stryker Corporation and Invacare Corporation occupy positions at opposite ends of the care continuum archetype spectrum, with the former anchoring acute care infrastructure integration and the latter exemplifying home care distribution network density. V. Guldmann A/S represents the European engineering-specialist archetype, with Danish origin signaling ceiling-mounted track architecture concentration. These three entities collectively illustrate how geographic regulatory proximity and end-user segment focus determine sustainable margin capture.
| Leading Market Players |
|---|
| Stryker Corporation |
| Invacare Corporation |
| Arjo |
| Hillrom |
| Joerns Healthcare |
| Savaria Corporation |
| Drive DeVilbiss Healthcare |
| V. Guldmann A/S |
| Human Care Group |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at 600-lb to 1000-lb tier manufacturers in the United States and Denmark concentrates pricing power among dual-motor architecture specialists, while steel and aluminum input volatility compresses margin floors for fixed-contract hospital suppliers. This scale concentration forces tiered pricing stratification across premium FDA 510(k) cleared systems, standard IEC 60601-1 compliant units, and economy manual configurations serving rural long-term care operators.
Pricing Analysis
FDA 510(k) clearance requirements dictate the pricing tier structure across premium, standard, and economy levels. Premium electric ceiling systems with integrated nurse station controls command sustained margins through reimbursement eligibility under Medicare safe patient handling programs, while standard mobile lifts compete on lithium iron phosphate battery specifications and charging speed. Cost compression in the 400-lb entry tier is intensifying because rural long-term care operators substitute gait belts for mechanical transfers, making home care agencies the least price-sensitive segment due to Medicaid waiver program coverage.
Supply Chain Analysis
Inventory lead times for reinforced chassis components extend beyond capital budget cycles at acute care facilities pursuing EU Machinery Directive recertification. Manufacturing clusters in the United States, Germany, and Denmark anchor component fabrication, with steel and aluminum sheet metal and lithium iron phosphate battery cells feeding final assembly. Single-source vulnerability concentrates in ceiling track structural engineering assessments, while distribution runs through group purchasing organizations consolidating multi-facility health system procurement in Texas, Florida, and Pennsylvania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bariatric lifts market functions as a defensive-moat sector where regulatory entrenchment through FDA 510(k) clearance and ISO 10535 sling certification creates durable switching costs that protect incumbent positioning.
For Market Incumbents: Consolidate GPO relationship capture in for-profit post-acute chains and invest in telehealth-integrated load cell monitoring to shift revenue toward predictive maintenance subscriptions. The threat of lithium iron phosphate battery commoditization from Asian suppliers demands backward integration into power system assembly or exclusive chemistry partnerships to defend margin structure. For New Entrants and Emerging Players: Lead with hybrid pneumatic-electric configurations targeting hurricane-prone Gulf Coast states and remote Mountain West facilities where grid reliability concerns remain underserved. The Indian tier-2 and tier-3 city geriatric facility buildout under National Health Mission investments represents the most penetrable geography, with CDSCO harmonization creating import eligibility for ISO 10535 certified entrants establishing local distribution partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ceiling-mounted track architecture providers with installed base density enabling service contract attachment. Long-term viability over the projection horizon favors acquisition targets with European retrofit market positioning under EU Machinery Directive compliance deadlines, with the signal to watch being reimbursement coding expansion for bariatric-specific handling equipment across Medicare state plan variations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance anchors premium pricing eligibility under Medicare reimbursement protocols. |
| Hospital System Partnership | Integrated bed-to-lift workflows secure multi-year capital equipment commitments. |
| Software Companion Development | Load cell telematics enable predictive maintenance subscription revenue conversion. |
| Reimbursement Strategy | Medicaid waiver program alignment opens residential home care addressable demand. |
| CE Marking Pathway | EU Machinery Directive compliance captures German and French retrofit replacement cycles. |
Study Parameters
Operator-level perspectives from hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and home health agency operations leads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) premarket notification databases, CMS Medicare reimbursement coding records, hospital procurement contract registries, and EU Machinery Directive compliance filings. Bottom-up unit demand modeling triangulated against top-down facility investment flow analysis across acute care, long-term care, and home care settings.
Sensitivity analysis across the analysis window tested volume and value outputs against variable input assumptions for steel and aluminum commodity pricing, lithium iron phosphate battery cost curves, and Medicare state plan reimbursement expansion timing. Segmentation dimensions modeled encompassed product type, end user facility category, weight capacity tier, and deployment power architecture. CAGRs were derived from facility bed stock growth projections, replacement cycle compression from intelligent load-sensing capabilities, and regulatory recertification mandate impacts on European retrofit demand.
Underlying assumptions cover OSHA safe patient handling directive enforcement continuity, EU Machinery Directive compliance deadline adherence, and Medicare reimbursement policy stability, with deviation risk concentrated in commodity metals price volatility and Medicaid waiver program state-level variation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Bariatric Rollator Walkers Market
Bariatric Surgery
Global Bariatric Walking Aids Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
North America Bariatric Surgery Devices Market
Bariatric Surgery
Chile Bariatric Surgery Market
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market
Bariatric Surgery
Australia Bariatric Surgery Market
Bariatric Surgery
Mexico Bariatric Surgery Market
Bariatric Surgery
Bariatric Walkers Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
China Bariatric Surgery Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
Japan Bariatric Surgery Market
Bariatric Surgery
Brazil Bariatric Surgery Market