
 Lentil Market | 2026-2036
Lentil Market Size, Share, and Industry Trends Forecast 2026-2036
Lentil Market Intelligence
The price gap between premium-grade organic lentils and commodity bulk supply is hardening as buyers enforce stricter protein content and defect thresholds. AGT Food and Ingredients leverages its vertically integrated processing network across Saskatchewan and Turkey to sustain consistent quality premiums. Cargill anchors North American origination through direct farmer contracting programs that dominate the Plains corridor.
Lentils are edible seeds of Lens culinaris, a cool-season legume containing approximately 25-30% protein by dry weight and requiring specific rhizobium inoculation for nitrogen fixation in semi-arid soils. Green lentils retain their shape during cooking and command premium positioning in European retail channels, while red lentils, processed through decortication and splitting, lead volume growth in South Asian food manufacturing where dal production consumes the majority of imports. The nutraceutical segment extracts concentrated protein isolates for sports nutrition applications, though this remains a margin pool rather than a volume driver.
Health Canada enforces maximum residue limits for glyphosate and other crop chemicals that directly determine export eligibility for Canadian originators. India's Food Safety and Standards Authority mandates strict aflatoxin and foreign matter thresholds that filter which suppliers access government buffer stock tenders. Stakeholders must monitor how climate volatility in the Northern Plains and Australian winter cropping zones reshapes origination reliability without assuming geographic supply stability.
Market Dynamics
Protein content standardization is hardening into the decisive competitive filter across lentil procurement, with buyers enforcing minimum thresholds that disqualify legacy bulk supply and reward precision agriculture investment.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory sustainability disclosures for imported legumes are redirecting procurement toward certified low-carbon originators who can document nitrogen-fixing crop rotation.
- Decortication technology:Advanced splitting and polishing equipment is expanding red lentil processing capacity in Turkey and India, enabling finer grade segregation for dal manufacturers.
- India:Government buffer stock tenders through FCI procurement channels are anchoring minimum volume guarantees that stabilize farmer planting decisions.
Market Restraints
- Glyphosate residue thresholds:Health Canada and EU EFSA maximum residue limits create non-tariff barriers that block conventional Canadian shipments from premium European retail channels.
- Prairie drought cycles:Saskatchewan and Alberta concentration exposes origination reliability to soil moisture volatility that compresses protein consistency year-to-year.
- Pulse protein isolates:Pea and fava protein extraction technologies are capturing sports nutrition formulation share that lentils have failed to penetrate.
Strategic Opportunities
- Southeast Asian food manufacturing:Bangladesh and Myanmar milling sectors remain underdeveloped for green lentil dehulling, creating first-mover space for equipment-and-grain integrated supply.
- FSSAI aflatoxin protocols:India's tightening mycotoxin surveillance is disqualifying African and marginal originators, opening tender access for compliant Australian and Canadian suppliers.
- Direct-to-retail traceability platforms:Blockchain-enabled lot tracking is bypassing traditional exporter-aggregator layers in European organic channels.
Industry Challenges
- Rhizobium strain specificity:Matching inoculant variants to local soil microbiomes requires agronomic expertise scarce in expanding production zones like Kazakhstan and Ukraine.
- Organic transition timelines:Three-year certification periods lock land out of premium pricing before revenue premiums materialize, straining farmer cash flow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lentil Market |
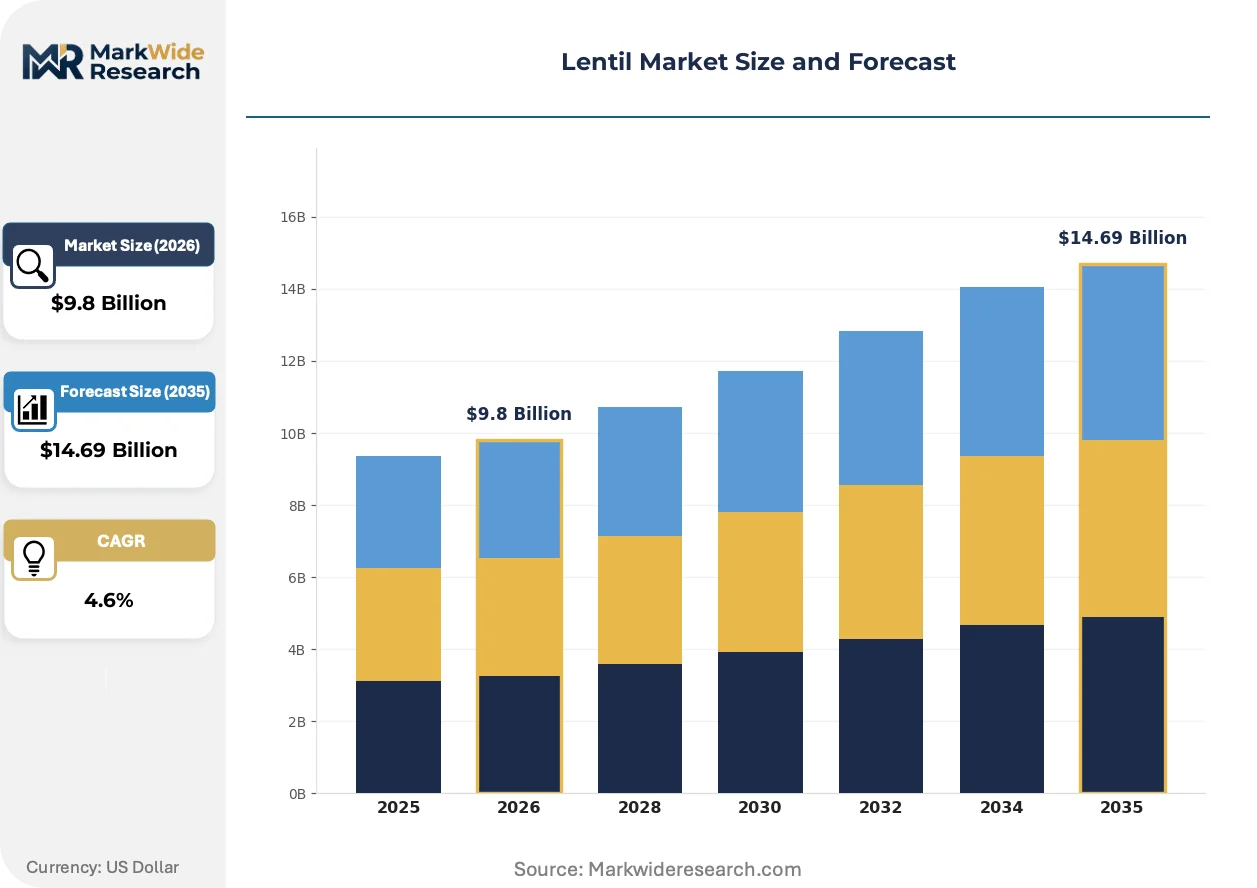
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Lentils, Red Lentils, Yellow Lentils, Black Lentils End User: Food Industry, Feed Industry, Nutraceuticals, Retail Consumers Packaging Type: Bags, Cans, Bulk Containers, Vacuum Packs Distribution Channel: Supermarkets, Online Retail, Wholesalers, Specialty Stores |
| Companies Covered | TOO Atameken Agro Trade, North Pulse Traders, OOO Volgatrade, AGT Food and Ingredients, Great Grains Group USA, TOO ARS Trading, Orient Exports P Ltd, Cargill, Tasty Bite Eatables Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lentil Market Strategic Shifts & Innovations
Precision sorting and digital traceability are converging to restructure how lentil quality is verified and priced, displacing visual inspection with objective biochemical measurement.
Near-infrared spectroscopy is overtaking manual grading at primary elevators, enabling real-time protein and moisture quantification that determines immediate price tier placement. Large European retailers and South Asian millers are mandating NIR certificates for contract eligibility, compressing acceptance windows for borderline shipments. This technology is overtaking traditional density-based cleaning as the gatekeeper for premium positioning.
Canada's PMRA is tightening glyphosate pre-harvest application windows, forcing Prairie farmers to adopt desiccation alternatives like diquat or swathing that alter seed coat integrity. The policy is fragmenting export eligibility between conventional and reduced-chemical supply streams. European importers are responding with dual-sourcing strategies that segregate Canadian shipments by desiccation protocol.
Spot market purchasing by Indian dal processors is yielding to forward contracting with designated originators who guarantee FSSAI-compliant aflatoxin documentation. This behavior change is concentrating procurement relationships around vertically integrated exporters with in-house laboratory capacity. The shift is most visible in Mumbai and Chennai processing clusters where government tender participation now requires pre-qualified supplier registries.
Lentil Market Segmentation
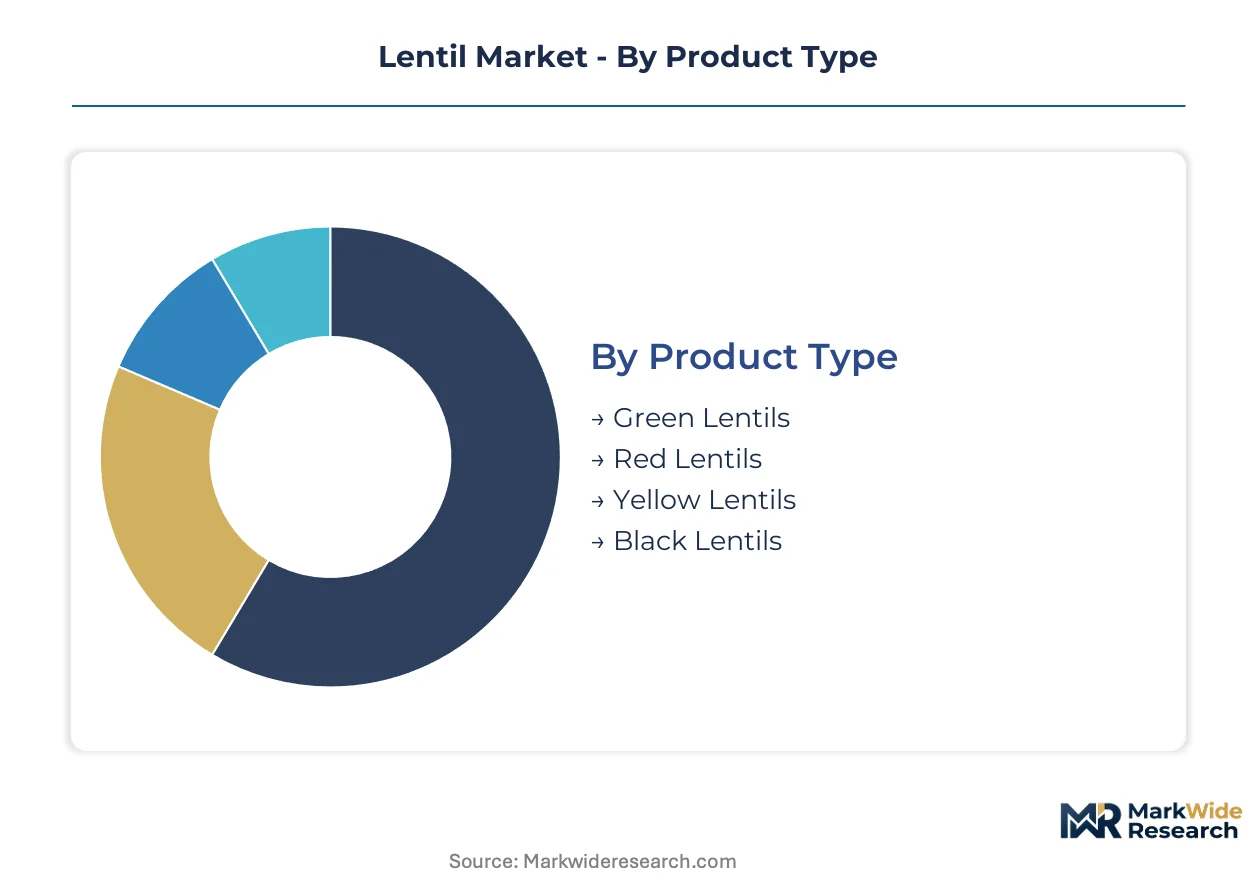
Segmentation in the lentil market tracks how protein content thresholds, processing requirements, and certification standards fragment procurement across distinct supply streams. Buyers now enforce grade-specific contracts that align product type with end-use application and channel positioning.
Product Type:
Upgrade cycles in lentil processing equipment are widening the quality gap between whole-seed and split-seed categories as precision sorting technology penetrates primary elevators.
- Green Lentils:These whole-seed varieties retain their lens shape through cooking and carry 24-28% protein by dry weight with firm texture profiles. European retail channels in France and Germany concentrate demand for certified organic green lentils where EFSA glyphosate limits filter conventional supply. Saskatchewan and Alberta farmers command premiums through identity-preserved contracts with Swiss and Dutch importers.
- Red Lentils:Decorticated and split through advanced milling equipment, these varieties dominate South Asian dal production with faster cooking times and softer texture. Bangladesh and Myanmar food manufacturers drive volume growth as these markets expand processing capacity beyond traditional Indian mill clusters. Turkish splitting facilities in Anatolia now compete with Indian processors for red lentil origination.
- Yellow Lentils:Similar decortication processing yields a milder flavor profile preferred in Middle Eastern cuisine applications.
- Black Lentils:Smaller seed size and distinctive caviar-like appearance command niche positioning in North American specialty food channels.
Volume placements concentrate in Red Lentils; the faster expansion belongs to Green Lentils.
End User:
Cost tier stratification separates commodity bulk supply from certified premium streams as procurement specifications harden across buyer categories.
- Food Industry:Dal manufacturers, canning operations, and plant-based meat formulators consume the majority of traded volume with strict protein minimums and defect thresholds. Indian FSSAI buffer stock tenders anchor procurement volumes for government distribution programs. European pulse processors increasingly demand nitrogen-fixing crop rotation documentation under EU Farm to Fork Strategy compliance requirements.
- Retail Consumers:Organic and heritage variety demand in urban centers drives premium pricing for traceable lot-specific supply. Direct-to-consumer platforms in Toronto, London, and Sydney bypass traditional exporter-aggregator layers through blockchain-enabled verification. Health Canada maximum residue limits determine which Canadian originators access this channel.
- Feed Industry:Ruminant and aquaculture feed formulations utilize lower-grade screenings and broken seeds excluded from food channels.
- Nutraceuticals:Protein isolate extraction for sports nutrition applications remains a margin-focused segment with limited volume scale.
Procurement volumes cluster in Food Industry; Retail Consumers show the steepest expansion trajectory.
Packaging Type:
Application requirements dictate packaging selection as shelf-life demands and handling economics diverge across customer types.
- Bulk Containers:Food manufacturers and institutional buyers favor 1-2 metric ton flexible intermediate bulk containers for cost-efficient handling at scale. Australian and Canadian export terminals load ocean freight in bulk for Indian and Turkish mill reception. Fumigation and moisture control specifications vary by destination port requirements.
- Vacuum Packs:Extended shelf-life packaging captures organic and specialty retail premiums through oxygen barrier protection against rancidity. European supermarket chains in Germany and Austria mandate vacuum packaging for private-label organic lines. The format supports longer distribution cycles for landlocked Central Asian markets.
- Bags:Standard woven polypropylene remains the default for commodity trade with printed lot codes for traceability.
- Cans:Precooked and ready-to-eat formats serve emergency food assistance and military procurement channels.
Shipment volumes concentrate in Bulk Containers; Vacuum Packs gain share fastest in premium channels.
Distribution Channel:
Customer type fragmentation is restructuring channel economics as procurement centralization in food manufacturing contrasts with retail fragmentation.
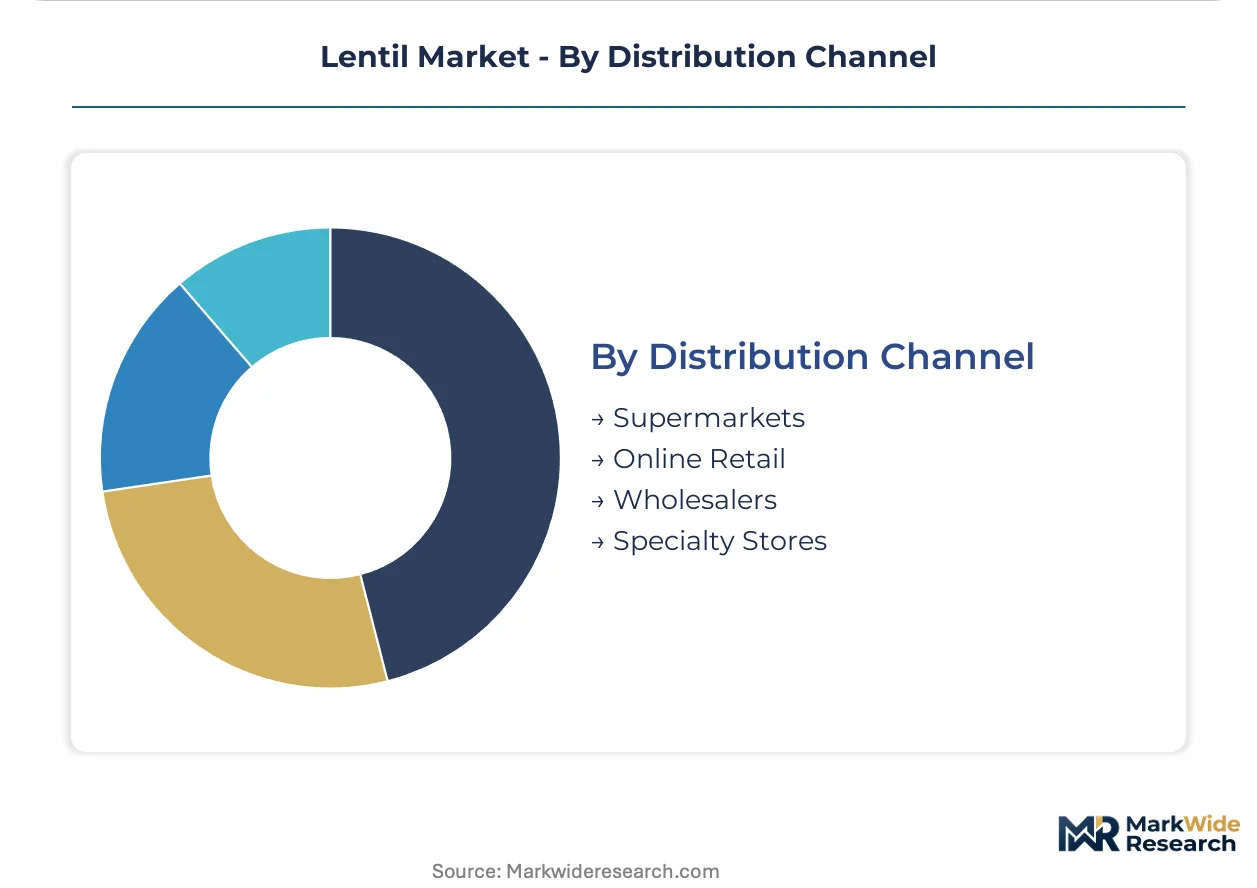
- Wholesalers:Traditional aggregator-exporters in Mumbai, Mersin, and Melbourne maintain dominance in South Asian and Middle Eastern volume trade. These intermediaries consolidate smallholder supply for mill-scale buyers and manage FSSAI and EFSA compliance documentation. Relationship-based credit terms sustain their position despite traceability platform disruption in premium tiers.
- Online Retail:Direct-to-consumer platforms and B2B procurement marketplaces are capturing specialty and organic segments through lot-specific transparency. Indian e-grocery expansion in Bangalore and Hyderabad creates new origination-to-pantry pathways for branded dal suppliers. European organic buyers increasingly bypass wholesalers for blockchain-verified direct contracts.
- Supermarkets:Mass retail chains in France, Canada, and Australia drive standard-grade packaged lentil volumes with private-label concentration.
- Specialty Stores:Ethnic grocery and health food channels serve diaspora communities and clean-label consumers with heritage varieties.
Transaction volumes concentrate in Wholesalers; Online Retail climbs fastest in organic and specialty tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saskatchewan's Prairie corridor dominates lentil origination, with Regina and Saskatoon processing clusters anchoring Canadian export capacity for European and South Asian destinations.
Canada
Domestic consumption and government procurement through the Canadian Grain Commission sustain prairie planting volumes. Health Canada PMRA tightening of glyphosate pre-harvest windows is fragmenting export eligibility between conventional and reduced-chemical supply streams. Saskatchewan's elevator network near Moose Jaw and Swift Current deploys near-infrared spectroscopy for real-time protein grading that determines price tier placement.
India
Government buffer stock tenders through FCI procurement channels anchor minimum volume guarantees that stabilize farmer planting decisions. FSSAI aflatoxin and foreign matter thresholds filter which suppliers access government distribution programs. Mumbai and Chennai processing clusters now require pre-qualified supplier registries for tender participation, concentrating procurement around vertically integrated exporters with in-house laboratory capacity.
Turkey
Red lentil splitting demand from Bangladesh and Myanmar food manufacturers drives Anatolian processing expansion. Turkish splitting facilities in Gaziantep and Mersin compete with Indian processors for origination, enabled by advanced decortication and polishing equipment. Mersin port infrastructure supports bulk container shipments to Middle Eastern and South Asian mill reception points.
Australia
FSSAI-compliant aflatoxin documentation opens tender access for Australian suppliers as India's mycotoxin surveillance tightens. Winter cropping zones in Victoria and South Australia face climate volatility that reshapes origination reliability without assuming geographic supply stability. Port Adelaide and Melbourne export terminals load ocean freight for Indian government buffer stock channels.
France
EFSA glyphosate maximum residue limits filter conventional Canadian supply from premium European retail channels. EU Farm to Fork Strategy mandatory sustainability disclosures redirect procurement toward certified low-carbon originators who document nitrogen-fixing crop rotation. Paris and Lyon retail clusters drive certified organic green lentil premiums through identity-preserved contracts with Swiss and Dutch importers.
Lentil Market Key Industry Players
Premium-margin players sit above commodity-margin players across protein consistency and certification documentation, with quality-tier stratification hardening into the decisive competitive filter. The vendor base spans vertically integrated processors with in-house laboratory capacity, regional aggregator-exporters managing FSSAI and EFSA compliance documentation, and commodity traders consolidating smallholder supply for mill-scale buyers. Strategic archetypes include precision agriculture investors capturing protein premiums, splitting equipment operators expanding red lentil processing capacity, and blockchain-enabled traceability platforms bypassing traditional exporter-aggregator layers. Dominant competitive moves center on backward integration into farmer contracting programs and geographic expansion of decortication capacity in underdeveloped milling markets.
Among North American originators, AGT Food and Ingredients and Cargill exemplify the vertically integrated archetype, leveraging Saskatchewan processing networks and direct farmer contracting to sustain consistent quality premiums. TOO Atameken Agro Trade and TOO ARS Trading represent Central Asian commodity traders consolidating regional supply for export channels. Orient Exports P Ltd occupies a position within the South Asian aggregator tier, managing compliance documentation for FSSAI tender access.
| Leading Market Players |
|---|
| TOO Atameken Agro Trade |
| North Pulse Traders |
| OOO Volgatrade |
| AGT Food and Ingredients |
| Great Grains Group USA |
| TOO ARS Trading |
| Orient Exports P Ltd |
| Cargill |
| Tasty Bite Eatables Limited |
| Others |
Cost & Logistics Intelligence
Backward integration into farmer contracting programs anchors both supply security and premium capture for dominant Canadian originators. Saskatchewan's elevator network and direct origination relationships sustain protein-grade premiums that commodity traders cannot replicate.
Pricing Analysis
Protein-content-based pricing anchors contract negotiations, with NIR-verified certificates determining immediate price tier placement. Three-tier pricing structure across premium, standard, and economy levels separates organic green lentils for European retail from commodity red lentils for South Asian dal production. Cost compression in the standard tier is intensifying because Turkish and Indian splitting capacity expansion floods the decortication market. Food manufacturers exhibit highest price sensitivity, while organic retail channels absorb premiums for traceable lot-specific supply.
Supply Chain Analysis
Regional distribution centers in Regina, Mersin, and Mumbai form a hub-and-spoke pattern that consolidates Prairie origination for ocean freight export. Supply concentrates in Canada, Turkey, and Australia, with Saskatchewan's Prairie corridor feeding European and South Asian destinations. Raw material flows draw from rhizobium-inoculated seed stock, glyphosate-compliant desiccation protocols, and FSSAI-certified aflatoxin testing. Single-source vulnerability runs through Saskatchewan's soil-moisture-dependent protein consistency. Distribution runs through bulk container shipments to mill reception points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained origination in the Northern Plains props pricing as drought cycles compress protein consistency year-to-year. Limited elevator capacity with NIR spectroscopy certification creates bottlenecks that filter market access.
For Market Incumbents: To counter Turkish splitting capacity expansion, AGT Food and Ingredients and Cargill should deepen captive supply of high-protein seed stock through direct farmer contracting in Saskatchewan and Alberta. Certification investment in EU Farm to Fork Strategy compliance documentation secures premium European retail positioning against conventional supply exclusion. For New Entrants and Emerging Players: Launch via blockchain-enabled traceability platforms that bypass traditional exporter-aggregator layers in European organic channels. Bangladesh and Myanmar green lentil dehulling capacity remains underdeveloped, creating first-mover space for equipment-and-grain integrated supply. Target FSSAI pre-qualified supplier registry status to access Mumbai and Chennai government tender participation. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of vertically integrated processors with in-house laboratory capacity and established FSSAI compliance documentation. Long-term viability hinges on climate-adaptive origination diversification beyond Prairie concentration. Watch for India's FSSAI aflatoxin protocol tightening as inflection indicator for Australian and Canadian supplier access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farmer Contracting | Direct origination relationships in Saskatchewan sustain protein-grade premiums against commodity traders. |
| NIR Spectroscopy Deployment | Real-time protein quantification at primary elevators determines immediate price tier placement. |
| FSSAI Compliance Certification | In-house laboratory capacity opens government buffer stock tender access in Mumbai and Chennai. |
| EU Farm to Fork Strategy Alignment | Nitrogen-fixing crop rotation documentation redirects procurement toward certified low-carbon originators. |
| Decortication Capacity Expansion | Advanced splitting equipment in Anatolia competes with Indian processors for red lentil origination. |
Research Approach
Multi-period observation of protein content thresholds, glyphosate residue compliance, and FSSAI tender participation rates anchored the trend analysis, supplemented by interviews with grain elevator operators, dal processing facility managers, agricultural input distributors, and European retail procurement leads. Secondary validation drew from Canadian Grain Commission export data, Indian FCI procurement records, EU Farm to Fork Strategy documentation, and Health Canada PMRA regulatory filings. Bottom-up origination volume estimates and top-down consumption demand projections were triangulated for consistency.
Input-output matrices modeled lentil flows across product type, end user, packaging format, and distribution channel dimensions throughout the forecast period. CAGRs were derived from segmented volume trajectories calibrated to government procurement policy shifts and climate volatility patterns in Prairie and Australian winter cropping zones. Forecast inputs included FSSAI aflatoxin surveillance tightening timelines and EU EFSA maximum residue limit enforcement intensity.
Climate volatility in Saskatchewan and Alberta, regulatory acceleration in India and the European Union, and pulse protein isolate substitution in sports nutrition are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Durum Wheat Flour Market
Grains
Argentina Grains Market
Grains
Europe Wheat Market
Grains
Ancient and Specialty Grain Flour Market
Grains
Fortified Rice Market
Grains
Chickpeas Market
Grains
North America Wheat Market
Grains
Cultured Wheat Market
Grains
Green Banana Flour Market
Grains
Grain Storage Silos Market
Grains
Basmati Rice Market
Grains
Organic Wheat Flour Market
Grains
India Rice Market
Grains
Corn Market
Grains
China Rice Market
Grains
Non-Basmati Rice Market