
 Argentina Grains Market | 2026-2036
Argentina Grains Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Grains Market Outlook
Precision agriculture and digital farm management platforms is reconfiguring how Argentine grain producers optimize yield and logistics. Cargill leverages its Rosario-based crushing complex and river terminal network to anchor soybean origination across Santa Fe province. Bunge Global competes through backward integration into fertilizer distribution and port operations along the Paraná waterway. Louis Dreyfus Company navigates export logistics via its Timbúes terminal, sustaining throughput to Asian destinations.
Argentina grains encompass cereal and oilseed crops cultivated across the Pampas and peripheral agricultural zones, with protein content, moisture levels, and oil concentration serving as key quality parameters for international trade. These commodities supply food processing, livestock nutrition, and renewable energy feedstocks in both domestic and export markets. Soybeans dominate export value, with margin pools concentrating at crushing facilities that supply meal and oil to international buyers. Corn occupies the fastest-growing demand channel through expanded animal feed consumption in Vietnam and Indonesia. Wheat quality grades stratify across premium bread-making varieties and standard feed classifications, reflecting divergent end-use requirements.
SENASA phytosanitary certification requirements shape export market access, with residue limits and GMO approval protocols determining destination eligibility. The Argentine central bank's foreign exchange regulations influence producer selling behavior and grain stockholding patterns. BIS-equivalent grain standards and Mercosur trade protocols further condition cross-border flows. Stakeholders must monitor waterway infrastructure investment decisions and biofuel blending mandate adjustments to anticipate origination and export volume shifts.
Market Dynamics
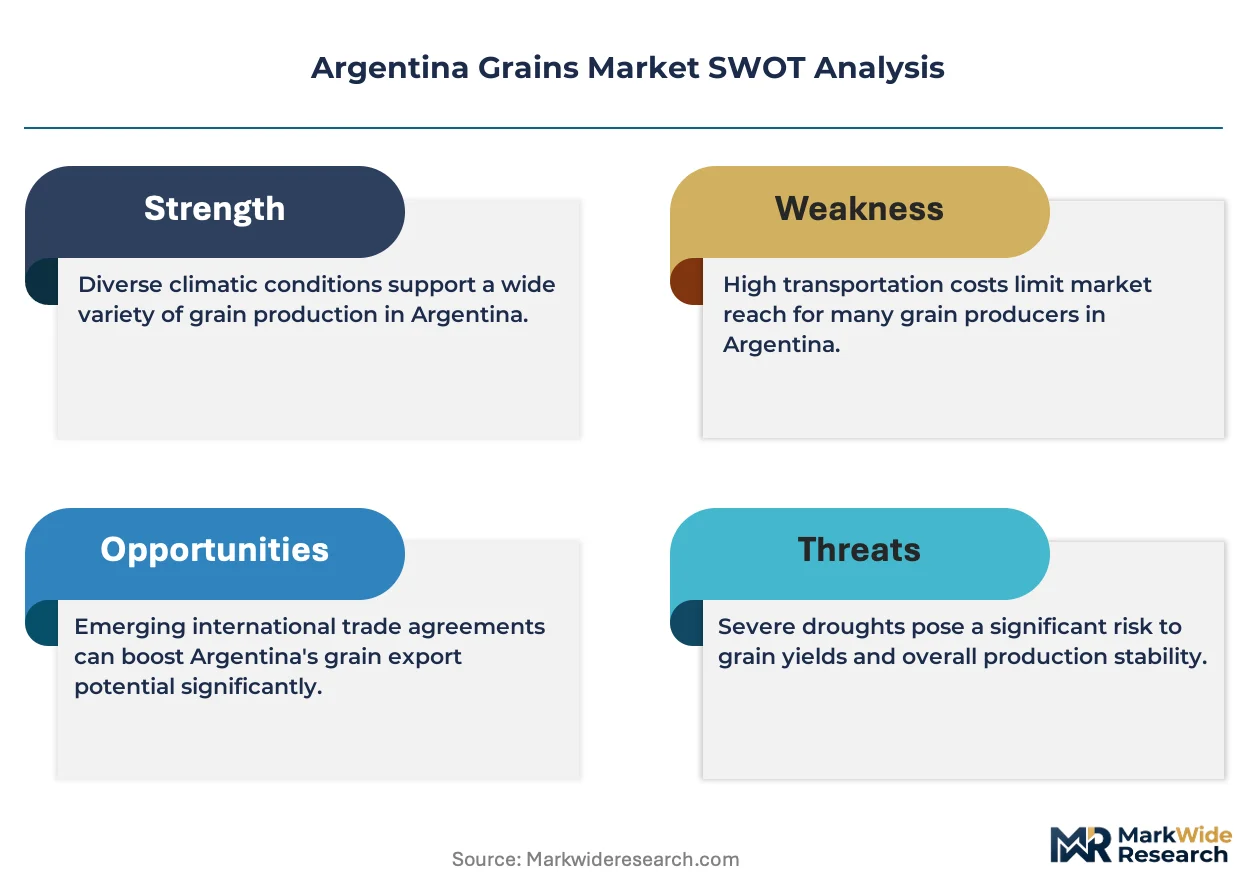
Argentina's grain sector operates under acute foreign exchange distortion, where central bank dollar-peso spreads and export retention policies force producers into barter-based contracting and deferred payment structures that reshape origination economics.
Growth Catalysts
- Biofuel Blending Mandates:Argentina's renewable energy framework mandates escalating biodiesel incorporation rates, anchoring domestic crush demand for soybeans and stabilizing processor margins through captive offtake.
- Vietnam Feed Mill Expansion:Southeast Asian aquaculture and pork production complexes are scaling corn and soy meal imports, with Argentine origin gaining preference over US Gulf supply on freight cost differentials.
- Variable-Rate Seeding Technology:Precision planting systems calibrated to soil conductivity maps are lifting Pampas soybean yields by optimizing seed density across productivity zones.
Market Restraints
- Paraná Waterway Depth Volatility:Low river gauges during drought cycles force vessel light-loading, inflating unit freight costs and compressing FOB netbacks to Rosario terminals.
- SENASA Phytosanitary Certification Delays:Inspection backlogs and documentation complexity create demurrage exposure at Timbúes and Quequén ports, particularly for GMO corn shipments to China.
- Synthetic Protein Substitution:Fermentation-derived amino acids and insect meal are displacing soy meal inclusion rates in European compound feed formulations.
Strategic Opportunities
- Northwest Argentina Expansion:Tucumán and Salta provinces offer untapped sorghum and corn acreage with access to Chilean Pacific ports, bypassing Paraná logistics constraints.
- Carbon Credit Monetization:No-till farming protocols certified under Verra standards enable grain exporters to bundle verified emission reductions with commodity sales to EU buyers.
- Containerized Grain Exports:Direct stuffing at inland elevators for Asian destinations is circumventing bulk vessel bottlenecks and capturing premium identity-preserved premiums.
Industry Challenges
- Agronomic Data Integration:Fragmented farm management software platforms prevent seamless yield prediction models from informing forward contracting decisions at cooperative level.
- Silobag Storage Quality Control:On-farm hermetic storage systems require specialized monitoring protocols to prevent aflatoxin development during humid harvest windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Grains Market |
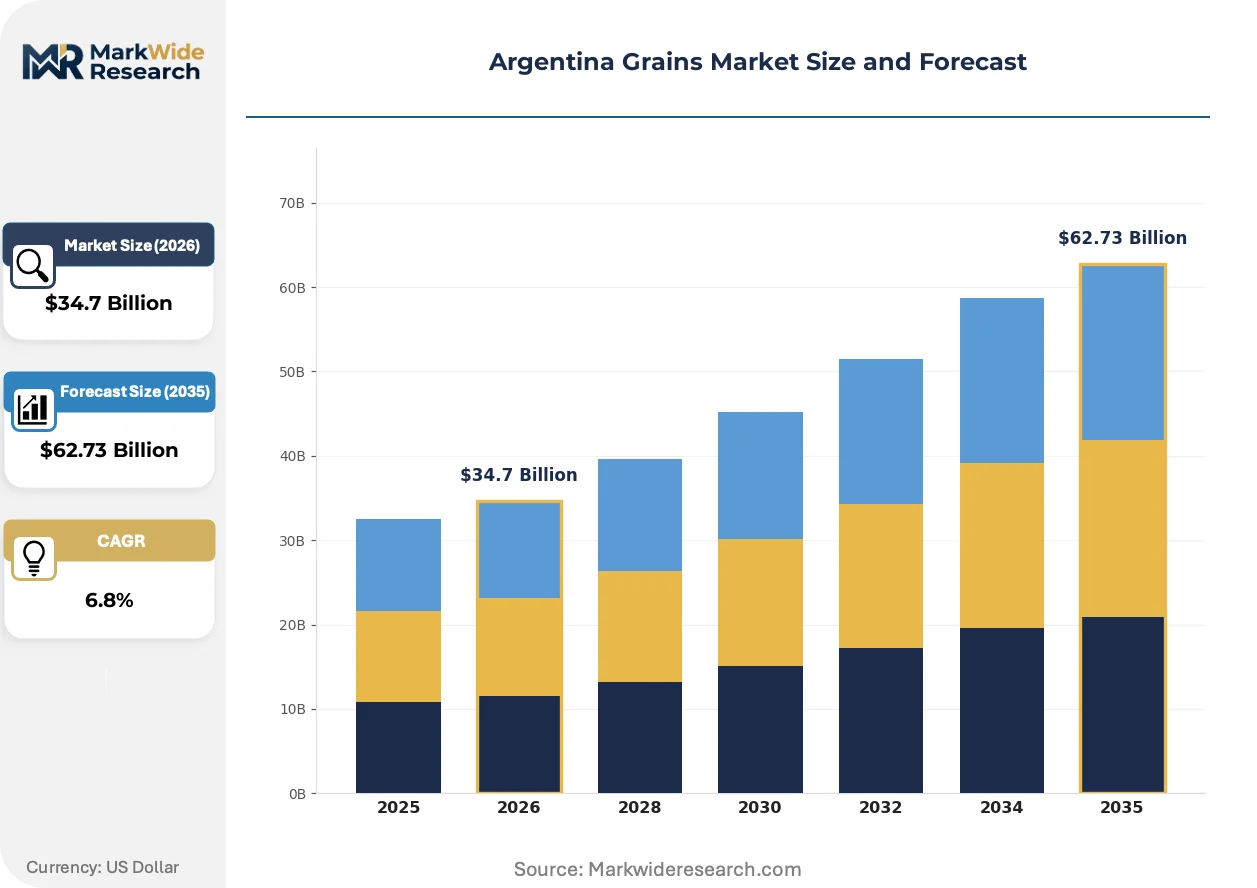
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soybeans, Corn, Wheat, Barley End Use Industry: Food Processing, Animal Feed, Biofuel, Export Distribution Channel: Wholesale, Retail, Direct Sales, E-commerce Quality Grade: Premium, Standard, Low-grade, Organic |
| Companies Covered | Viterra, Cargill, COFCO International, Bunge Global, AGD, Louis Dreyfus Company, Archer Daniels Midland, ACA, Molinos Agro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Grains Market Strategic Shifts
Digital infrastructure and sustainability verification protocols are restructuring how Argentine grain flows from field to export vessel, compressing information asymmetries between producers and destination buyers.
Satellite-based crop monitoring fused with machine learning yield forecasting is collapsing the information gap between Pampas farmgate production estimates and Chicago futures pricing. Large trading houses now deploy proprietary drone imagery networks to pre-position logistics before harvest completion. This transparency compression erodes traditional cooperative bargaining power in origination.
SENASA's electronic phytosanitary certification system mandates real-time traceability data submission for all export-bound grain lots, with non-compliance triggering automatic shipment holds. The regulation forces elevators to upgrade inventory management software and integrate with national customs platforms. Small and mid-sized cooperatives face disproportionate compliance costs relative to integrated crusher-exporters with captive IT infrastructure.
Feed mill procurement teams in Vietnam and Indonesia now contract Argentine origin through origin-swap arrangements with Brazilian suppliers, using price differentials rather than physical cargo flows to manage exposure. This financialized sourcing behavior displaces traditional FOB contracting at Rosario. The shift concentrates price discovery power with Singapore-based trading desks and compresses Argentine processor origination premiums.
Argentina Grains Market Segmentation
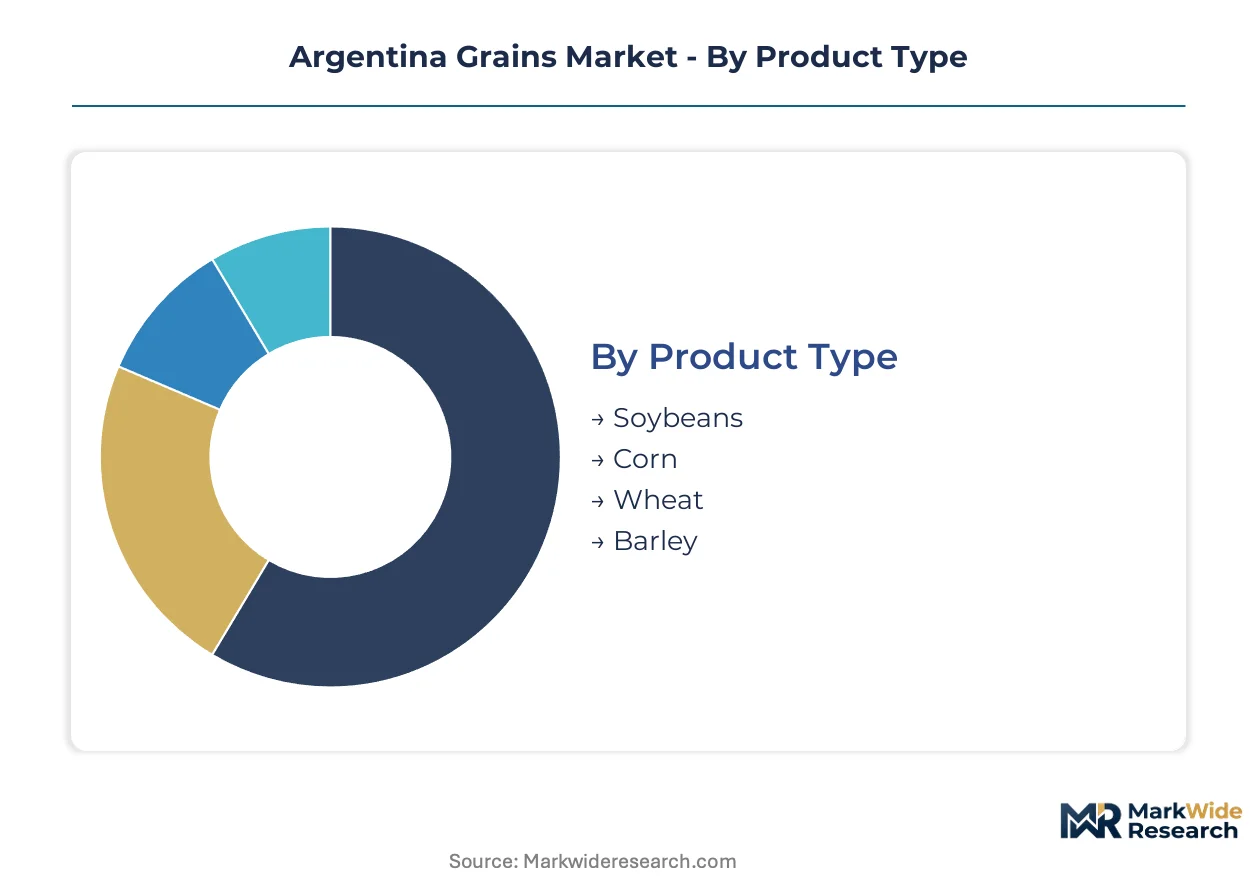
Grain segmentation in Argentina reflects divergent quality protocols, destination requirements, and processing economics that shape origination premiums. SENASA certification standards and end-use specifications create distinct commercial lanes within each product category. Understanding these partitions enables targeted positioning across crushing, milling, and export channels.
Product Type:
Cost tier differentiation across crop categories determines margin capture potential and infrastructure investment intensity. Soybeans command premium processing economics through oil and meal extraction, while corn and wheat compete on volume throughput and quality stratification.
- Soybeans:High-protein oilseed with 18-20% oil content and 44% meal protein specifications. Crushing complexes in Santa Fe and Buenos Aires provinces concentrate demand, with SENASA GMO documentation requirements shaping China-bound export eligibility.
- Corn:Yellow dent varieties dominate feed and industrial channels, with moisture specifications tightening for Southeast Asian aquaculture feed mills. Vietnam and Indonesia procurement teams prioritize Argentine origin on freight cost differentials against US Gulf supply.
- Wheat:Hard red winter and soft varieties supply domestic milling and regional Mercosur trade, with protein content stratifying across bread-making and feed classifications.
- Barley:Malting-grade specifications serve Argentine brewing industry, with feed-grade absorption by cattle operations in Córdoba and La Pampa provinces.
Soybeans holds installed capacity. Corn is rotating up the share rankings.
End Use Industry:
Application-driven demand channels create divergent procurement patterns, quality thresholds, and price discovery mechanisms across the Argentine grain complex.
- Food Processing:Wheat milling and oil refining operations require consistent protein and moisture specifications, with BIS-equivalent standards governing cross-border Mercosur trade flows.
- Animal Feed:Compound feed manufacturers in Buenos Aires and Santa Fe provinces drive corn and soy meal consumption, with inclusion rates facing pressure from fermentation-derived amino acid substitutes in European formulations.
- Biofuel:Biodiesel blending mandates anchor domestic soybean crush demand, with renewable energy framework escalation stabilizing processor margins through captive offtake.
- Export:FOB Rosario and Timbúes terminals channel grain to Southeast Asian and European destinations, with SENASA phytosanitary certification determining market access eligibility.
Animal Feed captures the largest volume throughput. Biofuel is climbing the fastest.
Distribution Channel:
Volume concentration and customer scale determine channel economics, with bulk logistics favoring wholesale structures and identity-preserved premiums supporting direct contracting.
- Wholesale:Elevator aggregation and river terminal origination dominate soybean and corn flows, with cooperative selling pools consolidating farmgate production for crusher and exporter offtake.
- Retail:Bagged seed and specialty grain sales serve small-scale livestock producers in peripheral agricultural zones, requiring localized storage and transport infrastructure.
- Direct Sales:Large Pampas farming operations contract directly with crushing facilities, bypassing cooperative intermediaries and capturing origination premiums through volume commitments.
- E-commerce:Digital platforms for input procurement and forward contracting are emerging among mid-tier producers, though physical grain delivery remains logistics-constrained.
Wholesale maintains dominant flow volumes. Direct Sales is gaining share fastest.
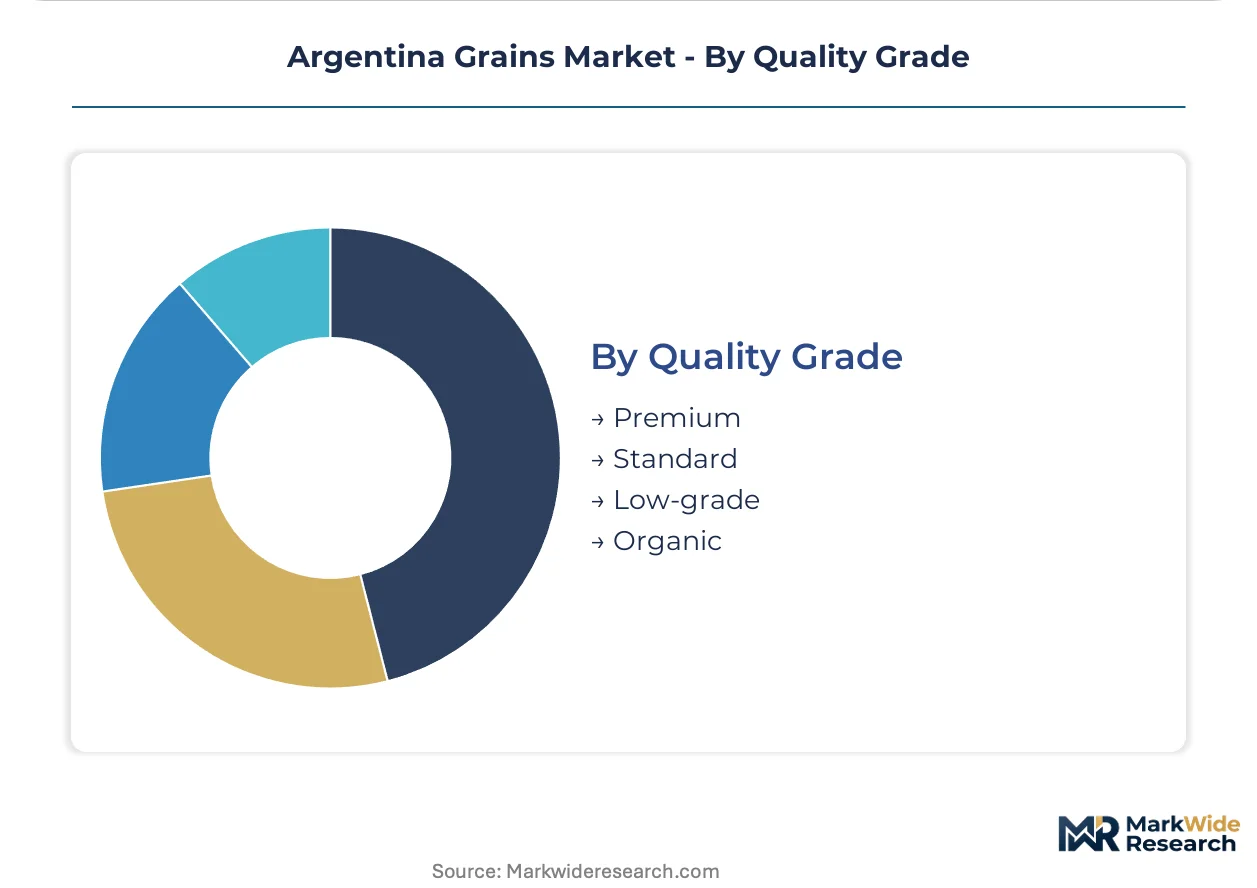
Quality Grade:
Customer type and destination market requirements stratify grain into tiered pricing bands, with certification premiums and penalty structures shaping producer sorting decisions.
- Premium:High-protein wheat and identity-preserved soybeans command export and specialty milling premiums, with Verra-certified no-till protocols enabling carbon credit bundling to EU buyers.
- Standard:Commodity-grade corn and wheat supply bulk export and domestic feed channels, with moisture and foreign matter tolerances defined by SENASA export standards.
- Low-grade:Sub-specification grain diverts to domestic cattle feeding or ethanol processing, with price discounts reflecting nutritional density shortfalls.
- Organic:Non-GMO and chemical-free certifications serve niche European and North American markets, requiring segregated handling infrastructure and extended rotation compliance.
Standard grade commands the widest throughput base. Premium is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina exports grains through Rosario river terminals to Southeast Asian feed mills in Vietnam and Indonesia, with European biodiesel processors and Chinese crushing facilities anchoring secondary demand corridors. SENASA phytosanitary protocols condition destination eligibility across these trade lanes. Currency volatility and waterway depth fluctuations reshape seasonal shipment patterns.
Buenos Aires Province
Domestic crushing complexes and port terminals concentrate soybean origination volumes. SENASA's electronic certification system mandates real-time traceability submission for Timbúes-bound export lots. The Bahía Blanca grain corridor anchors wheat shipments to Brazilian millers through Mercosur preferential trade protocols.
Santa Fe Province
Rosario's river terminal network channels corn and soybean flows to Vietnamese aquaculture feed manufacturers. The central bank's export retention policies force local cooperatives into barter-based contracting structures. Crushing facilities along the Paraná waterway compete for Pampas farmgate supply through direct origination programs.
Córdoba Province
No-till soybean rotations dominate acreage allocation across the central Pampas core. Variable-rate seeding technology calibrated to soil conductivity maps lifts yields in heterogeneous productivity zones. Silobag storage systems proliferate among mid-tier producers seeking to bypass cooperative elevator discounts.
Entre Ríos Province
Paraná waterway depth volatility during drought cycles forces vessel light-loading at Concepción del Uruguay terminals. Containerized grain stuffing at inland elevators is emerging as a bulk vessel bottleneck workaround. Freight cost differentials against US Gulf supply sustain Argentine corn competitiveness in Indonesian procurement tenders.
Northwest Argentina
Tucumán and Salta provinces offer untapped sorghum and corn acreage with Pacific port access through Chilean transshipment. SENASA documentation requirements for GMO corn shipments to China create compliance complexity at secondary export points. Carbon credit monetization under Verra standards enables emission reduction bundling to EU buyers from no-till protocols.
Argentina Grains Market Competitive Environment
Channel-controlling players compete with product-specialist players across origination, crushing, and export terminal functions. The market structure concentrates around integrated trading houses with captive port infrastructure and cooperative aggregators serving fragmented farmgate supply. Three archetypes dominate: river-terminal-anchored crushers, cooperative selling pools, and direct-contracting large farming operations. Competitive moves center on backward integration into fertilizer distribution and geographic expansion into Northwest Argentina bypass corridors.
Within the integrated trading house tier, Cargill, Bunge Global, and Louis Dreyfus Company occupy positions defined by river terminal control and Asian destination relationships. Cargill's Rosario-based complex exemplifies crusher-terminal integration. Bunge Global represents backward integration archetypes through fertilizer and port operations. Louis Dreyfus Company anchors the export logistics specialization vector via Timbúes throughput capacity.
| Leading Market Players |
|---|
| Viterra |
| Cargill |
| COFCO International |
| Bunge Global |
| AGD |
| Louis Dreyfus Company |
| Archer Daniels Midland |
| ACA |
| Molinos Agro |
| Others |
Value Chain & Pricing Dynamics
Paraná waterway depth volatility determines both the spread between FOB Rosario and delivered Southeast Asian prices and the configuration of origination logistics across the Argentine grain complex. This hydrological risk vector compresses processor margins during drought cycles while forcing supply chain adaptation through containerized stuffing and Pacific corridor development.
Pricing Analysis
Precision agriculture technology-generation pricing gaps separate early adopters of variable-rate seeding systems from conventional producers, with yield optimization premiums stratifying farmgate contracting terms. The dominant structure runs through commodity spot markets layered with forward contract offtake from crushing facilities. Price differentiation rests on SENASA certification tier and volume scale, with identity-preserved premiums for Verra-certified no-till protocols. Cost compression in standard-grade corn flows is intensifying because Vietnamese feed mills now execute origin-swap arrangements with Brazilian suppliers rather than physical Argentine cargo. Small cooperatives exhibit highest price sensitivity due to IT infrastructure gaps for electronic phytosanitary compliance.
Supply Chain Analysis
SENASA phytosanitary certification requirements function as export-control regime equivalents, restricting GMO corn flows to China and conditioning market access eligibility across destination corridors. Geographic supply concentration centers on Argentina, Brazil, and the US Gulf as the three origination nodes serving Southeast Asian feed demand. Raw material dependencies draw from phosphate fertilizer imports, diesel fuel for farm operations, and imported crop protection chemistry. Single-source vulnerability concentrates at the Timbúes-Rosario river terminal cluster, where vessel light-loading during low-gauge periods creates systemic throughput risk. Distribution runs through cooperative elevator aggregation into crusher-exporter origination programs, with direct contracting bypass emerging among large Pampas operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-derived amino acids and insect meal substitutes threaten soy meal inclusion rates in European compound feed, forcing Argentine grain stakeholders into defensive positioning across origination and export functions.
For Market Incumbents: Build captive origination moats through backward integration into fertilizer distribution and silobag storage infrastructure. Cargill and Bunge Global should deepen direct contracting relationships with large Pampas farming operations to preempt cooperative intermediation. SENASA electronic certification compliance represents the critical lever for maintaining China-bound GMO corn eligibility against Brazilian competitor inroads. For New Entrants and Emerging Players: Establish a beachhead in Northwest Argentina sorghum and corn origination through Chilean Pacific port access, bypassing Paraná logistics constraints entirely. Tucumán and Salta provinces offer the most penetrable geography given underdeveloped elevator infrastructure and absence of integrated trading house dominance. Carbon credit monetization under Verra standards provides the go-to-market angle for EU-bound premium grade differentiation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-tier cooperative aggregators with captive port access and IT infrastructure for SENASA compliance. Long-term viability across the analysis window hinges on origination technology adoption curves and waterway infrastructure investment decisions. Watch containerized grain export volumes through Concepción del Uruguay as the inflection signal for logistics model disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fertilizer Distribution | Bunge Global's Paraná waterway operations demonstrate how captive input supply secures origination economics against currency volatility. |
| Variable-Rate Seeding Technology Deployment | Soil conductivity mapping systems lift Pampas soybean yields and compress information asymmetries between producers and Chicago futures pricing. |
| Verra Carbon Credit Certification | No-till protocol verification enables EU-bound grain exporters to bundle emission reductions with commodity sales for premium capture. |
| Containerized Grain Export Infrastructure | Direct stuffing at inland elevators circumvents bulk vessel bottlenecks and captures identity-preserved premiums from Asian buyers. |
| Northwest Argentina Geographic Expansion | Tucumán and Salta acreage development with Chilean Pacific access diversifies origination away from Paraná depth volatility. |
Study Parameters
A spread of perspectives from grain trading executives at Rosario-based crushing complexes, SENASA regulatory affairs officers, Vietnamese feed mill procurement directors, and cooperative elevator managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through Argentine central bank foreign exchange regulation filings, SENASA phytosanitary protocol documentation, and SEC 10-K disclosures from listed trading houses. Bottom-up volume modeling from provincial production estimates triangulated against top-down trade flow analysis from customs records.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning crop type, quality grade tier, end-use industry channel, and regional origination cluster. CAGRs derived from historical trade flow trajectories layered with policy scenario adjustments for biofuel blending mandate escalation and export retention regime shifts. Forecast inputs incorporated Paraná waterway gauge variability patterns and Southeast Asian feed mill capacity expansion pipelines.
Macroeconomic conditions sit as an overlay; deviation in peso-dollar exchange rate spreads or biodiesel subsidy adjustments would shift the trajectory. Forecasts reflect documented assumptions regarding SENASA certification processing timelines and Chinese GMO approval protocols. Cross-checking against Rosario grain exchange price benchmarks and vessel freight rate indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Europe Wheat Protein Market
Grains
Rolled Oats Market
Grains
Global Cassava Flour Market
Grains
North America Wheat Protein Market
Grains
White Rice Flour Market
Grains
Global Quinoa Market
Grains
Mexico Rice Market
Grains
Grain Bins Market
Grains
Ancient and Specialty Grain Flour Market
Grains
Uganda Grains Market
Grains
Torrified Wheat Market
Grains
Brown Rice Market
Grains
Global Maize Market
Grains
Bangladesh Rice Market
Grains
Wild Rice Market
Grains
Global Oats Market