
 Bulk Reception Feeder Market | 2026-2036
Bulk Reception Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Reception Feeder Market Analysis
EPA particulate-matter enforcement is pivoting capital planning across the bulk-materials sector. FLSmidth leverages its integrated testing infrastructure to validate sealed-chamber designs before deployment. Metso Outotec anchors its position through deep expertise in high-capacity vibratory systems for hard-rock mining. Schenck Process UK Limited competes on precision weighing integration with feeder lines, a niche where technical differentiation commands premium positioning.
A bulk reception feeder is a mechanized material-handling unit engineered to receive, meter, and transfer raw bulk solids from trucks, railcars, or vessels into downstream processing or storage systems, typically achieving throughput rates from 100 to over 10,000 tonnes per hour depending on configuration and material density. Belt feeders dominate iron-ore and coal applications where continuous, high-volume flow with minimal spillage remains critical to port and mine-site economics. Vibratory feeders capture expanding share in food-processing and recycling lines where gentle handling of fragile or heterogeneous materials prevents degradation and contamination losses. Gravity feeders retain cost advantage in agricultural grain reception, though their dependence on consistent particle size and moisture limits deployment flexibility.
OSHA silica-exposure rules and EU F-Gas Regulation on sealed-system refrigerants shape equipment-sealing and ventilation specifications that directly influence feeder enclosure design and maintenance protocols. MEE dust-control mandates in China and EPA New Source Performance Standards in the United States create divergent compliance pathways that manufacturers must navigate for market access. Stakeholders must weigh regional regulatory divergence against platform standardization when configuring global product portfolios.
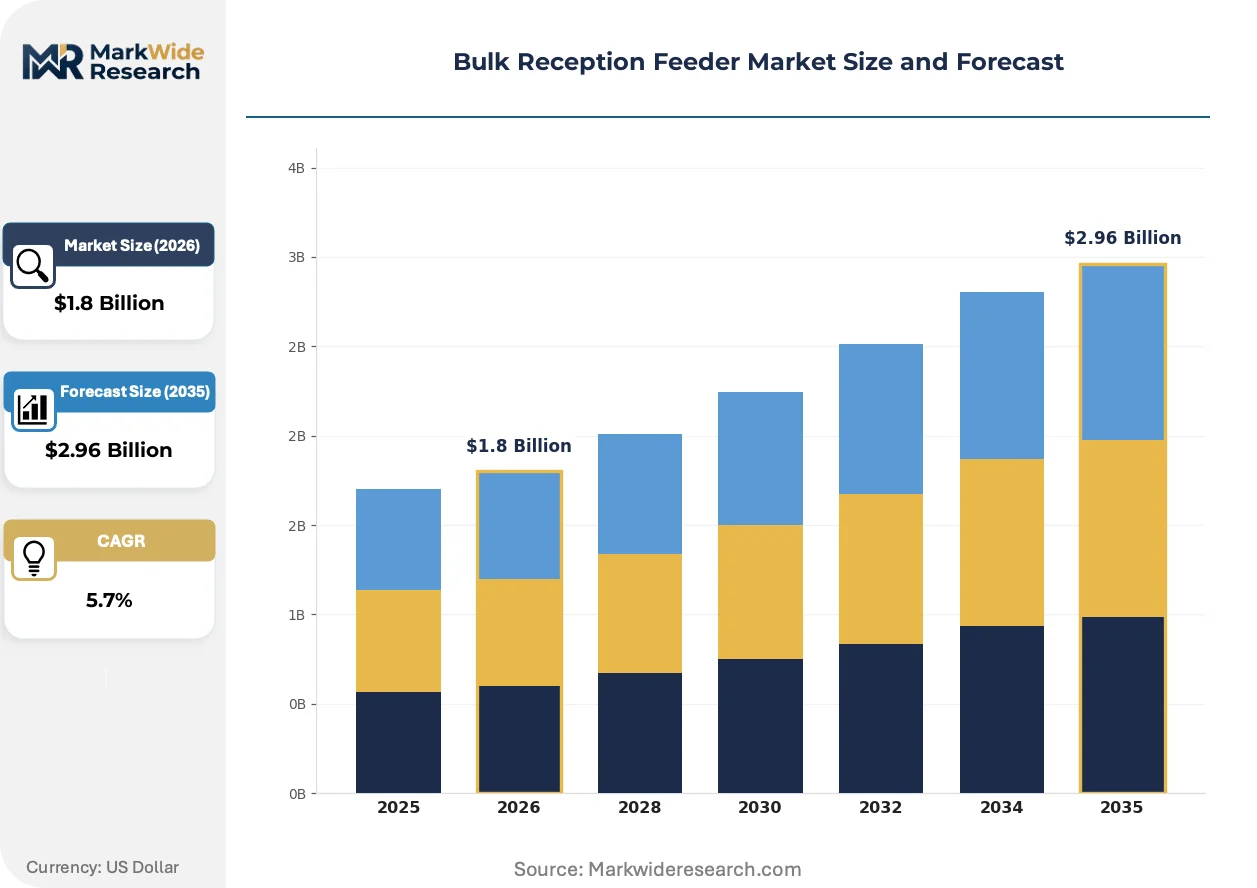
Market Dynamics
EPA New Source Performance Standards and MEE dust-control mandates are forcing wholesale redesign of feeder enclosures, compressing procurement cycles as mining operators race to retrofit port and mine-site infrastructure before enforcement deadlines.
Growth Catalysts
- Automated ore handling:Mining companies in Australia's Pilbara region are deploying high-throughput reception systems to accommodate export volume expansion. Belt feeder installations at Port Hedland and Dampier anchor this demand.
- EPA particulate enforcement:Stricter PM2.5 and PM10 thresholds under US environmental law are compelling coal and mineral processors to specify fully enclosed feeder designs. Capital planning now prioritizes sealed-chamber configurations.
- Iron-ore export growth:Brazil's Minas Gerais state continues expanding bulk-commodity throughput, driving demand for vibratory and belt feeder systems capable of 10,000+ tonnes per hour.
Market Restraints
- Steel input volatility:Fluctuating alloy and plate steel prices compress fabrication margins for feeder manufacturers. Cost pass-through mechanisms remain contested in contract negotiations.
- Supply concentration:Precision weighing components and industrial vibration motors concentrate among German and Japanese suppliers. Geopolitical friction disrupts lead times for critical subassemblies.
- Gravity feeder substitution limits:Agricultural grain reception retains cost advantage for gravity-fed systems, constraining premium feeder penetration in moisture-stable, particle-consistent applications.
Strategic Opportunities
- Recycling line expansion:European Union circular-economy mandates under the EU Green Deal are accelerating demand for gentle-handling vibratory feeders in municipal and industrial waste sorting facilities.
- Digital twin integration:Convergence of IIoT sensors with predictive maintenance platforms enables remote monitoring of feeder wear and throughput optimization. Mining operators in Chile are piloting these deployments.
- Food-processing certification:FSSAI hygiene mandates in India are creating specification requirements for stainless-steel, washdown-capable feeder designs previously absent in bulk solids handling.
Industry Challenges
- Silica-exposure compliance:OSHA respirable crystalline silica rules demand redesigned ventilation and sealing protocols. Engineering teams face compressed timelines to validate enclosure integrity.
- Legacy system integration:Brownfield mining sites require feeder retrofits compatible with decades-old control architectures. Interface standardization gaps inflate commissioning costs and delay acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Reception Feeder Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity Feeders, Belt Feeders, Vibratory Feeders, Chain Feeders Application: Mining, Agriculture, Food Processing, Recycling End User: Mining Companies, Food Manufacturers, Recycling Facilities, Agricultural Producers Installation: Onsite Installation, Mobile Units, Permanent Setup, Temporary Setup |
| Companies Covered | FLSmidth, Metso Outotec, Schenck Process UK Limited, ABB Ltd., Siemens AG, Astec Industries, TELESTACK LTD., Mahindra Tsubaki Conveyor Systems, Haver & Boecker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Reception Feeder Market Emerging Trajectories
Feeder technology is pivoting toward sealed, sensor-integrated designs as environmental enforcement tightens and throughput demands escalate across hard-rock mining and bulk-export terminals.
Condition-monitoring instrumentation is converging with bulk reception feeder architectures to enable predictive maintenance and real-time throughput optimization. Mining operators in Western Australia are adopting these configurations fastest, driven by remote-site maintenance cost pressures. The technology is converging with traditional mechanical designs to compress unplanned downtime and extend wear-component life cycles.
The EU F-Gas Regulation is restricting refrigerant use in sealed-system climate control for electronic feeder components. Manufacturers must redesign thermal management for motor drives and sensor enclosures without conventional cooling agents. Food-processing and pharmaceutical applications in Northern Europe face the steepest compliance curves.
Maintenance contracting is unbundling from capital equipment sales as mining houses seek to transfer operational risk. Service providers now compete on availability guarantees rather than spare-parts margins. This shift is most pronounced in Chilean copper operations and Australian iron-ore ports where labor mobility constraints inflate in-house technical staffing costs.
Bulk Reception Feeder Market Segmentation
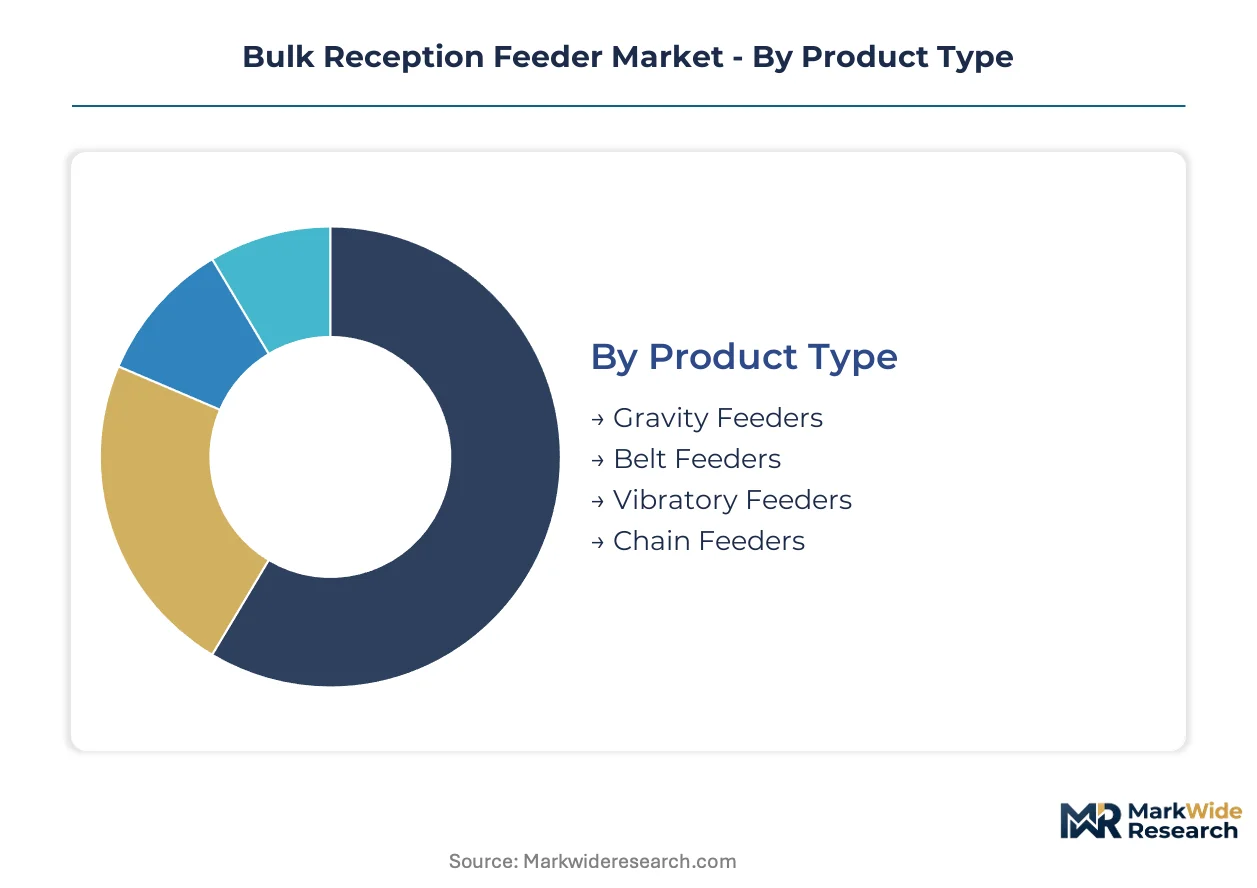
Feeder architecture determines capital allocation patterns across mining, agriculture, and industrial processing. Technical specifications vary sharply by material density, throughput requirements, and regulatory exposure. Procurement teams segment investments by operational tempo, retrofit complexity, and compliance burden.
Product Type:
Supply concentration for precision drive components and specialized belting tilts procurement power toward manufacturers with captive fabrication or long-term supplier contracts.
- Belt Feeders:Continuous rubber or steel-cord belt systems with variable-speed drives achieve 10,000+ tonnes per hour in iron-ore and coal applications. Pilbara mining operators and Brazilian export terminals specify these for high-volume, low-spillage reception. EPA particulate enforcement is accelerating fully enclosed belt configurations with sealed transfer points.
- Vibratory Feeders:Electromagnetic or electromechanical drive units generate controlled oscillation for gentle material handling. Food-processing lines in Northern Europe and recycling facilities under EU circular-economy mandates specify these for fragile or heterogeneous feedstocks where degradation losses are costly.
- Gravity Feeders:Chute-based systems rely on particle mass and angle of repose for flow control without powered components. Agricultural grain reception in moisture-stable, particle-consistent applications retains this lowest-capital option despite limited flexibility.
- Chain Feeders:Heavy-duty apron or drag-chain configurations handle abrasive, high-impact materials in hard-rock mining. Underground and surface quarry operations deploy these where belt damage from sharp, heavy lumps would accelerate maintenance cycles.
Belt feeders absorb the bulk of installed capacity; vibratory feeders are expanding most quickly.
Application:
Margin structure diverges sharply between commodity bulk handling and certified hygienic processing, with regulatory compliance costs compressing returns in food applications.
- Mining:Hard-rock and bulk-commodity extraction drives demand for highest-throughput, most durable reception systems. Australian iron-ore ports and Chilean copper concentrators anchor global procurement volume. Automated ore-handling investments prioritize availability guarantees and predictive maintenance integration.
- Recycling:Municipal and industrial waste sorting under EU Green Deal mandates requires gentle-handling vibratory configurations. Heterogeneous feedstocks with variable density and contamination profiles demand adaptive metering precision that gravity systems cannot deliver.
- Agriculture:Grain and oilseed reception at elevators and port terminals favors simpler mechanical solutions where particle consistency permits. Seasonal throughput peaks and moisture sensitivity constrain capital intensity relative to continuous-process mining.
- Food Processing:FSSAI hygiene mandates in India and EU sanitary standards require stainless-steel, washdown-capable designs with sealed bearings and quick-release components. Certification overhead elevates procurement costs but creates specification stickiness.
Mining absorbs the bulk of installed capacity; recycling is gaining share fastest.
End User:
Customer scale and technical staffing depth determine whether procurement favors capital-sale or availability-contracting models.
- Mining Companies:Large diversified miners and pure-play iron-ore operators specify integrated reception systems with digital twin compatibility. Maintenance risk transfer to OEM service providers is most advanced in Chilean copper and Australian bulk-export operations.
- Recycling Facilities:Municipal operators and private waste-management contractors face feedstock variability that demands flexible, quick-changeover feeder configurations. EU circular-economy investment waves are accelerating fleet renewal.
- Food Manufacturers:Dairy, grain-processing, and packaged-goods producers balance hygienic design against throughput economics. FSSAI and EU hygiene mandates are forcing stainless-steel specification upgrades in previously cost-driven segments.
- Agricultural Producers:Grain elevators, cooperatives, and large farming operations prioritize seasonal reliability and lowest capital outlay. Gravity and simple belt configurations dominate where technical staffing for complex maintenance is scarce.
Mining companies command the largest installed base; recycling facilities are climbing the fastest.
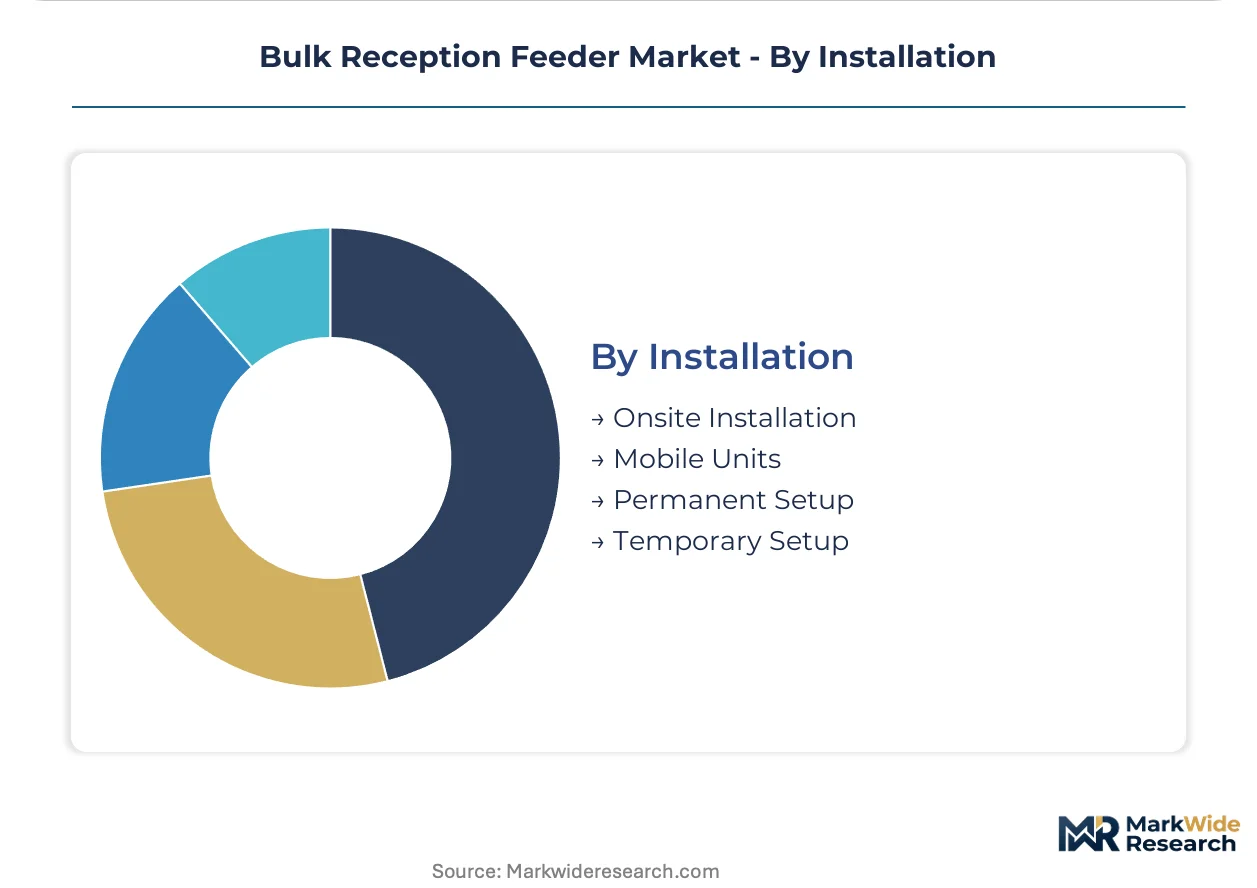
Installation:
Mobility requirements reflect project lifecycle uncertainty and site tenure economics across brownfield and greenfield developments.
- Permanent Setup:Fixed foundations with integrated civil works anchor high-volume, long-life mining and port infrastructure. Pilbara iron-ore terminals and Brazilian export corridors specify these for decades-long operational horizons.
- Mobile Units:Skid-mounted or trailer-based configurations enable rapid relocation across quarry phases, construction projects, and temporary stockpile operations. Short-term contracts and geological uncertainty favor this flexibility despite higher per-tonne capital cost.
- Onsite Installation:Project-specific engineering with custom chute work, support structures, and control integration dominates large mining and processing greenfields. Commissioning timelines stretch months as legacy system interfacing demands custom protocol bridges.
- Temporary Setup:Rental or lease-based deployment for surge capacity, seasonal agricultural peaks, or emergency replacement. Service providers compete on availability guarantees rather than equipment sale margins in this segment.
Permanent setups hold the bulk of installed capacity; mobile units are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilbara mining clusters in Western Australia and Minas Gerais export corridors in Brazil concentrate automated reception infrastructure investment, with special economic zones in Chile and tax-incentivized manufacturing regions in Germany and China anchoring supplier ecosystems.
Australia
Port Hedland and Dampier terminals drive belt feeder procurement for iron-ore export expansion. EPA dust-control mandates accelerate fully enclosed system specifications. Pilbara mining operators deploy high-throughput reception systems to accommodate volume growth targets.
Brazil
Minas Gerais state anchors South American bulk-commodity throughput expansion with vibratory and belt feeder demand. ANVISA industrial equipment standards shape import certification pathways. Vale-operated export corridors specify 10,000+ tonnes per hour reception capacity.
Chile
Copper concentrators in Antofagasta and Coquimbo regions automate ore handling to offset labor mobility constraints. MEE-equivalent dust frameworks under CONAMA influence enclosure design specifications. Escondida and Collahuasi anchor predictive maintenance pilot programs.
China
Shandong Peninsula and Yangtze River Delta manufacturing bases supply precision drive components for export markets. MEE dust-control mandates enforce sealed-chamber configurations for domestic mining and port applications. Tianjin and Qingdao terminals retrofit reception systems for coal and iron-ore handling.
Germany
Ruhr industrial belt and Bavarian fabrication clusters concentrate precision weighing component and vibration motor production. EU F-Gas Regulation restricts refrigerant use in sealed-system climate control for electronic feeder components. Schenck Process exemplifies engineering-intensive positioning in measurement-integrated systems.
Bulk Reception Feeder Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the Bulk Reception Feeder Market, creating a tiered structure where scale-driven fabricators and precision-engineering boutiques occupy distinct value positions. Equipment manufacturers cluster around three strategic archetypes: integrated mining-technology conglomerates, precision weighing and measurement specialists, and regional fabrication houses serving commodity bulk-handling. M&A activity concentrates on digital twin and IIoT capability acquisition, while capacity expansion targets Australian and Brazilian port infrastructure waves.
Among Nordic engineering conglomerates, FLSmidth and Metso Outotec occupy positions emphasizing integrated testing infrastructure and high-capacity vibratory expertise respectively. Schenck Process UK Limited sits within the precision measurement tier, representing the convergence of weighing technology with material-handling systems. These three anchors illustrate how competitive positioning diverges between scale-driven project execution and technical differentiation in niche specification environments.
| Leading Market Players |
|---|
| FLSmidth |
| Metso Outotec |
| Schenck Process UK Limited |
| ABB Ltd. |
| Siemens AG |
| Astec Industries |
| TELESTACK LTD. |
| Mahindra Tsubaki Conveyor Systems |
| Haver & Boecker |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up fabrication specialists have consolidated regional mid-caps across Germany's Ruhr belt and China's Shandong Peninsula, compressing supplier counts while extending payment terms to captive component vendors. This ownership concentration tightens pricing discipline among belt and vibratory feeder manufacturers serving Australian mining houses and Brazilian export terminals.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to sealed-chamber belt feeders ordered for EPA-mandated retrofits at US coal terminals. Three-tier pricing structure across premium, standard, and economy levels separates predictive-maintenance-integrated systems from basic mechanical configurations. Pricing pressure stems from steel input volatility eroding fabrication margins. Agricultural grain elevators exhibit highest price sensitivity, while Chilean copper concentrators prioritize availability guarantees over capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Pilbara iron-ore operators and Vale-managed Brazilian export corridors. Precision vibration motors and industrial weighing components concentrate in Germany and Japan. Supply rests on specialty alloy plate, rubber-cord belting, and sealed-bearing assemblies. Single-source vulnerability for electromagnetic drive units from Japanese suppliers exposes lead-time risk. Distribution runs through project-integrated EPC contractors and aftermarket service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
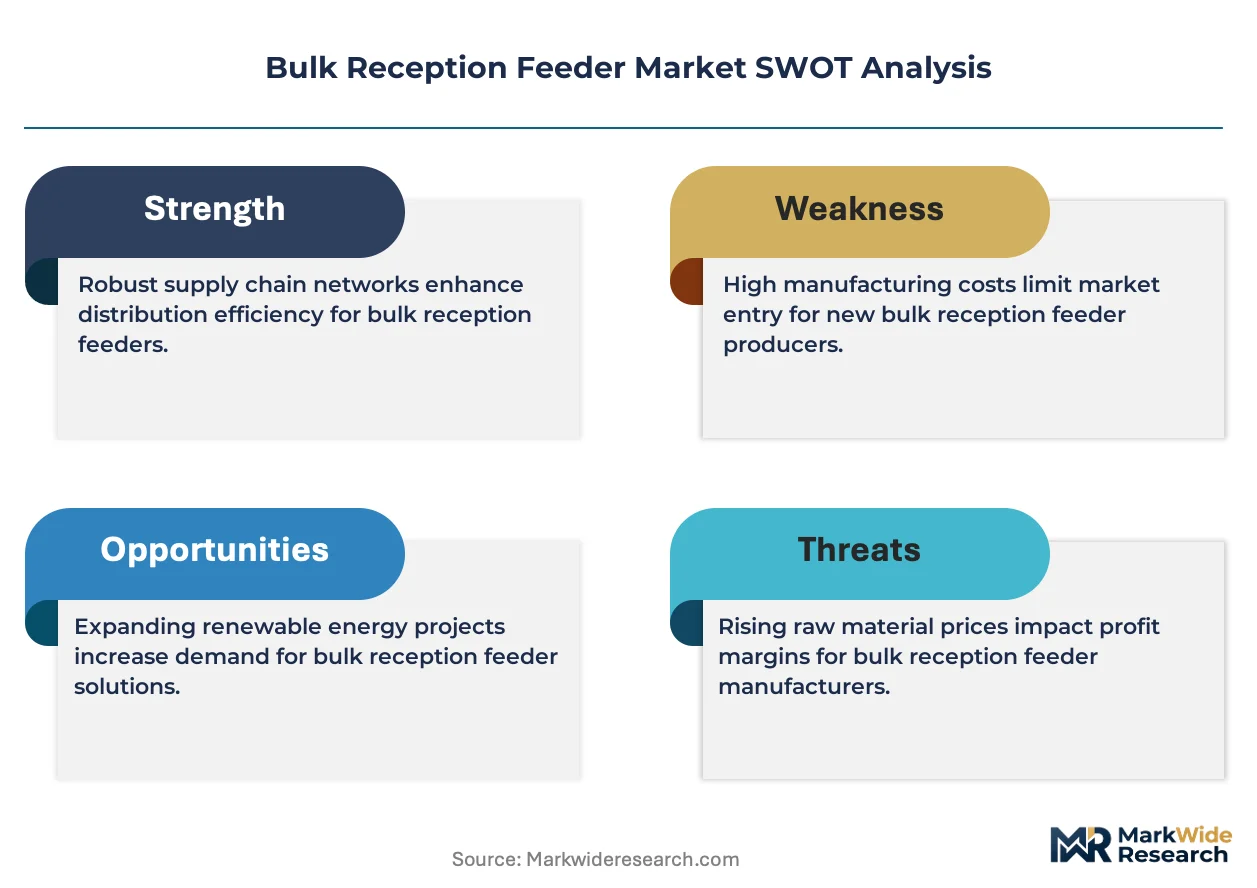
Consolidation pressure from MEE and EPA dust-enforcement deadlines is forcing subscale fabricators to exit or sell, creating acquisition opportunities for cashed-up specialists.
For Market Incumbents: Acquire predictive-maintenance software assets to bundle digital-twin capabilities with mechanical feeder sales. Secure captive supply of precision vibration motors through backward integration into Japanese or German component suppliers. This counters emerging IIoT-native entrants threatening commoditized hardware margins. For New Entrants and Emerging Players: Digital-channel routes through mining-equipment rental platforms offer lower-friction access to temporary-setup demand in African copper belts and Southeast Asian quarry operations. Target mobile-unit configurations for construction and seasonal agricultural applications. Lead with availability-based contracting rather than capital-sale positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor stainless-steel fabrication specialists in India's Maharashtra and Gujarat industrial corridors facing FSSAI certification cost burdens. Long-term viability hinges on hygienic-design capability transfer to food-processing growth markets. Watch MEE enforcement intensity in China's Tianjin and Qingdao port zones as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sealed-Chamber Design Certification | EPA particulate enforcement validates enclosure integrity before port deployment. |
| Predictive Maintenance Platform Integration | IIoT sensor convergence extends wear-component life for Pilbara operators. |
| Precision Weighing Capability Acquisition | Schenck Process measurement expertise commands premium in iron-ore metering. |
| Mobile Unit Fleet Expansion | Skid-mounted configurations capture quarry phase uncertainty in African copper belts. |
| Stainless-Steel Hygienic Design Investment | FSSAI mandates in India create specification stickiness in food-processing lines. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across maintenance directors at Pilbara iron-ore terminals, plant engineers at Chilean copper concentrators, OEM procurement teams in Germany, and aftermarket service heads in Australia. EPA enforcement databases, MEE dust-control directives, ANVISA industrial equipment standards, and iron-ore export statistics from Western Australia and Minas Gerais supplied validation layers. Bottom-up unit economics and top-down sector sizing were reconciled through iterative triangulation.
Data-stream reconciliation across shipment volumes, installation records, and capital-expenditure disclosures shaped the analytical framework. Segmentation dimensions spanned product architecture, application intensity, end-user scale, and mobility requirements across the projection horizon. CAGRs were derived from fitted growth curves against historical replacement cycles and regulatory compliance wave timing. Iron-ore throughput expansion in Brazil and automated ore-handling investments in Australia supplied industry-specific forecast anchors.
The model holds under stable regulatory enforcement timelines and uninterrupted alloy supply; deviation in tariff regimes or geopolitical friction over precision component trade would shift replacement demand patterns. Forecasts reflect documented assumptions regarding technology adoption curves and compliance deadline adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Plows Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Square Silos Market
Agricultural Equipment
Crop Spraying Drone Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
North America Electric Zero Turn Mower Market
Agricultural Equipment
Agricultural Trailer Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Agriculture Evaporative Cooling Pad Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market
Agricultural Equipment
Flexible Silos Market
Agricultural Equipment
Rotavator Market
Agricultural Equipment
Irrigation Syringe Market