
 Chickpeas Market | 2026-2036
Chickpeas Market Size, Share, and Industry Trends Forecast 2026-2036
Chickpeas Market Intelligence
Foodservice buyers and retail consumers is bifurcating demand patterns across the chickpeas value chain. COSUCRA leverages its European processing infrastructure to supply specialty chickpea ingredients for plant-based formulations. AGT Foods dominates North American pulse trading with vertically integrated sourcing from Canadian prairie growers. Roquette Frères extends its protein extraction expertise into chickpea isolates for meat-alternative applications.
Chickpeas are annual legumes of the Cicer arietinum species, containing approximately 20-25% protein and 60-65% carbohydrate by dry weight, with commercial cultivars differentiated by seed size, color, and desi versus kabuli classification. The legume functions primarily as a human food staple, livestock feed ingredient, and increasingly as a functional protein source in processed foods and nutraceuticals. Whole Chickpeas and Chickpea Flour together occupy the largest value share, reflecting entrenched consumption in South Asian and Middle Eastern cuisines alongside rising gluten-free baking applications. Canned Chickpeas is recording the fastest volume expansion in Western retail channels, where convenience positioning offsets margin compression from private-label competition. The Powdered form captures premium pricing in ingredient supply chains serving sports nutrition and infant formula manufacturers.
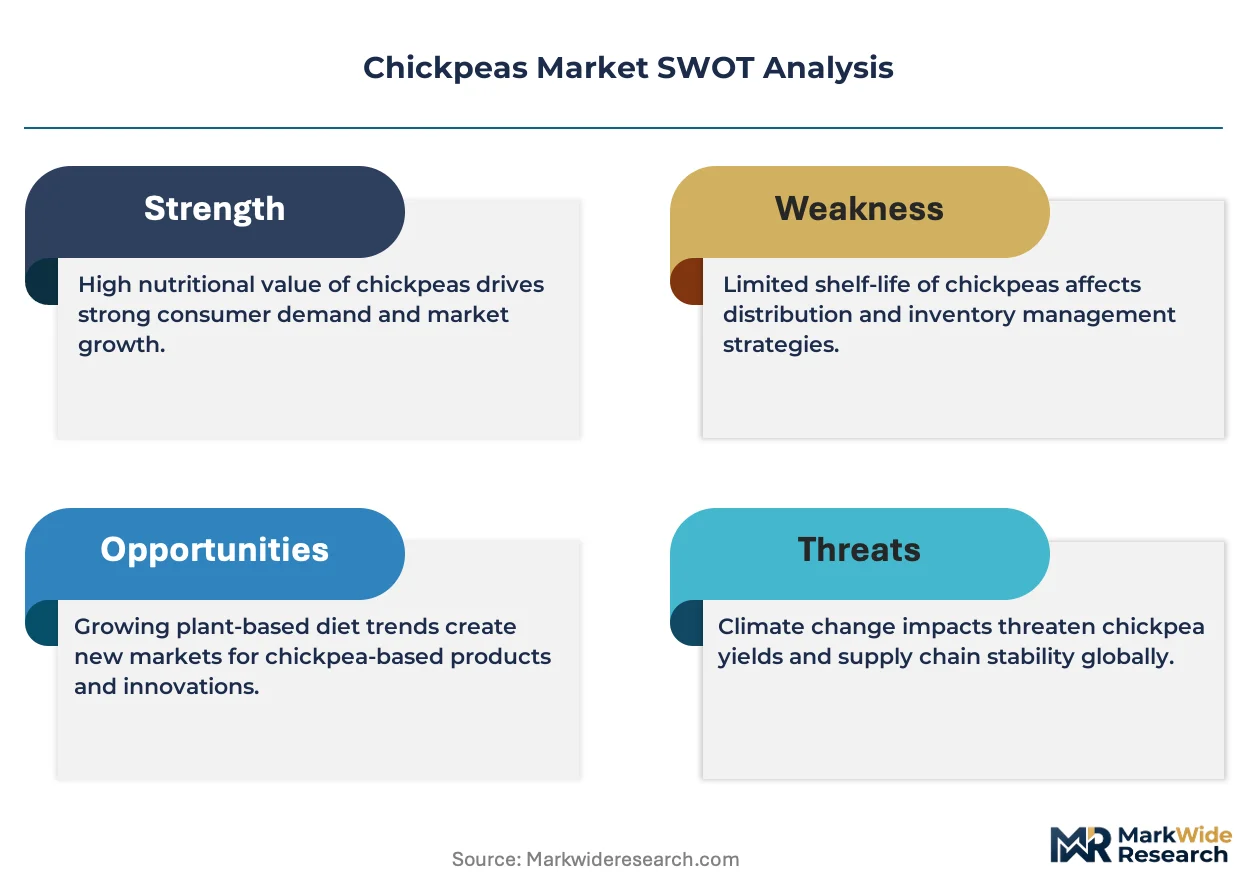
The EU Green Deal and REACH compliance requirements shape import standards for pesticide residues and carbon footprint disclosure across European supply chains. India's FSSAI and DGFT regulations govern domestic food safety benchmarks and export licensing procedures for kabuli chickpea shipments to premium markets. FDA and USDA oversight in the United States determines permissible processing aids and organic certification pathways for chickpea-based products entering American distribution. Stakeholders must monitor evolving protein content thresholds and mycotoxin limits as buyer specifications tighten across regulated jurisdictions.
Market Dynamics
The EU Green Deal's sustainable agriculture mandates are compressing supply chain timelines for European processors while simultaneously opening premium export channels for compliant growers in India and Canada.
Growth Catalysts
- EU Green Deal compliance requirements:REACH-aligned carbon footprint disclosure and pesticide residue standards are filtering non-compliant suppliers from European procurement pools, advantaging certified Indian and Canadian exporters.
- Plant-based protein formulation demand:Food & Beverage manufacturers are expanding chickpea isolate procurement for meat-alternative applications, pulling volume through specialty ingredient channels.
- Kabuli chickpea processing expansion in India:Domestic consumption growth and export-oriented processing capacity additions are concentrating value-add activities in Gujarat and Madhya Pradesh clusters.
Market Restraints
- Input cost volatility in nitrogen fertilizers:Natural gas price fluctuations transmit directly into grower margins across Canadian prairie provinces and Australian chickpea belts.
- Desi chickpea supply concentration in Ethiopia and Myanmar:Political instability and forex constraints in these origin markets create shipment reliability risks for Middle Eastern buyers.
- Protein content variability in heritage cultivars:Inconsistent 18-22% protein ranges in traditional desi varieties limit their uptake in standardized sports nutrition formulations.
Strategic Opportunities
- Underpenetrated infant formula applications:Hypoallergenic positioning of chickpea protein hydrolysates creates white space in European and North American pediatric nutrition channels.
- EU AI Act and CSRD convergence:Automated supply chain traceability tools paired with sustainability disclosure mandates are creating first-mover advantages for digitized processors.
- Direct-to-manufacturer ingredient platforms:Bypassing traditional commodity traders, chickpea flour and isolate suppliers are building captive relationships with plant-based meat startups.
Industry Challenges
- Protein extraction engineering talent scarcity:Specialized expertise in aqueous fractionation and spray-drying optimization remains concentrated among a handful of European and North American processing technologists.
- Organic certification timeline compression:Three-year transition periods for conventional acreage conversion are misaligned with buyer demand acceleration for certified organic chickpea ingredients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chickpeas Market |
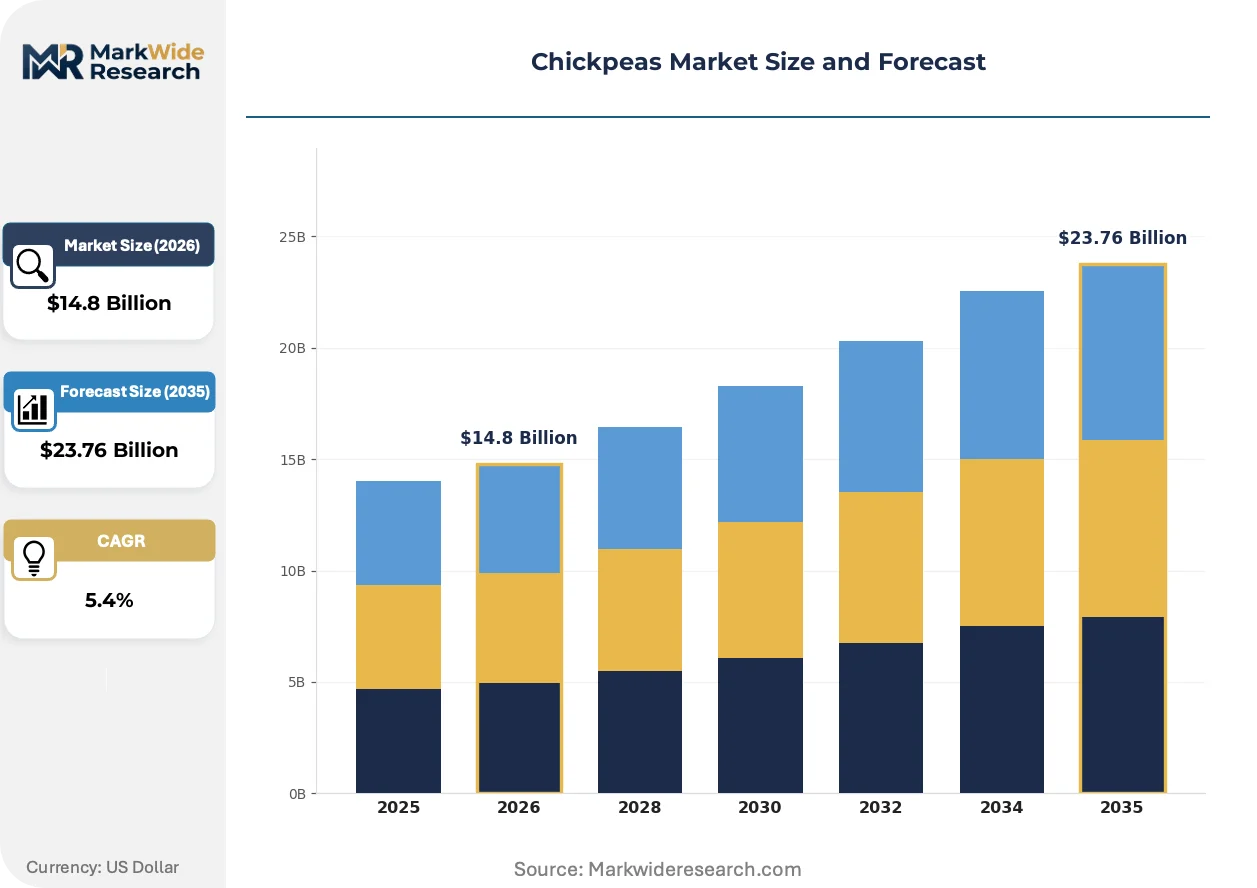
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Chickpeas, Chickpea Flour, Roasted Chickpeas, Canned Chickpeas End Use Industry: Food & Beverage, Animal Feed, Cosmetics, Pharmaceuticals Distribution Channel: Supermarkets, Online Retail, Wholesalers, Specialty Stores Form: Dried, Canned, Powdered, Frozen |
| Companies Covered | COSUCRA, Grupo Lucas, Glanbia Nutritionals, NuCicer, Severino Becagli, AGT Foods, Döhler Group, Hügli Holding AG, Roquette Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chickpeas Market Strategic Shifts & Innovations
Processing technology advances and regulatory disclosure requirements are fragmenting the commodity chickpea trade into parallel premium and industrial supply channels with diverging specification standards.
Dry fractionation technology is bifurcating the chickpea protein concentrate market. European ingredient houses are deploying air-classification systems to produce 60-70% protein concentrates without solvent use. Meat-alternative formulators in Germany and the Netherlands are adopting these concentrates at pace, while traditional whole-flour buyers in South Asian diaspora markets face compressed availability of standard-grade material.
REACH and EU Green Deal carbon border adjustment mechanisms are tightening import documentation requirements for pesticide residues and embodied emissions. European processors must now submit third-party verified lifecycle assessments for kabuli chickpea shipments from India and Turkey. Premium retail brands in France and Germany are responding by consolidating procurement around certified low-carbon suppliers.
Foodservice operators are unbundling chickpea procurement from legacy commodity contracts. Large North American restaurant chains are negotiating direct supply agreements with Canadian prairie grower cooperatives for identity-preserved desi varieties. This disintermediation is most visible in the fast-casual Mediterranean segment, where menu transparency claims require cultivar-level traceability from specific Saskatchewan and Alberta farm clusters.
Chickpeas Market Segmentation
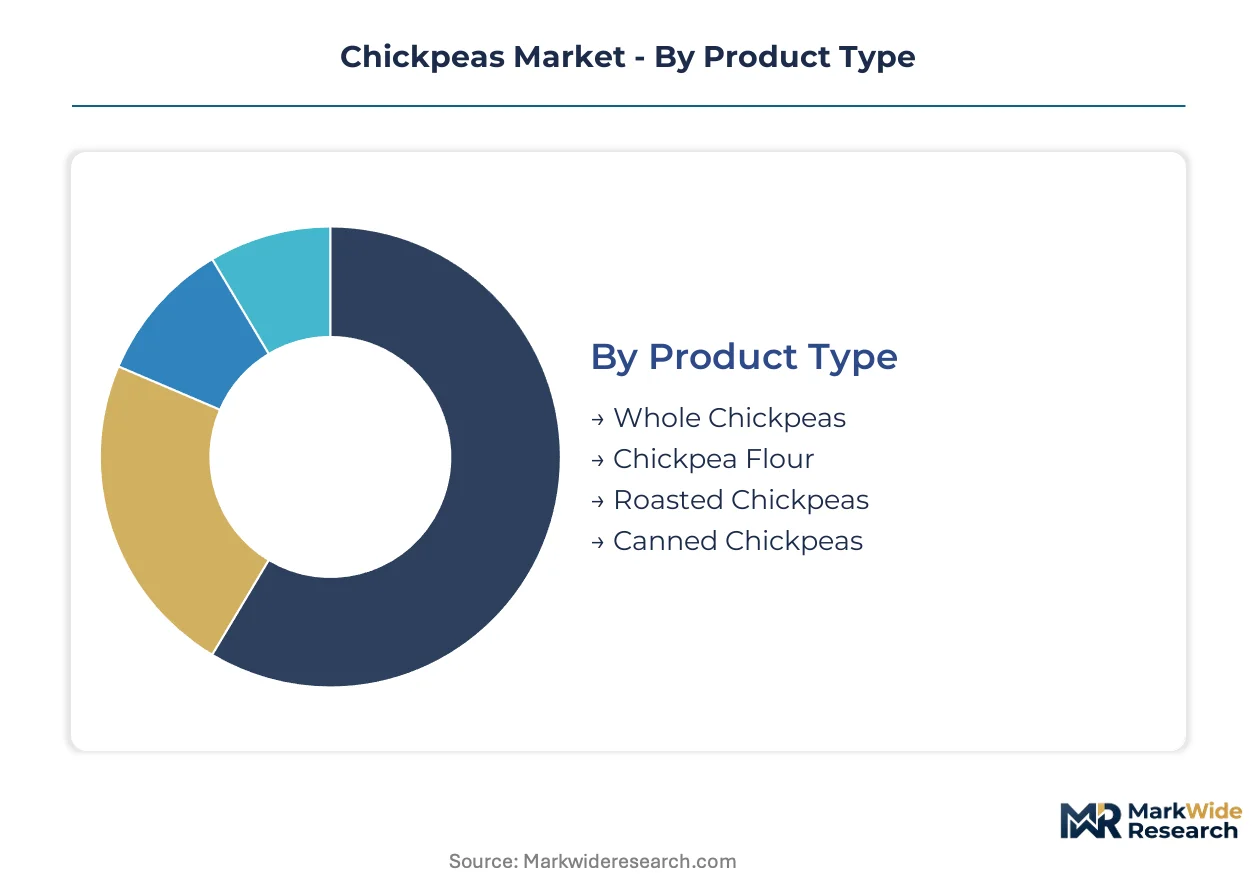
Chickpea segmentation reveals divergent margin structures across product formats and distribution pathways. Processing intensity and shelf stability create distinct value capture opportunities for suppliers serving ingredient versus retail channels.
Product Type:
Margin pools concentrate in value-added processing stages rather than raw commodity trading.
- Whole Chickpeas:Raw seed format with 20-25% protein content serves traditional South Asian and Middle Eastern cooking applications. Bulk procurement by food manufacturers in India and Turkey concentrates volume, while heritage desi varieties command premiums in ethnic retail channels.
- Chickpea Flour:Milled product with gluten-free positioning captures formulation demand from European and North American bakery manufacturers. Roquette Frères and COSUCRA extract higher margins through specialty particle size specifications for pasta and snack applications.
- Roasted Chickpeas:Snack format with extended shelf life targets health-conscious consumers through convenience retail positioning.
- Canned Chickpeas:Ready-to-eat preservation format dominates Western supermarket shelves with private-label compression offset by foodservice volume.
The dominant share belongs to Whole Chickpeas, while Chickpea Flour is closing the gap fastest.
End Use Industry:
Application diversification spreads revenue across human nutrition, animal husbandry, and industrial extraction channels.
- Food & Beverage:Primary consumption channel spanning whole seed, flour, and protein isolate applications. Plant-based meat startups in Germany and the Netherlands pull chickpea isolate volume through direct procurement agreements.
- Animal Feed:Secondary outlet for damaged and lower-grade seeds with protein meal specifications competing against soybean and canola alternatives. Canadian prairie feedlots incorporate desi chickpea screenings into ruminant rations during drought years.
- Cosmetics:Emerging application for chickpea starch in natural skincare formulations targeting European clean beauty segments.
- Pharmaceuticals:Niche demand for protein hydrolysates in hypoallergenic infant nutrition products under development by European pediatric formula manufacturers.
Food & Beverage commands the largest revenue pool, though Animal Feed demonstrates the steepest expansion trajectory during protein price spikes.
Distribution Channel:
Channel selection determines margin retention versus volume throughput tradeoffs for suppliers.
- Supermarkets:Mass retail placement for canned and dried formats with high brand recognition requirements. German chains Edeka and Rewe consolidate shelf space around certified organic and low-carbon labeled products.
- Online Retail:Direct-to-consumer pathway for specialty flour and roasted snack formats with subscription model potential. Indian platforms BigBasket and Blinkit aggregate fragmented regional brands into national distribution.
- Wholesalers:Volume aggregation for foodservice and industrial buyers with specification flexibility and price sensitivity.
- Specialty Stores:Ethnic grocery and health food positioning for heritage varieties and organic certifications with premium pricing power.
Supermarkets retain the dominant position, yet Online Retail is gaining share fastest through platform consolidation.
Form:
Preservation and processing state dictates logistics economics and end-use flexibility.
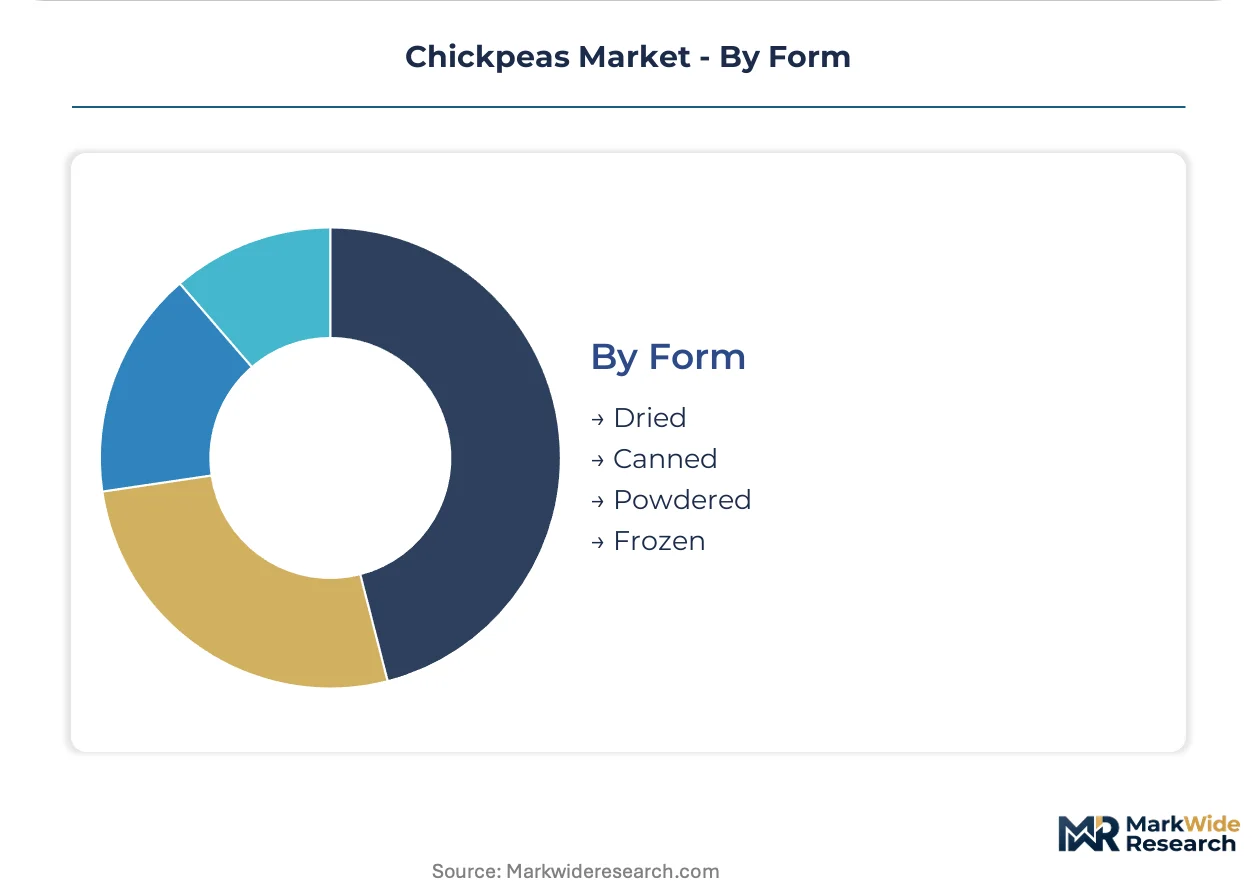
- Dried:Stable bulk commodity format with 12-month shelf life enabling ocean freight economics. Indian export processors in Gujarat and Madhya Pradesh concentrate value-add activities around kabuli drying and sorting.
- Canned:Brine-preserved ready-to-eat format with ambient distribution requirements. North American retail channels favor this convenience positioning despite higher unit costs.
- Powdered:Milled and spray-dried formats for ingredient supply chains with particle size and protein content specifications. Sports nutrition manufacturers specify this form for protein fortification applications.
- Frozen:Blanched and quick-frozen whole seeds for foodservice and prepared meal applications with cold chain dependency.
Dried form holds the dominant share, while Powdered is climbing the fastest on ingredient channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian export processors in Gujarat and Madhya Pradesh ship kabuli varieties to European ingredient houses and North American food manufacturers, while Canadian prairie cooperatives supply identity-preserved desi cultivars to Mediterranean fast-casual chains.
India
Domestic consumption expansion and export-oriented processing capacity drive volume through Gujarat and Madhya Pradesh clusters. FSSAI and DGFT regulations govern food safety benchmarks and kabuli chickpea export licensing to premium markets. Value-add activities concentrate in Gujarat's Rajkot and Ahmedabad processing zones where sorting, drying, and flour milling operations serve European and Middle Eastern buyers.
Canada
Identity-preserved desi varieties for foodservice traceability claims pull procurement from Saskatchewan and Alberta farm cooperatives. Canadian Grain Commission standards regulate seed quality and cultivar certification for export shipments. Processing infrastructure in Regina and Saskatoon handles cleaning, splitting, and protein concentrate preparation for North American plant-based meat manufacturers.
Germany
Meat-alternative formulators in Cologne and Hamburg accelerate chickpea isolate procurement through direct ingredient agreements. EU Green Deal REACH compliance and carbon border adjustment mechanisms filter non-compliant suppliers from procurement pools. Roquette Frères operates protein extraction facilities in Lestrem, supplying isolates to German and Dutch plant-based meat startups.
United States
Retail channel expansion for canned and dried formats drives procurement through Midwest distribution hubs. FDA and USDA oversight determines permissible processing aids and organic certification pathways for chickpea-based products. Foodservice operators in Chicago and Los Angeles negotiate direct supply agreements for cultivar-level traceability from specific Canadian prairie farm clusters.
Turkey
Re-export processing and regional trade hub positioning connect Middle Eastern buyers to Black Sea and Central Asian origin supplies. Turkish Ministry of Agriculture and Forestry regulations govern import phytosanitary standards and re-export certification. Processing facilities in Gaziantep and Mersin handle cleaning, sorting, and packaging for shipment to Saudi Arabian and UAE food manufacturers.
Chickpeas Market Key Industry Players
Player mix skews toward vertically integrated processors with captive sourcing networks and specialty ingredient houses with fractionation expertise. The vendor base concentrates around three strategic archetypes: European protein extraction specialists, North American pulse traders with grower cooperative relationships, and diversified food ingredient conglomerates with multi-legume portfolios. Competitive moves center on backward integration into identity-preserved acreage and technology licensing for aqueous fractionation processes.
Within the specialty ingredient tier, COSUCRA exemplifies European processing infrastructure deployment for plant-based formulations, while AGT Foods anchors North American pulse trading with vertically integrated sourcing relationships. Roquette Frères occupies a position at the protein extraction frontier, extending isolates into meat-alternative applications. These three entities represent divergent strategic vectors: European fractionation technology, North American commodity consolidation, and global ingredient diversification.
| Leading Market Players |
|---|
| COSUCRA |
| Grupo Lucas |
| Glanbia Nutritionals |
| NuCicer |
| Severino Becagli |
| AGT Foods |
| Döhler Group |
| Hügli Holding AG |
| Roquette Frères |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles at Indian kabuli processors compress margin buffers when EU Green Deal carbon disclosure requirements tighten certification premiums. This lead-time exposure concentrates pricing power among vertically integrated handlers in Gujarat and Madhya Pradesh clusters, while spot-market buyers absorb volatility from Ethiopian and Myanmar desi supply disruptions.
Pricing Analysis
Air-classification technology pricing gaps separate solvent-free 60-70% protein concentrates from legacy whole-flour grades. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with EU REACH-compliant kabuli varieties commanding premiums over conventional desi shipments. Cost compression in canned retail formats is intensifying because private-label competition at North American supermarkets erodes branded shelf space. Foodservice operators negotiating direct grower contracts demonstrate the lowest price sensitivity, while commodity traders facing Ethiopian forex constraints show the highest.
Supply Chain Analysis
Mundra and Hazira port congestion on westbound India-Europe lanes elevates container freight costs for kabuli export processors. Supply concentrates in India, Canada, and Turkey, with raw seed flows drawing from Saskatchewan prairie cooperatives and Gujarat sorting facilities. Nitrogen fertilizer price volatility and natural gas input costs create commodity price volatility across Canadian prairie provinces. Distribution runs through identity-preserved channels for Mediterranean fast-casual traceability claims and bulk commodity pipelines for Middle Eastern feed manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based protein formulation demand is accelerating chickpea isolate procurement as EU Green Deal mandates reshape ingredient sourcing standards. This regulatory-technology inflection creates asymmetric opportunities across incumbent defense, entrant positioning, and capital deployment strategies.
For Market Incumbents: Shield fractionation margins by locking in captive kabuli acreage through multi-season grower contracts in Gujarat and Madhya Pradesh. Invest in aqueous extraction R&D to offset protein extraction engineering talent scarcity before European competitors consolidate specialty isolate capacity. Certification investment in EU REACH-aligned carbon disclosure systems anchors premium pricing power against commodity traders lacking traceability infrastructure.
For New Entrants and Emerging Players: Organic certification fast-track programs in Canadian prairie provinces offer white-space entry before three-year transition timelines close availability windows. Target hypoallergenic infant formula applications in European pediatric nutrition channels where chickpea protein hydrolysate penetration remains minimal. Direct-to-manufacturer ingredient platforms bypass legacy commodity traders and build captive relationships with German and Dutch plant-based meat startups.
For Investors and Strategic Acquirers: Long-term, this sits as a protein-transition infrastructure play because plant-based meat alternative demand institutionalizes specialty isolate supply chains. Acquisition targets center on mid-cap processors with deployed air-classification capacity and established EU Green Deal compliance documentation. The signal to watch is FSSAI export licensing expansion for kabuli shipments as Indian regulators streamline premium market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Identity-Preserved Acreage | Captive kabuli supply from Gujarat farm clusters secures EU carbon disclosure compliance premiums. |
| Aqueous Fractionation Technology Licensing | Specialized extraction expertise from European processing technologists isolates high-value protein concentrates. |
| Direct-to-Manufacturer Platform Launch | Bypassing commodity traders builds sticky relationships with Cologne and Hamburg meat-alternative formulators. |
| Organic Certification Pipeline Investment | Three-year transition programs in Saskatchewan and Alberta align supply with accelerating certified ingredient demand. |
| EU AI Act Traceability System Deployment | Automated supply chain tools paired with CSRD mandates create first-mover advantages for digitized processors. |
Research Approach
Desk research of FAO trade statistics, Indian DGFT export licensing records, and EU REACH compliance documentation preceded structured interviews with chickpea processing plant managers, ingredient procurement leads at German meat-alternative manufacturers, Canadian prairie grower cooperative directors, and FSSAI regulatory affairs specialists. Secondary validation drew from Canadian Grain Commission quality reports, FDA food additive petitions, and customs data from Mundra and Hazira port authorities. Bottom-up volume modeling from country-level production data and top-down demand triangulation from end-use industry consumption patterns converged on segment-level estimates.
Variance decomposition across product type, end-use industry, distribution channel, and form dimensions structured the analytical framework over the projection horizon. CAGRs derived from fitted trend extrapolation with regulatory inflection adjustments. Modeled inputs incorporated nitrogen fertilizer cost indices, EU carbon border adjustment mechanism implementation timelines, and plant-based meat startup formation rates in German and Dutch innovation clusters.
Underlying assumptions cover sustained EU Green Deal enforcement, stable India-Europe shipping lane capacity, and continued plant-based protein R&D investment flows, with deviation risk concentrated in Ethiopian and Myanmar political stability, natural gas price volatility affecting fertilizer input costs, and FSSAI regulatory processing delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
South America Rice Market
Grains
00 Flour Market
Grains
Gluten Free Ancient Grain Market
Grains
White Rice Flour Market
Grains
Grain-Based Flours Market
Grains
Europe Rice Market
Grains
North America Wheat Protein Market
Grains
Global Maize Market
Grains
North America Maize Market
Grains
Global Grain Mill Products Market
Grains
Wheat Flour Market
Grains
Ghana Grain Market
Grains
North America Wheat Flour Market
Grains
Global Oats Market
Grains
Bangladesh Rice Market
Grains
North America Oats Market