
 Ancient and Specialty Grain Flour Market | 2026-2036
Ancient and Specialty Grain Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Ancient and Specialty Grain Flour Market Outlook
Bakery applications is realigning the demand profile for ancient and specialty grain flour as artisan producers and clean-label commercial bakers expand formulation trials. Bob's Red Mill leverages its employee-owned structure to sustain long-term supplier relationships with heritage grain cooperatives across the Pacific Northwest. King Arthur Baking Company anchors its market position through extensive recipe education platforms that drive consumer familiarity with spelt and teff. Cargill competes by controlling large-scale quinoa sourcing networks that supply industrial bakery customers with consistent protein specifications.
Ancient and specialty grain flour encompasses milled products derived from non-hybridized cereal grains such as quinoa, spelt, teff, and amaranth, typically retaining bran and germ fractions with protein contents ranging from 12% to 18% depending on varietal and growing conditions. These flours serve commercial and artisan food producers seeking differentiated nutritional profiles, gluten alternatives, or distinctive flavor characteristics in finished goods. Quinoa flour leads product type volumes due to established supply chains and broad consumer recognition, while teff flour represents the fastest-expanding category as Ethiopian cuisine gains mainstream traction in North American and European foodservice. Amaranth flour occupies a premium niche targeting allergen-free formulations, with margin pools concentrated in certified organic and non-GMO verified channels that command substantial price premiums over conventional wheat alternatives.
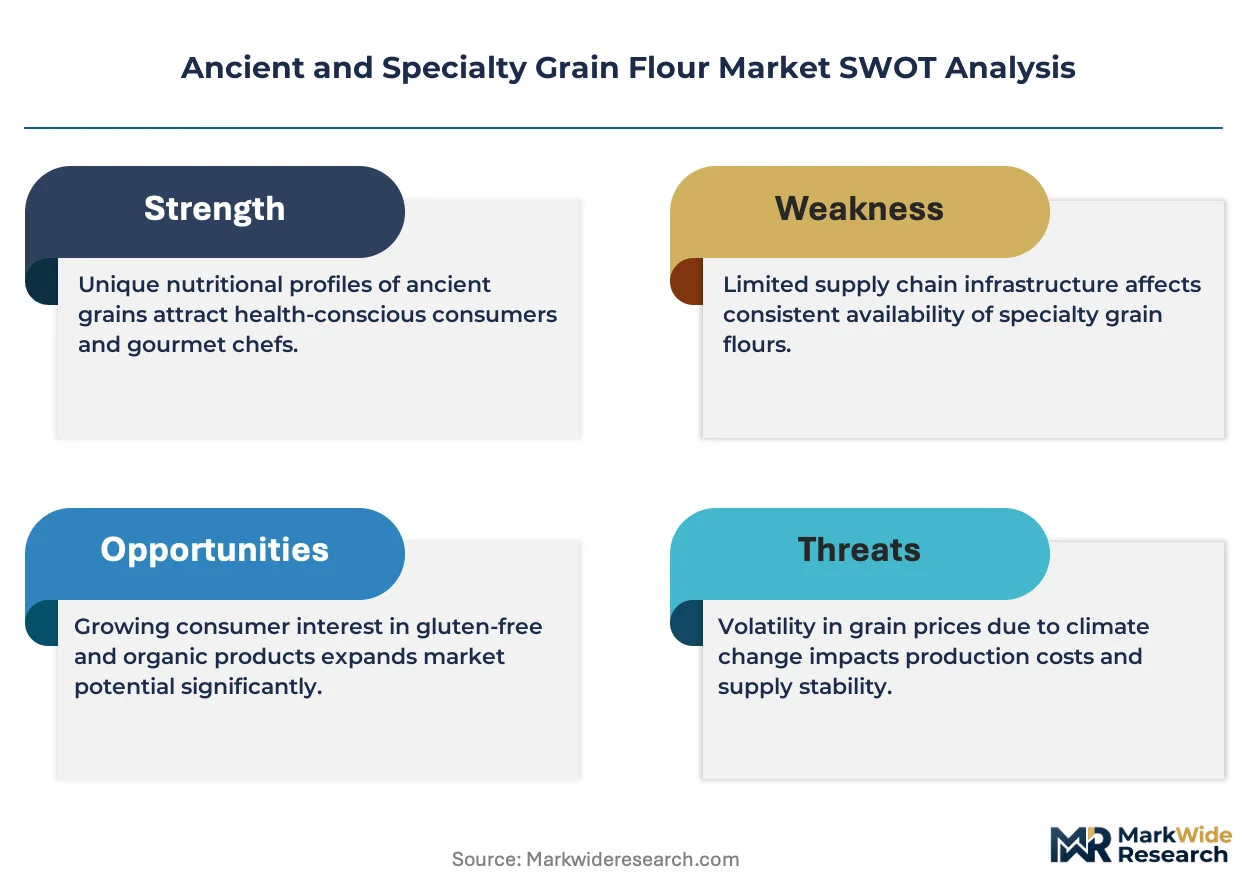
The FDA's Food Safety Modernization Act requirements shape import and handling protocols for specialty grain flours entering United States commerce, with particular scrutiny of allergen cross-contact prevention in multi-grain milling facilities. EFSA's novel food assessments and the EU Green Deal's carbon-footprint disclosure mandates are tightening traceability requirements for ancient grain supply chains across European markets. Stakeholders must monitor evolving organic certification harmonization between USDA and EU regulatory frameworks, as divergence in permitted substances or transition-period rules threatens to fragment market access for dual-certified producers.
Market Dynamics
The EU Green Deal's carbon-footprint disclosure mandates are forcing heritage grain supply chains to restructure traceability systems from farm to mill, while artisan bakery clusters in Germany and the Pacific Northwest simultaneously pull volume toward certified organic channels.
Growth Catalysts
- Clean-label bakery demand:Artisan producers and commercial bakers are expanding formulation trials with spelt and teff to meet consumer expectations for ingredient transparency and reduced processing.
- EU Green Deal mandates:Sustainable farming requirements under the European Commission's framework are redirecting agricultural subsidies toward heritage crop cultivation and soil-regenerative practices.
- Ethiopian cuisine mainstreaming:North American and European foodservice operators are incorporating teff-based injera and flatbreads into menu diversification strategies.
Market Restraints
- Input cost volatility:Quinoa pricing fluctuates with Andean harvest variability and climate-induced yield compression in high-altitude growing regions.
- Supply concentration risk:Premium amaranth sourcing clusters in Mexico and Peru, creating single-origin dependency for allergen-free certified channels.
- Regulatory friction:FDA Food Safety Modernization Act allergen cross-contact protocols impose costly facility segregation requirements on multi-grain millers.
Strategic Opportunities
- Underpenetrated German craft clusters:Regional milling cooperatives in Bavaria and Baden-Württemberg retain capacity to scale heritage wheat varieties for export-qualified production.
- Regulatory tailwind:USDA and EU organic certification harmonization negotiations could unlock dual-certified margin pools for cross-Atlantic suppliers.
- Technology convergence:Near-infrared spectroscopy and blockchain traceability are combining to verify protein content and origin claims at mill intake points.
Industry Challenges
- Skill gaps in heritage grain agronomy:Farmers lack technical knowledge for non-hybridized cultivar management, threatening yield consistency for spelt and emmer contracts.
- Certification timeline compression:Three-year organic transition periods and novel food assessments by EFSA delay market entry for new varietal introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ancient and Specialty Grain Flour Market |
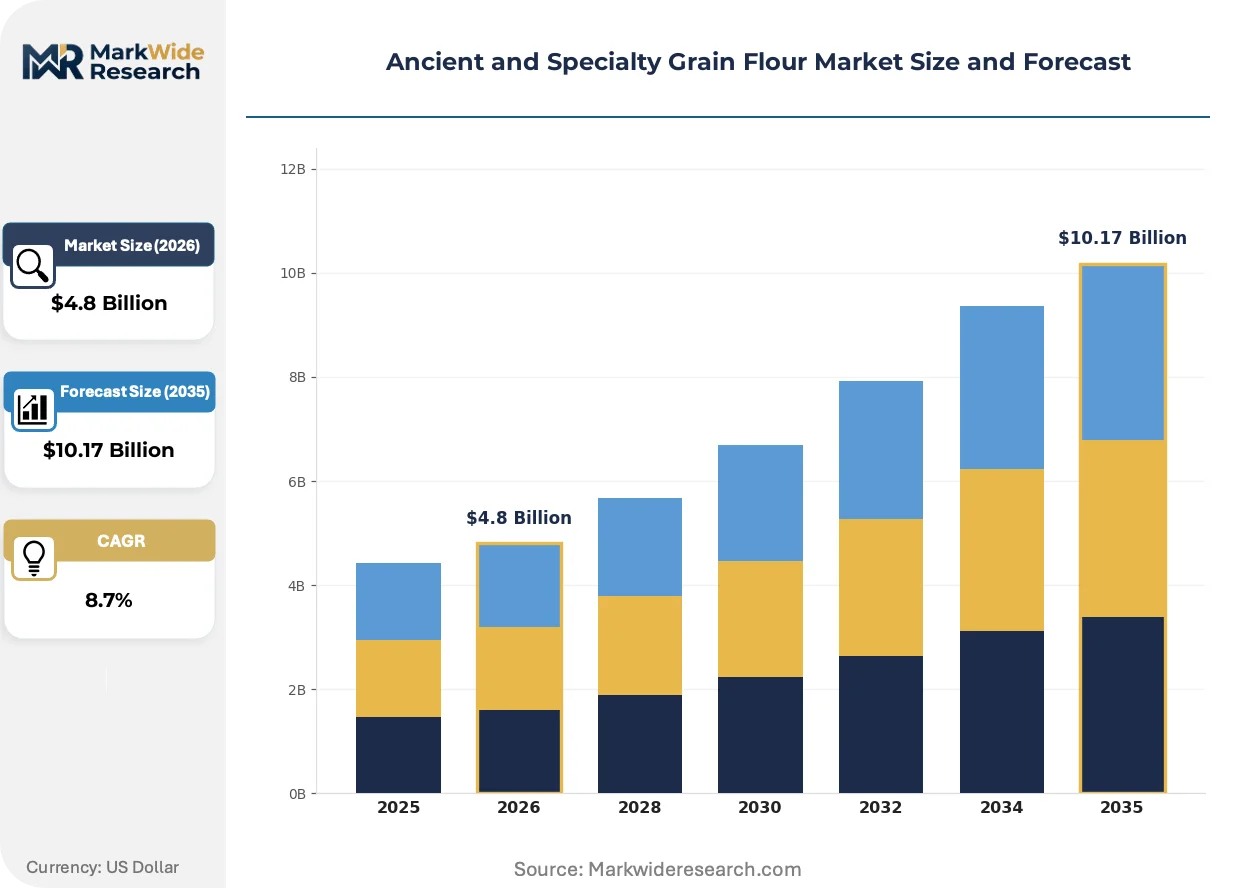
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quinoa Flour, Spelt Flour, Teff Flour, Amaranth Flour End User: Restaurants, Bakeries, Health Food Stores, Home Bakers Packaging Type: Bags, Bulk Containers, Sachets, Pouches Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Limagrain, Hain Celestial Group, General Mills, Cargill, Associated British Foods, Bob’s Red Mill, Ardent Mills, King Arthur Baking Company, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ancient and Specialty Grain Flour Market Strategic Shifts
Stone-milling technology revival and digital traceability platforms are converging to reposition heritage grains as premium inputs, while regulatory disclosure requirements reshape competitive differentiation around verified supply chain narratives.
Impact milling equipment with variable stone gap settings is absorbing quality variation across heritage wheat lots, enabling artisan millers to maintain consistent extraction rates despite non-uniform kernel sizes. Small-batch producers in Oregon and Vermont are adopting these retrofitted systems to serve clean-label bakery accounts. The technology is absorbing price premiums previously captured by industrial roller mills through narrative differentiation around "whole kernel" processing integrity.
REACH chemical safety registrations and EU Green Deal carbon-accounting rules are tightening input documentation for imported specialty grains entering European commerce. Milling facilities must now disclose agricultural chemical applications and transportation emissions across multi-tier supplier networks. German regional cooperatives are responding by consolidating backward into seed multiplication and on-farm storage to compress documentation chains.
Direct procurement relationships between craft bakeries and heritage grain cooperatives are displacing conventional distributor intermediaries in premium flour channels. Bakeries in Minneapolis, Copenhagen, and Melbourne are contracting directly with Pacific Northwest and Danish organic growers for named-variety wheat with specified protein ranges. This pattern concentrates most visibly in urban clusters where consumer education investments have preceded supply chain reconfiguration.
Ancient and Specialty Grain Flour Market Segmentation
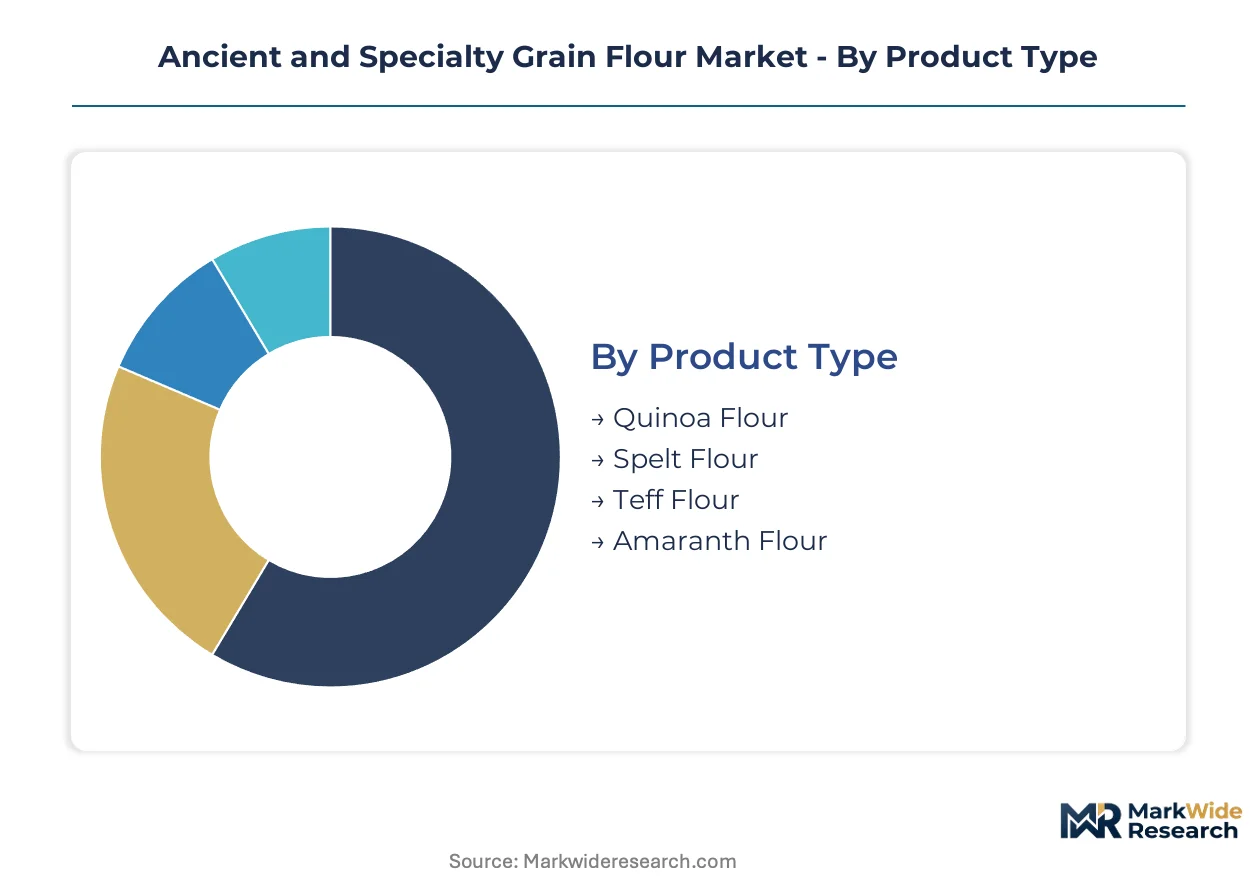
Segmentation in ancient and specialty grain flour markets reveals how capital deployment, certification requirements, and supply chain complexity concentrate margin capture across distinct product and channel configurations. Producers and investors must map these divisions to align milling capacity with the fastest-expanding demand pockets.
Product Type:
Capital intensity varies sharply across heritage grain milling, with protein-standardization equipment and allergen-segregation infrastructure driving differential upfront investment requirements.
- Quinoa Flour:Milled from saponin-stripped seed with protein content standardized between 12% and 15% through near-infrared sorting systems. Industrial bakery customers in Germany and the Pacific Northwest concentrate procurement around consistent protein specifications for gluten-free formulation trials.
- Teff Flour:Derived from the world's smallest cereal grain at less than 1mm diameter, requiring specialized dehulling and fine-grinding equipment. Ethiopian cuisine mainstreaming in North American foodservice accelerates volume expansion for injera and flatbread applications.
- Spelt Flour:Heritage wheat variant demanding stone-milling retrofits for bran retention in clean-label channels.
- Amaranth Flour:Allergen-free niche requiring dedicated facility segregation and organic certification premiums.
Quinoa flour absorbs the bulk of installed capacity; teff flour is expanding most quickly.
End User:
Customer-type segmentation exposes divergent price sensitivity and volume commitment patterns across artisan and institutional purchasing behaviors.
- Bakeries:Artisan and commercial producers drive formulation innovation through direct heritage grain contracts with specified protein ranges and named-variety traceability. Clean-label positioning in Minneapolis, Copenhagen, and Melbourne urban clusters sustains premium flour absorption.
- Restaurants:Foodservice operators integrate teff-based injera and ancient grain flatbreads into menu diversification strategies, with procurement shifting toward distributor bypass for origin-verified supply.
- Health Food Stores:Retail channel concentrating organic and non-GMO verified SKUs with substantial price premiums over conventional alternatives.
- Home Bakers:Recipe education investments by ingredient brands convert consumer familiarity into repeat purchase loyalty.
Bakeries command the deepest supplier relationships; restaurants are gaining share fastest through foodservice menu integration.
Packaging Type:
Packaging configuration directly shapes logistics economics and shelf-life extension investments across channel-specific delivery requirements.
- Bulk Containers:Industrial-scale totes and supersacks minimize per-unit handling costs for high-volume bakery and foodservice accounts with established cold-chain or climate-controlled storage.
- Bags:Standard 5-pound and 25-pound paper or woven polypropylene formats dominate retail and small commercial procurement, with oxygen-barrier liners extending shelf stability for oil-rich amaranth flour.
- Pouches:Stand-up flexible packaging with reseal features targets premium home baker segments and specialty store merchandising.
- Sachets:Single-use portion packs serve recipe trial and foodservice sampling applications with minimal waste exposure.
Bulk containers carry the highest throughput volumes; pouches are climbing the fastest on premium positioning.
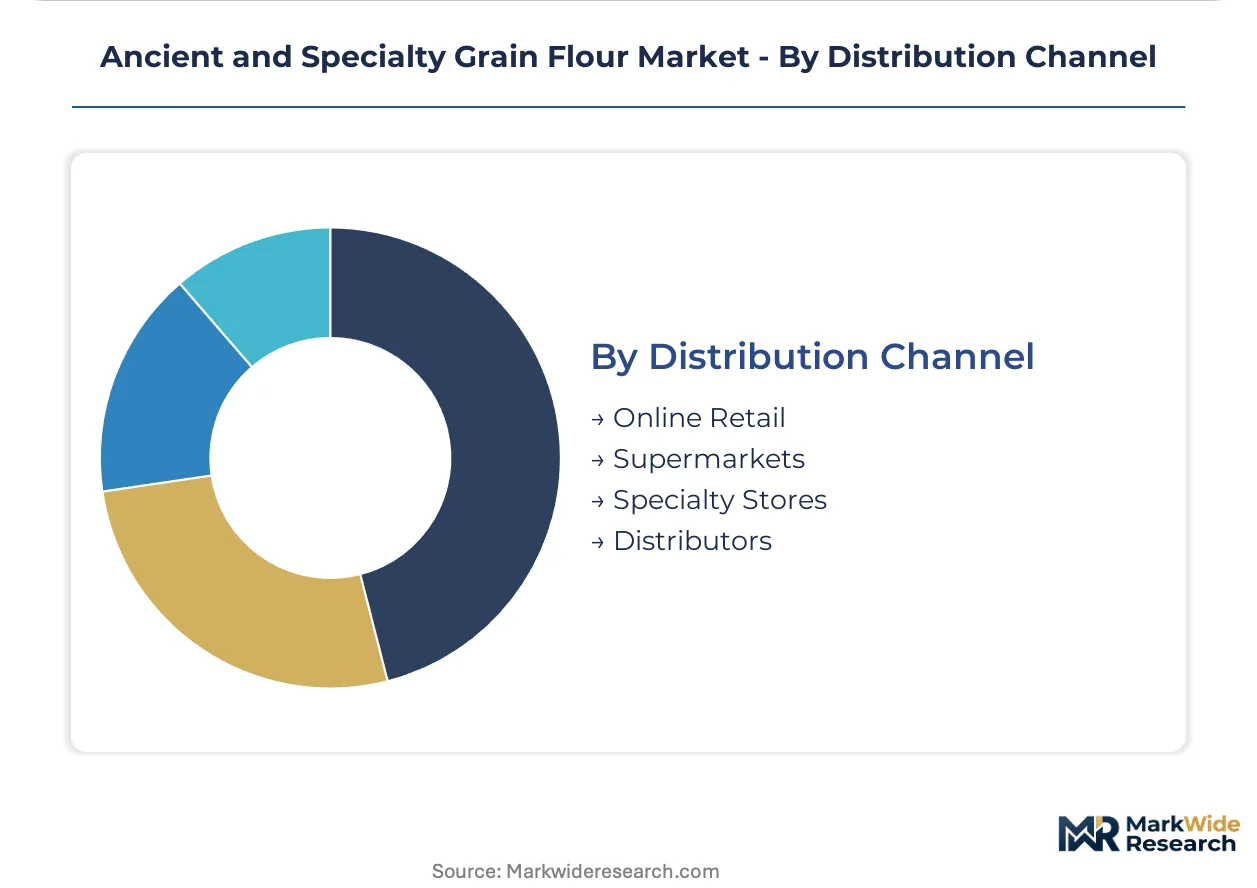
Distribution Channel:
Channel structure determines working capital intensity and margin compression exposure through intermediary layer count and direct-to-customer fulfillment requirements.
- Specialty Stores:Independent natural food retailers and co-ops sustain premium pricing through educated staff and consumer education investments that precede supply chain reconfiguration.
- Online Retail:Direct-to-consumer platforms and marketplace listings absorb growing subscription and replenishment demand, with fulfillment economics favoring multi-SKU bundling for home delivery efficiency.
- Supermarkets:Conventional grocery placement requires slotting fee investments and mass-market packaging formats that dilute heritage narrative differentiation.
- Distributors:Traditional broadline and specialty foodservice intermediaries face displacement pressure as craft bakeries consolidate direct procurement relationships with heritage grain cooperatives.
Specialty stores retain the strongest margin architecture; online retail is gaining share fastest on fulfillment convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quinoa production concentrates in Andean highlands while milling and consumption gravity pulls toward Germany and the United States. This geographic split creates trade dependencies that climate variability and EU carbon-accounting rules increasingly complicate.
Germany
Artisan bakery clusters in Bavaria and Baden-Württemberg drive heritage wheat absorption through regional milling cooperatives. EU Green Deal mandates redirect agricultural subsidies toward soil-regenerative cultivation of spelt and emmer varieties. The Stuttgart and Munich metropolitan corridors anchor premium flour distribution networks serving clean-label commercial bakers.
United States
Pacific Northwest heritage grain cooperatives supply stone-milled spelt and teff to Minneapolis and Portland craft baking clusters. FDA Food Safety Modernization Act protocols impose allergen segregation costs on multi-grain facilities in Oregon and Washington. Direct procurement relationships between urban bakeries and regional growers compress distributor margins in specialty channels.
Ethiopia
Domestic teff consumption remains substantial while export-oriented milling capacity expands for North American and European foodservice accounts. National agricultural extension programs support smallholder yield improvements for white and brown teff varieties. Addis Ababa processing facilities serve as consolidation points for injera flour bound to diaspora markets.
Peru
Andean quinoa cultivation faces climate-induced yield compression in Puno and Cusco highland provinces. REACH chemical safety registrations and EU carbon-footprint disclosure requirements tighten export documentation burdens on cooperative aggregators. Lima-based processors invest in near-infrared sorting systems to standardize protein specifications for German industrial bakery contracts.
Canada
Prairie provinces pilot heritage wheat varietal trials to diversify crop rotations beyond commodity durum and hard red spring. Health Canada and CFIA allergen labeling rules align with US FDA protocols, easing cross-border flour trade. Manitoba and Saskatchewan organic cooperatives supply amaranth to allergen-free certified channels in US Midwest metropolitan markets.
Ancient and Specialty Grain Flour Market Competitive Environment
Top-tier vendors anchor industrial-scale supply chains, while regional stone-milling specialists and employee-owned cooperatives occupy premium artisan channels. Market structure fragments across three strategic tiers: multinational agribusinesses controlling quinoa sourcing networks, heritage-focused millers emphasizing named-variety traceability, and direct-procurement cooperatives serving urban craft bakery clusters. Dominant competitive moves include backward integration into seed multiplication and on-farm storage, plus technology licensing for blockchain-verified origin claims.
Within the heritage-focused tier, Bob's Red Mill and King Arthur Baking Company exemplify divergent approaches to consumer education and supplier relationship architecture. Bob's Red Mill leverages its employee-owned structure to sustain long-term Pacific Northwest cooperative partnerships. King Arthur Baking Company anchors positioning through recipe education platforms that drive familiarity with spelt and teff. Cargill represents the industrial-scale archetype, controlling large-scale sourcing networks that supply consistent protein specifications to commercial bakery customers.
| Leading Market Players |
|---|
| Limagrain |
| Hain Celestial Group |
| General Mills |
| Cargill |
| Associated British Foods |
| Bob's Red Mill |
| Ardent Mills |
| King Arthur Baking Company |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Clean-label bakery procurement mandates for named-variety traceability and specified protein ranges are compressing supplier qualification timelines and amplifying premiums for verified heritage grain channels. German regional milling cooperatives and Pacific Northwest stone-millers absorb these premiums through direct contracting relationships that bypass conventional distributor markups.
Pricing Analysis
Short lead-time premiums for certified organic teff and amaranth flour run above contract baselines as Ethiopian and Peruvian harvest variability stretches procurement windows. Three-tier pricing structure across premium, standard, and economy levels separates certified organic heritage wheat from transitional-grade spelt and commodity-positioned quinoa. Pricing pressure stems from Andean climate-induced yield compression that tightens quinoa spot availability. Artisan bakeries show least price sensitivity through direct grower contracts; industrial bakery customers exhibit highest sensitivity to protein-standardization surcharges.
Supply Chain Analysis
Dual-sourcing qualification requirements from German industrial bakery customers and US clean-label distributors are forcing heritage grain cooperatives to maintain parallel Andean and domestic supplier relationships. Quinoa concentrates in Peru and Bolivia; teff sourcing draws from Ethiopia and domestic US trial plots; amaranth rests on Mexican and Canadian prairie production. Saponin-stripping equipment, stone-milling retrofits, and allergen-segregation infrastructure constitute critical capital dependencies. Single-origin concentration in Puno highlands creates climate-exposure vulnerability. Distribution runs through regional milling cooperatives consolidating backward into seed multiplication and on-farm storage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase as blockchain-verified origin claims and near-infrared protein spectroscopy displace paper-based traceability and manual lot testing. Stone-milling retrofits with variable gap settings are absorbing quality premiums previously captured by industrial roller mills.
For Market Incumbents: Extend backward integration into heritage wheat seed multiplication and on-farm storage to compress EU Green Deal documentation chains. Consolidate Pacific Northwest cooperative partnerships before regional capacity saturates. Invest in near-infrared sorting infrastructure to defend protein-standardization margins against Peruvian processor upgrades.
For New Entrants and Emerging Players: Blockchain-integrated traceability platforms offer entry leverage into distributor-bypass channels serving Minneapolis and Copenhagen craft bakery clusters. Target underpenetrated Bavarian regional milling cooperatives with capacity to scale emmer and einkorn for export-qualified production. Lead with subscription-based direct procurement software that automates named-variety contracting.
For Investors and Strategic Acquirers: The window for entry favors employee-owned heritage grain cooperatives with captive organic certification and established artisan bakery relationships. Long-term viability hinges on dual-certified USDA-EU organic positioning as harmonization negotiations progress. Watch EFSA novel food assessment timelines for teff varietal introductions as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Multiplication | German cooperatives compress EU Green Deal carbon-accounting documentation chains through captive cultivation. |
| Blockchain Traceability Platform Deployment | Lima-based processors verify protein content and origin claims for FDA-compliant US import channels. |
| Stone-Milling Equipment Retrofit | Oregon and Vermont millers absorb quality variation across non-uniform heritage wheat kernel sizes. |
| Direct Procurement Relationship Consolidation | Urban craft bakeries in Melbourne and Copenhagen bypass distributor intermediaries for named-variety contracts. |
| Dual-Certified Organic Capacity Expansion | Canadian prairie cooperatives position for USDA-EU harmonization unlocking cross-Atlantic margin pools. |
Study Parameters
Independent corroboration across milling cooperative managers, heritage grain agronomists, and clean-label bakery procurement leads underwrites the qualitative findings. Primary interviews with stone-mill equipment specialists, organic certification auditors, and foodservice distributor category managers combined with secondary validation from FDA Food Safety Modernization Act guidance documents, EU Green Deal agricultural subsidy disclosures, and EFSA novel food assessment registers. Bottom-up capacity estimates from regional milling facilities triangulate against top-down consumption projections across bakery, restaurant, and retail channels.
Comparable-period anchoring to historical heritage grain adoption curves in German and US Pacific Northwest markets structured the projection framework. The analysis models volume and value across product type, end user, packaging configuration, and distribution channel dimensions throughout the forecast period. CAGRs derive from segmented growth rate blending weighted by protein-standardization equipment deployment trajectories and Ethiopian cuisine mainstreaming velocity in North American foodservice.
Several conditions sit outside the modeled scope, including abrupt EU-US organic certification divergence, catastrophic Andean drought events, and rapid synthetic protein displacement in commercial bakery formulations. Deviation in EFSA novel food assessment timelines or FDA allergen cross-contact protocol enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Precooked Flour Market
Grains
Ghana Grain Market
Grains
Organic Cereals Market
Grains
Paraguay Grains Market
Grains
Grain Bins Market
Grains
Whole-Wheat Flour Market
Grains
IQF Rice Market
Grains
Asia Pacific Maize Market
Grains
Chickpeas Market
Grains
Cornmeal Market
Grains
Grain Dryers Market
Grains
Gluten Feed Market
Grains
Argentina Maize Market
Grains
United States Gluten-Free Oats Market
Grains
Triticale Market
Grains
Mesquite Flour Market