
 Non-Basmati Rice Market | 2026-2036
Non-Basmati Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Basmati Rice Market Analytics
Private-label bundling of fortified non-basmati rice with pulses and spices is realigning retail purchasing patterns across South Asian markets. LT Foods leverages its integrated milling and packaging infrastructure to supply these bundled formats to European ethnic grocers. Cargill Incorporated anchors bulk procurement contracts with African government buyers through its Geneva-based commodity trading arm. KRBL Limited differentiates via specialty aromatic non-basmati lines aimed at Middle Eastern hospitality channels.
Non-basmati rice comprises indica and japonica cultivars outside the basmati GI designation, typically exhibiting amylose content above 22 percent and kernel length under 6.5 millimeters, milled for daily consumption, industrial starch extraction, and animal feed formulation. Long grain non-basmati dominates export parity calculations due to cooking expansion ratios favored by West African and Caribbean buyers. Online retail distribution channels are recording the fastest volume growth as direct-to-consumer platforms bypass traditional mandi intermediaries in India and Bangladesh.
The Food Safety and Standards Authority of India mandates pesticide residue testing and maximum limits for cadmium and arsenic in milled rice destined for export markets. The Codex Alimentarius Commission and ISO 17025 accreditation frameworks shape laboratory certification requirements for rice-exporting nations seeking European Union market access. Stakeholders must monitor evolving maximum residue limit harmonization between ASEAN and Gulf Cooperation Council jurisdictions to preempt shipment rejections and border detention costs.
Market Dynamics
India's FSSAI pesticide residue tightening is compressing export eligibility windows, forcing millers to reconfigure procurement networks toward certified contract farming clusters in Andhra Pradesh and Telangana.
Growth Catalysts
- Fortification mandates:Government rice fortification programs in Bangladesh and the Philippines are pulling parboiled non-basmati volumes into institutional channels.
- MEE dual carbon goals:China's Ministry of Ecology and Environment is accelerating biomass gasification retrofits in rice husk-fired power generation, creating captive offtake for milling residues.
- Broken rice demand:West African brewing and starch extraction industries are expanding specification contracts for 25 percent broken varieties.
Market Restraints
- Input cost volatility:Urea and DAP fertilizer subsidies in India fluctuate with election cycles, destabilizing paddy production economics for smallholders.
- Supply concentration risk:Vietnam's Mekong Delta accounts for over half of exportable surplus, exposing buyers to salinity intrusion and upstream dam regulation.
- Technical limitation:Parboiling energy intensity locks millers into natural gas or husk-fired boilers with limited renewable alternatives.
Strategic Opportunities
- E-commerce channels:Direct-to-consumer platforms in Dhaka and Karachi are bypassing traditional mandi intermediaries, capturing margin compression.
- EU Green Deal alignment:Carbon border adjustment mechanisms are creating certification premiums for mills with ISO 14001 and renewable energy certificates.
- Ready-meal manufacturing:Southeast Asian food processors are expanding procurement of quick-cooking parboiled rice for convenience retail formats.
Industry Challenges
- ISO 17025 accreditation timelines:Laboratory certification for arsenic and cadmium testing is creating 8-12 month export approval bottlenecks.
- Skill gaps in spectral analysis:Near-infrared grain quality assessment requires trained technicians scarce in secondary milling clusters.
- Legacy ERP integration:Traceability software for FSSAI compliance conflicts with existing inventory management systems in mid-scale mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Basmati Rice Market |
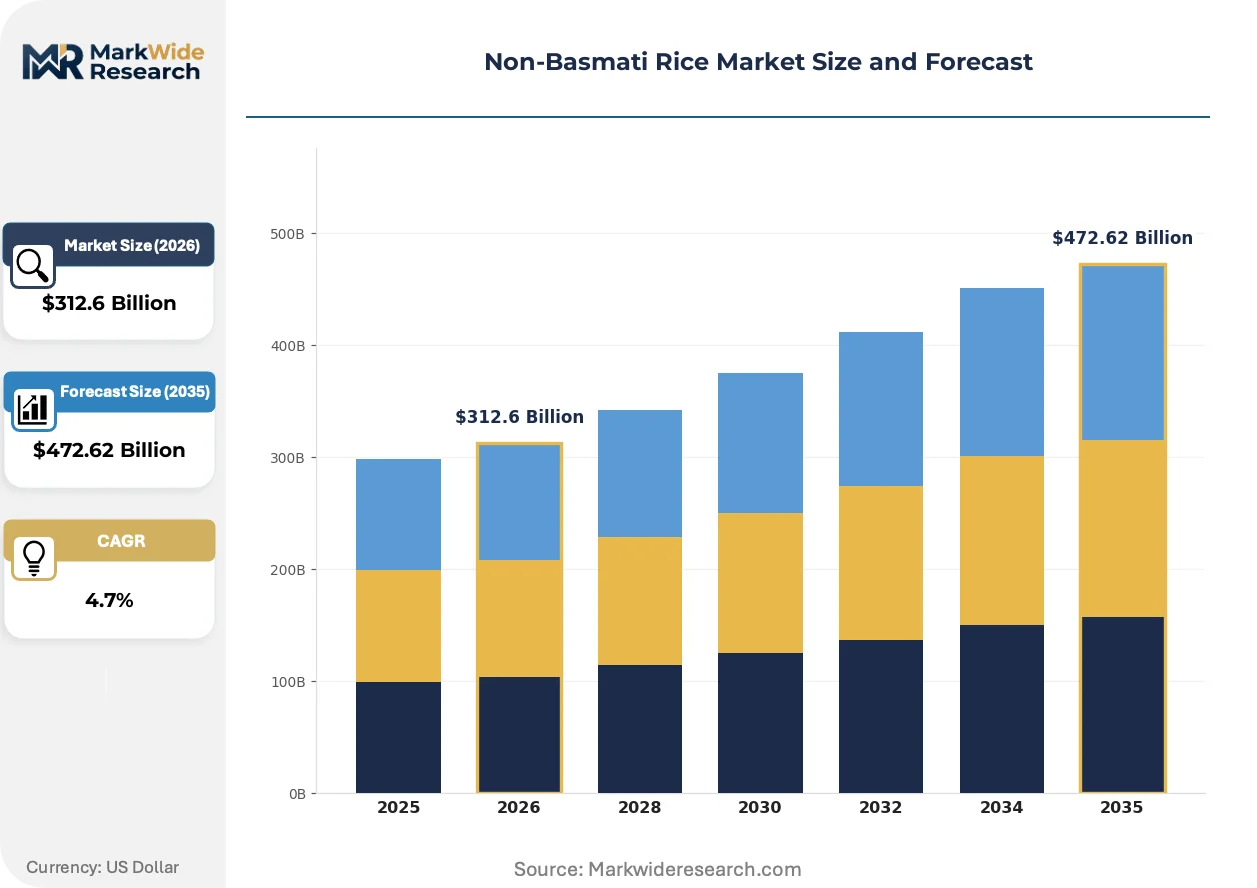
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long Grain, Short Grain, Medium Grain, Aromatic End User: Households, Restaurants, Food Processing, Catering Distribution Channel: Supermarkets, Online Retail, Wholesale, Convenience Stores Geographical Application: Domestic Consumption, Export, Institutional Use, Industrial Cooking |
| Companies Covered | Lundberg Family Farms, LT Foods, Amira Nature Foods, Shriram Food Industry Pvt. Ltd., KRBL Limited, Ebro Foods, Mars Incorporated, Cargill Incorporated, GRM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Basmati Rice Market Evolving Landscape
Digital traceability and renewable energy retrofits are compressing cost structures while regulatory compliance layers reshape competitive positioning across export corridors.
Blockchain-enabled provenance tracking is decentralizing quality verification away from centralized laboratory testing. European ethnic grocers and African government buyers are piloting distributed ledger systems for pesticide residue documentation. This architecture is decentralizing trust mechanisms, reducing border detention risk for certified consignments.
REACH authorization requirements for fumigant methyl bromide alternatives are accelerating phosphine and controlled atmosphere adoption in EU-bound shipments. Container operators and port authorities in Hamburg and Rotterdam are retrofitting ventilation infrastructure. Aromatic non-basmati lines destined for Middle Eastern hospitality channels face the steepest compliance cost escalation.
Food service distributors in Lagos and Abidjan are consolidating procurement through annual volume tenders, displacing spot market purchasing. West African import parastatals are centralizing rice buying under sovereign commodity funds. This pattern concentrates price-setting power among fewer institutional buyers, compressing trading margins for traditional brokers.
Non-Basmati Rice Market Segmentation
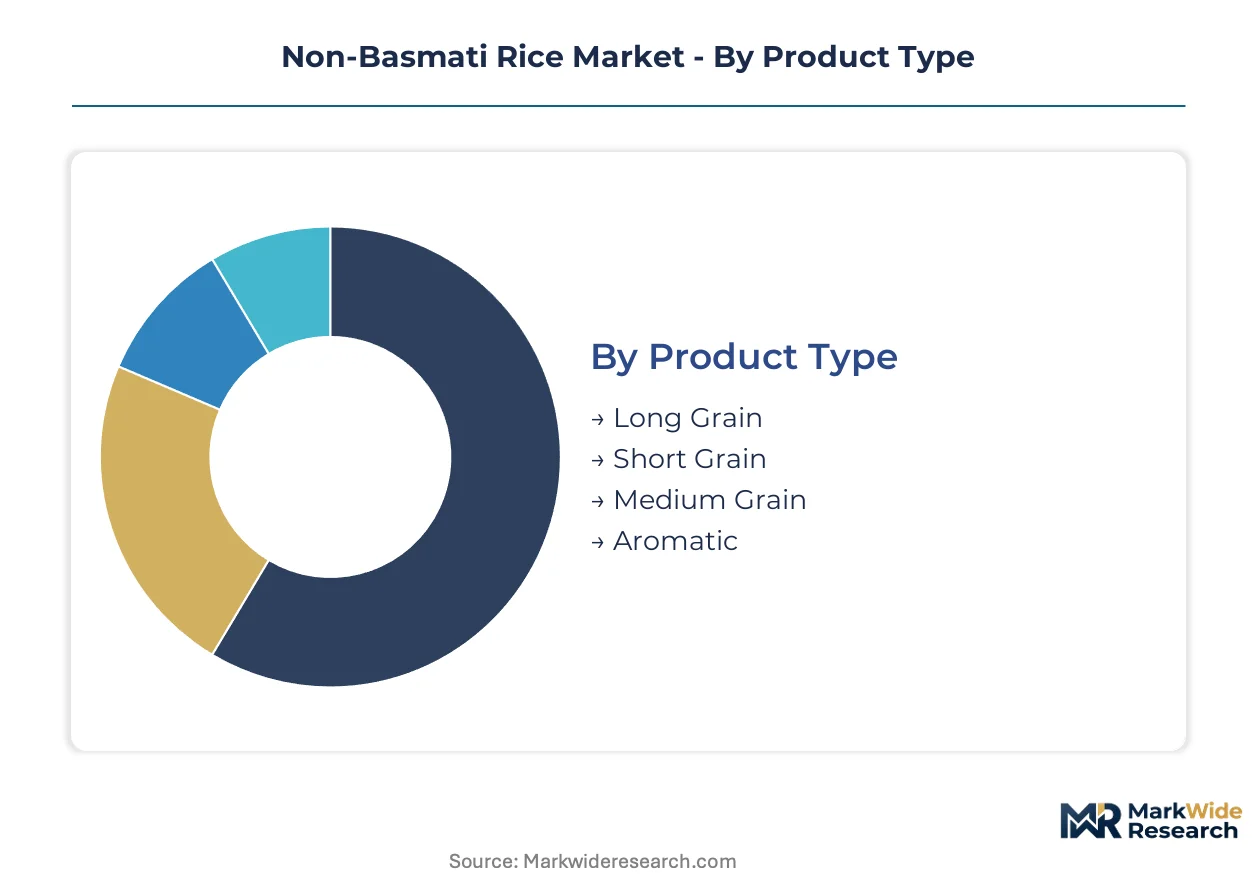
Non-basmati rice segmentation reflects divergent technical specifications and procurement logics across food service, industrial processing, and retail channels. Kernel dimensions, amylose content, and cooking properties determine suitability for specific end-uses and price realization.
Product Type:
Grain morphology and starch chemistry define functional performance in target applications.
- Long Grain:Kernel length exceeds 6.0 millimeters with amylose content above 22 percent, delivering high cooking expansion ratios preferred by West African and Caribbean buyers. Export parity calculations center on this variety due to volume concentration in Vietnamese and Indian export terminals.
- Aromatic:Distinct volatile compound profiles create premium positioning in Middle Eastern hospitality channels. Specialty lines from KRBL Limited and regional millers command price premiums through controlled varietal purity and fragrance retention protocols.
- Short Grain:Higher moisture absorption suits East Asian sticky rice applications and industrial starch extraction.
- Medium Grain:Balanced amylose-amylopectin ratio serves Latin American and Mediterranean daily consumption patterns.
Long Grain leads on scale; Aromatic leads on momentum.
End User:
Procurement scale and specification tolerance create distinct margin structures across buyer categories.
- Food Processing:Parboiled and broken rice varieties feed ready-meal manufacturing and starch extraction operations in Southeast Asia. Bangladesh and Philippine government fortification programs pull institutional volumes through tender-based procurement.
- Households:Direct-to-consumer platforms in Dhaka and Karachi are compressing traditional mandi intermediaries, accelerating volume growth in packaged retail formats.
- Restaurants:Consistency requirements and volume contracts favor established milling brands with ISO 17025 accredited quality systems.
- Catering:Price-sensitive bulk purchasing concentrates on broken grades and parboiled varieties for large-scale food service operations.
Food Processing captures the steepest expansion trajectory; Households are gaining share fastest through channel digitization.
Distribution Channel:
Channel economics determine certification requirements and working capital intensity for millers.
- Online Retail:Direct-to-consumer platforms bypass traditional intermediaries in India and Bangladesh, recording the fastest volume growth across all channels. Margin compression favors integrated milling and packaging operations.
- Wholesale:Bulk procurement contracts with African government buyers and sovereign commodity funds concentrate price-setting power among fewer institutional purchasers.
- Supermarkets:Private-label bundling with pulses and spices realigns purchasing patterns across South Asian markets, requiring flexible packaging infrastructure.
- Convenience Stores:Small-format retail in urban clusters demands localized distribution networks and working capital absorption for inventory holding.
Wholesale dominates absolute volume; Online Retail climbs the fastest on penetration gains.
Geographical Application:
Regulatory compliance layers differentiate market access requirements across destination types.
- Export:FSSAI pesticide residue limits, Codex Alimentarius frameworks, and EU Green Deal carbon border adjustments create multi-jurisdictional compliance burdens. ISO 17025 accreditation timelines generate 8-12 month approval bottlenecks for new market entrants.
- Domestic Consumption:India's internal distribution networks serve government ration programs and open market sales, with fortification mandates expanding in high-malnutrition districts.
- Institutional Use:School feeding programs and public distribution systems in Bangladesh and the Philippines specify fortified parboiled grades with micronutrient coating requirements.
- Industrial Cooking:Centralized kitchen operations for corporate campuses and hospital networks demand consistent cooking performance and traceability documentation.
Export leads on value realization complexity; Institutional Use is expanding most quickly on policy mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Non-basmati rice cultivation and milling scaled first across the Gangetic plains of India before spreading to Southeast Asian river deltas. Modern trade corridors now connect these historical production zones to West African and Middle Eastern consumption centers.
India
Andhra Pradesh and Telangana contract farming clusters supply certified pesticide-compliant paddy to export millers. FSSAI tightened maximum residue limits for exports, forcing procurement network reconfiguration. Kakinada and Visakhapatnam port terminals handle bulk shipments to African government buyers.
Vietnam
Mekong Delta milling capacity expansion serves both domestic fortification programs and cross-border trade into China and the Philippines. MEE dual carbon goals accelerate biomass gasification retrofits in rice husk-fired power generation. Can Tho and An Giang provinces concentrate parboiling infrastructure for institutional procurement.
China
Ministry of Ecology and Environment regulations drive husk residue valorization into captive energy systems. Yangtze River Delta processors import broken grades for industrial starch extraction. Hunan and Jiangxi provinces maintain strategic reserves while sourcing specialty varieties from Mekong suppliers.
Nigeria
Federal Ministry of Agriculture rice development programs reduce import dependence through local milling incentives. Lagos and Kano food service distributors consolidate procurement through annual volume tenders. Northern irrigation schemes expand paddy output for domestic parboiling operations.
Saudi Arabia
SFDA import standards shape specification requirements for aromatic non-basmati lines. Jeddah and Dammam hospitality channels drive premium positioning for fragrance-retention protocols. Sovereign commodity funds centralize bulk purchasing under unified import parastatals.
Non-Basmati Rice Market Competitive Landscape
The competitive structure tilts toward integrated milling and trading conglomerates with accredited quality systems. Tiered specialization separates bulk commodity handlers from premium aromatic specialists. Three archetypes dominate: government-contract bulk suppliers, private-label retail bundlers, and specialty hospitality channel operators. Capacity expansion in Mekong Delta clusters and backward integration into certified contract farming represent the dominant competitive moves.
Within the integrated conglomerate tier, Cargill Incorporated and Mars Incorporated occupy positions anchoring bulk procurement to African institutional buyers. KRBL Limited exemplifies the specialty aromatic archetype targeting Middle Eastern hospitality channels with controlled varietal purity protocols. LT Foods represents private-label bundling capabilities supplying European ethnic grocers with fortified rice-pulse-spice combinations.
| Leading Market Players |
|---|
| Lundberg Family Farms |
| LT Foods |
| Amira Nature Foods |
| Shriram Food Industry Pvt. Ltd. |
| KRBL Limited |
| Ebro Foods |
| Mars Incorporated |
| Cargill Incorporated |
| GRM |
| Others |
Value Network & Pricing Analysis
Government rice fortification mandates in Bangladesh and the Philippines are pulling parboiled volumes into institutional tender channels, forcing millers to absorb micronutrient coating costs and recalibrate procurement toward certified contract farming clusters that command premium paddy pricing.
Pricing Analysis
Three-tier pricing structure across premium aromatic, standard long-grain, and economy broken grades separates KRBL's fragrance-retention protocols from bulk commodity handlers. Price differentiation hinges on ISO 17025 accreditation status and FSSAI pesticide compliance certification. Cost compression in standard long-grain tiers is intensifying because African government buyers are consolidating annual volume tenders. Food processing channels show least price sensitivity due to specification rigidity, while catering operations exhibit highest elasticity to broken grade availability.
Supply Chain Analysis
Container freight rate volatility between Kakinada and Lagos is compressing trading margins for traditional brokers who lack integrated milling infrastructure. Geographic supply concentration centers on Vietnam's Mekong Delta, India's Andhra Pradesh, and Thailand's Chao Phraya basin. Raw material flows draw from urea-dependent smallholder networks, DAP-subsidized input programs, and husk-fired energy systems. Single-source vulnerability from Mekong salinity intrusion threatens exportable surplus reliability. Distribution runs through sovereign commodity funds and direct-to-consumer platforms that bypass mandi intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's tightening FSSAI residue limits and Vietnam's MEE dual carbon retrofit incentives, with compliance cost differentials reshaping competitive positioning across export corridors.
For Market Incumbents: Anticipate consolidation pressure from African government buyers centralizing procurement under sovereign commodity funds by deepening backward integration into certified contract farming in Telangana and accelerating ISO 14001 certification to capture EU Green Deal premiums. Defensive capacity positioning in Mekong Delta clusters mitigates salinity intrusion exposure. For New Entrants and Emerging Players: EU Green Deal carbon border adjustment mechanisms in Europe open a window for mills with renewable energy certificates to displace legacy competitors. White-space targets include direct-to-consumer platforms in Dhaka and Karachi, and specialty aromatic lines for Saudi hospitality channels. A go-to-market angle anchored in blockchain-enabled provenance tracking reduces border detention risk for certified consignments. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale mills possessing accredited laboratory infrastructure and flexible packaging capabilities for private-label bundling. Long-term viability favors integrated operations with captive husk energy systems and traceability software stacks. The signal to watch is FSSAI-ASEAN maximum residue limit harmonization progress as an inflection indicator for export eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | FSSAI pesticide compliance secures export eligibility windows for African government tenders. |
| Biomass Gasification Retrofit | MEE dual carbon goals in China create captive energy offtake for milling residue valorization. |
| Blockchain Provenance Implementation | Distributed ledger systems reduce Rotterdam and Hamburg border detention risk for EU-bound shipments. |
| ISO 17025 Laboratory Accreditation | Eight-to-twelve month approval timelines create competitive moats against unaccredited competitors. |
| E-commerce Platform Launch | Direct-to-consumer channels in Dhaka and Karachi compress traditional mandi intermediary margins. |
Research Methodology
Multiple input streams — primary interviews with rice mill operations heads, FSSAI regulatory compliance officers, and African government procurement directors; secondary validation through customs trade databases, FAO rice market reports, and Codex Alimentarius documentation; plus bottom-up and top-down triangulation — were reconciled to construct segment-level volume and value estimates.
Historical shipment patterns from Kakinada and Visakhapatnam terminals were cross-referenced against panel input from Mekong Delta millers and European ethnic grocer category buyers across the analysis window. Segmentation modeling incorporated grain morphology tiers, end-use procurement logics, distribution channel economics, and destination regulatory clusters. CAGRs were derived from trend extrapolation of parboiled institutional volumes and broken grade industrial demand, with biomass energy retrofit adoption curves and e-commerce penetration rates serving as industry-specific forecast inputs.
Revisions become necessary when FSSAI-ASEAN regulatory harmonization stalls, Mekong Delta salinity intrusion accelerates, or EU carbon border adjustment implementation timelines shift. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Global Wheat Market
Grains
China Maize Market
Grains
Gluten Free Ancient Grain Market
Grains
Durum Wheat Flour Market
Grains
Green Banana Flour Market
Grains
Global Cassava Flour Market
Grains
Torrified Wheat Market
Grains
Global Maize Market
Grains
GMO Corn Market
Grains
Italy Rice Market
Grains
North America Wheat Protein Market
Grains
Pea Grits Market
Grains
South America Wheat Market
Grains
Black Gram Market
Grains
Europe Wheat Protein Market
Grains
Spelt Wheat Market