
 Europe Wheat Market | 2026-2036
Europe Wheat Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wheat Market Foresight
Contract farming and grain pool financing is reconfiguring capital requirements for smaller European millers, allowing asset-light participation in wheat origination. Cargill leverages its Black Sea-to-Rotterdam logistics corridor to sustain volume leadership across soft and hard wheat grades. Roquette Frères specializes in premium wheat starch extraction, anchoring its position in the food ingredient value chain. Louis Dreyfus competes through integrated port-to-bakery supply contracts that reduce counterparty risk for industrial buyers.
Wheat is a grass-family cereal grain with protein content ranging from eight to fifteen percent depending on cultivar, primarily milled into flour for human consumption or processed into feed rations for livestock. The grain undergoes tempering, grinding, and sifting to achieve specific extraction rates that determine end-use suitability for bread, pasta, or industrial starch. Soft wheat occupies the largest volume share across European milling operations due to its dominance in cake and biscuit formulations where lower gluten strength is required. Durum wheat commands premium pricing in the pasta production segment, where semolina purity standards create a concentrated margin pool for specialized processors. Feed grade wheat is accelerating as compound feed manufacturers substitute grain for soy in rations, responding to cost volatility in oilseed markets.
EMA and EFSA frameworks govern pesticide residue thresholds and mycotoxin limits in wheat destined for food use, while REACH compliance affects agrochemical inputs across the cultivation base. The EU Green Deal's Farm to Fork Strategy is tightening nitrogen fertilizer application limits, directly shaping yield expectations and input cost structures for growers in France, Germany, and Poland. Stakeholders must monitor how the EU AI Act's deployment rules for agricultural decision-support tools will reshape precision farming adoption and grain quality prediction capabilities.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing nitrogen fertilizer application limits across French, German, and Polish wheat belts, forcing yield recalibration and input cost restructuring throughout the European cultivation base.
Growth Catalysts
- Feed Substitution:Compound feed manufacturers are accelerating wheat procurement to replace soy in livestock rations, responding to oilseed price volatility and protein demand intensification from European meat processors.
- REACH Compliance:Agrochemical input standardization under ECHA frameworks is consolidating supplier bases, favoring large-scale growers who can absorb certification and residue-testing overhead.
- Rotterdam Port Infrastructure:Black Sea-to-North Sea logistics corridors are shortening grain transit windows, enabling just-in-time milling operations across Benelux and northern France.
Market Restraints
- Nitrogen Cost Volatility:Natural gas price swings directly transmit to ammonium nitrate fertilizer costs, compressing margins for wheat growers locked into forward delivery contracts.
- Mycotoxin Thresholds:EFSA maximum residue limits for deoxynivalenol and zearalenone in food-grade wheat are disqualifying harvests from premium milling channels, forcing downgrade to feed markets.
- Maize Substitution:Feed compounders retain flexibility to pivot toward imported maize when Black Sea wheat spreads widen, capping price recovery for European feed wheat grades.
Strategic Opportunities
- Precision Agriculture Convergence:Satellite imagery and soil sensor networks are hybridizing with variable-rate nitrogen application, enabling French cooperatives to maintain yields under tightening EU fertilizer caps.
- Starch Extraction Expansion:Industrial wheat processing for modified starches and ethanol production remains underdeveloped in Poland and Romania relative to wet milling capacity in France.
- CSRD Reporting Alignment:Corporate sustainability disclosure mandates are creating procurement premiums for wheat traceable to low-carbon cultivation protocols certified under EU Green Deal frameworks.
Industry Challenges
- Grain Pool Financing Complexity:Smaller millers face working capital constraints when participating in collective origination structures, requiring new risk-sharing instruments from agricultural lenders.
- Tempering Equipment Retrofit Costs:Legacy milling infrastructure across southern European facilities requires capital-intensive upgrades to achieve extraction rates competitive with northern European operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wheat Market |
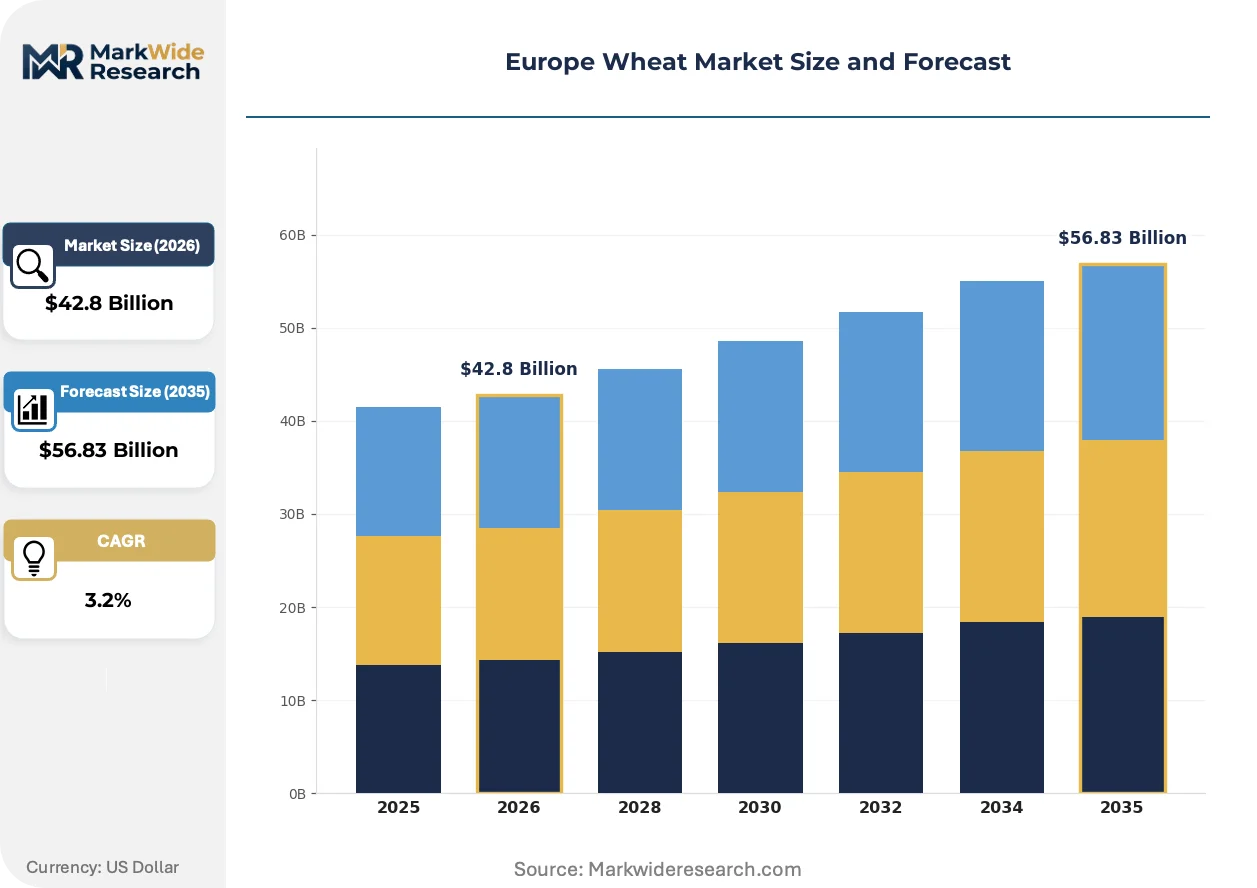
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $56.83 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Wheat, Hard Wheat, Durum Wheat, Red Wheat End Use Industry: Baking, Pasta Production, Animal Feed, Confectionery Grade: Premium, Standard, Feed Grade, Organic Packaging Type: Bags, Bulk, Pallets, Containers |
| Companies Covered | Cargill, Archer Daniels Midland, Bunge, Louis Dreyfus, AGRANA Beteiligungs-AG, Roquette Frères, Tereos SCA, Lidea, Südzucker AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wheat Market Shifts & Advancements
Digital agronomy and processing automation are compressing quality prediction timelines and reshaping how European wheat moves from field to flour, with regulatory compliance and feed substitution driving technology adoption curves.
Hyperspectral imaging systems deployed at grain intake terminals are accelerating mycotoxin and protein content detection without laboratory latency. French and German cooperatives are adopting these systems fastest, pressured by EFSA enforcement timelines. The technology is hybridizing traditional visual grading with automated sorting, enabling real-time segregation that protects food-grade premiums.
REACH authorization requirements for glyphosate and neonicotinoid alternatives are narrowing the agrochemical toolkit available to European growers. Input suppliers are reformulating product lines around biopesticide actives, though efficacy gaps persist in Fusarium control. Durum wheat cultivation in Italy and Spain faces the steepest adaptation curve due to Mediterranean climate disease pressure.
Compound feed manufacturers are consolidating wheat procurement through long-term offtake agreements directly with grain pools, bypassing traditional merchant intermediaries. This channel compression is most visible in the Netherlands and Denmark, where vertically integrated livestock operations demand price transparency and origin documentation aligned with EU Green Deal carbon accounting requirements.
Europe Wheat Market Segmentation
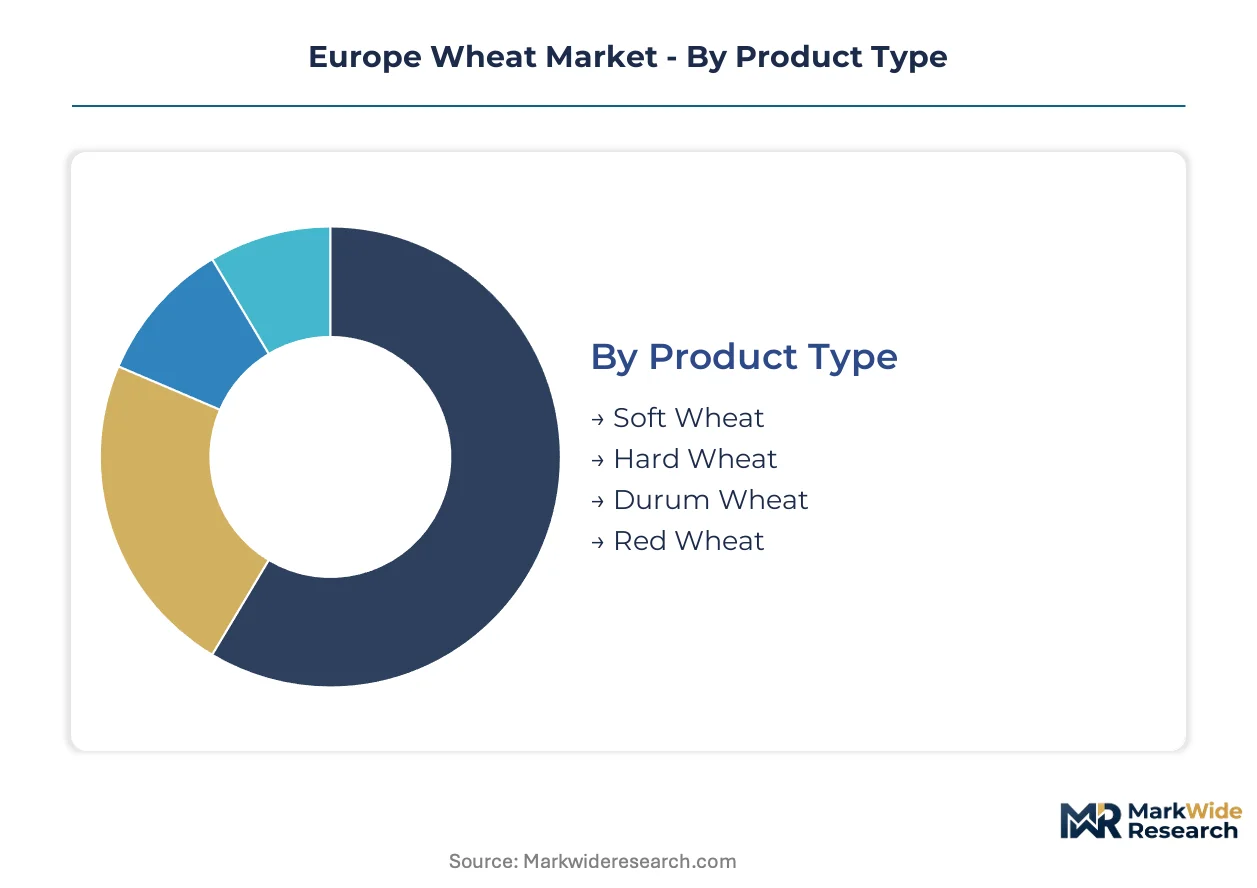
European wheat procurement patterns diverge sharply across product specifications and end-use requirements, with milling infrastructure, regulatory thresholds, and feed substitution economics creating distinct demand pools. Segmentation reveals where margin concentration and volume expansion collide across the value chain.
Product Type:
Protein content and gluten strength define the use-case spectrum from industrial baking to starch extraction and livestock nutrition.
- Soft Wheat:Lower protein content (8-11%) and weaker gluten structure suit cake, biscuit, and pastry formulations where extensibility matters more than elasticity. French millers in the Paris Basin dominate procurement volumes, leveraging established tempering infrastructure to maintain extraction rates above 75% for biscuit manufacturers in Belgium and the Netherlands.
- Hard Wheat:Higher protein (12-15%) and strong gluten networks deliver the structural integrity required for artisan and industrial bread production. German baking conglomerates along the Rhine corridor anchor demand, though EFSA mycotoxin thresholds are disqualifying increasing harvest volumes from premium milling channels.
- Durum Wheat:Amber endosperm and extreme hardness produce semolina with purity standards unmatched for pasta extrusion; Italian processors in Emilia-Romagna and Campania maintain dedicated supply contracts.
- Red Wheat:Hard red winter and spring varieties offer intermediate protein profiles for blended flour formulations; Polish cooperatives are expanding cultivation to reduce import dependency from Black Sea origins.
Established volume favors Soft Wheat; emerging adoption favors Hard Wheat as protein premiums widen under feed substitution pressure.
End Use Industry:
Customer concentration and margin stability vary dramatically across downstream applications, from price-tolerant artisan bakers to cost-sensitive feed compounders.
- Baking:Industrial bread, viennoiserie, and frozen dough production consumes the largest volume share, with French and German facilities requiring consistent gluten performance across seasonal harvest variation. REACH-compliant agrochemical documentation is becoming a procurement gate for major bakery chains.
- Pasta Production:Durum semolina purity demands create a concentrated margin pool; Italian processors pay premiums for cultivars meeting 12.5% minimum protein with ash content below 0.55%.
- Animal Feed:Compound feed manufacturers in the Netherlands and Denmark are accelerating wheat procurement to displace soy in poultry and swine rations, responding to oilseed price volatility and EU Green Deal protein self-sufficiency targets.
- Confectionery:Ultra-low ash soft wheat flours for chocolate enrobing and wafer production command specialty premiums; Belgian and Swiss processors source through dedicated grain pools.
Feed substitution is climbing the fastest as livestock processors lock in long-term offtake agreements directly with grain pools.
Grade:
Certification tier and residue compliance separate price bands more sharply than intrinsic quality differentials alone.
- Premium:EFSA-compliant food-grade wheat with deoxynivalenol below 750 ppb and full agrochemical traceability; French cooperative silos in the Beauce region dominate origination.
- Standard:Conventional milling wheat meeting basic commercial specifications without organic or carbon certification; volume concentrates in German and Polish elevator networks.
- Feed Grade:Higher mycotoxin tolerance and variable protein content acceptable for livestock rations; Black Sea imports compete directly with European originations in Rotterdam pricing.
- Organic:EU organic regulation compliance with three-year conversion protocols and prohibited synthetic inputs; Austrian and Italian growers capture scarcity premiums.
Standard grade holds volume concentration; organic certification commands the steepest premium expansion trajectory.
Packaging Type:
Logistics configuration and handling economics shape procurement decisions across containerized export, just-in-time milling, and bulk compound feed delivery.
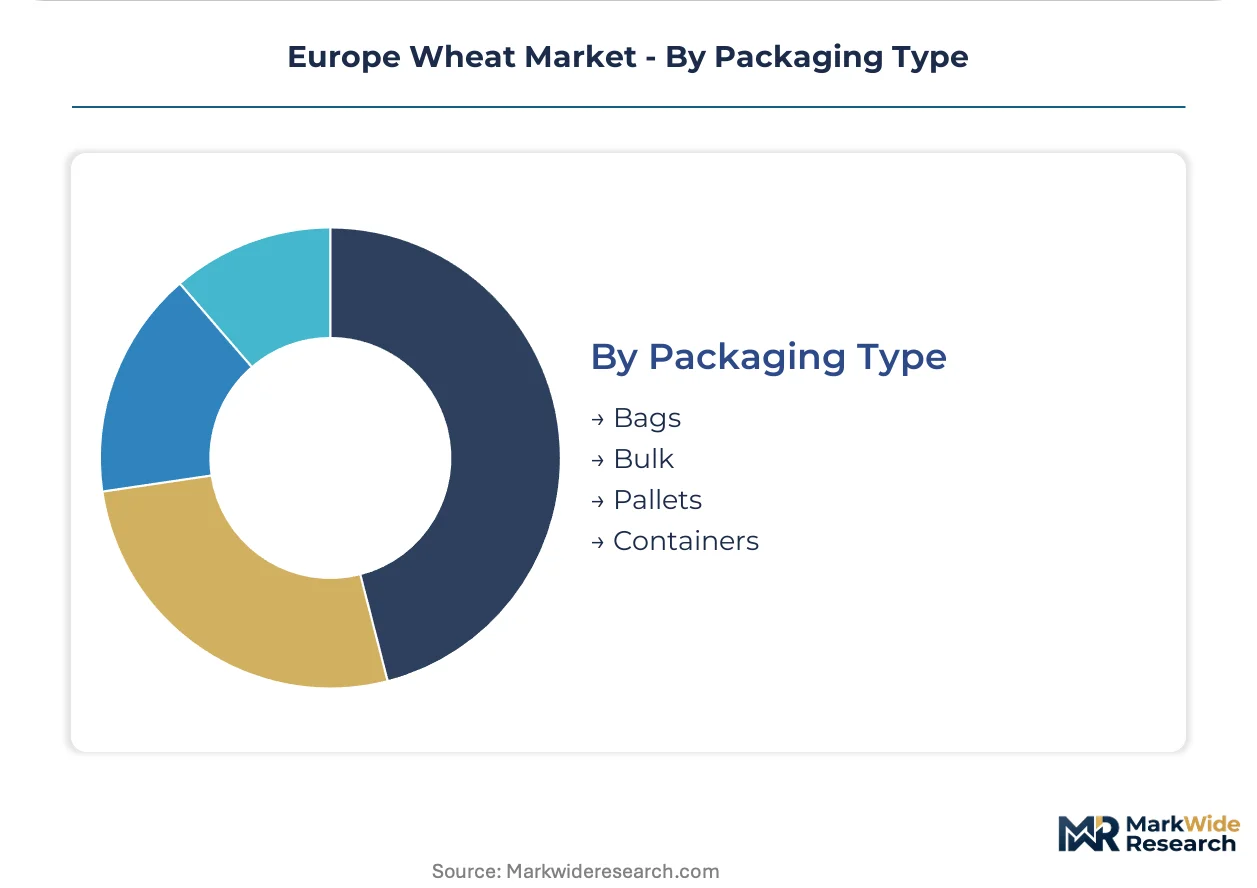
- Bulk:Unpacked grain movement via river barge and rail dominates intra-European trade, minimizing handling costs for large-scale millers with dedicated intake infrastructure.
- Containers:Sealed unitized shipment protects quality for premium food-grade exports to North African and Middle Eastern destinations; port concentration in Marseille and Rotterdam.
- Bags:25-50 kg woven polypropylene sacks serve artisan millers and specialty food manufacturers lacking pneumatic intake systems; higher per-tonne logistics cost.
- Pallets:Unitized bag stacks for confectionery and small-batch bakery procurement; limited volume share concentrated in Swiss and Austrian alpine regions.
Bulk infrastructure anchors continental volume; containerization is expanding most quickly for premium export grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's nitrogen fertilizer caps are redrawing yield geography across European wheat belts, forcing cultivation intensity adjustments and cooperative consolidation in response to tightening environmental compliance.
France
Paris Basin millers dominate soft wheat procurement for Benelux biscuit manufacturers, leveraging Beauce region silos for EFSA-compliant premium grades. The Farm to Fork Strategy's nitrogen limits are compressing application rates in Île-de-France wheat operations. Roquette Frères anchors industrial starch extraction in Lestrem, capturing value from wet milling capacity unmatched elsewhere in Europe.
Germany
Rhine corridor baking conglomerates anchor hard wheat demand for industrial bread and frozen dough production. REACH authorization requirements for glyphosate alternatives are narrowing agrochemical options for growers in North Rhine-Westphalia. Hamburg port infrastructure enables just-in-time milling operations with Black Sea grain intake competing directly against domestic origination.
Italy
Emilia-Romagna and Campania processors maintain dedicated durum supply contracts for semolina purity in pasta extrusion. Mediterranean climate disease pressure is steepening Fusarium control adaptation curves under ECHA biopesticide reformulation timelines. Naples-area millers are retrofitting tempering equipment to achieve extraction rates competitive with northern European operations.
Poland
Cooperative elevator networks in the central lowlands are expanding hard red wheat cultivation to reduce Black Sea import dependency. CSRD reporting mandates are creating procurement premiums for traceable low-carbon cultivation protocols. Łódź-region compound feed manufacturers are locking long-term offtake agreements directly with grain pools, bypassing traditional merchant intermediaries.
Netherlands
Rotterdam port infrastructure anchors Black Sea-to-North Sea logistics corridors, shortening grain transit windows for Benelux milling operations. Vertically integrated livestock operations in Gelderland demand price transparency and origin documentation aligned with EU Green Deal carbon accounting. Tereos SCA maintains processing presence, responding to feed substitution demand from Danish and Dutch poultry integrators.
Europe Wheat Market Competitive Landscape
On the supply side, the industry is consolidating around integrated trading houses with captive logistics infrastructure and specialized processors with differentiated extraction capabilities. The competitive map reveals three strategic archetypes: global grain merchants controlling port-to-mill corridors, cooperative processors with regional origination lock-in, and industrial ingredient specialists monetizing starch and protein fractionation. Dominant competitive moves include backward integration into grain pool financing structures and geographic expansion of premium export containerization capacity.
Among the integrated trading archetype, Cargill, Bunge, and Louis Dreyfus occupy positions defined by Black Sea-to-Rotterdam logistics control and port-to-bakery contract structures that reduce counterparty risk for industrial buyers. These entities exemplify scale-driven consolidation where volume throughput and working capital depth determine origination access. Cargill's corridor dominance and Louis Dreyfus's integrated supply contracts represent the template for merchant competition in European wheat procurement.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Bunge |
| Louis Dreyfus |
| AGRANA Beteiligungs-AG |
| Roquette Frères |
| Tereos SCA |
| Lidea |
| Südzucker AG |
| Others |
Supply & Pricing Matrix
Undercapacity in French Beauce region silos is tightening origination leverage for premium-grade wheat, compressing supplier flexibility while amplifying price premiums for EFSA-compliant food-grade certification.
Pricing Analysis
Certification level under EU Green Deal carbon accounting protocols creates the primary spread between procurement tiers. Three-tier pricing structure across premium, standard, and feed-grade levels reflects residue compliance thresholds and traceability documentation depth. Cost compression in standard-grade channels is intensifying because Black Sea imports compete directly at Rotterdam pricing benchmarks. Compound feed manufacturers in the Netherlands exhibit highest price sensitivity due to volume procurement and substitution flexibility toward maize, while Italian pasta processors show lowest sensitivity given semolina purity premiums.
Supply Chain Analysis
Tariff exposure between Black Sea origins and EU member states dominates supply chain risk calculus for Rotterdam port operators. Geographic supply concentrates in France, Germany, and Poland, with French Beauce cooperatives anchoring premium-grade origination. Raw material dependencies rest on ammonium nitrate fertilizer, glyphosate alternatives under REACH reformulation, and diesel fuel for inland barge logistics. Single-source vulnerability persists in specialized durum wheat cultivars for Italian semolina production. Distribution runs through river-barge networks feeding Paris Basin and Rhine corridor milling clusters, with containerized export capacity expanding at Marseille for North African destinations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe wheat procurement sits in early-cycle expansion as feed substitution accelerates and precision agriculture adoption penetrates French cooperative networks.
For Market Incumbents: Harden origination control through backward integration into grain pool financing structures, locking working capital partnerships with agricultural lenders serving smaller millers. Expand containerized export capacity at Marseille and Rotterdam to capture North African and Middle Eastern premium demand. Defensive positioning requires countering merchant intermediary disintermediation by compound feed manufacturers in the Netherlands and Denmark. For New Entrants and Emerging Players: Pursue industrial starch extraction expansion in Poland and Romania, where wet milling capacity remains underdeveloped relative to French operations. White-space concentration sits in CSRD-aligned low-carbon cultivation certification services for German and Polish cooperatives. Go-to-market execution should anchor on direct grain pool partnerships with Łódź-region compound feed manufacturers, bypassing traditional merchant channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision agriculture hardware and hyperspectral imaging terminal deployment. Long-term viability through the projection horizon favors processors with differentiated extraction capabilities and captive logistics infrastructure. Acquisition targets should screen for cooperative processors with regional origination lock-in and EFSA-compliant certification depth. The signal to monitor is EU AI Act deployment rules reshaping agricultural decision-support tool adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Pool Financing | Cargill and Louis Dreyfus structure working capital partnerships that lock origination access for smaller millers. |
| Hyperspectral Imaging Terminal Deployment | French cooperatives accelerate mycotoxin detection without laboratory latency, protecting food-grade premiums. |
| CSRD-Aligned Certification Investment | Polish and German growers capture procurement premiums through traceable low-carbon cultivation protocols. |
| Containerized Export Capacity Expansion | Rotterdam and Marseille port operators shorten transit windows for North African premium-grade destinations. |
| Precision Agriculture Convergence | Satellite imagery and soil sensor networks enable French cooperatives to maintain yields under EU fertilizer caps. |
Research Methodology
The analysis maps soft wheat, hard wheat, durum wheat, and feed-grade procurement channels, each validated through cooperative elevator managers, port logistics operators, and compound feed procurement leads. Primary interviews with French millers, German baking conglomerate supply chain directors, and Italian pasta processor sourcing heads combined with secondary validation from EFSA residue threshold documentation, EU Green Deal Farm to Fork Strategy filings, and REACH authorization timelines. Customs data from Eurostat trade flows and cooperative silo capacity reports anchored bottom-up volume estimates against top-down consumption modeling.
Assumptions held nitrogen fertilizer application limits and EFSA mycotoxin thresholds fixed across the modeling period, while feed substitution elasticity and precision agriculture adoption rates varied by scenario. Segmentation dimensions modeled include protein content tier, end-use industry concentration, grade certification level, and packaging logistics configuration. CAGRs derived from trend extrapolation of historical procurement volumes adjusted for regulatory yield compression and input cost restructuring. Industry-specific forecast inputs incorporated Black Sea import spread volatility and Rotterdam port throughput capacity utilization.
Sensitivities concentrate around EU AI Act deployment timelines for agricultural decision-support tools and REACH authorization outcomes for glyphosate alternatives. Forecasts reflect documented assumptions about feed substitution permanence and carbon accounting protocol adoption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Colombia Grains Market
Grains
Non-Basmati Rice Market
Grains
Cultured Wheat Market
Grains
Global Grain Analysis Market
Grains
White Rice Flour Market
Grains
India Rice Market
Grains
Global Maize Market
Grains
South Africa Grain Market
Grains
Asia-Pacific Wheat Market
Grains
GMO Corn Market
Grains
Triticale Market
Grains
Mexico Rice Market
Grains
Rolled Oats Market
Grains
Spain Rice Market
Grains
Global Oats Market
Grains
Cameroon Grains Market