
 Myanmar Maize Seed Market | 2026-2036
Myanmar Maize Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Myanmar Maize Seed Market Foresight
Myanmar's National Seed Policy is expanding compliance requirements for varietal registration and field performance testing. Charoen Pokphand Group leverages its integrated feed-to-farm operations to secure captive demand for certified hybrid seeds. Myanma Awba Group anchors its position through deep rural distribution networks spanning the central dry zone. East-West Seed competes on tropical maize germplasm adapted to Myanmar's monsoon variability.
Maize seed comprises reproductive propagules selected for specific agronomic traits including yield potential, disease resistance, and moisture stress tolerance, typically produced through controlled pollination or biotechnological enhancement for commercial crop establishment. Hybrid seeds dominate value capture due to farmer willingness to pay for yield consistency and drought tolerance in rainfed systems. Open-pollinated varieties retain volume share among subsistence growers in Shan State who save and replant farm-sourced seed. Agrochemical Stores as a distribution channel concentrate margin pools through credit-linked input bundling that locks in repeat purchases across growing seasons.
The Department of Agricultural Research enforces field inspection protocols and minimum germination standards that filter uncertified seed from formal channels. BIS-aligned seed testing laboratories in Yangon and Mandalay verify genetic purity and seed health metrics for imported germplasm. Stakeholders must monitor how the country's national seed regulator balances varietal import approvals against domestic breeding capacity investments.
Market Dynamics
The Department of Agricultural Research is tightening field inspection protocols and minimum germination standards, forcing seed companies to upgrade laboratory capabilities and traceability systems across the Mandalay-Sagaing corridor.
Growth Catalysts
- Livestock Feed Expansion:Commercial poultry and pig operations in the central dry zone are scaling maize offtake volumes. This captive demand pull incentivizes farmers to switch from saved seed to certified hybrid varieties.
- Irrigation Infrastructure:State-led canal rehabilitation in Sagaing Region is converting rainfed plots to irrigated systems. Irrigated maize commands higher seed investment due to yield predictability.
- Seed Certification Framework:The national seed policy is expanding varietal registration requirements. Compliance investments by distributors are filtering counterfeit seed from formal agrochemical store channels.
Market Restraints
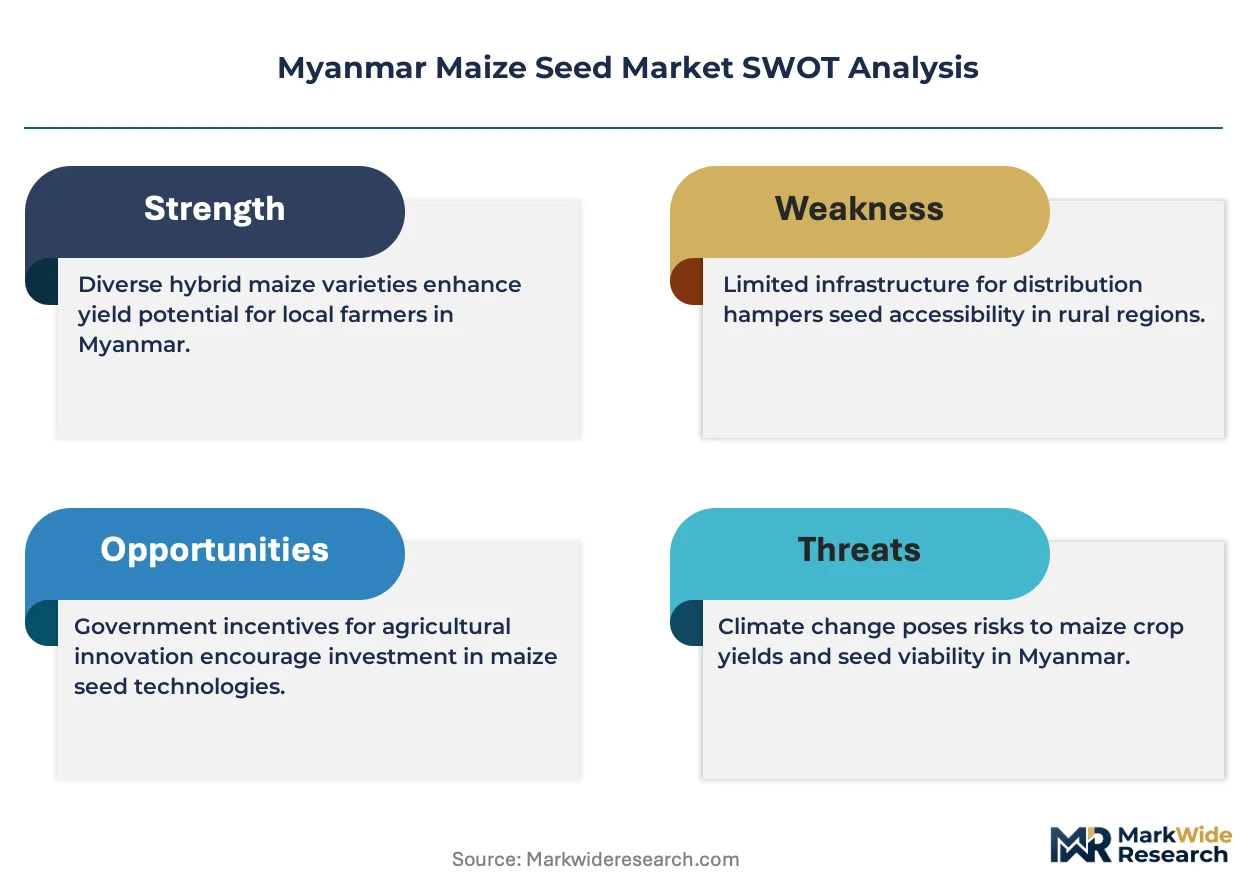
- Import Dependency for Parent Lines:Domestic breeding programs lack proprietary inbred germplasm. Reliance on Thai and Vietnamese parent seed exposes multipliers to foreign exchange volatility and shipping delays.
- Subsistence Seed Saving:Shan State smallholders persistently replant farm-sourced open-pollinated varieties. This behavior caps hybrid penetration in Myanmar's largest maize-producing state.
- Limited Cold Chain for Seed Storage:Ambient warehouse conditions in rural townships accelerate seed viability loss. Germination rates deteriorate before planting season arrives.
Strategic Opportunities
- Chin State Highland Expansion:Elevated terrain in northern Chin remains underpenetrated for commercial maize. Cold-tolerant hybrid germplasm adapted to shorter growing seasons could unlock this geography.
- Credit-Linked Input Bundling:Agrochemical stores are piloting digital ledger systems tying seed purchases to fertilizer and crop protection advances. Embedded finance deepens farmer lock-in.
- Tissue Culture Rapid Multiplication:Laboratory-based breeder seed production could compress the three-year foundation seed cycle. This technology convergence reduces field contamination risks.
Industry Challenges
- Field Inspection Capacity Bottlenecks:The Department of Agricultural Research employs insufficient qualified inspectors to cover peak planting windows in remote townships. Certification backlogs delay commercial release.
- Genetic Purity Verification Costs:BIS-aligned laboratories in Yangon and Mandalay charge prohibitive fees for protein electrophoresis testing. Small-scale multipliers struggle to absorb compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myanmar Maize Seed Market |
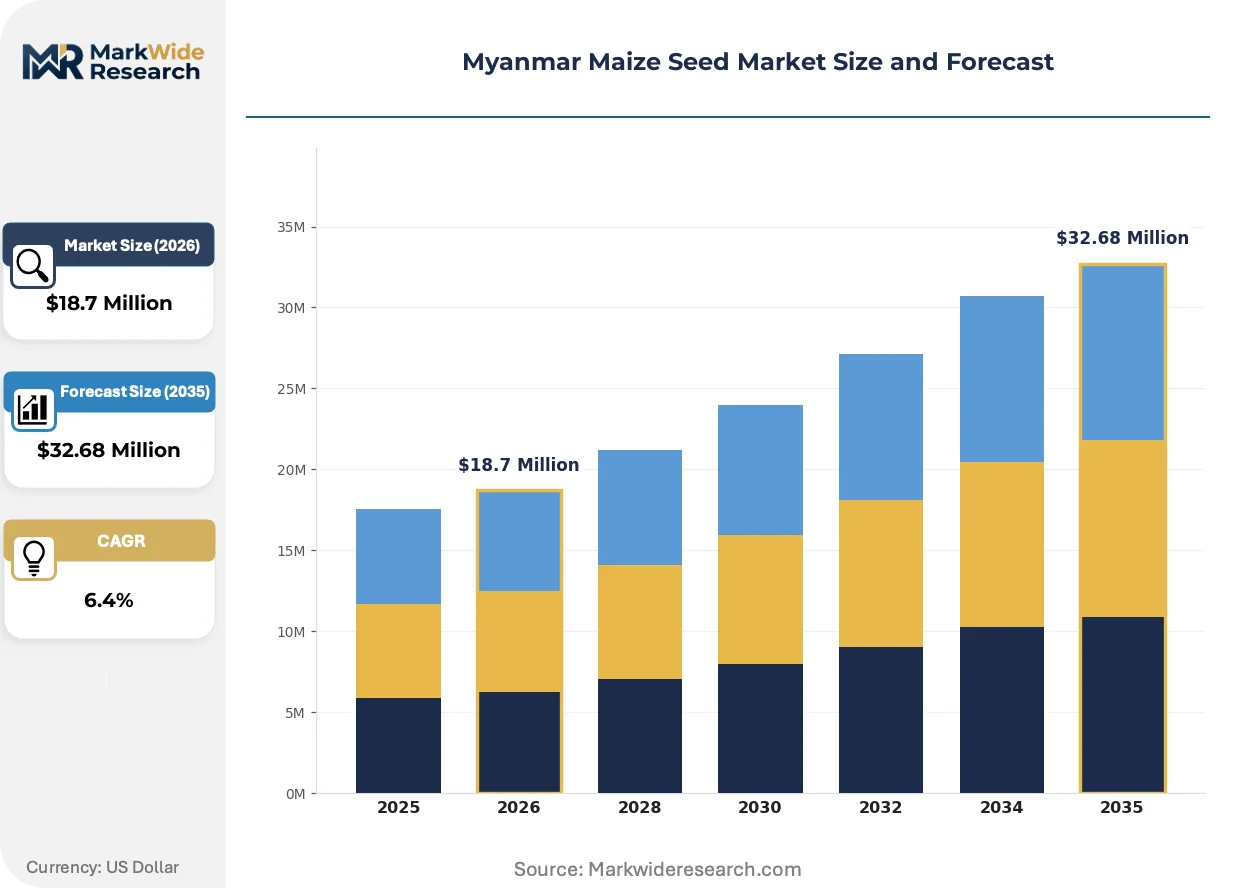
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $32.68 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Open-Pollinated Varieties, GM Seeds, Seed Coatings End User: Farmers, Agricultural Cooperatives, Seed Distributors, Research Institutions Distribution Channel: Online Retailers, Agrochemical Stores, Farmer Cooperatives, Direct Sales Packaging Type: Bulk Bags, Retail Packs, Foil Packs, Custom Sizes |
| Companies Covered | Charoen Pokphand Group, Myanma Awba Group, East-West Seed, Corteva Agriscience, Groupe Limagrain, Syngenta AG, Dagon Group, UPL Limited, Known-You Seed, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myanmar Maize Seed Market Shifts & Advancements
Digital traceability platforms and climate-adaptive germplasm are restructuring how seed quality is verified and how farmers select varieties across Myanmar's fragmented distribution landscape.
Blockchain-enabled seed authentication is decentralizing quality verification away from centralized laboratory testing. Agrochemical store networks in Magway Region are piloting QR-code verification systems that link seed packets to field inspection records. This technology is decentralizing trust mechanisms from government certification bodies toward distributed ledger transparency.
The Department of Agricultural Research is harmonizing varietal registration protocols with ASEAN seed trade standards. This regulatory alignment reduces duplicate field testing for imported Thai and Vietnamese hybrids. Multi-national seed firms are responding by accelerating variety submission pipelines for the Myanmar market.
Farmer buying patterns are compressing toward consolidated input purchases through single-channel credit relationships. Independent village-level retailers in the central dry zone are losing share to agrochemical store chains offering bundled seed-finance-technical advisory packages. This shift is most pronounced in irrigated pockets of Mandalay Region where commercial maize density supports dedicated agronomist staffing.
Myanmar Maize Seed Market Segmentation
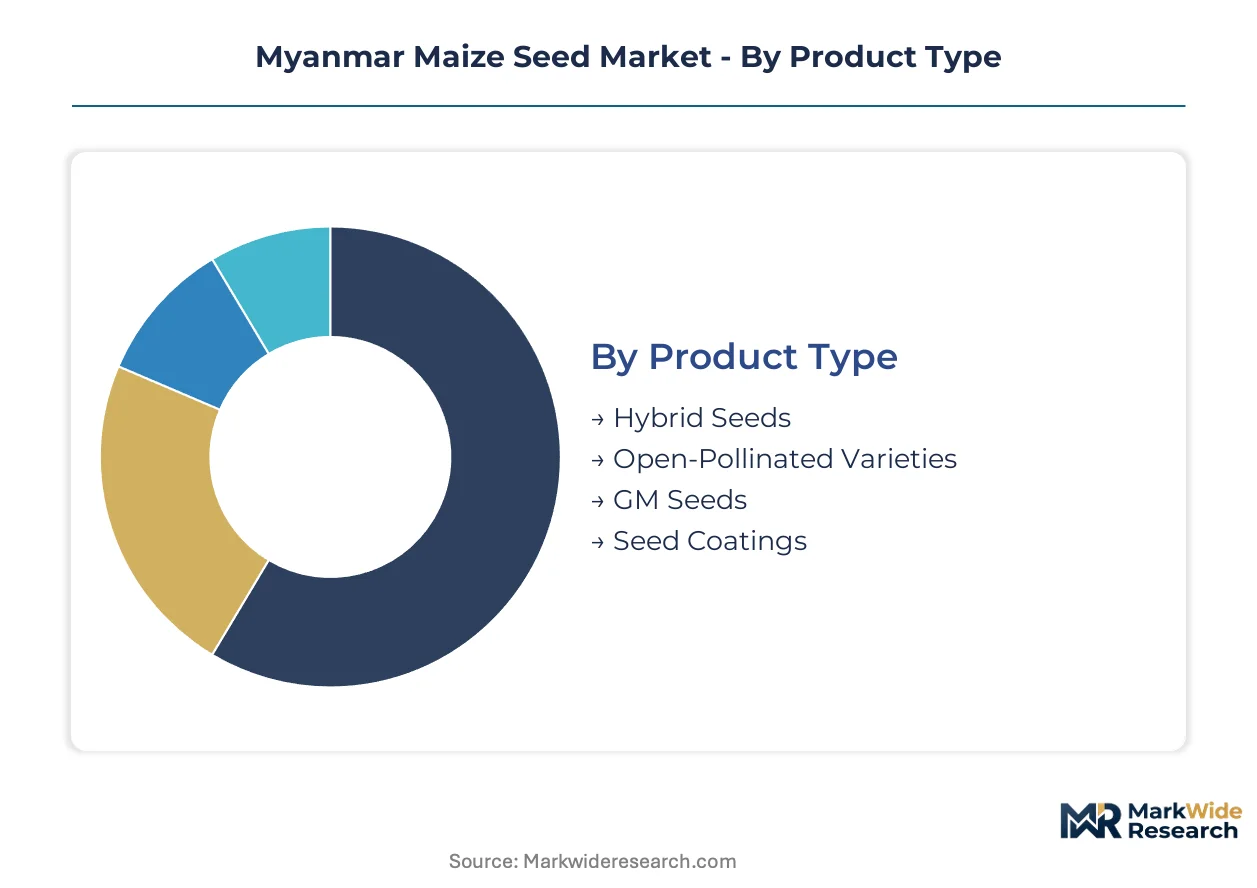
Myanmar's maize seed market fragments across product technologies, buyer types, and distribution infrastructure. Each segmentation layer reveals distinct margin pools and upgrade pathways as the country's seed certification framework tightens.
Product Type:
Farmer upgrade cycles from saved seed to certified purchases reshape product mix dynamics across Myanmar's central dry zone and Shan State highlands.
- Hybrid Seeds:Controlled cross-pollination between inbred lines produces high-yielding F1 progeny with standardized agronomic performance. Demand concentrates in the Mandalay-Sagaing corridor where irrigated commercial farms prioritize yield consistency and drought tolerance.
- Open-Pollinated Varieties:Naturally pollinated populations maintain genetic diversity through successive generations, enabling farmer seed saving. Subsistence growers in Shan State dominate this segment, constrained by limited capital for annual seed purchases and weak distribution reach into remote townships.
- GM Seeds:Biotechnologically enhanced germplasm with engineered insect resistance or herbicide tolerance traits. Regulatory approvals through the Department of Agricultural Research remain limited, restricting commercial availability to pilot demonstration plots.
- Seed Coatings:Polymer or biological treatments applied to seed surfaces for moisture retention, pathogen protection, or nutrient priming. Agrochemical store channels bundle coated seeds with crop protection packages in Magway Region.
Hybrid seeds sit at the top of the volume ranking, with seed coatings climbing the fastest as input bundling deepens.
End User:
Buyer sophistication tiers determine pricing power and technical service requirements across Myanmar's fragmented agricultural landscape.
- Farmers:Individual cultivators ranging from subsistence smallholders to commercial operators managing multiple hectares. Irrigated pockets of Mandalay Region generate concentrated demand for certified hybrid purchases backed by agronomist support.
- Agricultural Cooperatives:Collective purchasing entities aggregating member demand for volume discounts and shared storage infrastructure. These groups anchor procurement in the central dry zone where maize density justifies consolidated logistics.
- Seed Distributors:Licensed multipliers and wholesalers operating under Department of Agricultural Research certification protocols. Quality verification bottlenecks constrain expansion beyond Yangon and Mandalay laboratory catchment areas.
- Research Institutions:Public breeding programs and international germplasm evaluation networks. Limited domestic breeding capacity keeps these actors dependent on Thai and Vietnamese parent line imports.
Farmers command the dominant share of transaction volume, with agricultural cooperatives expanding most quickly as credit-linked input bundling spreads.
Distribution Channel:
Channel configuration determines working capital intensity and farmer loyalty mechanisms across Myanmar's rural township network.
- Agrochemical Stores:Branded retail chains offering bundled seed-fertilizer-credit packages with embedded technical advisory. These outlets capture premium positioning in irrigated commercial zones through repeat purchase lock-in.
- Farmer Cooperatives:Member-owned procurement collectives leveraging aggregated demand for manufacturer-direct pricing. Storage infrastructure gaps limit their geographic reach to central corridor townships with reliable road access.
- Direct Sales:Seed company field staff engaging large commercial farms for volume contracts. This channel bypasses distributor margins but requires dedicated agronomist staffing that only major hybrids players sustain.
- Online Retailers:E-commerce platforms and mobile-based ordering systems with township-level delivery aggregation. Digital payment penetration and seed viability concerns during ambient-temperature shipping constrain adoption outside urban peripheries.
Agrochemical stores hold the volume leadership position, with direct sales gaining share fastest among commercial farm consolidation.
Packaging Type:
Packaging specifications align with buyer scale and storage infrastructure availability across Myanmar's climatic zones.
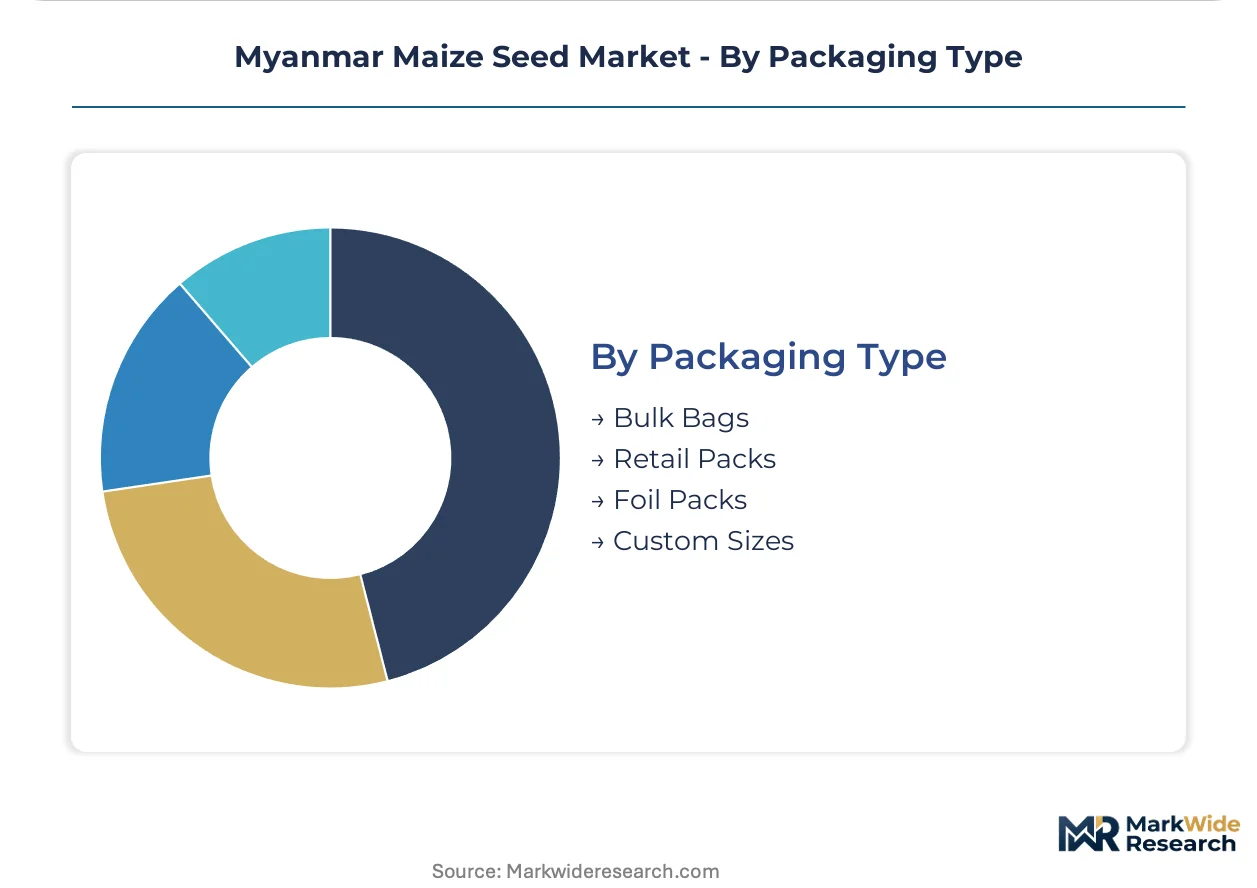
- Retail Packs:Small-unit sachets and pouches targeting smallholder trial purchases and varietal diversification. These formats dominate agrochemical store shelves in Shan State where capital constraints limit bulk commitments.
- Bulk Bags:Large-volume woven polypropylene containers for cooperative and commercial farm procurement. Mandalay Region's irrigated blocks generate concentrated demand for tonnage-scale deliveries with mechanized handling.
- Foil Packs:Metallized barrier films providing moisture and oxygen protection for high-value hybrid germplasm. Premium positioning in this format responds to ambient warehouse conditions that accelerate viability loss.
- Custom Sizes:Contract-manufactured packaging specifications for institutional buyers and export-oriented multiplication programs. Lead time requirements and minimum order quantities restrict accessibility to well-capitalized distributors.
Retail packs lead transaction frequency, with bulk bags expanding most quickly as cooperative aggregation strengthens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Myanmar's maize seed industry traces its commercial roots to the central dry zone's irrigation investments during the 1990s, when Thai and Vietnamese germplasm first penetrated through cross-border trade corridors. The Mandalay-Sagaing corridor remains the historical anchor, though production geography now fragments across multiple agro-ecological zones.
Mandalay Region
Irrigated commercial blocks in Mandalay command premium seed investments from poultry feed operations scaling throughout the central dry zone. The Department of Agricultural Research maintains its primary seed certification laboratory here, enforcing field inspection protocols that filter counterfeit germplasm from formal channels. Meiktila and Myingyan townships cluster the highest density of certified hybrid multiplication plots.
Sagaing Region
State-led canal rehabilitation is converting rainfed maize plots to irrigated systems, elevating farmer willingness to pay for drought-tolerant hybrid varieties. The national seed policy's expanded varietal registration requirements apply with particular stringency in this emerging production belt. Monywa and Shwebo districts anchor seed distributor networks extending credit-linked input bundling to commercial growers.
Shan State
Subsistence smallholders dominate this highland geography, persistently replanting farm-sourced open-pollinated varieties that cap hybrid penetration. Weak distribution infrastructure into remote townships reinforces seed-saving behavior despite yield penalties. Taunggyi and Kalaw serve as limited commercial nodes where agrochemical store chains maintain skeletal presence.
Magway Region
Agrochemical store networks pilot QR-code verification systems here, decentralizing seed quality trust mechanisms through blockchain-enabled authentication. The national seed certification framework's compliance investments concentrate margin pools among branded retail chains. Pakokku and Magway city anchor this digital traceability experimentation.
Chin State
Elevated northern terrain remains underpenetrated for commercial maize, presenting expansion opportunities for cold-tolerant hybrid germplasm adapted to shorter growing seasons. Limited road infrastructure constrains seed viability during ambient-temperature transport from multiplication zones. Hakha and Falam townships represent frontier markets where direct sales channels bypass distributor infrastructure entirely.
Myanmar Maize Seed Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification compliance and technical advisory capabilities, with the market structuring into three discernible tiers. Charoen Pokphand Group anchors the integrated feed-to-farm tier through captive demand pull from commercial livestock operations. Specialist hybrid breeders occupy the mid-tier, competing on tropical germplasm adaptation and drought tolerance traits. Commodity traders and uncertified seed multipliers populate the bottom tier, eroding price discipline through informal channel leakage. Dominant competitive moves include backward integration into parent line breeding and geographic expansion into underpenetrated highland zones.
Among Thai-origin conglomerates with integrated agribusiness operations, Charoen Pokphand Group exemplifies the feed-to-farm archetype that locks in seed demand through captive offtake agreements. Myanma Awba Group occupies a position within the domestic distribution specialist tier, leveraging deep rural networks across the central dry zone to aggregate smallholder demand. East-West Seed represents the tropical germplasm specialist archetype, competing on variety portfolios adapted to monsoon variability and rainfed system constraints. These three anchors illustrate how competitive positioning fragments across integration depth, geographic density, and trait specialization vectors.
| Leading Market Players |
|---|
| Charoen Pokphand Group |
| Myanma Awba Group |
| East-West Seed |
| Corteva Agriscience |
| Groupe Limagrain |
| Syngenta AG |
| Dagon Group |
| UPL Limited |
| Known-You Seed |
| Others |
Supply & Pricing Matrix
Captive backward integration into parent line breeding anchors both supply security and pricing power for integrated Thai conglomerates operating across the Mandalay-Sagaing corridor. This structural choice insulates Charoen Pokphand Group from foreign exchange volatility that squeezes margin for distributors dependent on Vietnamese and Thai germplasm imports.
Pricing Analysis
Three-tier pricing structure across certified hybrid, foundation seed, and farm-saved open-pollinated varieties dominates transaction economics. Price differentiation hinges on Department of Agricultural Research certification tier and bundled technical advisory intensity. Cost compression in the uncertified tier is intensifying because counterfeit seed leakage erodes formal channel discipline. Subsistence smallholders in Shan State exhibit highest price sensitivity, while irrigated commercial operators in Mandalay Region absorb premium positioning for drought-tolerant genetics.
Supply Chain Analysis
Dual-sourcing requirements for parent line germplasm mandate qualification across Thai and Vietnamese breeding programs, with Chinese genetic material emerging as tertiary option. The supply chain draws from Bangkok and Ho Chi Minh City multiplication zones, with foundation seed cycling through Yangon and Mandalay laboratory verification. Single-source vulnerability concentrates in proprietary inbred lines controlled by multinational breeders. Distribution runs through agrochemical store chains offering credit-linked input bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Myanmar's maize seed market functions as a geographic-arbitrage play where Thai and Vietnamese breeding expertise commands premium positioning against domestic multiplication cost advantages. Regulatory alignment gaps between ASEAN seed trade standards and Department of Agricultural Research protocols create compliance cost differentials favoring established regional players.
For Market Incumbents: Deepen laboratory capabilities in Mandalay and Yangon to compress genetic purity verification turnaround times threatened by Department of Agricultural Research inspector capacity bottlenecks. Anchor channel control through exclusive credit relationships with agrochemical store chains in the central dry zone. Prioritize in-house parent line breeding investments to reduce Thai and Vietnamese germplasm dependency. For New Entrants and Emerging Players: Enter via cold-tolerant hybrid development targeting Chin State highland expansion where established distribution networks remain skeletal. The underpenetrated northern terrain offers lowest competitive density for shorter-season germplasm. Deploy direct sales agronomist teams to bypass agrochemical store margin capture entirely. For Investors and Strategic Acquirers: Roll-up economics work for domestic distribution specialists with deep rural township networks because seed certification compliance investments are filtering uncertified competitors from formal channels. Target acquisition archetypes include Mandalay-based multipliers with established Department of Agricultural Research relationships. Watch seed inspection protocol harmonization with ASEAN standards as inflection indicator for import substitution pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Parent Line Breeding | Captive germplasm supply insulates Charoen Pokphand Group from Thai baht volatility affecting import-dependent competitors. |
| Digital Traceability Platform Deployment | Blockchain-enabled QR verification in Magway Region decentralizes quality trust from Department of Agricultural Research laboratories. |
| Highland Germplasm Development | Cold-tolerant hybrid portfolios unlock Chin State frontier markets with limited existing distribution infrastructure. |
| Credit-Linked Input Bundling Expansion | Embedded finance through agrochemical stores deepens farmer lock-in across Mandalay Region irrigated blocks. |
| Tissue Culture Rapid Multiplication Investment | Laboratory-based breeder seed production compresses foundation seed cycles and reduces field contamination risks. |
Research Methodology
Bottom-up farmer demand modeling reconciled against top-down seed distributor tracking forms the analytical core of this study. Primary interviews with seed company agronomists, Department of Agricultural Research certification officers, agrochemical store proprietors, and livestock feed procurement managers were cross-validated against secondary sources including Department of Agricultural Research field inspection records, ASEAN seed trade harmonization documents, and Myanmar agricultural customs data.
Input-output matrices mapped seed multiplication volumes through foundation seed, certified seed, and farm-saved propagation stages across the projection horizon. Segmentation dimensions modeled include product technology tier, buyer sophistication level, distribution channel configuration, and regional agro-ecological zone. CAGRs were derived from trend extrapolation of hybrid penetration rates and irrigation infrastructure expansion trajectories, with price elasticity assumptions calibrated against credit-linked input bundling adoption curves.
Inputs from Department of Agricultural Research certification databases were available through the study window; gaps in Chin State township-level distribution data introduce uncertainty bands for frontier market sizing. Forecasts reflect assumptions regarding seed policy enforcement consistency and parent line import approval timelines. Deviation in Department of Agricultural Research inspector hiring or ASEAN harmonization acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Europe Vegetable Seed Market
Seeds
Faba Beans Market
Seeds
Africa Vegetable Seed Market
Seeds
North America Tomato Seed Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Myanmar Seed Market
Seeds
Apple Seed Oil Market
Seeds
Eucommia Seed Oil Market
Seeds
Garden Seeds Market
Seeds
Canary Seeds Market
Seeds
Africa Chia Seeds Market
Seeds
China Vegetable Seed Market
Seeds
India Maize Seed Market
Seeds
Pigeon Pea Market
Seeds
India Forage Seed Market