
 India Rice Market | 2026-2036
India Rice Market Size, Share, and Industry Trends Forecast 2026-2036
India Rice Market Outlook
Buyer concentration across Indian rice value chains is rebalancing as organized food manufacturers and quick-service restaurant chains consolidate procurement volumes away from fragmented local traders. KRBL Limited leverages its integrated basmati processing infrastructure across Punjab and Haryana to sustain premium positioning in export channels. LT Foods Limited anchors domestic supply through proprietary aging facilities, while Adani Wilmar Limited competes on scale across mass-market white rice segments.
India rice comprises Oryza sativa grains processed through parboiling, steaming, or raw milling to achieve moisture levels of 12-14 percent and head-rice recovery rates critical for commercial grading. Basmati rice commands the highest margin pools due to geographic indication protection and export premiums to Gulf markets, while brown rice attracts health-conscious urban households through supermarkets and online retail channels. White rice still dominates volume throughput across wholesale markets and local grocers serving price-sensitive consumers.
FSSAI pesticide residue limits, BIS grading standards for long and medium grain, and Agricultural Produce Market Committee regulations at state mandis collectively shape milling practices, procurement logistics, and interstate trade flows. The Food Corporation of India's minimum support price operations buffer farmer incomes but distort private sector sourcing economics in surplus states. Stakeholders must monitor how export parity shifts between Indian and Pakistani basmati affect inventory holding strategies and forward contracting behavior.
Market Dynamics
FSSAI pesticide residue limits are compressing traditional milling margins and forcing capital deployment toward certified sorting infrastructure across Punjab and Haryana processing clusters.
Growth Catalysts
- Export parity premiums:Gulf market demand for geographic indication-protected basmati sustains forward contracting volumes from private integrated silos around Amritsar and Karnal.
- PLI scheme incentives:Food processing incentives under India's production-linked initiative subsidize aging facility upgrades and automated packaging lines for organized millers.
- Quick-service restaurant procurement:Chain consolidation in Maharashtra and Karnataka generates standardized long-grain offtake agreements with traceability requirements.
Market Restraints
- Water input volatility:Groundwater depletion in Punjab canal commands restricts kharif sowing reliability and raises irrigation compliance costs for paddy cultivators.
- APMC regulatory friction:State mandi fees and interstate movement permits distort private sector sourcing economics against Food Corporation of India minimum support price operations.
- Substitute grain competition:Wheat and millet consumption campaigns under POSHAN Abhiyaan redirect institutional procurement volumes in Rajasthan and Gujarat.
Strategic Opportunities
- Eastern Uttar Pradesh underpenetration:Gorakhpur and Varanasi districts lack integrated silo infrastructure, creating first-mover advantages for private capital deployment in procurement networks.
- Organic certification tailwinds:NPOP accreditation demand from European importers rewards conversion of Haryana acreage to residue-free cultivation with premium offtake guarantees.
- E-commerce channel innovation:Quick commerce platforms in Bengaluru and Hyderabad enable direct-to-kitchen brown rice distribution, bypassing traditional wholesale mandi layers.
Industry Challenges
- Sorting technician scarcity:Certified equipment operators capable of calibrating optical color sorters to FSSAI residue thresholds command wage premiums that strain mid-scale miller payrolls.
- Legacy ERP integration:Mandi-linked procurement software from state agricultural departments resists API connectivity with private warehouse management systems, forcing manual reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Rice Market |
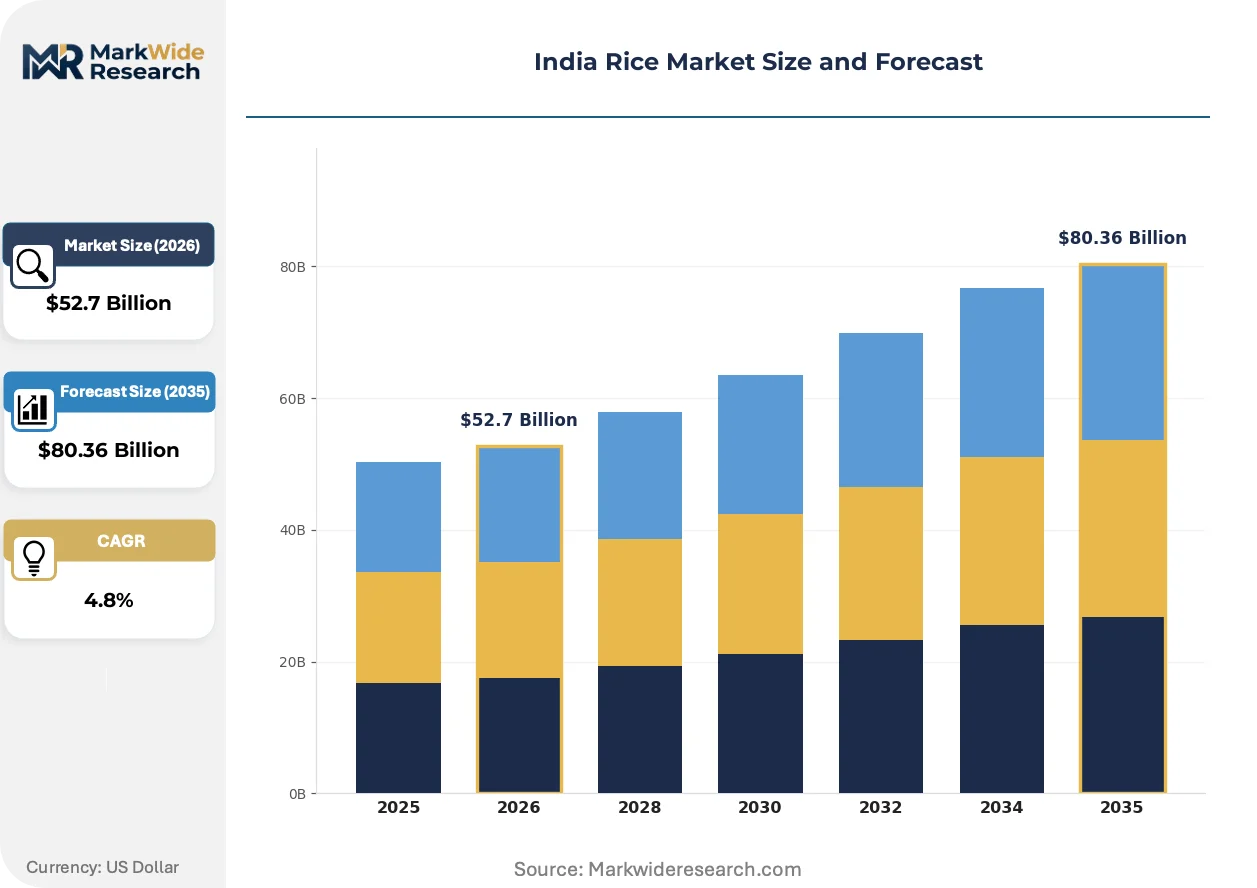
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rice, Brown Rice, Basmati Rice, Jasmine Rice End User: Households, Food Manufacturers, Restaurants, Exporters Distribution Channel: Supermarkets, Online Retail, Wholesale Markets, Local Grocers Grading: Long Grain, Short Grain, Medium Grain, Specialty Grades |
| Companies Covered | Veer Overseas Limited, Adani Wilmar Limited, KRBL Limited, Amira Nature Foods, Kohinoor Foods, LT Foods Limited, Amar Singh Chawal Wala, Rohit Exports, Shri Lal Mahal Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Rice Market Strategic Shifts
Digital traceability infrastructure and automated grading systems are compressing information asymmetries between farmgate and export terminal, restructuring how quality premiums flow back to cultivators.
Optical sorting technology is converging with near-infrared spectroscopy for real-time pesticide residue detection at mill intake points. Large export houses in Amritsar are deploying these systems ahead of FSSAI enforcement timelines. The convergence is compressing batch rejection windows from days to hours, enabling just-in-time procurement contracting that reduces working capital lockup.
FSSAI's tightened maximum residue limits for organophosphates and carbamates are disqualifying traditional parboiling methods in unregistered units. Millers in Karnal and Panipat are retrofitting steam stabilization lines to comply. Small-scale operations in Ludhiana district face displacement pressure as certification costs exceed their annual equipment depreciation budgets.
Urban households in Mumbai and Delhi are substituting supermarket private-label brown rice for loose white rice from kirana stores. Quick commerce platforms capture this shift through subscription models with guaranteed aging certificates. The channel rotation is most visible in Bengaluru's Whitefield and Koramangala clusters where delivery frequency exceeds traditional restocking cycles.
India Rice Market Segmentation
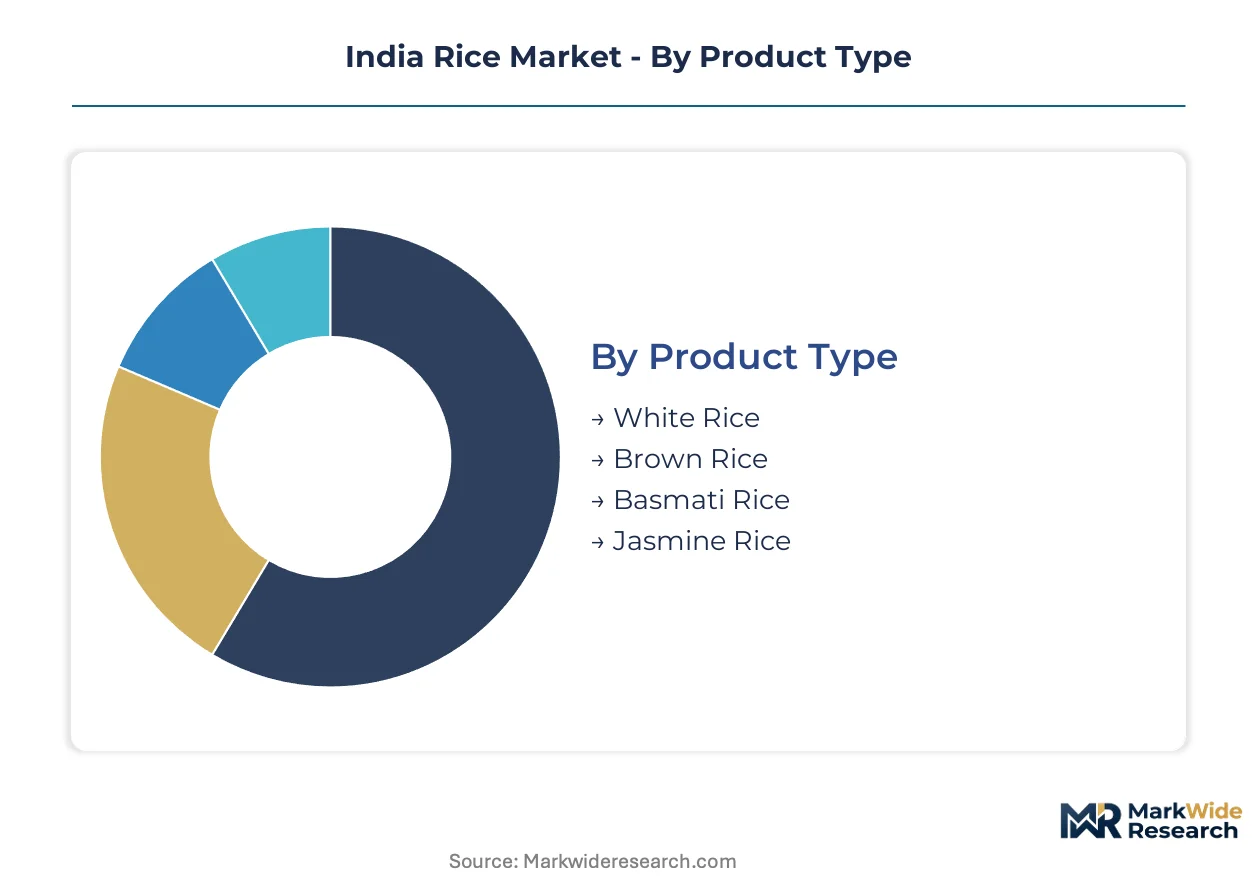
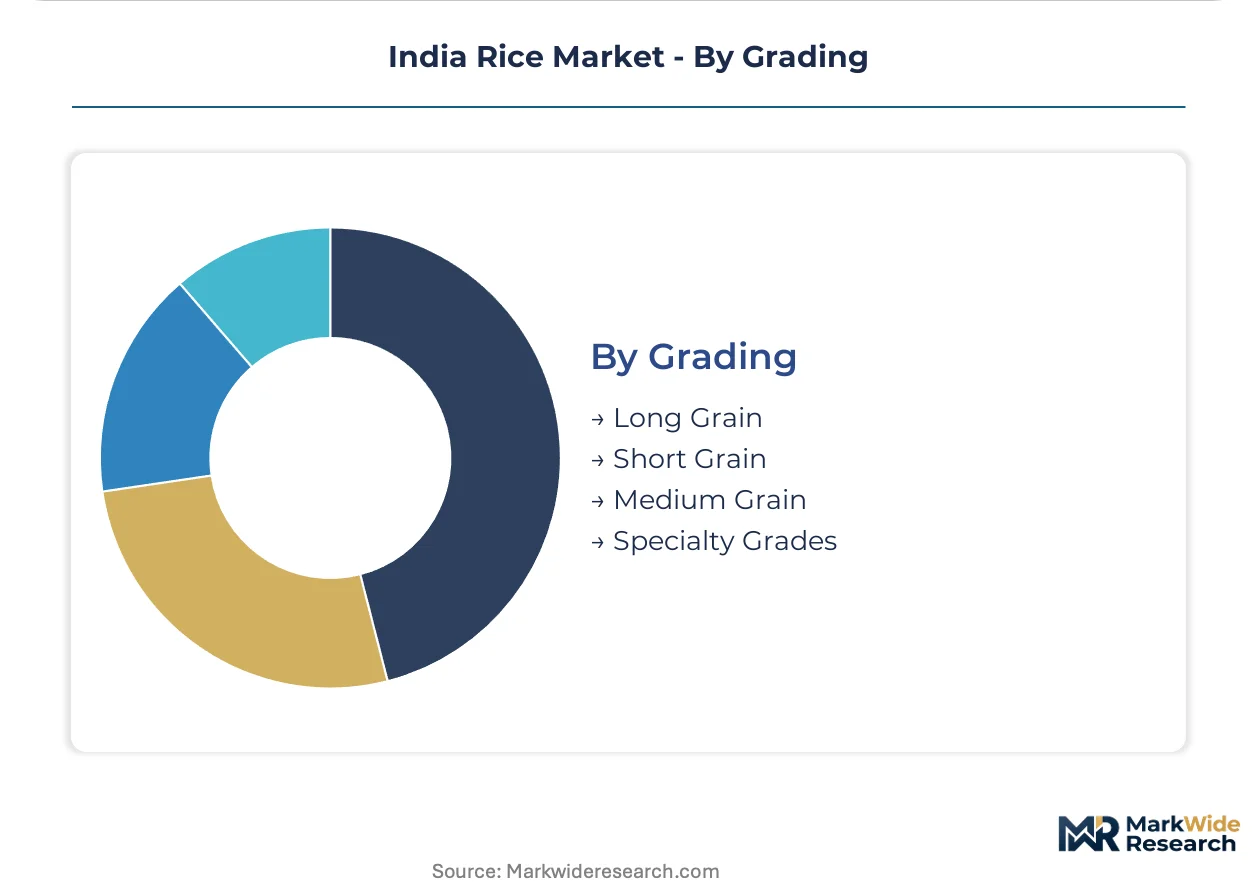
Segmentation in the India rice market determines procurement economics, margin capture, and regulatory compliance pathways. Each dimension—product type, end user, distribution channel, and grading—carves distinct operational requirements and investment priorities for millers and traders.
Product Type:
Integration depth varies sharply across product types, with some grades functioning as standalone consumer propositions while others embed into institutional supply chains.
- Basmati Rice:Aromatic long-grain varieties carry geographic indication protection under Indian law, commanding export premiums to Gulf Cooperation Council markets. Procurement clusters around Amritsar and Karnal, where private integrated silos maintain aging infrastructure for 12-24 month maturation cycles.
- White Rice:Polished grains with bran and germ removed dominate volume throughput across government public distribution systems and mass-market retail. Demand concentrates in Bihar and Uttar Pradesh, where price-sensitive households prioritize caloric density over nutritional retention.
- Brown Rice:Whole-grain format retains bran layer and attracts health-conscious urban consumers through supermarket private-label programs in Mumbai and Delhi.
- Jasmine Rice:Fragrant medium-grain variety sees limited cultivation in India, primarily sourced for specialty restaurant supply in Karnataka and Tamil Nadu.
Volume placements concentrate in White Rice; the faster expansion belongs to Basmati Rice.
End User:
Customer type segmentation reveals diverging procurement sophistication, from fragmented household purchases to consolidated institutional contracting with traceability mandates.
- Food Manufacturers:Organized processors in Uttar Pradesh and Maharashtra require standardized moisture specifications and batch certification for ready-to-eat and extruded snack production. FSSAI compliance timelines are compressing supplier qualification windows.
- Households:Individual consumers source through kirana stores, supermarkets, and quick-commerce platforms, with purchasing decisions driven by price point, brand recognition, and cooking convenience.
- Restaurants:Quick-service chains in Bengaluru and Hyderabad negotiate annual offtake agreements with specified head-rice recovery rates and delivery frequency guarantees.
- Exporters:Trading houses in Haryana and Punjab manage Gulf-bound basmati shipments through DGFT-licensed facilities with phytosanitary certification and customs-bonded warehousing.
Contract value concentrates with Food Manufacturers; the steepest expansion trajectory is visible in Exporters.
Distribution Channel:
Channel segmentation tracks the displacement of traditional mandi intermediation by organized retail and digital platforms with direct farmgate linkages.
- Wholesale Markets:State-regulated APMC mandis in Punjab and Haryana remain the dominant price discovery mechanism for bulk grain movement, though fee structures distort private sector economics against FCI procurement.
- Online Retail:Quick-commerce platforms in Whitefield and Koramangala clusters enable subscription-based brown rice distribution with guaranteed aging certificates and sub-30-minute delivery windows.
- Supermarkets:Organized retail chains in Mumbai and Delhi stock private-label packaged rice with BIS grading compliance and barcode traceability.
- Local Grocers:Neighborhood kirana stores serve cash-dependent consumers with loose white rice and minimal quality differentiation.
Transaction volume concentrates in Wholesale Markets; the fastest channel expansion belongs to Online Retail.
Grading:
Grain classification under BIS standards structures milling investment and export eligibility, with length specifications determining end-use suitability.
- Long Grain:Grains exceeding 6.6mm in length command premium positioning in Gulf export markets and quick-service restaurant supply chains. Haryana and Punjab cultivation clusters specialize in this grade with dedicated parboiling infrastructure.
- Specialty Grades:Aromatic and pigmented varieties target health-conscious segments and ethnic cuisine applications, requiring segregated processing lines to prevent cross-contamination.
- Medium Grain:Shorter kernels suit idli and dosa preparation in South Indian institutional kitchens, with concentrated demand in Tamil Nadu and Karnataka.
- Short Grain:Rounded grains find limited application in Indian consumption patterns, primarily absorbed by starch extraction and brewing industries.
Production volume concentrates in Long Grain; the premium expansion rate belongs to Specialty Grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Indian rice concentrates in Punjab and Haryana basmati belts, Maharashtra food manufacturing corridors, and Karnataka quick-service restaurant clusters. State-level procurement policies and groundwater regulations reshape regional production economics.
Punjab
Basmati procurement dominates through Amritsar and Ludhiana mandis, where private integrated silos compete with Food Corporation of India minimum support price operations. FSSAI pesticide residue enforcement disqualifies traditional parboiling units lacking certified sorting infrastructure. The Amritsar-Karnal corridor anchors aging facility investments for 12-24 month maturation cycles serving Gulf export markets.
Haryana
Karnal and Panipat districts specialize in long-grain processing with dedicated steam stabilization lines retrofitting for compliance. The state's agricultural marketing board structures mandi fees that distort private sector sourcing against FCI procurement. Karnal-based export houses deploy optical sorting with near-infrared spectroscopy ahead of enforcement timelines.
Maharashtra
Organized food manufacturers in Mumbai and Pune expand procurement of specialty grades for ready-to-eat and extruded snack production. State agricultural department procurement software resists API connectivity with private warehouse management systems. Quick-service restaurant chains in Mumbai negotiate standardized long-grain offtake agreements with traceability requirements.
Karnataka
Bengaluru quick-commerce platforms in Whitefield and Koramangala clusters enable subscription-based brown rice distribution with guaranteed aging certificates. The state's food processing incentives under PLI scheme subsidize automated packaging lines for organized millers. Bengaluru's delivery frequency exceeds traditional wholesale mandi restocking cycles.
Uttar Pradesh
Gorakhpur and Varanasi districts lack integrated silo infrastructure, creating first-mover advantages for private capital deployment. Eastern regions underpenetrate relative to western procurement networks around Lucknow. Food manufacturers require standardized moisture specifications and batch certification with compressing supplier qualification windows.
India Rice Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty certification and direct-to-consumer channels. The market structures around integrated basmati processors with captive aging infrastructure, diversified food conglomerates with mass-market scale, and regional exporters with Gulf market relationships. Three archetypes dominate: geographic indication-protected specialists, PLI-subsidized automated millers, and quick-commerce-enabled brown rice distributors. Competitive moves concentrate on procurement network expansion and sorting technology certification.
Within the integrated processing tier, KRBL Limited and LT Foods Limited exemplify divergent strategic positions. KRBL anchors premium basmati positioning through Punjab-Haryana silo infrastructure. LT Foods occupies domestic supply chain coordination with proprietary aging facilities. Adani Wilmar Limited represents scale-driven competition across mass-market white rice segments.
| Leading Market Players |
|---|
| Veer Overseas Limited |
| Adani Wilmar Limited |
| KRBL Limited |
| Amira Nature Foods |
| Kohinoor Foods |
| LT Foods Limited |
| Amar Singh Chawal Wala |
| Rohit Exports |
| Shri Lal Mahal Group |
| Others |
Value Chain & Pricing Dynamics
Minimum support price announcements from the Food Corporation of India cascade through Punjab and Haryana mandis into three distinct pricing tiers: export-grade basmati with aging premiums, institutional white rice locked to FCI benchmarks, and quick-commerce brown rice with subscription markups.
Pricing Analysis
Volume throughput concentrates in mass-market white rice where FCI procurement floors compress miller margins, while margin capture concentrates in geographic indication-protected basmati with Gulf export premiums. Price differentiation rests on FSSAI certification grade and captive aging infrastructure tenure. Pricing pressure intensifies in unregistered parboiling units facing residue compliance retrofit costs. Quick-service restaurant chains exhibit lowest price sensitivity due to traceability mandates, while kirana-dependent households in Bihar and Uttar Pradesh remain most elastic.
Supply Chain Analysis
FSSAI sorting certification gates upstream access for millers lacking optical color sorter calibration capability. Geographic supply draws from Punjab, Haryana, and Uttar Pradesh cultivation belts with concentrated kharif sowing. Raw material dependencies center on groundwater access, certified seed varieties, and organophosphate-free agrochemical inputs. Supply chain risk runs through groundwater depletion in Punjab canal commands restricting sowing reliability. Distribution runs through state APMC mandis, integrated private silos, and quick-commerce last-mile networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI pesticide residue enforcement constructs a cost-of-compliance moat that favors organized millers with certified sorting infrastructure over fragmented traditional operators.
For Market Incumbents: Lock in procurement network density around Amritsar and Karnal before PLI scheme incentives attract competing capital deployment. Deepen backward integration into captive aging facilities to defend basmati premium positioning against emerging automated millers. Prioritize API connectivity investments to resolve state agricultural department software reconciliation friction. For New Entrants and Emerging Players: Begin with eastern Uttar Pradesh silo infrastructure deployment in Gorakhpur and Varanasi districts where integrated procurement networks remain underpenetrated. Target organic certification conversion in Haryana acreage for European export offtake guarantees. Pursue quick-commerce brown rice subscription models in Bengaluru and Hyderabad clusters with guaranteed aging certificates. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale millers in Ludhiana district facing displacement from FSSAI compliance costs exceeding depreciation budgets. Long-term viability over a multi-year horizon rests on sorting technician training pipelines and optical spectroscopy deployment timing. Watch export parity spreads between Indian and Pakistani basmati as inventory holding strategy inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Infrastructure Deployment | FSSAI residue enforcement timelines compress batch rejection windows from days to hours for compliant millers. |
| Integrated Silo Network Expansion | Private capital deployment in eastern Uttar Pradesh captures first-mover procurement advantages before mandi fee reforms. |
| Organic Certification Conversion | NPOP accreditation unlocks premium offtake guarantees from European importers seeking residue-free supply. |
| Quick-Commerce Channel Integration | Direct-to-kitchen brown rice distribution in Bengaluru bypasses traditional wholesale mandi margin layers. |
| Backward Integration into Aging Facilities | Proprietary 12-24 month maturation cycles sustain basmati export premiums to Gulf Cooperation Council markets. |
Study Parameters
Independent corroboration across miller operations directors, FSSAI compliance officers, and export house procurement managers underwrites the qualitative findings. Primary fieldwork engaged state agricultural marketing board officials, optical equipment calibration technicians, and quick-commerce supply chain leads. Secondary validation drew from Agricultural Produce Market Committee trade records, Food Corporation of India procurement bulletins, DGFT export licensing databases, and BIS grading standard notifications. Bottom-up silo capacity assessments and top-down consumption modeling triangulate volume estimates.
Rate-of-change decomposition across product type, end user, distribution channel, and grain grading dimensions structures the analytical framework. CAGRs derive from segmented growth trajectory analysis over the projection horizon. Forecast inputs incorporate groundwater depletion scenarios in Punjab canal commands, PLI scheme incentive disbursement schedules, and FSSAI enforcement phase-in timelines.
Underlying measurement precision varies by segment; basmati export volumes carry tighter precision than fragmented kirana channel white rice estimates. Forecasts reflect assumptions around FCI minimum support price continuity, Gulf market import demand stability, and quick-commerce customer acquisition cost trajectories. A model refresh is warranted upon material change in FSSAI maximum residue limit enforcement intensity or Indo-Pak basmati export parity spreads.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Tunisia Grain Market
Grains
Low Fat Rice Market
Grains
Pea Grits Market
Grains
Rolled Oats Market
Grains
Heritage Grain Market
Grains
Global Oats Market
Grains
White Beans Market
Grains
Grain Roller Market
Grains
Mexico Rice Market
Grains
Mesquite Flour Market
Grains
Soy Grits Market
Grains
North America Wheat Flour Market
Grains
Spelt Wheat Market
Grains
Dried Spent Grain Market
Grains
Masa Corn Products Market
Grains
Europe Wheat Protein Market