
 Durum Wheat Flour Market | 2026-2036
Durum Wheat Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Durum Wheat Flour Market Foresight
Multi-source procurement among industrial pasta manufacturers is realigning how durum wheat flows from North American elevators to Mediterranean mills. Richardson International Limited leverages its Canadian prairie elevator network to secure premium hard amber durum for export. Casillo SpA anchors southern Italian milling with vertical integration into Apulian grain collection. Ardent Mills competes across the US high-plains belt with specialized cleaning and tempering infrastructure.
Durum wheat flour is milled from Triticum durum, a hard wheat species with protein content typically ranging from twelve to fourteen percent and amber endosperm that produces strong gluten networks essential for pasta extrusion. Semolina commands the largest product-type position due to its dominance in industrial pasta manufacturing, while pasta flour extends into artisanal and fresh-noodle applications. Food processors represent the most concentrated end-user segment, though specialty stores as a distribution channel capture disproportionate margin through imported Italian-origin positioning.
EU F-Gas Regulation and REACH compliance frameworks govern refrigerants and processing aids in European milling operations, while FDA standards and USDA grading protocols shape US import-export specifications for durum wheat. EFSA maximum residue limits for pesticides directly influence sourcing decisions across Mediterranean supply basins. Stakeholders must monitor evolving carbon-border adjustment mechanisms and their projected impact on transatlantic durum trade economics.
Market Dynamics
The EU F-Gas Regulation is compressing energy-intensive milling operations across Mediterranean supply basins, forcing capital redeployment toward heat-recovery systems and low-global-warming-potential refrigerants in semolina production facilities.
Growth Catalysts
- Artisanal pasta manufacturing:Small-batch producers in Italy's Emilia-Romagna cluster are expanding certified durum flour procurement, creating premium-tier demand that commands price premiums over commodity semolina.
- REACH compliance frameworks:European milling operations are retrofitting facilities to meet ECHA chemical safety standards, accelerating adoption of closed-loop tempering systems that reduce water and energy intensity.
- Carbon-border adjustment mechanisms:Importers are pre-emptively restructuring transatlantic supply chains to document embedded emissions ahead of phased tariff implementation on high-carbon agricultural inputs.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings in Canadian prairie production zones transmit directly to durum elevator pricing, compressing margins for non-integrated millers.
- Supply concentration risk:Premium hard amber durum availability clusters in Saskatchewan and North Dakota elevator networks, exposing buyers to weather-driven volume disruptions.
- Substitution threat:High-protein common wheat varieties are penetrating fresh-noodle applications where gluten strength requirements are less stringent than extruded pasta.
Strategic Opportunities
- Underpenetrated organic certification:Italian and French millers are building dedicated organic durum supply chains to capture price premiums in specialty retail channels.
- EU Green Deal agricultural transition:CAP subsidy realignment is incentivizing regenerative farming practices that reduce input intensity while maintaining protein content specifications.
- E-commerce direct-to-baker distribution:Small-package semolina sales through digital channels are bypassing traditional foodservice distributors to reach artisanal pasta startups.
Industry Challenges
- Skilled miller shortage:Tempering and extraction optimization expertise is aging out of the workforce faster than technical training programs can replenish qualified operators.
- Integrated certification timelines:Dual organic and carbon-neutral accreditation requires 18-36 month field-to-facility documentation chains that strain working capital for independent growers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Durum Wheat Flour Market |
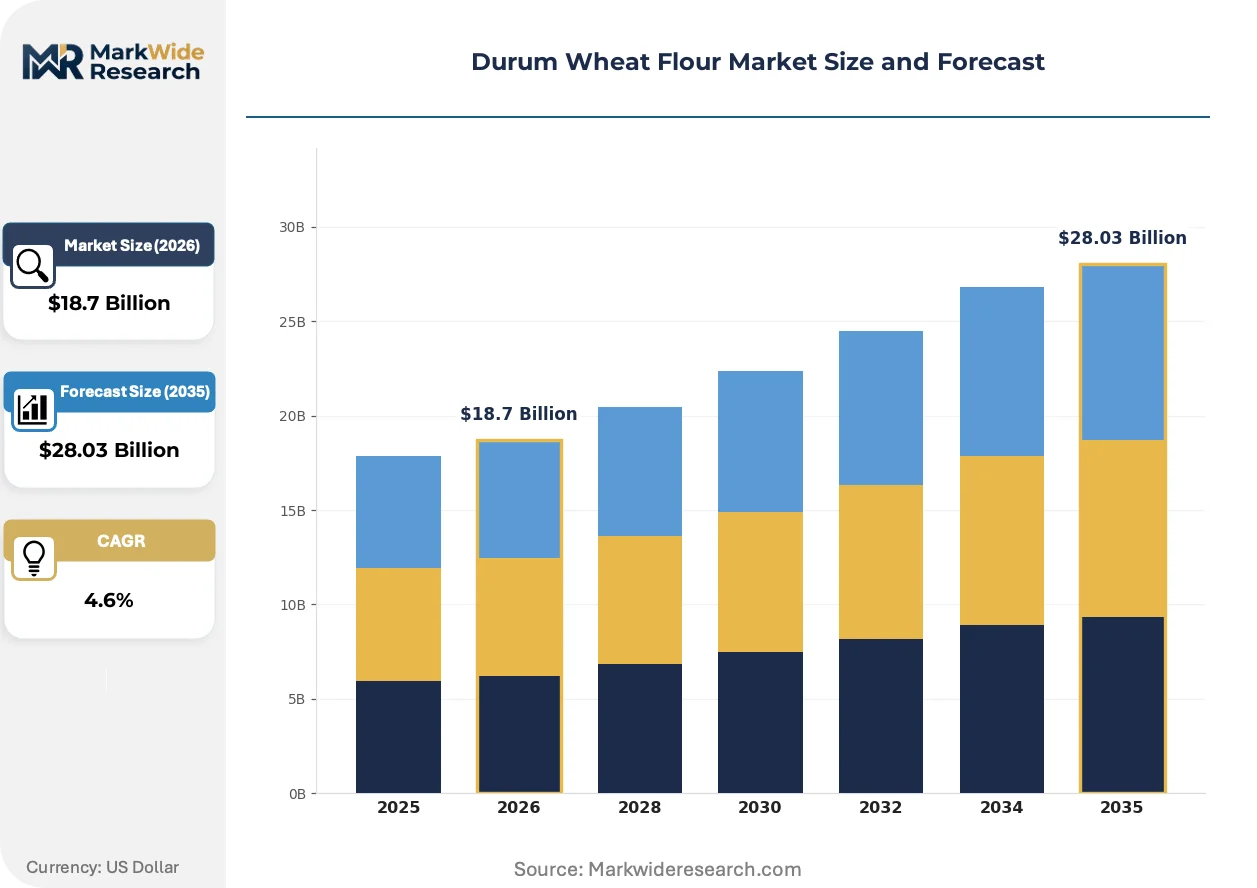
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Purpose Flour, Semolina, Bread Flour, Pasta Flour End User: Restaurants, Bakeries, Food Processors, Homes Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores Packaging Type: Bags, Jars, Bulk Containers, Sachets |
| Companies Covered | Richardson International Limited, King Arthur Baking Company, Inc., Archer Daniels Midland Company, Casillo SpA, Bob's Red Mill Natural Foods, Inc., Cargill, Incorporated, Ardent Mills, Antimo Caputo Srl, General Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Durum Wheat Flour Market Shifts & Advancements
NIR spectroscopy and automated granulation control are rewriting quality assurance protocols, while regulatory pressure on processing emissions accelerates equipment replacement cycles across European and North American milling bases.
Optical sorting technology is consolidating quality control functions that previously required multiple manual inspection stages. Industrial pasta manufacturers are adopting hyperspectral imaging systems to detect protein uniformity and vitreous kernel percentages in real-time. This compression of inspection labor is consolidating mid-tier millers into larger processing networks capable of justifying capital deployment.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in milling climate control systems. European operators must retrofit or replace cooling infrastructure by mandated step-down dates, redirecting maintenance budgets toward compliance. Italian semolina producers with legacy ammonia-based systems are gaining operational cost advantages over facilities dependent on synthetic refrigerant retrofits.
Direct sourcing contracts between pasta manufacturers and Canadian prairie elevator networks are displacing spot-market purchasing for premium hard amber durum. Large Italian millers are establishing multi-year volume commitments with Saskatchewan grain handlers to secure protein consistency and origin traceability. This relationship-based procurement model is most visible in high-volume industrial extrusion operations where formulation stability outweighs price flexibility.
Durum Wheat Flour Market Segmentation
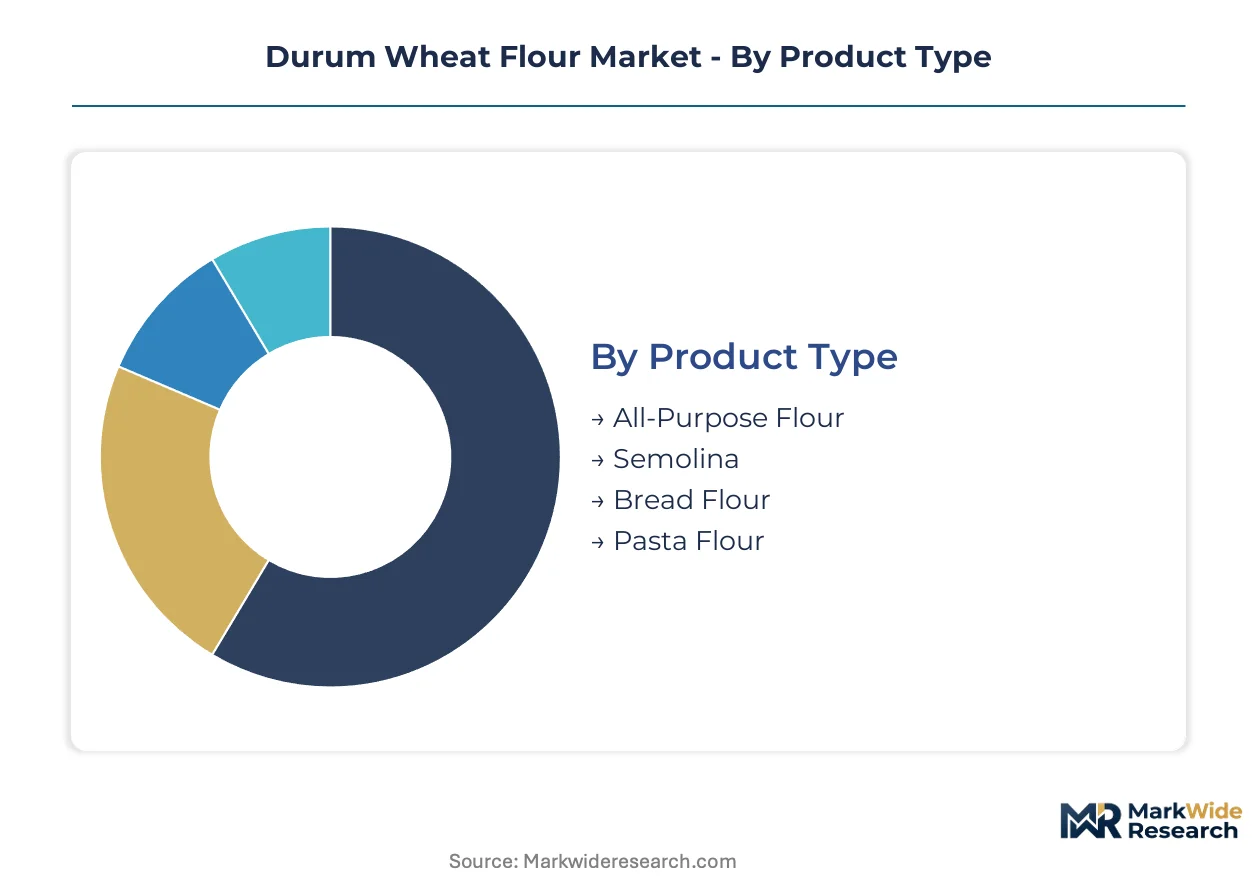
Durum wheat flour segmentation reveals how protein specifications and end-use applications fragment procurement patterns across industrial and artisanal channels. Product type distinctions drive milling infrastructure investments, while distribution channel choices determine margin capture for premium versus commodity positioning.
Product Type:
Semolina sits at the core of standalone industrial pasta manufacturing, while pasta flour and bread flour embed into more complex food production systems requiring formulation flexibility.
- Semolina:Coarsely ground endosperm from hard amber durum with protein content typically ranging twelve to fourteen percent. Demand concentrates in Italy's Emilia-Romagna industrial extrusion corridor where consistent gluten strength governs production yields. REACH-compliant tempering infrastructure is becoming a gating factor for supplier qualification.
- Pasta Flour:Finer granulation than semolina, optimized for fresh noodle and artisanal sheet applications. Small-batch producers in Apulia and Sicily are expanding certified procurement as EU Green Deal subsidies incentivize regenerative sourcing documentation.
- All-Purpose Flour:Lower protein extraction blends for general baking applications where durum's amber color provides differentiation rather than structural performance.
- Bread Flour:High-protein durum formulations targeting specialty leavened products; limited volume compared to common wheat alternatives.
Volume placements concentrate in Semolina; the faster expansion belongs to Pasta Flour.
End User:
Food processors dominate tonnage through integrated milling relationships, while restaurants and bakeries operate at smaller scale with higher service requirements.
- Food Processors:Industrial pasta manufacturers with dedicated extrusion lines requiring protein consistency across production runs. Direct sourcing contracts with Saskatchewan elevator networks are displacing spot purchasing for premium hard amber durum.
- Restaurants:Fresh pasta kitchens in Italian urban centers and North American metro areas sourcing small-batch semolina with origin traceability claims.
- Bakeries:Artisanal bread producers experimenting with durum blends for color and flavor differentiation in specialty retail positioning.
- Homes:Consumer-packaged semolina through retail channels; e-commerce direct-to-baker distribution is bypassing traditional foodservice networks for this segment.
Food processors anchor volume throughput; restaurants are climbing the fastest on per-unit value metrics.
Distribution Channel:
Supermarkets and wholesale channels move commodity-grade tonnage, while specialty stores and online retail extract premium through certification storytelling.
- Supermarkets:Mass-market semolina and pasta flour in standard packaging; pricing pressure from private-label alternatives compresses branded margin.
- Wholesale:Foodservice distributors supplying industrial processors and restaurant chains with bulk-container logistics.
- Specialty Stores:Imported Italian-origin positioning commands disproportionate margin through organic and DOP certification claims.
- Online Retail:Small-package semolina sales reaching artisanal pasta startups; digital channels enable direct miller-to-baker relationships outside traditional distributor networks.
Supermarkets dominate unit movement; specialty stores are gaining share fastest on margin contribution.
Packaging Type:
Bulk containers integrate into industrial just-in-time milling, while bags and sachets serve fragmented downstream channels with varying shelf-life requirements.
- Bulk Containers:Rail-sourced hard amber durum for large millers with dedicated cleaning and tempering infrastructure.
- Bags:Standard retail and foodservice format; kraft and polypropylene variants calibrated to moisture protection needs.
- Jars:Premium positioning for specialty retail with resealability and visual product presentation.
- Sachets:Single-use portions for restaurant trial and home experimentation; limited current volume but expanding in direct-to-consumer channels.
Bulk containers anchor industrial procurement; sachets are expanding most quickly in digital-native brand portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hard amber durum wheat from Saskatchewan and North Dakota prairie elevators anchors transatlantic supply chains. Mediterranean milling clusters process this North American grain alongside domestic harvests. Regulatory divergence between EU F-Gas mandates and USDA grading protocols fragments procurement strategies across major consuming regions.
Italy
Emilia-Romagna's industrial extrusion corridor consumes premium semolina for dried pasta manufacturing at scale. EU F-Gas Regulation compliance deadlines force millers in Parma and Modena to retrofit tempering infrastructure with low-global-warming-potential refrigerants. Apulian grain collection networks supply Casillo SpA's vertically integrated milling operations with domestic durum.
United States
North Dakota and Montana hard amber durum production feeds domestic pasta manufacturers and Mediterranean export contracts. USDA grading protocols for protein content and vitreous kernel percentage shape elevator pricing structures across the northern plains. Ardent Mills operates specialized cleaning and tempering infrastructure throughout the high-plains belt.
Canada
Saskatchewan's prairie elevator network concentrates premium hard amber durum availability for international shipment. Richardson International Limited leverages backward integration into grain collection to secure export volumes for Italian and North African millers. Canadian Grain Commission certification standards govern protein specifications for transatlantic cargo.
France
Provence and Languedoc durum production serves domestic pasta manufacturers and specialty millers targeting North African export markets. EFSA maximum residue limits for pesticides constrain sourcing from non-EU supply basins. EU Green Deal agricultural transition subsidies incentivize regenerative farming practices in southern growing regions.
Turkey
Southeastern Anatolia and Central Plateau durum cultivation supplies domestic pasta manufacturers and Middle Eastern re-export trade. The country's national food safety regulator enforces mycotoxin and pesticide residue standards aligned with EU import requirements. Izmir port infrastructure handles bulk grain flows from Black Sea and North American origins.
Durum Wheat Flour Market Competitive Landscape
Backward integration into grain collection and elevator networks dominates the current landscape among major processors. The vendor base clusters around three strategic archetypes: North American prairie-integrated grain handlers with export orientation, Mediterranean millers with tempering infrastructure specialization, and diversified food conglomerates with pasta manufacturing captive demand. M&A activity concentrates on elevator network consolidation and specialty mill acquisitions. Capacity expansion focuses on REACH-compliant tempering systems and optical sorting technology deployment.
Among North American integrated handlers, Richardson International Limited exemplifies prairie-elevator-network competitive positioning. Casillo SpA and Ardent Mills represent contrasting geographic archetypes—Mediterranean vertical integration versus US high-plains belt specialization. Archer Daniels Midland Company and Cargill, Incorporated occupy diversified-agribusiness positions with multi-commodity sourcing flexibility. King Arthur Baking Company, Inc. and Bob's Red Mill Natural Foods, Inc. sit within specialty retail-facing tiers emphasizing certification storytelling and direct-to-consumer distribution channels.
| Leading Market Players |
|---|
| Richardson International Limited |
| King Arthur Baking Company, Inc. |
| Archer Daniels Midland Company |
| Casillo SpA |
| Bob's Red Mill Natural Foods, Inc. |
| Cargill, Incorporated |
| Ardent Mills |
| Antimo Caputo Srl |
| General Mills, Inc. |
| Others |
Supply & Pricing Matrix
Optical sorting technology deployment across European and North American milling bases simultaneously compresses per-unit inspection costs and consolidates processing capacity into fewer capital-intensive facilities. This equipment transition rewards operators with legacy ammonia-based cooling infrastructure under EU F-Gas Regulation timelines, widening cost advantages over competitors facing synthetic refrigerant retrofit obligations.
Pricing Analysis
Service bundling separates contract-based procurement from spot-market purchasing, with multi-year volume commitments from Italian millers to Saskatchewan elevator networks including protein consistency guarantees and origin traceability documentation. Three-tier pricing structure across premium certified-organic, standard commercial-grade, and economy common-wheat-substitute levels reflects certification grade and volume scale differentiation. Pricing pressure stems from high-protein common wheat varieties penetrating fresh-noodle applications where gluten strength requirements are less stringent. Food processors exhibit highest price sensitivity due to formulation stability requirements, while specialty stores capture disproportionate margin through imported Italian-origin positioning with certification storytelling.
Supply Chain Analysis
Skilled miller shortages in Italy's Emilia-Romagna corridor and North Dakota's high-plains belt constrain tempering and extraction optimization capacity across premium semolina production zones. Hard amber durum availability clusters in Saskatchewan, North Dakota, and Alberta elevator networks, with protein specifications and vitreous kernel percentages governing Canadian Grain Commission and USDA grading protocols. Supply chain risk centers on weather-driven volume disruptions across prairie production zones with limited geographic diversification. Distribution runs through direct sourcing contracts displacing spot-market purchasing for premium hard amber durum in high-volume industrial extrusion operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NIR spectroscopy and automated granulation control are displacing manual quality assurance protocols, creating asymmetric returns for millers with capital deployment capacity against legacy inspection-dependent competitors.
For Market Incumbents: Lock in multi-year volume commitments with Saskatchewan and North Dakota elevator networks before carbon-border adjustment mechanisms phase in documentation requirements for embedded emissions. Secure REACH-compliant tempering infrastructure and ammonia-based cooling systems to exploit operational cost advantages over competitors facing synthetic refrigerant retrofits under EU F-Gas Regulation deadlines. Deepen backward integration into Apulian grain collection networks or Canadian prairie elevators to reduce spot-market exposure. For New Entrants and Emerging Players: Enter via e-commerce direct-to-baker distribution channels bypassing traditional foodservice networks to reach artisanal pasta startups with small-package semolina offerings. Target underpenetrated organic certification segments where Italian and French millers are building dedicated supply chains to capture price premiums in specialty retail channels. Lead with regenerative sourcing documentation aligned with EU Green Deal agricultural transition subsidies. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty mill acquisitions by diversified food conglomerates seeking captive pasta manufacturing demand and in elevator network consolidation by North American prairie-integrated grain handlers. Long-term viability favors operators with backward integration into grain collection and REACH-compliant tempering infrastructure specialization. Watch for carbon-border adjustment mechanism implementation timelines as inflection indicator for transatlantic supply chain restructuring velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elevator Networks | Richardson International Limited's prairie elevator control secures premium hard amber durum export volumes for Mediterranean millers. |
| REACH-Compliant Tempering Infrastructure Deployment | Italian semolina producers in Parma and Modena retrofit facilities to meet ECHA chemical safety standards ahead of compliance deadlines. |
| Organic Certification Supply Chain Construction | Apulian and Sicilian millers build dedicated field-to-facility documentation chains capturing specialty retail price premiums. |
| Direct Sourcing Contract Establishment | Large Italian millers displace spot purchasing with multi-year volume commitments to Saskatchewan grain handlers for protein consistency. |
| E-Commerce Direct-to-Baker Channel Development | Small-package semolina sales through digital platforms bypass traditional foodservice distributors to reach artisanal pasta startups. |
Research Methodology
Independent corroboration across primary interviews with grain elevator operators, semolina mill procurement directors, pasta manufacturing formulation managers, and EU regulatory compliance officers underwrites the qualitative findings. Secondary validation draws from Canadian Grain Commission certification standards, USDA grading protocols, EFSA maximum residue limit documentation, and customs trade flow records. Bottom-up volume modeling triangulates against top-down market sizing across product type, end user, and distribution channel segmentations.
Comparable-period anchoring to historical protein content specifications, vitreous kernel percentage trends, and tempering infrastructure deployment rates informs the projection framework across the analysis window. Modeled dimensions include product type granularity, end-use application intensity, packaging format logistics, and regional regulatory cluster alignment. CAGRs derive from segmented growth rate blending with industry-specific inputs including EU F-Gas Regulation compliance timelines and carbon-border adjustment mechanism phase-in assumptions.
Revisions become necessary when fertilizer and fuel price volatility in Canadian prairie production zones transmits more sharply to elevator pricing than modeled, or when high-protein common wheat substitution accelerates beyond fresh-noodle applications into extruded pasta. Material deviation in EU Green Deal subsidy realignment or skilled miller workforce replenishment rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Quinoa Flour Market
Grains
Global Oats Market
Grains
Fortified Rice Market
Grains
Organic Rice Flour Market
Grains
Brown Rice Market
Grains
Non-Basmati Rice Market
Grains
Rolled Oats Market
Grains
Black Gram Market
Grains
Soya Flour Market
Grains
South America Wheat Market
Grains
Oatmeal Market
Grains
North America Pulses Market
Grains
Ancient Grain Market
Grains
Organic Wheat Flour Market
Grains
Europe Maize Market
Grains
Dried Spent Grain Market