
 Basmati Rice Market | 2026-2036
Basmati Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Basmati Rice Market Analysis
The EU Green Deal's sustainable sourcing requirements for imported food commodities is recalibrating procurement standards across European retail channels. KRBL leverages its integrated milling and aging infrastructure to sustain volume leadership in premium export grades. LT Foods anchors its competitive position through specialized organic and heritage varietal portfolios targeting North American specialty grocers.
Basmati rice denotes a long-grain aromatic Oryza sativa cultivar distinguished by a minimum grain elongation ratio of 3.5:1 upon cooking and a characteristic 2-acetyl-1-pyrroline compound concentration exceeding 0.09 ppm. The grain undergoes mandatory aging for 12–18 months to develop its signature fluffy texture and non-sticky mouthfeel, serving as a premium staple across Middle Eastern, South Asian, and diaspora cuisines worldwide. White Basmati dominates volume throughput due to established milling infrastructure and consumer familiarity, while Organic Basmati captures expanding margin pools as certified procurement protocols harden across European and North American retail banners. Brown Basmati sustains niche growth among health-positioned channels where fiber retention and minimal processing command shelf-space premiums.
India's BIS grading standards and Pakistan's national food safety authority enforce varietal purity thresholds and maximum allowable broken-grain percentages that determine export eligibility and price realization. The EU's REACH-related contaminant screening and the USDA's organic certification framework create layered compliance architectures that shape market access trajectories for origin-country exporters. Stakeholders must monitor evolving Geographical Indication enforcement scope and carbon-border adjustment mechanisms that threaten to restructure landed-cost competitiveness across destination markets.
Market Dynamics
India's Geographical Indication enforcement under its national intellectual property framework is compressing cross-border labeling arbitrage while the EU Green Deal's carbon-border adjustment mechanisms threaten to restructure landed-cost competitiveness for South Asian exporters.
Growth Catalysts
- EU Green Deal sustainable sourcing mandates:European retail banners are hardening certified procurement protocols for imported aromatic rice varieties, creating compliant supply premiums for origin-country millers meeting REACH-related contaminant screening thresholds.
- Aged long-grain demand concentration in the Middle East:Saudi Arabia and the United Arab Emirates maintain the highest per-capita import volumes globally, sustaining volume throughput for 12–18 month aged inventory pipelines.
- Specialty food retail channel expansion:North American and European premium grocers are widening shelf-space allocation for heritage varietal portfolios targeting diaspora cuisine segments.
Market Restraints
- Input cost volatility in paddy procurement:Monsoon-dependent cultivation cycles in Punjab and Haryana generate harvest quantity uncertainty that compresses margin predictability for integrated millers.
- Supply concentration in Indo-Gangetic belt:Over 70 percent of export-grade Basmati originates from two Indian states, creating geographic risk exposure to climate anomalies and water allocation disputes.
- Regulatory friction from EU REACH contaminant screening:Maximum residue limit enforcement for agrochemical traces blocks substantial volume from accessing European retail channels despite meeting BIS purity thresholds.
Strategic Opportunities
- Organic certification penetration in North America:USDA organic framework compliance remains underdeveloped among Pakistani exporters, creating first-mover margin pools for certified heritage varietal sourcing.
- Carbon-border adjustment mechanism preparation:EU Green Deal implementation timelines offer a compliance preparation window for South Asian millers investing in renewable energy transition for parboiling and drying operations.
- Specialty e-commerce channel development:Direct-to-consumer platforms targeting South Asian diaspora households in the United Kingdom and Canada bypass traditional importer-distributor margin stacking.
Industry Challenges
- Geographical Indication enforcement complexity:Cross-border labeling disputes between Indian and Pakistani exporters require sustained legal expenditure to defend origin-authentication claims in third-country markets.
- Aging infrastructure capex requirements:Mandatory 12–18 month grain maturation demands dedicated climate-controlled warehousing capacity that smaller millers struggle to finance.
- Broken-grain percentage compliance:BIS and Pakistan's national food safety authority enforce divergent maximum allowable thresholds, forcing dual-standard processing lines for export eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Basmati Rice Market |
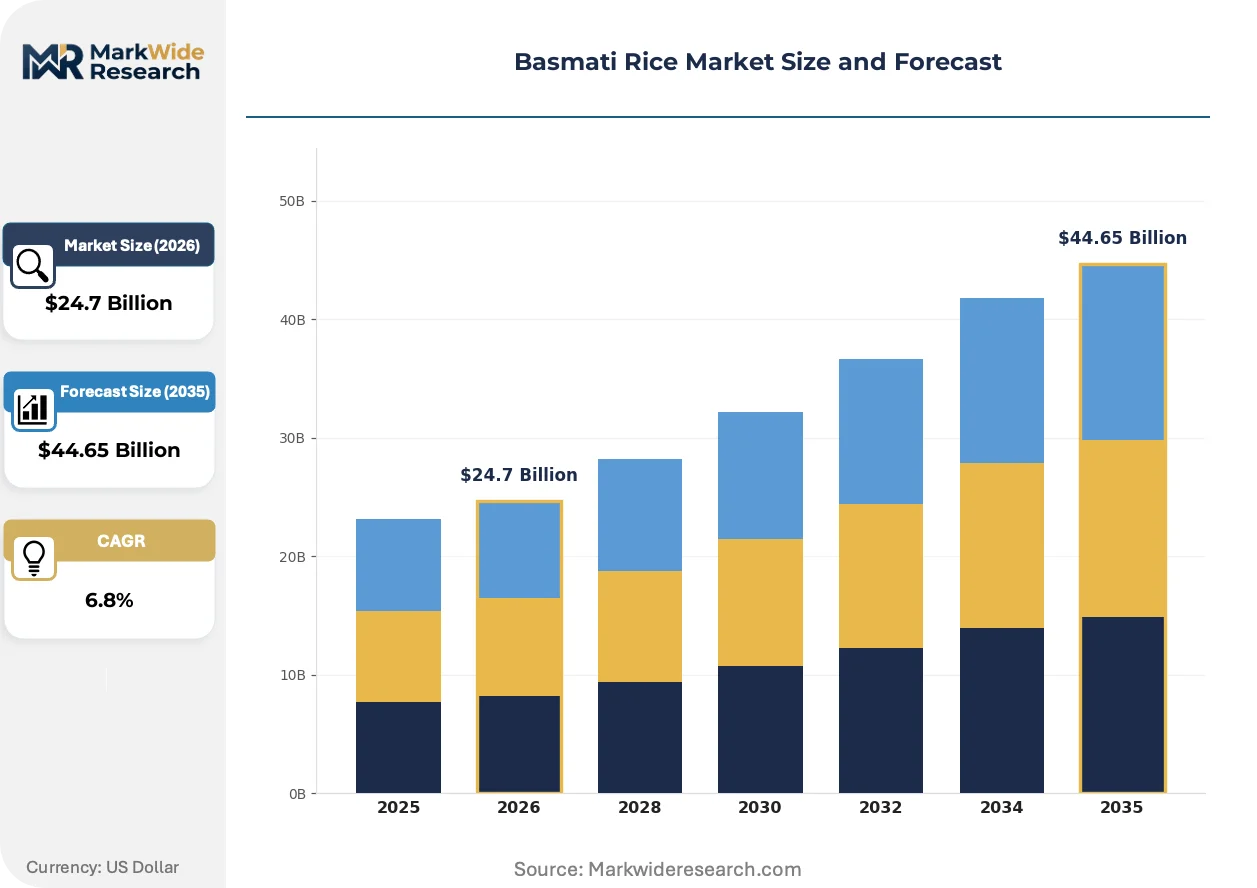
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Basmati, Brown Basmati, Long Grain Basmati, Organic Basmati Packaging Type: Bags, Boxes, Pouches, Bulk Distribution Channel: Supermarkets, Online Retail, Wholesale, Specialty Stores End User: Households, Restaurants, Food Processing, Catering Services |
| Companies Covered | Best Foods, Tilda Basmati Rice, KRBL, HAS Rice Pakistan, Adani Wilmar, LT Foods, Kohinoor Rice, Matco Foods, Amira Nature Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Basmati Rice Market Emerging Trajectories
Digital traceability platforms and renewable energy integration in parboiling operations are compressing traditional processing cost structures while specialty channel buyers harden provenance verification requirements.
Near-infrared spectroscopy for 2-acetyl-1-pyrroline compound detection is overtaking traditional organoleptic assessment methods in premium export grading. European specialty importers and Middle Eastern wholesale buyers are adopting these systems at accelerating pace to reduce lot rejection rates. This technology is overtaking legacy sensory panels, compressing inspection timelines from days to hours while hardening varietal purity enforcement.
REACH-related contaminant screening expansion under the EU Green Deal is recalibrating procurement standards across European retail channels. Maximum residue limit protocols for agrochemical traces now block substantial South Asian volume despite meeting origin-country food safety thresholds. Premium organic and heritage varietal segments are absorbing compliance costs fastest, while standard-grade exporters face progressive market access erosion.
Diaspora household purchasing through ethnic grocery chains is fragmenting traditional importer-distributor concentration in North America and Europe. Second-generation South Asian consumers in the United Kingdom and Canada are shifting toward direct-sourced heritage varietals with verifiable aging documentation. This pattern is most visible in Toronto and London metropolitan clusters, where specialty retailers now compete on grain elongation ratio certification rather than price alone.
Basmati Rice Market Segmentation
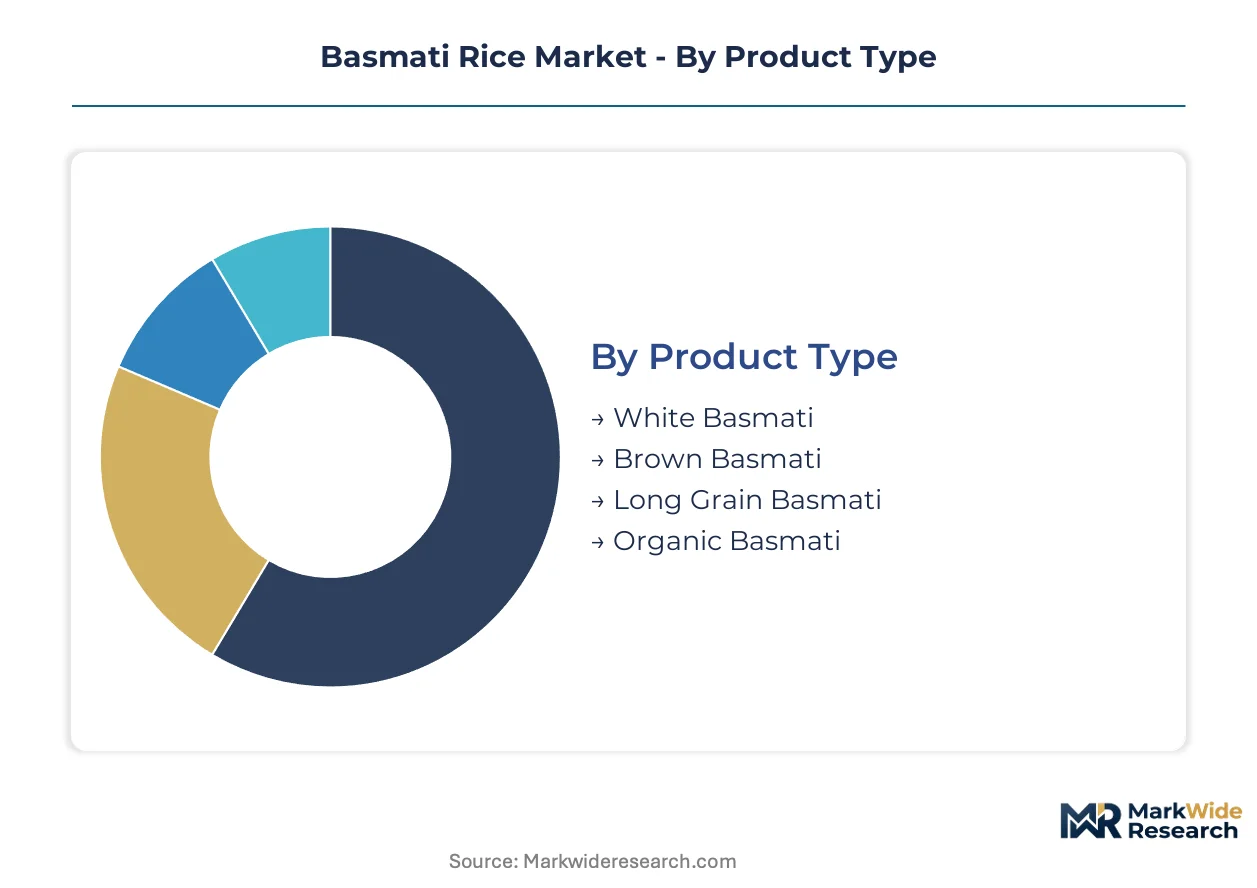
Basmati rice segmentation reveals distinct compliance architectures across product grades, with certification requirements varying sharply between conventional and organic categories. Packaging and channel strategies must align with aging infrastructure constraints and diaspora purchasing patterns in destination markets.
Product Type:
White Basmati carries BIS grading obligations alone, while Brown and Organic variants layer USDA or EU organic certification atop origin-authentication requirements.
- White Basmati:Milled to remove bran layer and polished to uniform appearance, this grade commands volume throughput due to established parboiling infrastructure across Punjab and Haryana. Saudi Arabian and UAE import quotas prioritize aged White Basmati inventory with documented 12–18 month maturation cycles.
- Organic Basmati:Cultivated under zero-synthetic-input protocols with third-party audit trails, this segment captures margin premiums in European retail banners enforcing EU Green Deal procurement mandates. REACH-related contaminant screening blocks substantial conventional volume, accelerating certified heritage varietal sourcing.
- Brown Basmati:Retains bran layer for fiber concentration, serving health-positioned channels in North American metropolitan clusters where minimal processing commands shelf-space premiums.
- Long Grain Basmati:Specifies grain elongation ratio minimums exceeding 3.5:1 upon cooking, with varietal purity enforcement through near-infrared spectroscopy detection of 2-acetyl-1-pyrroline compounds.
White Basmati sits at the top of the volume ranking, with Organic Basmati climbing the fastest.
Packaging Type:
Cost tiers separate commodity bulk shipments from premium consumer-facing formats with climate-control and traceability features.
- Bags:Polypropylene or jute woven sacks dominate Middle Eastern wholesale procurement, with moisture-barrier specifications critical for aged inventory preservation during extended Gulf storage.
- Pouches:Vacuum-sealed retail formats with oxygen scavengers serve diaspora households in Toronto and London metropolitan clusters seeking verifiable aging documentation.
- Boxes:Rigid packaging for gift-grade heritage varietals targets festival-season demand concentration in South Asian communities.
- Bulk:Containerized loose grain shipments to integrated millers and food processors minimize per-unit packaging cost for high-volume restaurant and catering procurement.
Bulk shipments represent the dominant cost tier for foodservice procurement, with pouches expanding most quickly in direct-to-consumer channels.
Distribution Channel:
Channel selection determines margin stacking depth and Geographical Indication enforcement exposure for origin-country exporters.
- Supermarkets:Mass retail banners in the United Kingdom and Germany enforce EU REACH screening protocols that block substantial South Asian volume despite BIS compliance, reshaping supplier eligibility criteria.
- Specialty Stores:Ethnic grocery chains in Canada fragment traditional importer-distributor concentration, with second-generation South Asian consumers prioritizing grain elongation certification over price positioning.
- Wholesale:Middle Eastern consolidated procurement through Saudi and UAE trading houses sustains volume throughput for aged inventory pipelines with established credit terms.
- Online Retail:Direct-to-consumer platforms bypass margin stacking, though cold-chain logistics requirements for climate-sensitive aged stock constrain geographic reach.
Wholesale channels anchor volume concentration in Gulf markets, with specialty stores gaining share fastest in North American diaspora clusters.
End User:
Application-specific requirements drive divergent aging, purity, and packaging specifications across consumption contexts.
- Restaurants:South Asian cuisine establishments in the United Kingdom and Canada require consistent grain elongation performance for biryani preparation, with lot rejection costs driving near-infrared spectroscopy adoption.
- Households:Diaspora purchasing patterns fragment toward heritage varietals with verifiable provenance, particularly in Toronto and London metropolitan areas.
- Food Processing:Ready-meal manufacturers and parboiled rice product lines enforce broken-grain percentage thresholds stricter than BIS export minima.
- Catering Services:Volume procurement for wedding and festival events in Middle Eastern markets prioritizes aged stock with fluffy texture characteristics.
Household consumption sits at the top of the volume ranking, with food processing climbing the fastest as ready-meal manufacturers harden incoming quality protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Basmati rice trade originated in the Indo-Gangetic plains, where centuries-old cultivation practices in Punjab and Haryana established the varietal standards now enforced through modern Geographical Indication frameworks.
India
Punjab and Haryana supply over 70 percent of export-grade Basmati, with BIS grading standards enforcing varietal purity and broken-grain thresholds. The FSSAI coordinates with DGFT to maintain export eligibility protocols. Amritsar and Karnal millers operate integrated aging warehouses serving Middle Eastern procurement houses.
Pakistan
Punjab province generates the majority of Pakistani Basmati exports, competing directly with Indian origin claims in third-country markets. The national food safety authority enforces divergent broken-grain standards that complicate dual-market processing. Karachi-based exporters navigate Geographical Indication disputes through sustained legal expenditure.
Saudi Arabia
The Kingdom maintains the highest per-capita import volume globally, with consolidated procurement through Jeddah and Riyadh trading houses prioritizing 12–18 month aged inventory. SFDA import protocols screen for documented maturation cycles. Dammam port facilities handle bulk containerized shipments under established credit terms.
United Arab Emirates
Dubai and Abu Dhabi serve as re-export hubs for Gulf Cooperation Council distribution, with MOHAP food safety screening layered atop origin-country certifications. The emirates' wholesale trading houses sustain volume throughput for aged stock pipelines. Sharjah's warehousing infrastructure supports climate-controlled grain preservation.
United Kingdom
London and Birmingham metropolitan clusters fragment traditional importer-distributor concentration through ethnic grocery chain expansion. EU REACH contaminant screening blocks substantial South Asian volume despite BIS compliance, reshaping supplier eligibility. Second-generation South Asian consumers prioritize grain elongation certification over price positioning.
Basmati Rice Market Vendor Landscape
Capital-heavy integrated millers compete with asset-light specialty traders across procurement, aging, and export grading functions. The vendor base concentrates around Punjab and Haryana processing corridors, with tiered differentiation across organic certification, heritage varietal portfolios, and direct-to-consumer channel penetration. Strategic archetypes include vertically integrated volume leaders, certified organic specialists, and diaspora-focused brand builders. Competitive moves center on aging infrastructure expansion and specialty retail shelf-space allocation.
Within the integrated milling tier, KRBL and LT Foods exemplify divergent positioning strategies. KRBL anchors volume leadership through captive parboiling and climate-controlled warehousing infrastructure. LT Foods occupies a position within certified organic and heritage varietal sourcing for North American specialty grocers. HAS Rice Pakistan represents Pakistani-origin exporters navigating Geographical Indication enforcement complexity in shared destination markets.
| Leading Market Players |
|---|
| Best Foods |
| Tilda Basmati Rice |
| KRBL |
| HAS Rice Pakistan |
| Adani Wilmar |
| LT Foods |
| Kohinoor Rice |
| Matco Foods |
| Amira Nature Foods |
| Others |
Supply Flow & Price Mechanics
Backward integration into captive aging warehouses anchors both supply security and pricing power for integrated millers serving Middle Eastern procurement houses. Punjab and Haryana millers with climate-controlled infrastructure command premium realizations over asset-light traders dependent on third-party storage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic heritage varietals from conventional export grades and broken-rice commodity tiers. Price differentiation rests on BIS purity certification and documented 12–18 month aging cycles, with EU REACH compliance adding a further certification premium. Cost compression in standard-grade export tiers is intensifying because monsoon-dependent paddy procurement generates harvest volatility. Foodservice buyers in Saudi Arabia and the UAE show lowest price sensitivity, prioritizing consistent grain elongation performance for biryani preparation.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Amritsar and Karnal milling clusters to Jeddah, Dubai, and London re-export nodes. Geographic supply concentration centers on India and Pakistan, with over 70 percent of export-grade volume originating from Punjab and Haryana. Raw material dependencies draw from monsoon-fed paddy cultivation, synthetic fertilizer inputs, and jute or polypropylene packaging materials. Single-source vulnerability to climate anomalies in the Indo-Gangetic belt threatens harvest predictability. Distribution runs through consolidated wholesale trading houses in Gulf markets and fragmenting ethnic grocery chains in North American and European diaspora clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor certified organic specialists and heritage varietal portfolio builders as EU Green Deal procurement mandates harden compliance premiums. Carbon-border adjustment preparation and renewable energy transition in parboiling operations constitute the primary cost-down pathway.
For Market Incumbents: Cement volume leadership through captive aging infrastructure expansion in Punjab and Haryana, defending against asset-light specialty traders encroaching on premium segments. Prioritize BIS and EU organic dual-certification investment to capture compliant supply premiums as REACH-related contaminant screening blocks conventional volume from European retail channels.
For New Entrants and Emerging Players: Specialty e-commerce platform partnerships offer the most penetrable channel wedge for direct-to-consumer heritage varietal distribution in Toronto and London metropolitan clusters. Target underdeveloped USDA organic certification penetration among Pakistani-origin exporters, leveraging first-mover positioning in North American specialty grocer procurement.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap integrated millers because aging infrastructure scarcity and fragmented landholding patterns prevent rapid greenfield replication. Five-to-ten-year viability hinges on carbon-border adjustment compliance positioning. Monitor EU Green Deal implementation timelines as the critical inflection signal for landed-cost competitiveness restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Controlled Aging Infrastructure Expansion | Captive warehousing capacity in Punjab and Haryana secures 12–18 month maturation pipelines for Gulf procurement houses. |
| Dual-Certification Investment (BIS + EU Organic) | REACH-compliant heritage varietal sourcing unlocks premium shelf-space allocation in German and UK retail banners. |
| Renewable Energy Transition in Parboiling | Solar thermal integration for drying operations reduces carbon intensity ahead of EU carbon-border adjustment mechanisms. |
| Direct-to-Consumer Channel Development | E-commerce platforms bypass traditional importer-distributor margin stacking in Toronto and London diaspora clusters. |
| Near-Infrared Spectroscopy Grading Adoption | 2-acetyl-1-pyrroline compound detection hardens varietal purity enforcement for Middle Eastern wholesale buyers. |
Methodological Framework
Bottom-up household and foodservice consumption modeling reconciled against top-down export volume tracking forms the analytical core of this study. Primary interviews with integrated miller executives, specialty grocer category buyers, Middle Eastern trading house procurement managers, and diaspora community retail operators combined with secondary validation from FSSAI export filings, DGFT trade statistics, EU REACH compliance databases, and customs records across destination markets. Triangulation across these sources ensures granular alignment between origin-country production estimates and import-destination consumption patterns.
Input-output matrices map paddy procurement flows through parboiling, aging, milling, and export grading stages across the projection horizon. Segmentation dimensions modeled include product type, certification tier, packaging format, distribution channel, and end-use application, with CAGRs derived from elasticity-adjusted demand projections and supply-side capacity constraints. Industry-specific forecast inputs incorporate monsoon variability indices, EU Green Deal implementation timelines, and diaspora population growth patterns in key destination markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to climate anomaly frequency, water allocation disputes in the Indo-Gangetic belt, and carbon-border adjustment mechanism scope expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Sorghum Market
Grains
Wheat Flour Market
Grains
South America Wheat Market
Grains
Global Flour Market
Grains
Cameroon Grains Market
Grains
South America Rice Market
Grains
Organic Cereals Market
Grains
Europe Maize Market
Grains
Tunisia Grain Market
Grains
Barley Grass Market
Grains
United States Maize Market
Grains
Europe Wheat Protein Market
Grains
Europe Rice Market
Grains
South Africa Grain Market
Grains
Barley Market
Grains
Spain Rice Market