
 China Rice Market | 2026-2036
China Rice Market Size, Share, and Industry Trends Forecast 2026-2036
China Rice Market Analysis
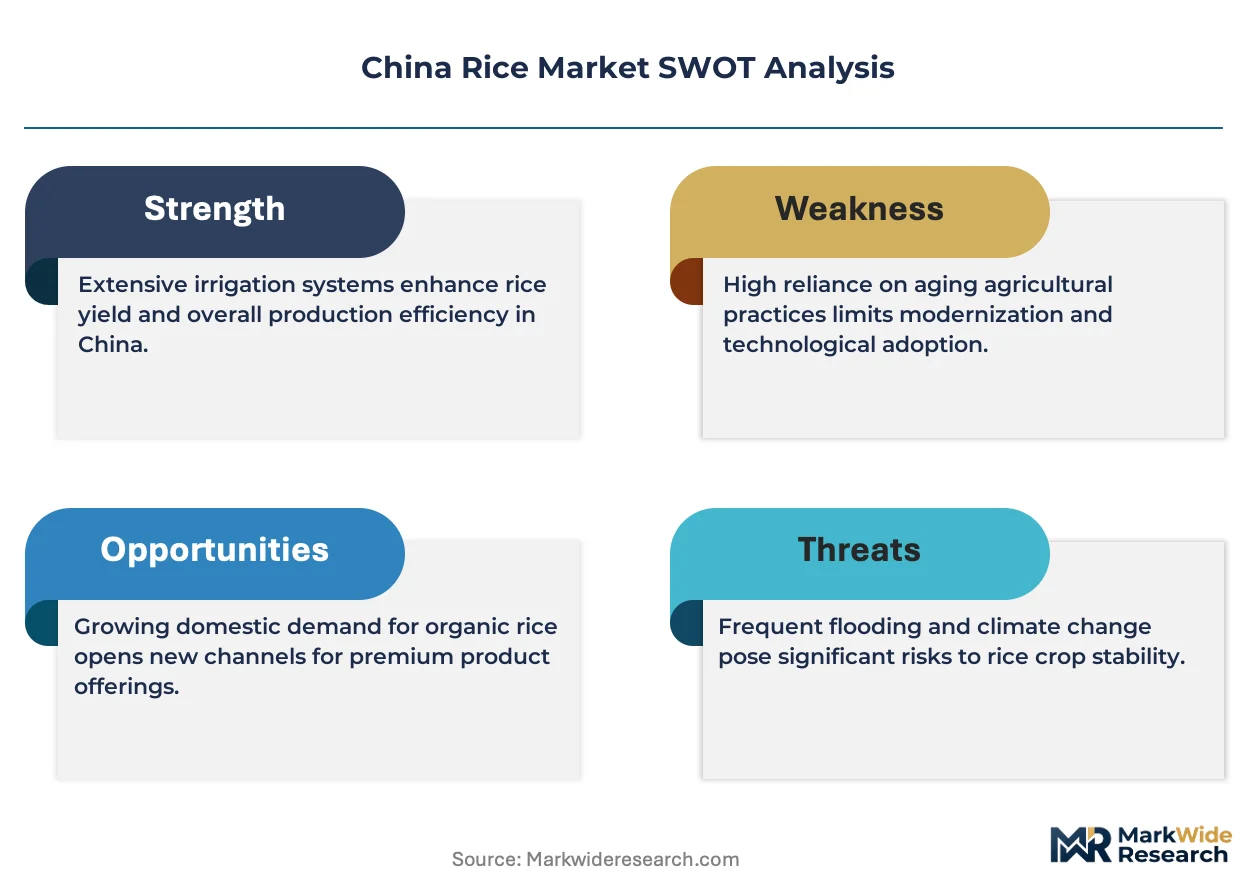
China's national food security strategy and the Ministry of Agriculture and Rural Affairs' green development benchmarks are pivoting domestic rice production toward lower-carbon cultivation methods. Yuan Longping High-Tech Agriculture Co. Ltd leverages its hybrid rice research heritage to sustain germplasm leadership across southern provinces. Jiangsu Zhongjiang Seed Industry Co. Ltd anchors premium seed supply in the Yangtze Delta, while China National Seed Group Co. Ltd dominates state-backed distribution channels and strategic reserve procurement.
Rice comprises the starchy endosperm of Oryza sativa grains, milled to remove hull and bran layers, with amylose content ranging from five to twenty-five percent determining cooking texture and digestibility. The grain serves as China's primary dietary carbohydrate source and industrial starch feedstock. White rice occupies the largest volume share in household and institutional channels, though organic and non-GMO grades within the quality grade dimension command disproportionate margin pools as urban consumers trade up. The food service application segment is expanding fastest, driven by centralized kitchen chains and ready-meal processors seeking consistent grain specifications.
SAMR enforces grain quality and labeling standards, while MEE regulates agricultural runoff and methane emissions from paddy fields under national pollution control frameworks. BIS-aligned testing protocols for imported rice varieties further shape market access conditions for foreign suppliers. Stakeholders must monitor evolving carbon intensity metrics in provincial procurement tenders and the pace of irrigation infrastructure modernization across the Northeast Plain.
Market Dynamics
China's dual carbon goals and national food security mandates are compressing cultivation timelines while forcing wholesale adoption of methane-mitigating paddy management across the Northeast Plain and Yangtze Delta. Provincial procurement offices now weight carbon intensity metrics alongside yield benchmarks in seed variety selection.
Growth Catalysts
- Food Service Centralization:Centralized kitchen chains and ready-meal processors are absorbing larger volumes of premium rice varieties with consistent grain specifications. This institutional demand concentrates procurement power among specifications-driven buyers.
- MEE Methane Regulations:The Ministry of Ecology and Environment's agricultural runoff and methane emission controls are accelerating adoption of alternate wetting and drying irrigation protocols. Compliance investments unlock preferential access to state grain reserve contracts.
- Yangtze River Delta Clustering:Economic density in Shanghai, Jiangsu and Zhejiang provinces generates concentrated demand for organic and non-GMO certified grades. Urban household income trajectories support sustained trade-up behavior in this corridor.
Market Restraints
- Water Input Volatility:Irrigation infrastructure modernization lags across the Northeast Plain, exposing rain-fed acreage to yield instability. Groundwater depletion in northern provinces intensifies production cost pressure.
- Seed Supply Concentration:Germplasm leadership consolidates among state-backed research institutes and licensed commercial breeders. Foreign genetic material faces BIS-aligned testing protocols that extend variety approval timelines.
- Substitution Pressure:Wheat and potato starch alternatives capture institutional carbohydrate demand in northern provinces. Dietary diversification campaigns in urban centers erode per-capita rice consumption trends.
Strategic Opportunities
- Carbon-Certified Premium Channels:SAMR's evolving grain quality and labeling standards create white space for verified low-carbon rice grades. Early compliance positions suppliers for provincial tender preference.
- Pearl River Delta Penetration:Guangdong and Fujian provinces show underpenetrated organic rice distribution relative to disposable income levels. Specialty retail and e-commerce direct fulfillment remain fragmented.
- Smart Irrigation Convergence:Integration of soil moisture sensors with drone-based nutrient application is reducing water intensity. Technology adopters achieve measurable methane reduction eligible for carbon credit schemes.
Industry Challenges
- Agronomist Skill Compression:Hybrid rice breeding expertise concentrates among retiring research cohorts. Knowledge transfer to commercial seed operations faces institutional friction.
- Certification Timeline Burden:Organic and non-GMO grade verification requires multi-year field history documentation. Smallholder compliance costs disadvantage fragmented farm structures.
- Legacy Procurement System Integration:Provincial grain bureaus operate on paper-based reserve allocation workflows. Digital traceability mandates create parallel reporting requirements without system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Rice Market |
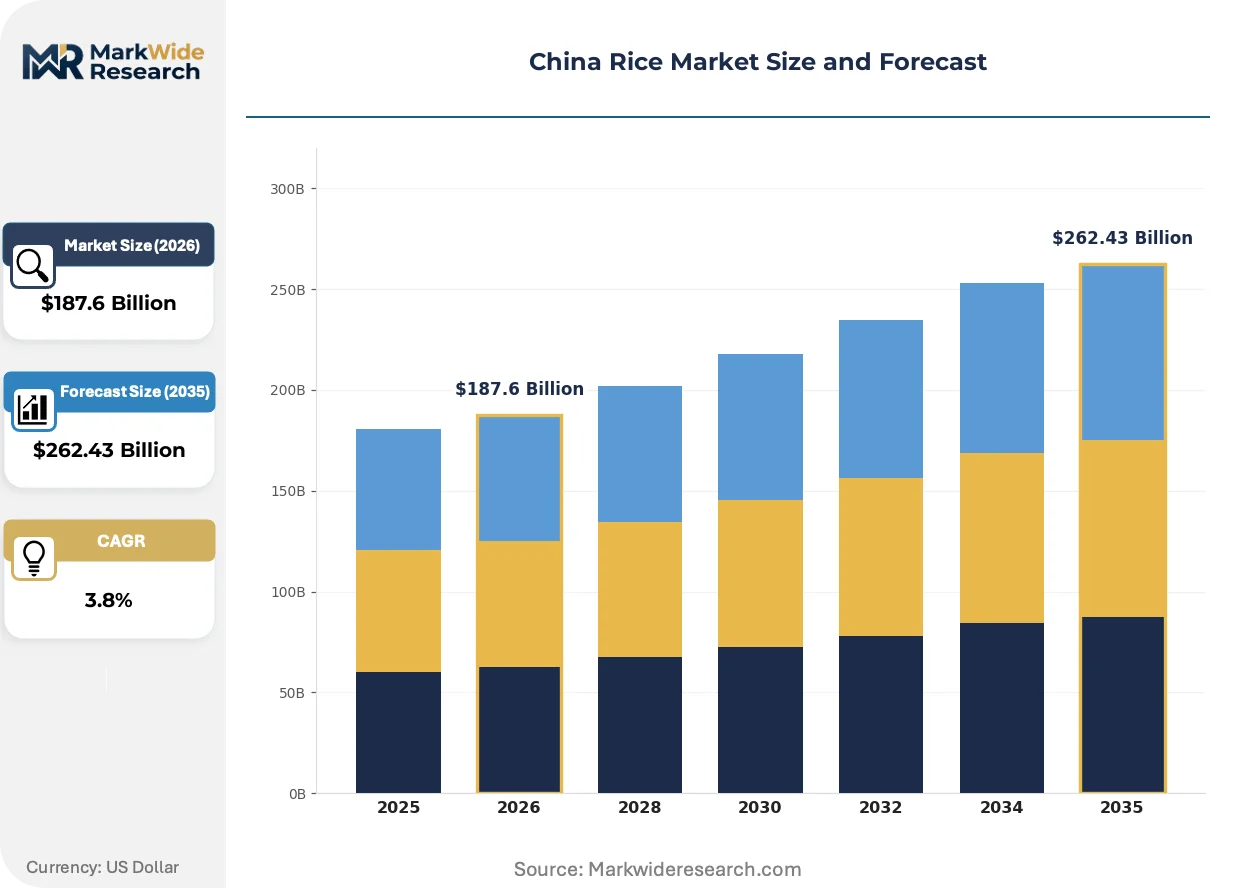
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $262.43 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rice, Brown Rice, Jasmine Rice, Basmati Rice Distribution Channel: Supermarkets, Online Retailers, Wholesale Markets, Farmers' Markets Application: Household, Food Service, Export, Industrial Quality Grade: Grade A, Grade B, Organic, Non-GMO |
| Companies Covered | Hefei Fengle Seed Industry Co. Ltd, Jiangsu Zhongjiang Seed Industry Co. Ltd, Yuan Longping High-Tech Agriculture Co. Ltd, Shandong Denghai Seed Co. Ltd, China National Seed Group Co. Ltd, Anhui Tsuen Yin Hi-Tech Seed Industry Co. Ltd, Zhongnongfa Seed Industry Group Co. Ltd, Heilongjiang Academy of Agricultural Sciences, Beidahuang Kenfeng Seed Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Rice Market Emerging Trajectories
Precision agriculture technologies and carbon accounting protocols are rewriting cultivation economics across China's rice belt. The intersection of state environmental mandates and commercial buyer specifications is accelerating technology diffusion beyond traditional adoption curves.
Drone-based variable-rate nitrogen application is decentralizing agronomic decision-making from county-level extension stations to individual farm operators. Medium-scale cooperatives in Jiangsu and Anhui provinces are deploying these systems at accelerating replacement cycles for manual scouting. The technology is decentralizing input procurement authority, compressing traditional supply hierarchies that routed through township-level distributors.
SAMR's carbon labeling pilot programs for agricultural products are mandating lifecycle emission disclosure for packaged rice entering premium retail channels. Industrial consequence includes mandatory third-party verification of paddy methane estimates and irrigation energy intensity. Northeast Plain processors face the steepest compliance adaptation given legacy drying infrastructure and coal-dependent thermal systems.
Urban household buyers are consolidating purchases through membership-based fresh food platforms that bundle certified grain with produce assortments. Traditional wholesale market channels lose volume share to these vertically integrated subscription models. Shanghai and Hangzhou metro areas exhibit the most pronounced channel migration, with specifications-driven procurement now dominating household rice selection.
China Rice Market Segmentation
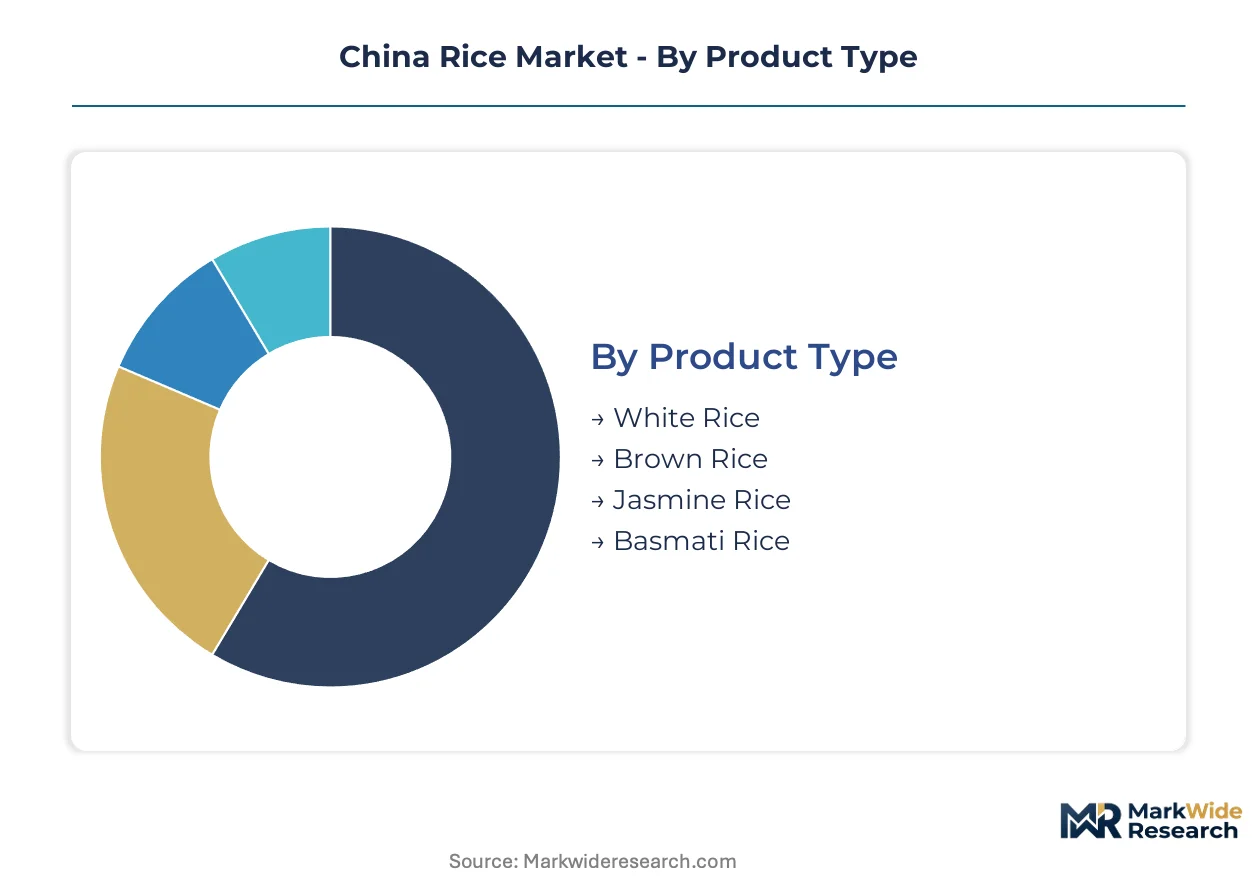
Segmentation in China's rice market reveals how procurement power concentrates among institutional buyers while household purchasing fragments across certification tiers. SAMR's evolving labeling mandates and provincial carbon procurement protocols are compressing the viable specification range for commercial suppliers.
Product Type:
Standardization dominates mass-market channels while specialty varieties command specification premiums in clustered urban demand zones.
- White Rice:Milled grains with hull and bran removed, amylose content ranging from five to twenty-five percent determining cooking texture. Volume concentrates in institutional procurement from Yangtze River Delta centralized kitchens, where consistent hydration properties reduce batch variability. MEE methane compliance costs are compressing margins for non-certified suppliers.
- Brown Rice:Partially milled grains retaining bran layer, delivering higher fiber content and extended shelf stability. Demand clusters in Shanghai and Hangzhou metro health-conscious households, with membership-based fresh food platforms capturing disproportionate share through bundled produce assortments.
- Jasmine Rice:Aromatic long-grain variety with distinctive floral notes, primarily sourced from southern provinces.
- Basmati Rice:Extra-long grain variety with low amylose content, serving ethnic restaurant channels and specialty retail.
Leading the category by volume: White Rice. Growing fastest: Brown Rice.
Distribution Channel:
Channel evolution tracks infrastructure modernization gaps between coastal clusters and interior provinces.
- Supermarkets:Branded retail footprint with certified grade segregation and traceability documentation. Penetration deepest in Pearl River Delta urban cores, where disposable income supports organic and non-GMO trade-up behavior.
- Online Retailers:Direct fulfillment platforms with subscription bundling and specifications-driven procurement. Shanghai and Hangzhou exhibit most pronounced channel migration, with vertically integrated models displacing traditional wholesale volume.
- Wholesale Markets:Legacy procurement hubs serving institutional buyers and rural distributors.
- Farmers' Markets:Localized spot purchasing with limited certification verification infrastructure.
Highest volume throughput: Supermarkets. Channel climbing fastest: Online Retailers.
Application:
End-use segmentation reflects the divergence between household fragmentation and food service consolidation.
- Household:Dispersed consumption across urban income tiers with certification-driven trade-up behavior. Yangtze River Delta economic density generates concentrated organic and non-GMO demand.
- Food Service:Centralized kitchen chains and ready-meal processors absorbing premium varieties with strict grain specifications. This institutional demand concentrates procurement power among specifications-driven buyers.
- Export:BIS-aligned testing protocols shape market access conditions for foreign-bound shipments.
- Industrial:Starch extraction and processed food manufacturing feedstock applications.
Largest volume base: Household. Steepest expansion trajectory: Food Service.
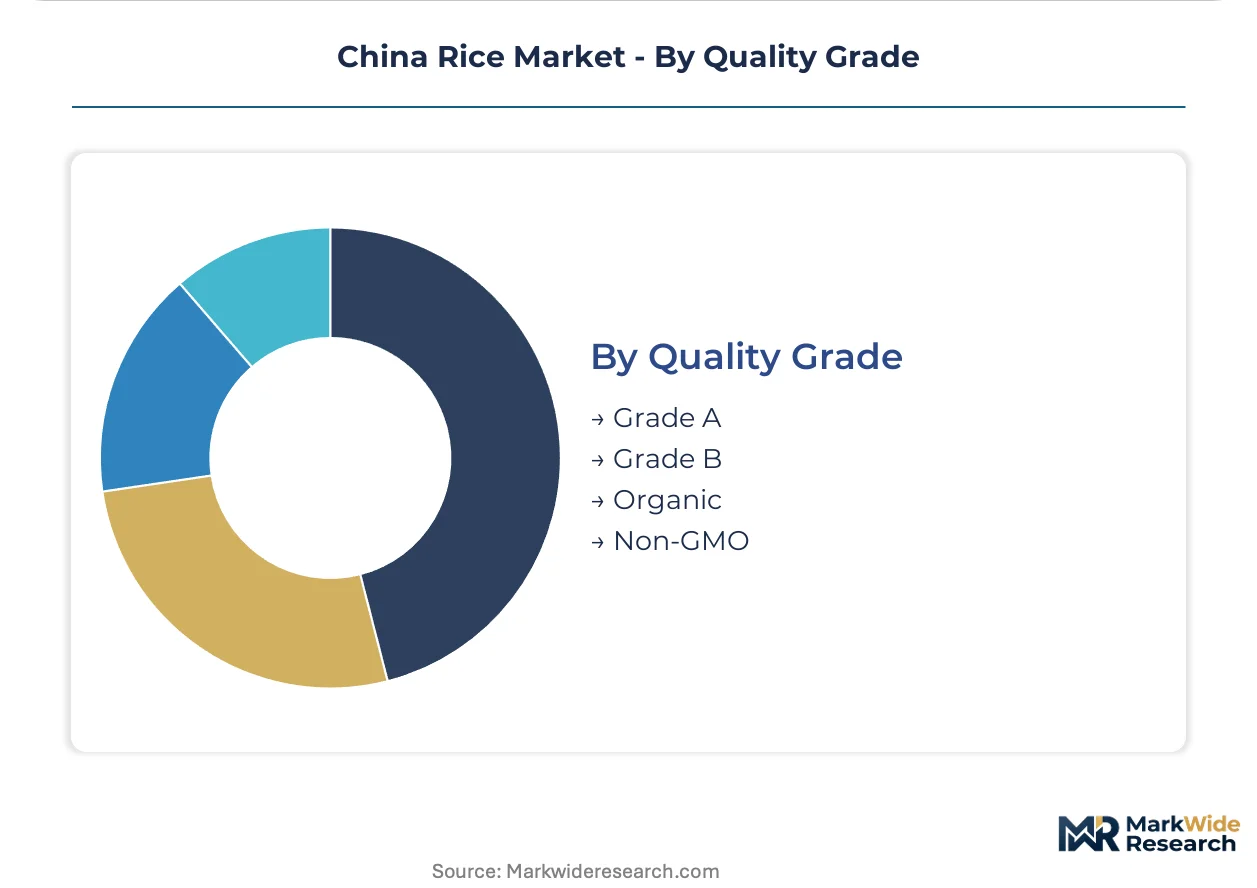
Quality Grade:
Grade stratification determines margin pool access across procurement channels.
- Grade A:Premium milling standards with maximum broken grain thresholds and moisture specifications. State grain reserve procurement increasingly weights carbon intensity metrics alongside traditional quality benchmarks.
- Organic:Multi-year field history documentation required, with verification costs disadvantaging fragmented smallholder structures. SAMR carbon labeling pilots mandate lifecycle emission disclosure for packaged retail entry.
- Grade B:Standard milling tolerances serving price-sensitive mass market channels.
- Non-GMO:Genetic integrity certification capturing urban household premium willingness.
Dominant volume position: Grade A. Gaining share fastest: Organic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors China's rice demand concentration through its Yangtze River Delta economic corridor, where disposable income trajectories and food service centralization generate premium-grade absorption. Provincial procurement offices across Jiangsu, Zhejiang and Anhui now weight carbon intensity metrics alongside yield benchmarks in seed variety selection.
Yangtze River Delta
Shanghai, Jiangsu and Zhejiang provinces concentrate organic and non-GMO certified demand through membership-based fresh food platforms. SAMR's carbon labeling pilots mandate lifecycle emission disclosure for packaged rice entering premium retail channels here. Hangzhou metro area exhibits the most pronounced channel migration from wholesale markets to vertically integrated subscription models.
Pearl River Delta
Guangdong and Fujian provinces show underpenetrated organic rice distribution relative to disposable income levels. MEE methane regulations accelerate adoption of alternate wetting and drying irrigation protocols across paddy fields here. Specialty retail and e-commerce direct fulfillment remain fragmented in Shenzhen and Guangzhou despite concentrated urban household purchasing power.
Northeast Plain
Heilongjiang and Jilin provinces face steepest compliance adaptation given legacy drying infrastructure and coal-dependent thermal systems. Provincial grain bureaus operate on paper-based reserve allocation workflows that create parallel reporting requirements under digital traceability mandates. Harbin-based processors confront groundwater depletion intensifying production cost pressure across rain-fed acreage.
Sichuan-Chongqing
Western China's primary rice-producing corridor absorbs hybrid rice germplasm from state-backed research institutes. China National Seed Group dominates state-backed distribution channels and strategic reserve procurement throughout this basin. Chengdu's centralized kitchen chains and ready-meal processors generate institutional demand for consistent grain specifications.
Beijing-Tianjin-Hebei
Northern provinces experience substitution pressure as wheat and potato starch alternatives capture institutional carbohydrate demand. Dietary diversification campaigns in Beijing and Tianjin urban centers erode per-capita rice consumption trends. SAMR enforces grain quality and labeling standards that shape procurement protocols for state grain reserve contracts.
China Rice Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and carbon-intensity dimensions, with organic and low-carbon verified varieties commanding disproportionate margin pools. The vendor base fragments across state-backed research institutes, licensed commercial breeders and provincial seed distribution networks. Three strategic archetypes dominate: germplasm heritage holders, state distribution channel controllers, and regional cooperative aggregators. Competitive moves concentrate on M&A for seed licensing rights and backward integration into captive germplasm development.
Within the germplasm heritage tier, Yuan Longping High-Tech Agriculture Co. Ltd occupies a position exemplifying hybrid rice research legacy across southern provinces. Jiangsu Zhongjiang Seed Industry Co. Ltd anchors premium seed supply concentration in the Yangtze Delta. China National Seed Group Co. Ltd represents the state-backed distribution archetype, controlling strategic reserve procurement channels nationwide. These three entities illustrate how competitive positioning stratifies between research-originated germplasm leadership and procurement-gatekeeping authority.
| Leading Market Players |
|---|
| Hefei Fengle Seed Industry Co. Ltd |
| Jiangsu Zhongjiang Seed Industry Co. Ltd |
| Yuan Longping High-Tech Agriculture Co. Ltd |
| Shandong Denghai Seed Co. Ltd |
| China National Seed Group Co. Ltd |
| Anhui Tsuen Yin Hi-Tech Seed Industry Co. Ltd |
| Zhongnongfa Seed Industry Group Co. Ltd |
| Heilongjiang Academy of Agricultural Sciences |
| Beidahuang Kenfeng Seed Co. Ltd |
| Others |
Supply Flow & Price Mechanics
Food service procurement concentration among centralized kitchen chains and ready-meal processors enforces specification-driven pricing across China's rice belt, where consistent grain attributes command premiums over spot-market commodity grades. SAMR carbon labeling mandates and MEE methane compliance costs are compressing margins for non-certified suppliers while elevating verified low-carbon varieties into preferential procurement tiers.
Pricing Analysis
Yield-guarantee contracts with seed performance benchmarks anchor value-based pricing for hybrid rice germplasm across southern provinces. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified grades in Yangtze River Delta membership platforms from mass-market white rice in wholesale channels. Pricing pressure stems from groundwater depletion in northern provinces intensifying production cost pressure across rain-fed acreage. Household buyers in Shanghai and Hangzhou metro areas exhibit lowest price sensitivity through subscription bundling, while institutional buyers in Beijing-Tianjin-Hebei negotiate aggressively against wheat and potato starch substitutes.
Supply Chain Analysis
SAMR grain quality standards and dual carbon procurement protocols function as de facto local-content rules, privileging domestic germplasm holders over foreign genetic material facing BIS-aligned testing extensions. Supply concentration centers on Heilongjiang and Jilin provinces for volume production, Jiangsu and Anhui for premium seed development, and Guangdong for food service absorption. Raw material dependencies include certified seed stock, controlled-release fertilizers for methane mitigation, and coal-dependent thermal drying infrastructure in the Northeast Plain. Single-source vulnerability concentrates in state-backed seed distribution channels controlled by China National Seed Group. Distribution runs through provincial grain bureaus with paper-based reserve allocation workflows creating parallel reporting requirements under digital traceability mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEE methane regulations and SAMR carbon labeling mandates construct a cost-of-compliance barrier that rewards early certification investment while disadvantaging fragmented smallholder structures unable to absorb multi-year field history documentation costs.
For Market Incumbents: Anticipate agronomist skill compression as hybrid rice breeding expertise concentrates among retiring research cohorts, locking in germplasm heritage advantages for Yuan Longping High-Tech Agriculture and licensed commercial breeders with institutional knowledge transfer protocols. Defensive consolidation through captive germplasm development and backward integration into smart irrigation convergence protects margin pools against provincial procurement offices weighting carbon intensity metrics in seed variety selection. For New Entrants and Emerging Players: SAMR carbon labeling pilots in the Yangtze River Delta open a window for verified low-carbon rice grades entering premium retail channels with mandatory third-party verification of paddy methane estimates. White-space targets cluster in Pearl River Delta organic rice distribution where specialty retail and e-commerce direct fulfillment remain fragmented relative to Shenzhen and Guangzhou disposable income levels. Go-to-market positioning through membership-based fresh food platforms bundling certified grain with produce assortments bypasses legacy wholesale market channel capture. For Investors and Strategic Acquirers: Distressed-cycle entries favor medium-scale cooperatives in Jiangsu and Anhui provinces deploying soil moisture sensors with drone-based nutrient application at accelerating replacement cycles. Long-term viability across the analysis window hinges on technology adopters achieving measurable methane reduction eligible for carbon credit schemes. Signal to watch: pace of irrigation infrastructure modernization across the Northeast Plain determining which processors can adapt legacy coal-dependent thermal systems to SAMR compliance mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Certified Seed Development | Positions suppliers for provincial tender preference under dual carbon procurement protocols. |
| Smart Irrigation Technology Deployment | Reduces water intensity and unlocks carbon credit eligibility for methane reduction verification. |
| Direct E-Commerce Fulfillment Buildout | Captures channel migration from wholesale markets in Shanghai and Hangzhou metro areas. |
| Backward Integration into Germplasm R&D | Secures licensing rights against state-backed research institute concentration. |
| Membership Platform Partnership | Accesses organic and non-GMO trade-up behavior through bundled produce subscription models. |
Methodological Framework
Multi-period observation of provincial procurement tender weightings, carbon intensity metric adoption curves, and food service centralization rates anchored the trend analysis, supplemented by interviews with seed breeding program directors, provincial grain bureau procurement officers, centralized kitchen chain supply chain managers, and agricultural extension station agronomists. Secondary validation drew from SAMR grain quality standard filings, MEE pollution control framework updates, China National Seed Group distribution channel disclosures, and provincial agricultural statistical yearbooks. Bottom-up acreage and yield estimates triangulated against top-down consumption surveys across the analysis window.
Segment-weighting approaches modeled product type stratification across white, brown, and aromatic varieties; distribution channel evolution tracking online retailer displacement of wholesale markets; application divergence between household fragmentation and food service consolidation; and quality grade tiering from Grade A through organic certification. CAGRs were derived from trend extrapolation of food service absorption rates and carbon compliance cost pass-through elasticity. Industry-specific forecast inputs included MEE methane regulation implementation pace and smart irrigation technology adoption curves in Jiangsu and Anhui cooperatives.
The model assumes a particular technology adoption path for drone-based variable-rate nitrogen application; alternative pathways for manual scouting retention would alter the outlook for decentralized input procurement authority. Forecasts reflect assumptions around SAMR carbon labeling pilot expansion and provincial procurement office digital traceability mandate compliance timelines. Commodity price volatility in fertilizer markets and groundwater access restrictions in northern provinces present revision triggers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Organic Oats Market
Grains
Soybean Market
Grains
Corn Gluten Feed Market
Grains
Basmati Rice Market
Grains
Grain Storage Systems Market
Grains
Grain Silos Market
Grains
Grain and Cereal Crop Market
Grains
Spelt Wheat Market
Grains
White Rice Flour Market
Grains
China Wheat Protein Market
Grains
Heritage Grain Market
Grains
Canada Pulses Market
Grains
Torrified Wheat Market
Grains
00 Flour Market
Grains
South American Maize Market
Grains
Oat Flour Market