
 Grain Storage Silos Market | 2026-2036
Grain Storage Silos Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Storage Silos Market Outlook
Buyer concentration among agricultural producers is decoupling from traditional cooperative-dominated procurement patterns as independent farming enterprises and grain traders expand direct purchasing. AGI leverages its integrated manufacturing network across North America to sustain volume leadership in hopper-bottom systems. Brock Grain Systems anchors its position through specialized engineering services for large-diameter flat-bottom installations. Sukup Manufacturing Co. competes aggressively in the mid-capacity segment with regionally distributed fabrication facilities.
Grain storage silos are cylindrical or rectangular structures engineered from corrugated steel, reinforced concrete, or composite materials, designed with specific aeration rates and moisture control systems to preserve cereal crop quality over extended periods. Flat-bottom silos dominate the large-scale export terminal segment where economies of storage volume outweigh foundation costs, while hopper-bottom configurations lead among agricultural producers requiring rapid discharge cycles for commodity marketing. Steel material construction captures the majority of new installations due to structural adaptability and shorter fabrication lead times compared to concrete alternatives.
The US Department of Agriculture and OSHA establish structural safety and fumigation handling protocols that directly influence silo design specifications and installation compliance costs. Brazil's ANVISA and national agricultural ministry enforce phytosanitary storage standards that shape import eligibility for grain handling equipment. Stakeholders must monitor evolving mycotoxin containment regulations and carbon-accounting requirements for embodied steel as procurement criteria increasingly integrate sustainability verification alongside traditional capacity and durability metrics.
Market Dynamics
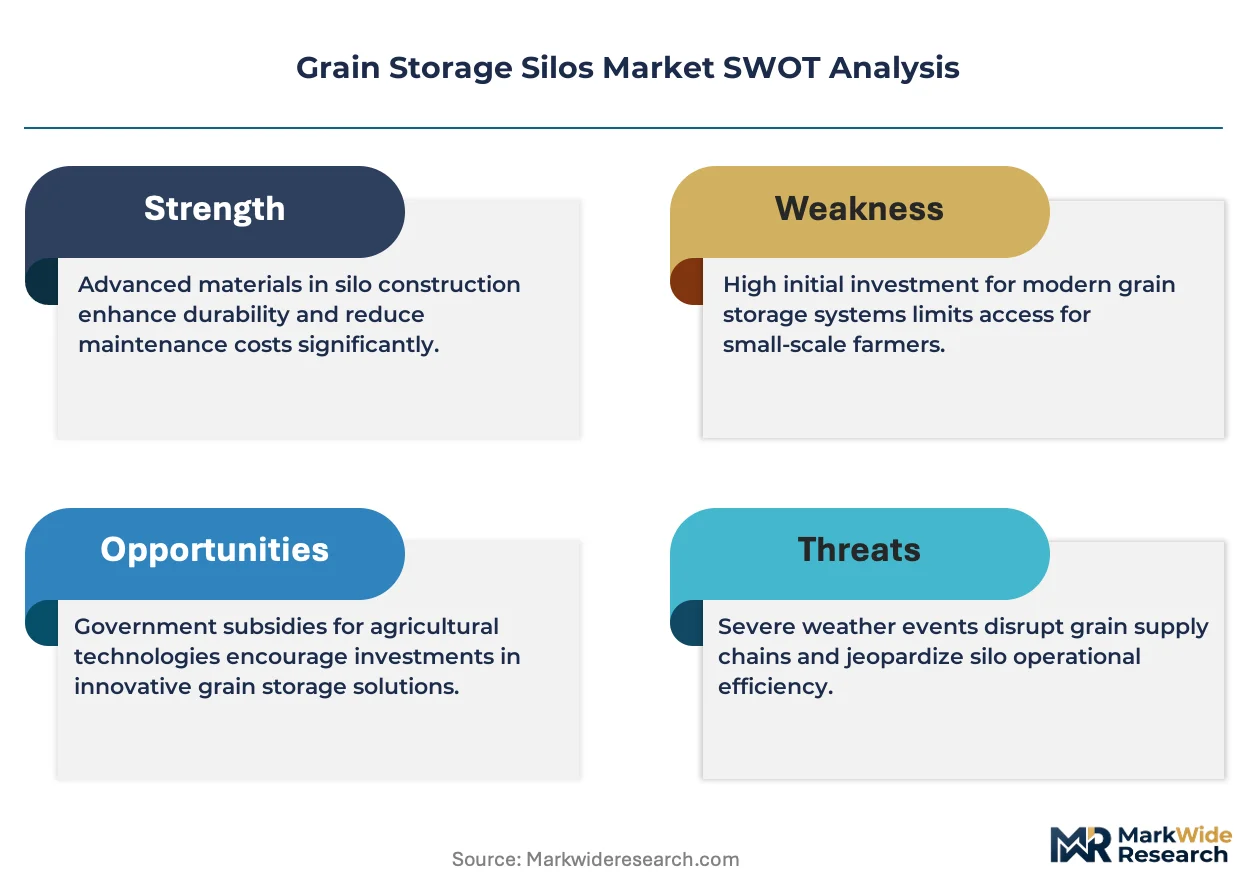
Steel price volatility and foundation engineering complexity are compressing margins for silo fabricators while export-oriented grain traders demand climate-resilient aeration systems that extend storage windows beyond traditional harvest cycles.
Growth Catalysts
- Post-harvest loss mandates:USDA food security programs incentivize on-farm storage infrastructure. Large-scale agricultural producers in the US Corn Belt expand capacity to capture price premiums during seasonal troughs.
- Phytosanitary compliance:Brazil's ANVISA storage standards for export eligibility drive replacement cycles. Grain terminals upgrade to flat-bottom systems with automated temperature monitoring.
- Aeration technology advancement:Variable-speed fan controllers and moisture-sensor integration extend safe storage duration. Ukrainian export operators retrofit existing concrete silos with steel superstructures.
Market Restraints
- Hot-rolled steel input costs:Galvanized coil price swings directly transmit to fabricated silo quotations. Fabricators lack pricing power to pass through volatility to fixed-contract agricultural buyers.
- Foundation engineering concentration:Specialized geotechnical contractors for large-diameter flat-bottom installations cluster in the US Midwest and southern Brazil. Project timelines stretch when these firms face scheduling conflicts.
- Concrete substitution in permanent terminals:Multi-decade storage facilities at major export hubs favor reinforced concrete for fire resistance and structural longevity. Steel silos face displacement in this segment.
Strategic Opportunities
- Ukraine reconstruction infrastructure:War-damaged storage capacity requires rapid-deployment steel systems. Modular hopper-bottom designs suit fragmented farmland ownership patterns.
- Carbon-accounting integration:EU Green Deal embodied-emissions disclosure requirements favor suppliers with verified steel sourcing. Early certification creates differentiation in European procurement.
- Remote monitoring convergence:IoT sensor networks and predictive maintenance algorithms reduce spoilage risk. Grain traders adopt subscription-based platform models alongside hardware procurement.
Industry Challenges
- Structural welding certification timelines:AWS D1.1 qualified welder shortages extend fabrication schedules. Training pipelines lag demand spikes during harvest-season procurement windows.
- Legacy concrete silo integration:Retrofit aeration systems must interface with decades-old foundations and discharge mechanisms. Engineering validation costs erode project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Storage Silos Market |
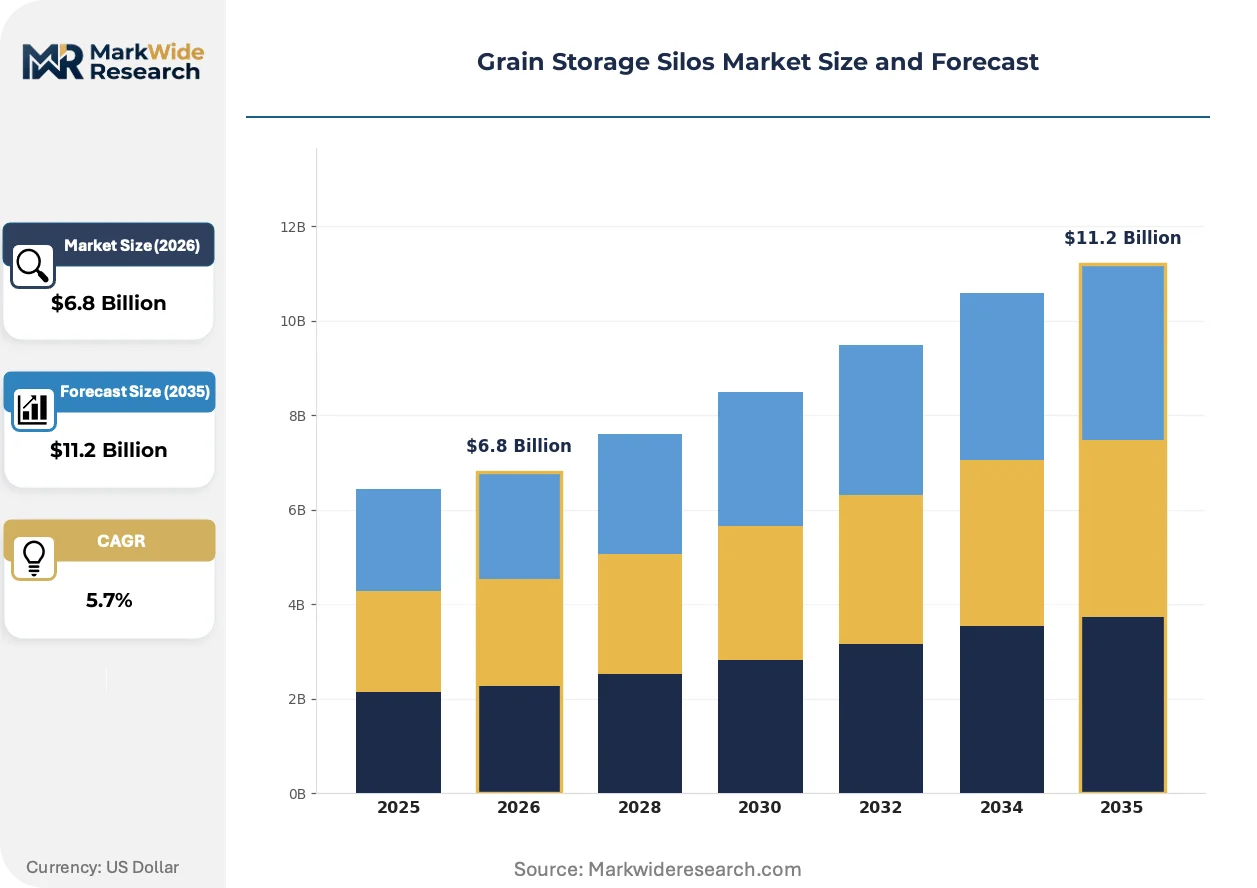
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bottom Silos, Hopper Bottom Silos, Bin Type Silos, Mobile Silos Material: Steel, Concrete, Fiberglass, Plastic End User: Agricultural Producers, Grain Traders, Cooperatives, Food Manufacturers Capacity: Small Scale, Medium Scale, Large Scale, Custom Size |
| Companies Covered | Brock Grain Systems, Sioux Steel Company, Ag Growth International Inc (AGI), Hoffmann Inc., CST Industries, Sukup Manufacturing Co., Chief Agri/Industrial Group, Symaga S.A.U, CTB Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Storage Silos Market Strategic Shifts
Digitalization of grain quality monitoring and modular fabrication techniques are compressing project delivery timelines while reshaping buyer expectations for operational intelligence.
Corrugated galvanized steel with zinc-aluminum-magnesium coating is electrifying durability standards for coastal and high-humidity installations. Brazilian soybean operators near Atlantic ports adopt these specifications to combat accelerated corrosion. The material is electrifying procurement criteria as traders demand 25-year structural warranties that legacy hot-dip galvanizing cannot match.
OSHA's updated confined-space entry protocols for grain handling facilities mandate continuous atmospheric monitoring systems. Silo designers integrate fixed gas-detection arrays and automated ventilation triggers into new installations. US agricultural cooperatives absorb compliance costs through operational insurance premium reductions.
Direct procurement from fabricators is displacing traditional cooperative purchasing consortia. Independent farming enterprises in Iowa and Illinois negotiate volume contracts with regional steel shops. This channel shift concentrates specification authority with agronomists rather than generalist purchasing managers.
Grain Storage Silos Market Segmentation
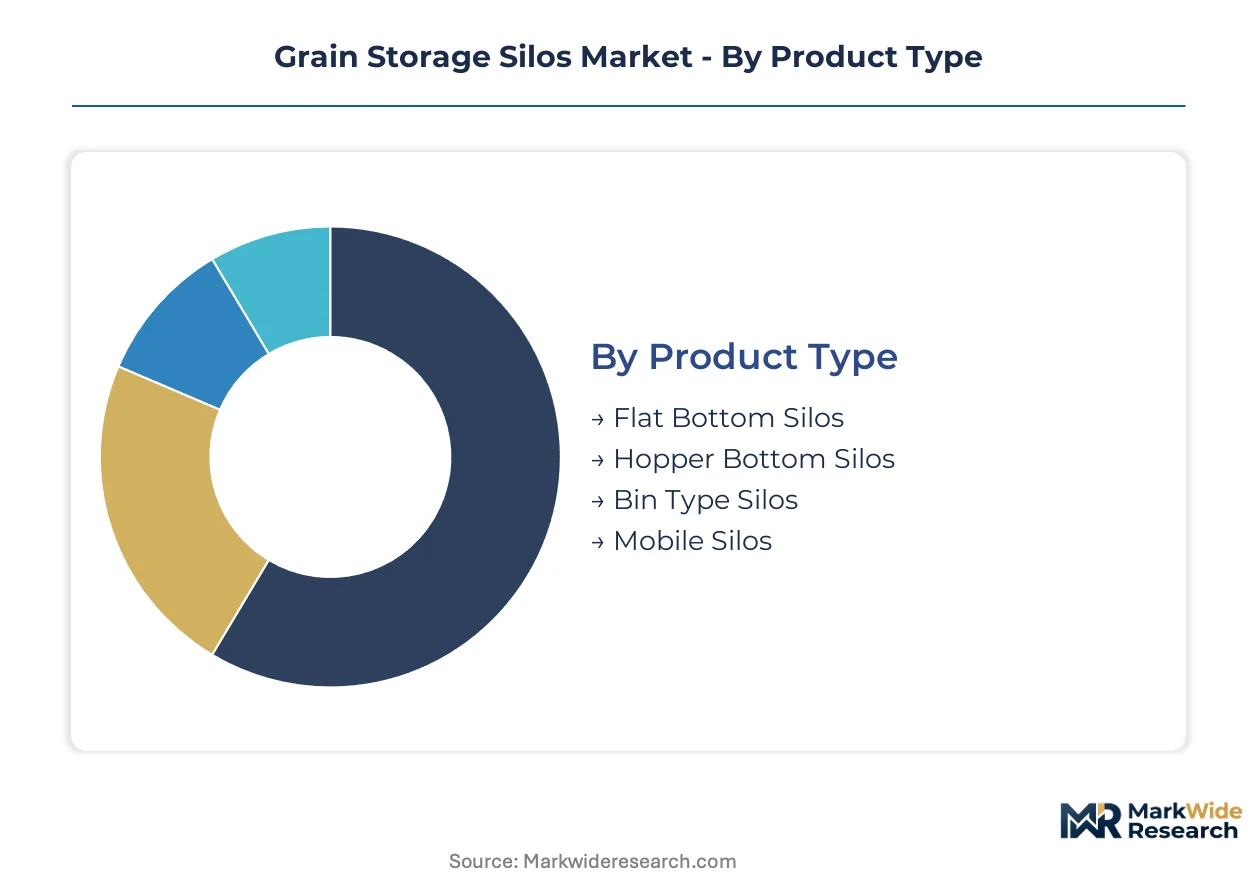
Grain storage silo procurement varies sharply by operational scale and crop marketing strategy. Specification authority concentrates with agronomists at agricultural enterprises and grain traders who prioritize discharge speed, aeration precision, and foundation economics over upfront capital cost.
Product Type:
Customization intensity spans from engineered-to-order flat-bottom foundations to standardized hopper-bottom modules shipped from distributed fabrication networks.
- Flat Bottom Silos:Reinforced concrete foundations support corrugated steel walls with diameters exceeding 30 meters for export terminal installations. Brazilian grain terminals along the Santos corridor deploy these configurations to achieve maximum storage density per hectare of terminal footprint.
- Hopper Bottom Silos:Self-supporting steel cones enable gravity discharge without mechanical sweep augers, cutting operational labor. Ukrainian agricultural producers favor 100-500 tonne units for rapid crop liquidation during volatile price windows.
- Bin Type Silos:Smaller-diameter cylindrical units serve on-farm buffer storage with minimal foundation requirements.
- Mobile Silos:Trailer-mounted configurations support harvest logistics contractors and temporary overflow capacity.
Most installed capacity flows through flat-bottom installations at permanent terminals. Expansion is steepest in hopper-bottom systems as independent farming enterprises build marketing flexibility.
Material:
Foundation permanence and corrosion exposure dictate material selection across coastal, humid continental, and arid production zones.
- Steel:Corrugated galvanized coils with zinc-aluminum-magnesium coatings dominate new fabrication due to structural adaptability and shorter lead times. US Corn Belt fabricators source hot-rolled coil from domestic mills to control specification consistency.
- Concrete:Reinforced cast-in-place structures anchor multi-decade export terminals where fire resistance and structural longevity outweigh first-cost premiums. Black Sea port authorities specify concrete for permanent installations.
- Fiberglass:Chemical-resistant shells serve specialty seed storage and high-value organic grain preservation.
- Plastic:Rotationally molded polyethylene units address small-scale on-farm storage with minimal installation infrastructure.
Steel fabrication commands the majority of annual installations. Concrete retains structural preference at permanent export hubs.
End User:
Procurement authority is fragmenting from cooperative consortia toward direct negotiations by independent operators and specialized traders.
- Agricultural Producers:Iowa and Illinois farming enterprises specify aeration-integrated hopper systems to capture seasonal price premiums through extended storage windows.
- Grain Traders:Export-oriented operators demand automated temperature monitoring and remote sensing integration for phytosanitary compliance documentation.
- Cooperatives:Legacy purchasing consortia consolidate specifications across member farms to achieve fabrication volume discounts.
- Food Manufacturers:Ingredient security programs drive dedicated on-site buffer storage for milling and processing operations.
Agricultural producers account for the largest installed base. Grain traders are gaining share fastest as export infrastructure expands.
Capacity:
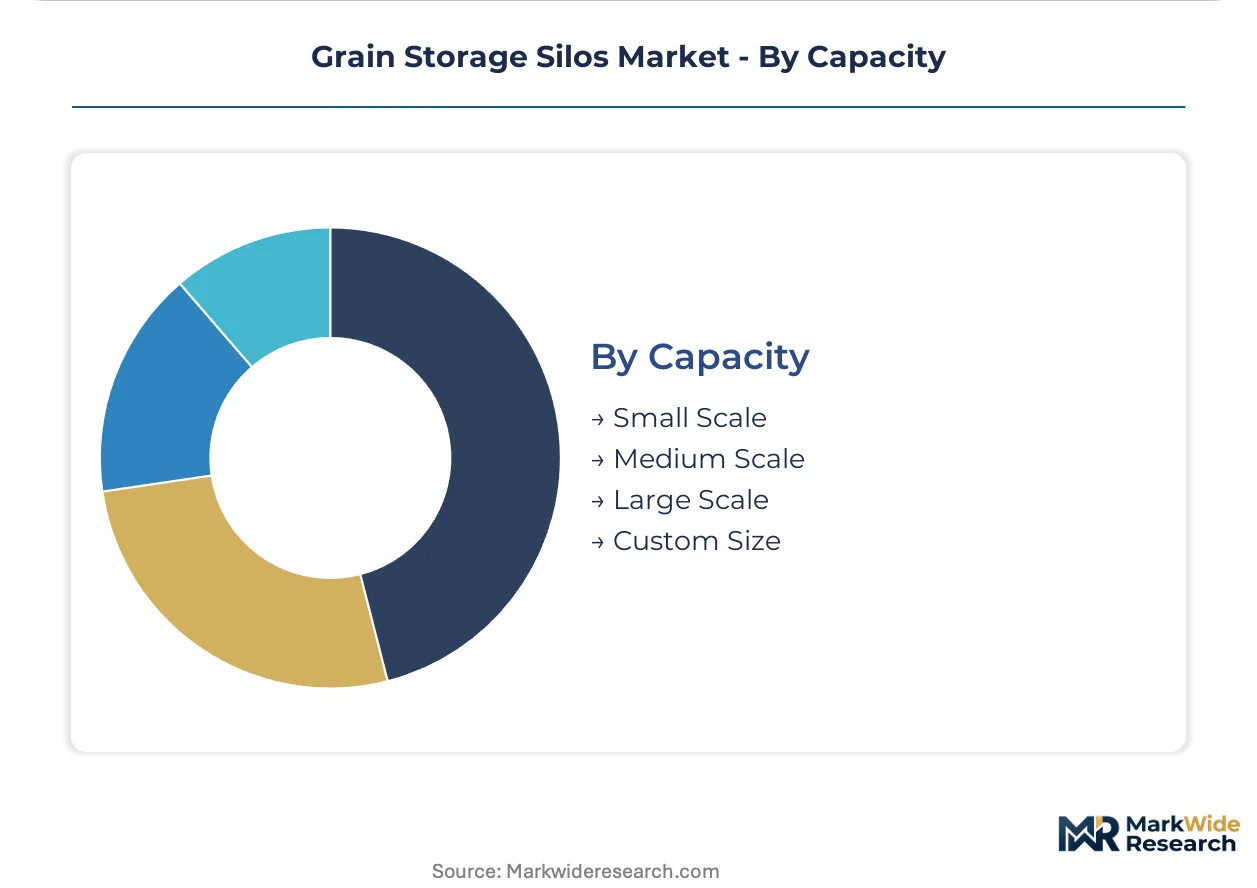
Economies of foundation engineering favor scale clustering, yet fragmented land ownership sustains demand across all size tiers.
- Small Scale:Sub-100 tonne units serve specialty crop producers and organic certification holders with segregated storage requirements.
- Medium Scale:100-1,000 tonne configurations balance foundation cost against operational flexibility for mid-sized farming enterprises.
- Large Scale:Terminal-class installations exceeding 5,000 tonnes concentrate at export hubs and river elevator complexes.
- Custom Size:Site-specific engineering addresses constrained footprints, existing foundation retrofits, and integration with legacy handling equipment.
Medium-scale installations represent the dominant procurement volume. Custom sizing is expanding most quickly as retrofit projects multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ukrainian export operators retrofit steel superstructures onto Soviet-era concrete foundations, while Brazilian terminals along the Santos corridor deploy flat-bottom systems to maximize storage density per hectare. This divergence in infrastructure strategy reflects distinct agricultural export pressures across major grain-producing economies.
United States
Iowa and Illinois farming enterprises expand hopper-bottom capacity to capture seasonal price premiums through extended storage windows. USDA food security programs incentivize on-farm infrastructure investments through cost-share mechanisms. The Corn Belt fabrication cluster around Des Moines and Cedar Rapids supplies corrugated galvanized systems with lead times under eight weeks.
Brazil
Soybean operators near Atlantic ports specify zinc-aluminum-magnesium coated steel to combat accelerated corrosion in high-humidity conditions. ANVISA phytosanitary storage standards drive replacement cycles at export terminals. The Mato Grosso grain corridor concentrates demand for rapid-discharge hopper systems serving volatile commodity marketing windows.
Ukraine
War-damaged storage capacity creates demand for rapid-deployment modular steel systems suited to fragmented farmland ownership. EU Green Deal embodied-emissions disclosure requirements favor suppliers with verified steel sourcing for reconstruction procurement. Odesa port authorities prioritize climate-resilient aeration systems extending storage beyond traditional harvest cycles.
Germany
EU carbon-accounting integration shapes procurement criteria as traders demand verified steel sourcing documentation. REACH compliance for coating chemistries influences specification authority among agronomists at large farming cooperatives. The Bavarian agricultural belt anchors demand for precision aeration systems with automated temperature monitoring.
India
FSSAI food grain storage standards mandate moisture control infrastructure at state procurement centers. The Punjab-Haryana wheat belt drives demand for medium-scale steel silos replacing conventional gunny bag storage. BIS certification requirements for structural steel specifications filter import eligibility for grain handling equipment.
Grain Storage Silos Market Competitive Environment
North American producers anchor the volume tier through integrated manufacturing networks; European specialists hold position through coating technology differentiation and precision engineering services. The vendor base clusters around three strategic archetypes: full-system integrators with captive fabrication, regional steel shops serving direct procurement channels, and concrete engineering firms anchoring permanent terminal installations. Competitive moves concentrate on backward integration into hot-rolled coil supply and geographic expansion of distributed fabrication networks to compress delivery timelines.
Among North American fabricators, Ag Growth International Inc (AGI), Brock Grain Systems, and Sukup Manufacturing Co. exemplify distinct competitive positioning. AGI represents the integrated manufacturing archetype with distributed production networks. Brock Grain Systems occupies a position anchored in specialized engineering services for large-diameter installations. Sukup Manufacturing Co. sits within the mid-capacity segment with regionally distributed fabrication capabilities serving independent farming enterprises.
| Leading Market Players |
|---|
| Brock Grain Systems |
| Sioux Steel Company |
| Ag Growth International Inc (AGI) |
| Hoffmann Inc. |
| CST Industries |
| Sukup Manufacturing Co. |
| Chief Agri/Industrial Group |
| Symaga S.A.U |
| CTB Inc. |
| Others |
Value Chain & Pricing Dynamics
Export-oriented grain traders in Brazil and Ukraine command project-based contract structures that bundle engineering, fabrication, and installation services. Their procurement concentration forces fabricators to absorb hot-rolled steel volatility rather than risk volume loss to regional competitors.
Pricing Analysis
Capacity additions in the US Corn Belt are reshaping price floors for hopper-bottom systems as regional fabricators compete for independent farming enterprise contracts. Pricing stratifies across premium, standard, and economy tiers based on coating specification and aeration integration depth. Cost compression in the mid-capacity segment is intensifying because galvanized coil suppliers lack long-term offtake commitments. Agricultural producers show highest price sensitivity, while grain traders prioritize climate-resilient specifications over capital cost.
Supply Chain Analysis
Direct-to-farm channels handle independent agricultural producer demand, while export terminal projects route through engineering-procurement-construction consortiums. Hot-rolled coil supply draws from US, Brazilian, and Ukrainian mills, with zinc-aluminum-magnesium coating chemistries sourced from European specialty chemical suppliers. Single-source vulnerability concentrates in qualified geotechnical contractors for large-diameter flat-bottom foundations. Distribution runs through regional fabrication networks for hopper-bottom modules and captive in-house production for integrated full-system providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where ANVISA phytosanitary storage standards and EU Green Deal embodied-emissions disclosure requirements create sustained replacement demand and sourcing verification premiums.
For Market Incumbents: Cement market position through backward integration into hot-rolled coil supply and captive zinc-aluminum-magnesium coating capacity. Expand distributed fabrication networks to compress delivery timelines below eight weeks for Corn Belt harvest windows. Defend against regional steel shops by locking multi-year aeration technology service contracts with grain traders. For New Entrants and Emerging Players: Launch via modular hopper-bottom designs targeting Ukrainian reconstruction procurement fragmented across smallholder farmland ownership. Prioritize rapid-deployment steel systems with EU-verified sourcing documentation to capture Green Deal-compliant demand. Penetrate through subscription-based remote monitoring platforms bundled with hardware sales to grain traders. For Investors and Strategic Acquirers: Agricultural equipment manufacturers are the most active acquirer in this space, seeking aeration technology and regional fabrication footprints. Mid-cap specialists with certified coating capabilities and established ANVISA compliance records represent prime targets. Watch for steel price stabilization signals as inflection indicators for margin recovery and valuation expansion across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Supply | Captive hot-rolled sourcing insulates AGI and Brock from galvanized price volatility. |
| EU Green Deal Certification Program | Verified steel sourcing documentation unlocks premium pricing in German reconstruction tenders. |
| Modular Fabrication Network Expansion | Distributed hopper-bottom production cuts delivery timelines for Iowa and Illinois harvest windows. |
| Remote Monitoring Platform Launch | IoT sensor subscriptions create recurring revenue alongside Ukrainian trader hardware procurement. |
| Geotechnical Contractor Partnership | Foundation engineering alliances reduce project timeline risk for Brazilian Santos corridor terminals. |
Study Parameters
Bottom-up agricultural producer modeling reconciled against top-down steel fabrication capacity tracking forms the analytical core. Primary interviews with grain elevator operators, silo fabrication plant managers, agricultural cooperative procurement directors, and geotechnical engineering contractors combined with secondary validation from USDA infrastructure program disclosures, ANVISA regulatory filings, Brazilian customs trade data, and EU Green Deal implementation documents. Triangulation across supply-side capacity assessments and demand-side installation tracking ensures cross-verified volume estimates.
Input-output matrices map hot-rolled coil consumption to installed silo capacity across product type, material specification, end-user category, and regional production cluster dimensions. Growth trajectories derive from segmented demand elasticity modeling and replacement cycle analysis throughout the forecast period. Forecast inputs include phytosanitary compliance deadline schedules, steel price volatility indices, and aeration technology adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained hot-rolled coil price spikes or accelerated concrete substitution at Black Sea export hubs. Projections reflect assumptions regarding ANVISA enforcement continuity and EU carbon-accounting implementation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Cultured Wheat Market
Grains
Wild Rice Market
Grains
Canada Pulses Market
Grains
Triticale Market
Grains
Soybean Market
Grains
North America Wheat Protein Market
Grains
South America Rice Market
Grains
Global Oats Market
Grains
Low Fat Rice Market
Grains
Gluten Free Ancient Grain Market
Grains
South Africa Maize Market
Grains
Lentil Market
Grains
Organic Rice Market
Grains
Oat Bran Market
Grains
Masa Corn Products Market
Grains
Gluten Feed Market