
 Global Precooked Corn Flour Market | 2026-2036
Global Precooked Corn Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Global Precooked Corn Flour Market Intelligence
Advanced extrusion and gelatinization technology is reconfiguring the production process for precooked corn flour, enabling greater control over particle size and hydration properties. Gruma SAB de CV leverages its extensive distribution network to dominate markets in Mexico and the United States. Empresas Polar anchors the market in key South American countries, while Cargill Incorporated utilizes its global grain sourcing capabilities to compete on a broad scale.
Precooked corn flour is a product derived from corn kernels that have been cooked, dried, and ground. The critical manufacturing step involves gelatinizing the starch, which allows the flour to form dough instantly with water. This characteristic makes it essential for preparing traditional foods like arepas, tamales, and instant polenta. The market for gluten-free products represents the fastest-growing application segment. In terms of product type, organic precooked flour commands a price premium, whereas regular precooked variants continue to account for the largest volume share.
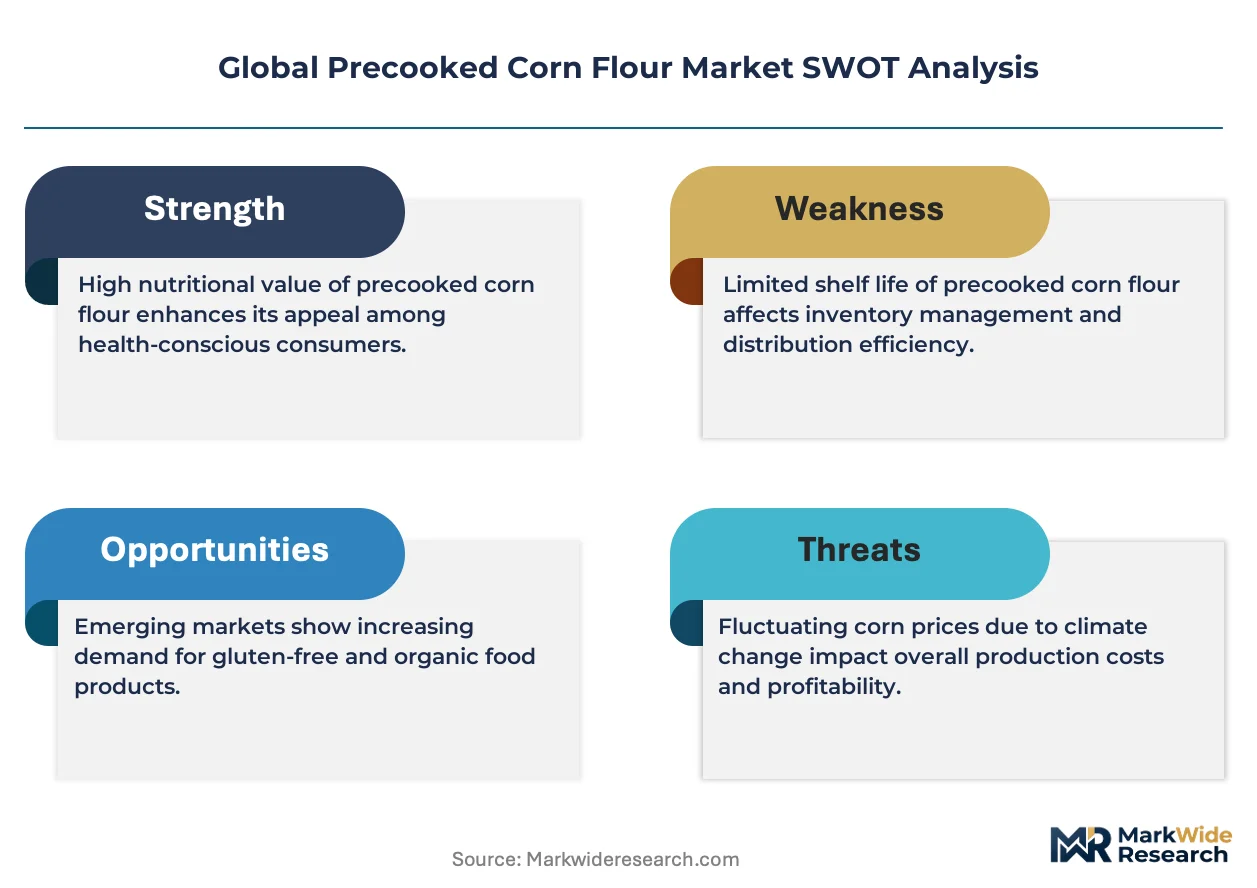
Food safety regulations from bodies like the US Food and Drug Administration (FDA), the European Food Safety Authority (EFSA), and Brazil's ANVISA are central to market access. These agencies enforce strict standards for mycotoxin levels, particularly aflatoxins in corn, and mandate clear allergen labeling for gluten-free claims. Future success depends on adapting product formulations to diverse culinary traditions while securing resilient, non-GMO corn supply chains.
Market Dynamics
The market's central dynamic is the divergence between high-volume, traditional consumption in Latin America and the rise of high-value, health-centric applications in developed economies. This split pressures supply chains to serve both commodity and specialty segments simultaneously.
Growth Catalysts
- Gluten-Free Certification:Formal gluten-free certification standards from bodies like the FDA and corresponding EU regulations build consumer confidence, directly supporting expansion into the health and wellness food sector.
- Clean Label Food Products:Demand from the processed food industry for simple, recognizable ingredients positions precooked corn flour as an ideal binder and texturizer in snacks, soups, and baked goods.
- Process Technology Advancement:Modern extrusion and gelatinization techniques provide precise control over flour properties like water absorption and particle size, enabling its use in novel food formulations.
Market Restraints
- Input Price Volatility:Fluctuation in the price of corn, particularly non-GMO and organic varieties, creates margin pressure for producers of premium and specialty precooked corn flours.
- Climatic and Agricultural Risks:Supply is concentrated in key corn-producing nations like the United States and Brazil, making the market susceptible to disruptions from droughts, floods, or crop diseases.
- Substitution from Other Flours:In the gluten-free baking segment, precooked corn flour faces competition from alternatives like rice, tapioca, and almond flours, which offer different textural and nutritional profiles.
Strategic Opportunities
- Geographic Expansion:Untapped demand exists in Asia-Pacific and Middle Eastern markets, where a growing middle class and rising awareness of celiac disease create openings for gluten-free staples.
- Plant-Based Formulations:The flour's binding and textural properties make it a valuable ingredient in the formulation of plant-based meat and dairy alternatives, a rapidly expanding food category.
- Fortified Product Lines:There is an opportunity to develop flours fortified with vitamins and minerals, targeting public health initiatives and nutritionally-conscious consumers in developing regions.
Industry Challenges
- Mycotoxin Compliance:Consistently meeting the stringent and varied mycotoxin limits for aflatoxins, as mandated by regulators like the EFSA and Brazil's ANVISA, requires rigorous testing and sourcing protocols.
- Supply Chain Segregation:Maintaining the integrity of non-GMO and organic supply chains is a significant operational challenge, demanding strict separation from conventional corn to prevent cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Precooked Corn Flour Market |
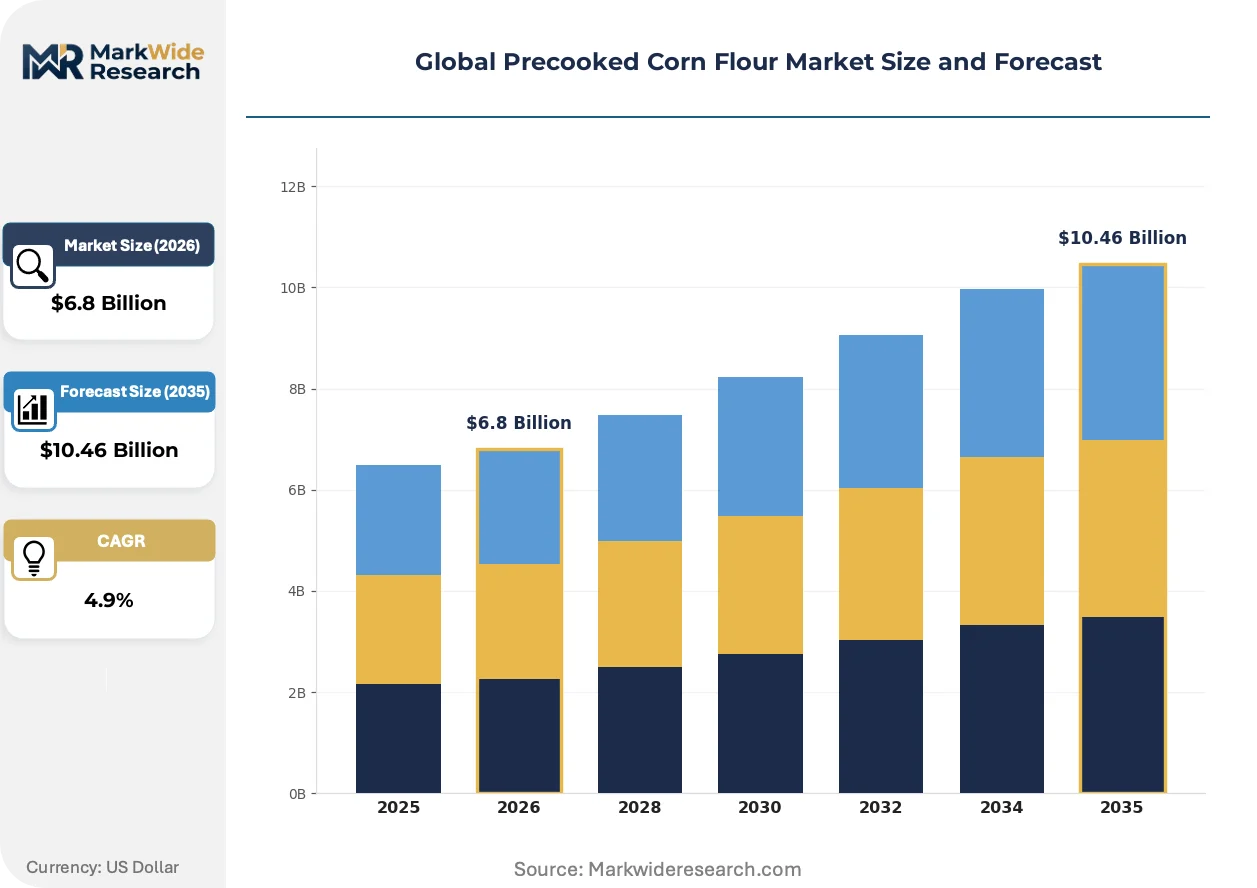
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.46 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Precooked, Instant Precooked, Flavored Precooked, Organic Precooked Application: Baked Goods, Snack Foods, Breakfast Cereals, Thickening Agents, Gluten-Free Products End User: Food Manufacturers, Bakeries, Restaurants, Household Consumers Packaging Type: Plastic Bags, Paper Bags, Pouches, Bulk Packaging |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Gruma SAB de CV, Bunge Limited, Empresas Polar, Harinera del Valle, Goya Foods, Inc., Bob's Red Mill Natural Foods, Molino Peila SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Precooked Corn Flour Market Strategic Shifts & Innovations
Technological refinement and evolving consumer dietary preferences are pushing precooked corn flour into new functional roles. The innovation focus is shifting from process efficiency to creating value-added ingredients for the global health food and convenience sectors.
Functional flour blends that combine precooked corn flour with ingredients like plant proteins or hydrocolloids are gaining traction. Food formulators in the industrial bakery and snack manufacturing sectors are the primary adopters of these sophisticated systems. This development is hybridizing the ingredient's traditional purpose, turning it from a simple carbohydrate base into a multifunctional system for texture modification and nutritional enhancement.
Regulatory frameworks for food transparency, including the FDA's allergen labeling rules and the EU's Food Information to Consumers regulation, are elevating the status of inherently simple ingredients. This forces manufacturers to provide clear, unambiguous product information, benefiting naturally gluten-free items like precooked corn flour. The gluten-free segment is most impacted, as producers leverage clean labels to justify premium positioning and build brand loyalty.
Consumer purchasing habits are evolving from buying large, commodity-style bags to preferring smaller, convenience-oriented packaging. This disrupts the traditional retail channel, which focused on bulk sales in ethnic or specialty stores, in favor of resealable pouches on mainstream supermarket shelves. This shift is most prominent in urban centers across North America and Europe, driven by demand for instant meal components.
Global Precooked Corn Flour Market Segmentation
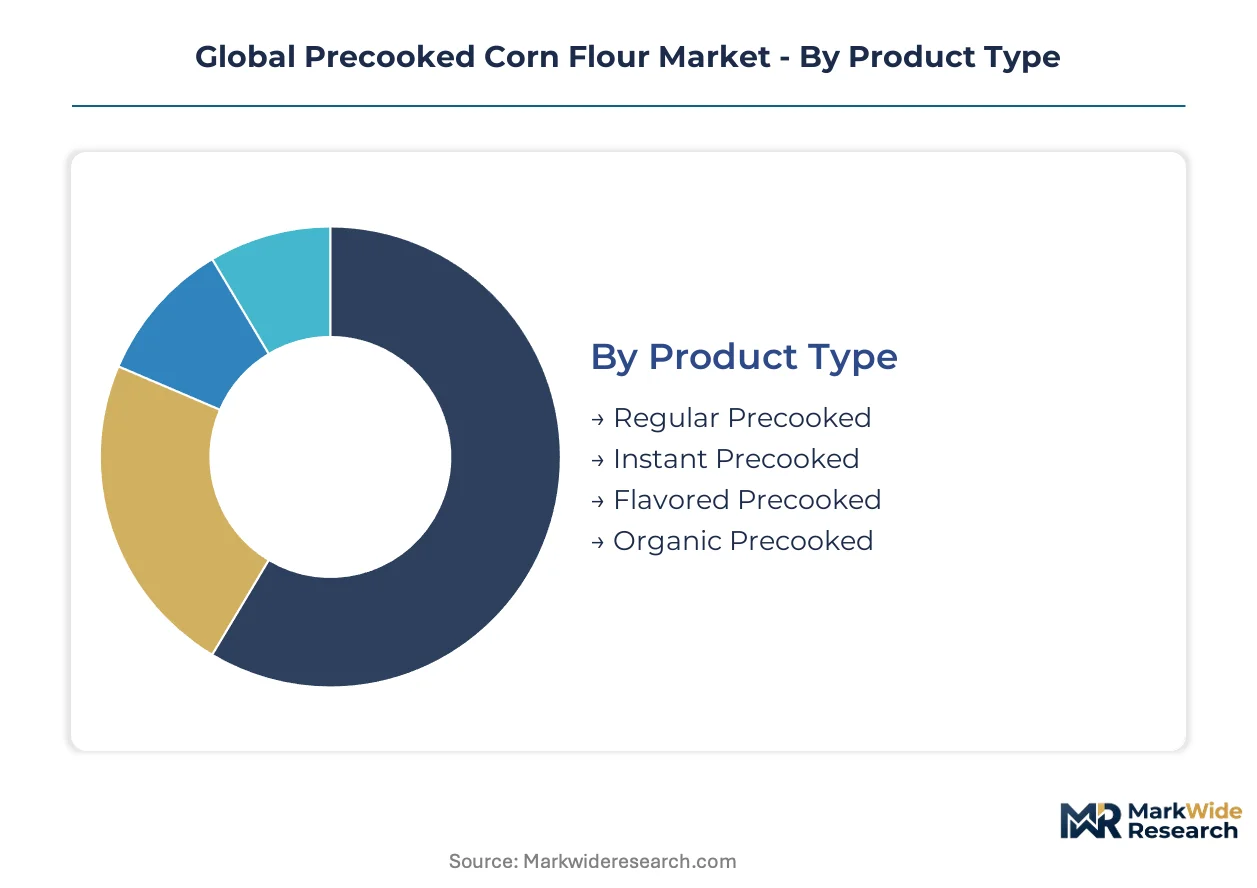
The precooked corn flour market stratifies across diverse product types, applications, end-users, and packaging formats. Understanding these distinct segments allows producers to tailor product development and market penetration strategies effectively. This granular view reveals where value creation and demand concentration truly reside.
Product Type:
The after-sales service intensity for precooked corn flour varies significantly by product type, reflecting the complexity of application support and quality assurance required by industrial buyers versus retail consumers.
- Regular Precooked:This fundamental product type undergoes a standard cooking and drying process, resulting in a versatile flour that forms the backbone of traditional Latin American dishes. Demand concentrates in Mexico and Colombia for daily food preparation, driving high-volume sales.
- Instant Precooked:Designed for rapid hydration, this variant allows for quicker preparation times, appealing to consumers seeking convenience in modern food applications. Its ease of use supports expansion into ready-to-eat meal components.
- Flavored Precooked:These flours incorporate seasonings or other ingredients to offer ready-to-use bases for specific dishes, reducing preparation steps for consumers. They target niche culinary preferences and convenience-oriented markets.
- Organic Precooked:Produced from corn grown without synthetic pesticides or fertilizers, this premium product type commands higher prices due to stringent certification requirements and consumer demand for natural ingredients. Consumer health trends in North America and Europe fuel its expansion.
By volume, Regular Precooked leads. By growth pace, Organic Precooked is ahead.
Application:
The cost tier of precooked corn flour applications ranges from high-volume, commodity-driven uses to niche, premium-priced health-focused segments.
- Baked Goods:Precooked corn flour serves as a key ingredient in various baked goods, including gluten-free breads, tortillas, and cakes, providing structure and texture. Traditional bakeries in Latin America utilize it extensively for authentic product lines.
- Snack Foods:This application leverages the flour's binding and textural properties in extruded snacks, corn chips, and other savory items, offering a gluten-free base. Manufacturers value its consistent performance in high-speed production.
- Breakfast Cereals:The flour is incorporated into various breakfast cereal formulations, including flakes and puffs, contributing to texture and nutritional profiles. It provides a gluten-free alternative in the cereal market.
- Thickening Agents:Due to its gelatinized starch, the flour functions as an effective thickening agent in soups, sauces, and gravies, offering a clean label alternative to modified starches. Food manufacturers use it for viscosity control.
- Gluten-Free Products:This segment represents the fastest-growing application, driven by increasing diagnoses of celiac disease and consumer preferences for gluten-free diets. Precooked corn flour is a core ingredient in a wide array of certified gluten-free foods across Europe and North America.
Gluten-Free Products demonstrate the steepest expansion trajectory. Baked Goods maintain consistent demand across established markets.
End User:
The volume of precooked corn flour consumed differs substantially across end-user categories, with industrial players driving large-scale procurement and households dictating retail trends.
- Food Manufacturers:This segment represents the largest industrial consumer, utilizing precooked corn flour as a bulk ingredient in a wide array of processed foods, including snacks, cereals, and ready meals. They prioritize consistent quality and large-scale supply chains.
- Bakeries:Commercial and artisan bakeries incorporate the flour into specialty breads, tortillas, and other baked goods, particularly for gluten-free or traditional ethnic product lines. These businesses require reliable ingredient sourcing for their daily operations.
- Restaurants:Foodservice establishments, especially those specializing in Latin American cuisine, use precooked corn flour for preparing dishes like arepas and tamales. Supply chain efficiency is critical for fresh preparation.
- Household Consumers:Individual consumers purchase precooked corn flour for home cooking, driven by cultural traditions, health-conscious choices, and the desire for convenient meal preparation. This segment is expanding in urban centers across North America.
Food Manufacturers consume the largest quantities of precooked corn flour. Household Consumers are expanding their usage in convenience-driven meal preparation.
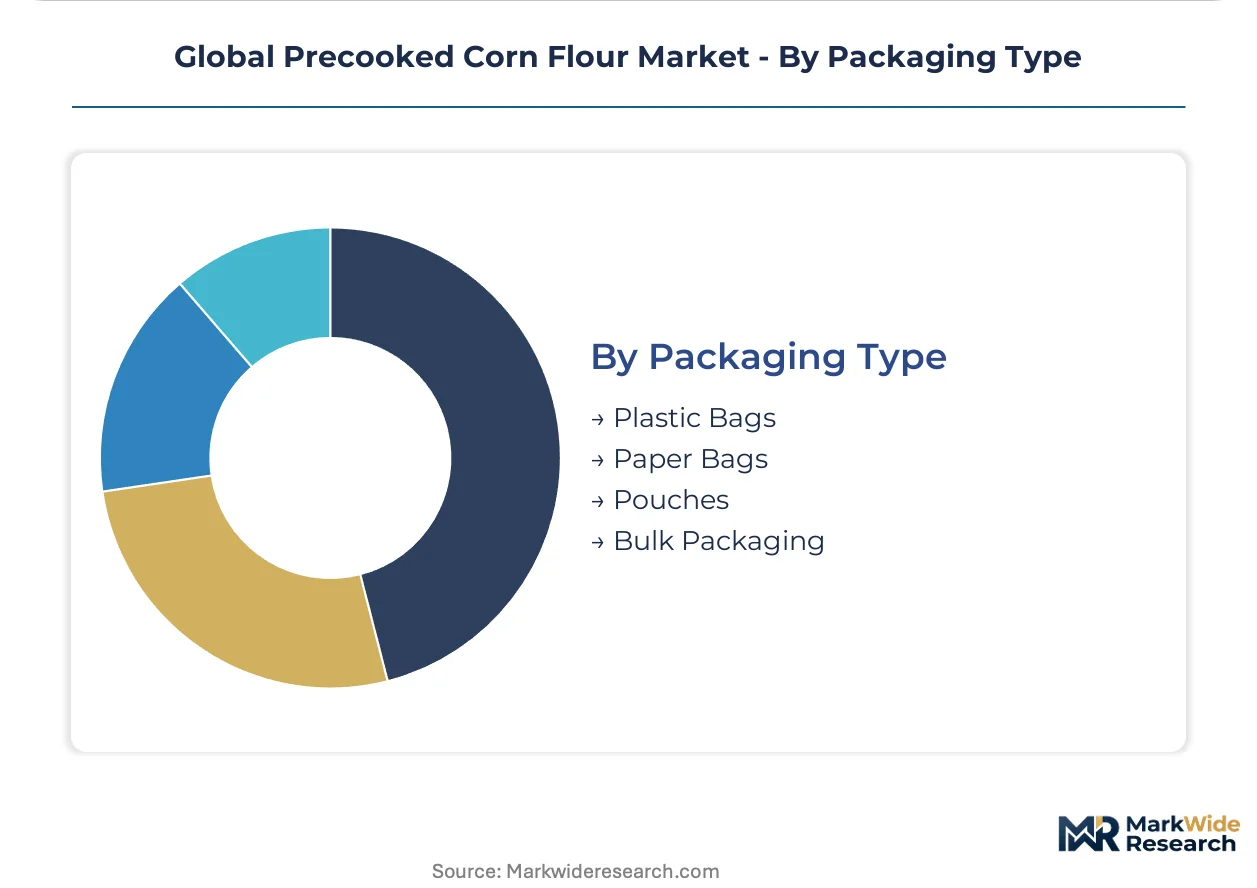
Packaging Type:
Customer type heavily influences the preferred packaging format, with industrial clients favoring bulk solutions and individual consumers opting for smaller, convenient options.
- Plastic Bags:These bags offer excellent moisture barrier properties and durability, making them a common choice for both retail and smaller industrial quantities. They are cost-effective for widespread distribution.
- Paper Bags:Often used for larger retail or smaller commercial volumes, paper bags provide a traditional and sometimes more environmentally perceived packaging solution. They are prevalent in ethnic food stores.
- Pouches:Stand-up and resealable pouches cater to convenience-driven consumers, offering ease of storage and portion control for household use. This format is popular in mainstream supermarkets in Europe.
- Bulk Packaging:Large sacks or containers are designed for industrial food manufacturers and large-scale bakeries, optimizing logistics and reducing packaging waste for high-volume users. This minimizes per-unit costs for large buyers.
Plastic Bags remain a dominant packaging choice for their cost-effectiveness. Pouches are gaining share fastest due to their consumer appeal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global precooked corn flour market sees significant trade flows from major corn-producing nations to regions with high consumption. This dynamic supports both traditional food markets and emerging health-conscious segments. Regulatory frameworks from various national bodies shape product standards and market access across these diverse geographies.
Mexico
Mexican demand for precooked corn flour remains consistently high, driven by its central role in traditional cuisine. The country's food safety regulations, mirroring international standards for mycotoxin control, ensure product quality. Mexico City and Guadalajara serve as key hubs for both traditional food production and the distribution of instant corn flour variants.
United States
United States consumption is expanding, particularly in the gluten-free and convenience food sectors. The US Food and Drug Administration (FDA) enforces strict allergen labeling and mycotoxin limits, building consumer trust. Urban centers like New York and Los Angeles exhibit strong demand for both ethnic food ingredients and health-oriented precooked corn flour products.
Brazil
Brazilian producers leverage abundant corn supplies to serve both domestic and export markets for precooked corn flour. ANVISA, Brazil's health surveillance agency, sets rigorous standards for food safety and quality, including aflatoxin levels. The São Paulo region leads in food manufacturing, integrating precooked corn flour into various processed food applications.
Germany
German consumer preferences for clean label and organic ingredients drive demand for premium precooked corn flour variants. European Food Safety Authority (EFSA) guidelines on food additives and contaminants directly influence product formulation and sourcing. Food processing clusters in Bavaria and North Rhine-Westphalia are adopting advanced extrusion technologies for new food formulations.
Colombia
Colombian households and foodservice establishments represent a substantial market for regular precooked corn flour, essential for daily meals like arepas. National food quality and safety standards regulate the ingredient's production and distribution. Bogotá and Medellín are major centers for both traditional flour distribution and the development of new convenience-oriented corn flour products.
Global Precooked Corn Flour Market Key Industry Players
Channel-controlling players compete with product-specialist players across the precooked corn flour market. The industry structure features a mix of globally integrated grain processors and regional manufacturers focused on traditional food markets. Strategic archetypes include large-scale commodity suppliers, ethnic food specialists, and premium organic ingredient providers. Companies primarily engage in geographic expansion and product portfolio diversification to capture market share.
At the scale-driven end, Cargill Incorporated exemplifies a major global agribusiness leveraging extensive grain sourcing capabilities. Gruma SAB de CV anchors the market in key North American and Latin American regions, reflecting a strong focus on traditional and convenience food segments. Empresas Polar, a major South American food company, occupies a significant position in its home markets by supplying staple food ingredients.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Gruma SAB de CV |
| Bunge Limited |
| Empresas Polar |
| Harinera del Valle |
| Goya Foods, Inc. |
| Bob's Red Mill Natural Foods |
| Molino Peila SpA |
| Others |
Cost & Logistics Intelligence
Regional undercapacity in key corn-producing nations like the United States and Brazil drives supplier behavior and pricing posture for precooked corn flour. This concentration creates susceptibility to agricultural disruptions, directly influencing market stability.
Pricing Analysis
Cost-plus contracts, often indexed to global corn futures, define pricing for high-volume precooked corn flour transactions. Price differentiation stems from stringent certification levels, particularly for organic and gluten-free variants, and the volume scale of procurement. Margin pressure intensifies due to input price volatility for non-GMO and organic corn varieties. Industrial food manufacturers demonstrate high price sensitivity, whereas health-conscious household consumers exhibit less sensitivity for premium certified products.
Supply Chain Analysis
Stringent food safety regulations, particularly mycotoxin limits enforced by bodies like the FDA and EFSA, effectively limit the flow of non-compliant precooked corn flour. Geographic supply concentrates in the United States, Brazil, and Mexico, primarily drawing from corn kernels as the main input. The supply chain faces significant structural risk from climatic and agricultural disruptions, such as droughts or crop diseases. Distribution runs through both large industrial food manufacturers and diverse retail channels for household consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The precooked corn flour market is experiencing a cyclical recovery, driven by renewed consumer spending on convenience foods and health-centric products. This uplift supports expansion across both traditional and specialty segments.
For Market Incumbents: Pre-empt emerging competition from alternative flours by diversifying product lines into functional blends and investing in advanced extrusion technologies. This mitigates the threat of substitution from rice or almond flours. Deepen vertical integration into non-GMO corn sourcing to secure resilient supply chains. Strengthen brand loyalty through robust gluten-free certification investment, justifying premium positioning.
For New Entrants and Emerging Players: Underpenetration in Asia-Pacific and Middle Eastern markets presents a significant entry point for new precooked corn flour players. Target the rapidly expanding plant-based formulations segment by offering specialized binding and textural properties. Focus on developing fortified product lines for nutritionally-conscious consumers in developing regions. A direct-to-consumer online sales strategy, emphasizing gluten-free benefits, offers a penetrable go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with strong supply chain control and established distribution networks in high-growth segments. The market demonstrates long-term viability, anchored by sustained demand for gluten-free and convenience foods. Target ethnic food specialists or premium organic ingredient providers for strategic acquisitions. The signal to watch is the accelerated adoption of precooked corn flour in plant-based meat alternatives, indicating broader industrial acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion into Asia-Pacific | Opens new demand centers for gluten-free staples among a growing middle class. |
| Investment in Advanced Extrusion Technology | Enhances product quality and consistency, supporting novel food formulations for industrial buyers. |
| Diversification into Functional Flour Blends | Creates value-added ingredients for industrial bakery and snack manufacturing sectors. |
| Fortified Product Line Development | Addresses public health initiatives and nutritionally-conscious consumers in developing regions. |
| Securing Non-GMO Corn Supply Chains | Ensures compliance with strict food safety regulations and consumer demand for natural ingredients. |
Research Approach
A spread of perspectives from food manufacturers, ingredient procurement managers, regulatory affairs specialists, and retail buyers converged on the working assumptions for market dynamics. This involved extensive primary interviews combined with rigorous secondary validation. Data sources included FDA filings, EFSA reports, ANVISA guidelines, and global customs data. This comprehensive approach facilitated bottom-up and top-down triangulation for robust market sizing.
The demand-supply balance for precooked corn flour was meticulously analyzed across the analysis window, considering consumption patterns against production capacities. The analytical framework modeled segmentation dimensions including product type, application, end-user, packaging format, and regional regulatory frameworks. Compound annual growth rates were derived from historical trend analysis and projected growth catalysts. Key forecast inputs included global corn harvest yields and gluten-free product innovation rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large-scale commodity suppliers or premium organic ingredient providers would shift outcomes. Forecasts reflect underlying assumptions about market stability and regulatory continuity. Material shifts in global corn supply or trade policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Asia Pacific Maize Market
Grains
Corn Gluten Feed Market
Grains
Uganda Grains Market
Grains
GMO Corn Market
Grains
Wheat Protein Market
Grains
Canada Pulses Market
Grains
Organic Rice Flour Market
Grains
Oat Flour Market
Grains
Global Wheat Market
Grains
Corn Silage Market
Grains
Asia-Pacific Guar Market
Grains
Basmati Rice Market
Grains
Africa Maize Market
Grains
Rolled Oats Market
Grains
Grain Silos and Storage System Market
Grains
Organic Rice Market