
 Organic Wheat Flour Market | 2026-2036
Organic Wheat Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Wheat Flour Market Analysis
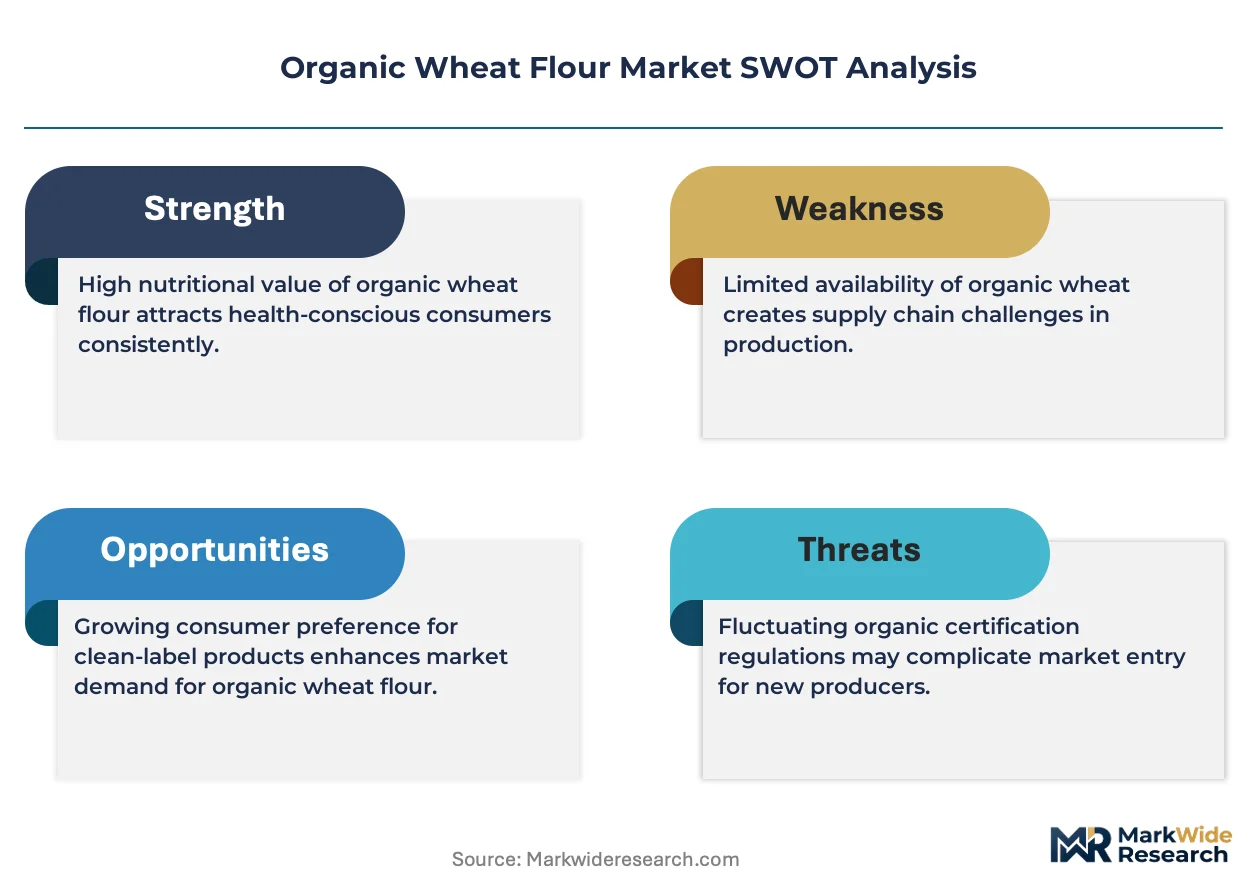
North American organic grain milling capacity is hardening as regional wheat belts expand certified acreage. Ardent Mills leverages its multi-facility network to sustain bulk supply contracts with commercial bakeries across the United States. Bob's Red Mill Natural Foods differentiates through stone-ground heritage varietals and direct-to-consumer channel control. Heartland Mill Inc. anchors its position through backward integration into certified organic wheat farming in Kansas and Nebraska.
Organic wheat flour consists of milled endosperm, bran, and germ from Triticum aestivum cultivated without synthetic pesticides or fertilizers, with protein content typically ranging from 9% to 14% depending on varietal and extraction rate. Its primary commercial purpose centers on clean-label baked goods, pasta, and specialty foods where certification substantiates premium positioning. Whole wheat flour commands the deepest margin pool as consumers associate visible bran content with nutritional density and authenticity. Bread flour competes most intensely among artisan producers seeking high-gluten performance without chemical additives. Online retail represents the fastest-expanding distribution channel as subscription models and direct mill-to-kitchen logistics reduce intermediary costs.
The USDA National Organic Program governs certification and labeling standards for domestic production, while the EU Organic Regulation defines equivalent requirements for imported flour entering European markets. FDA food safety mandates and state-level organic integrity programs create layered compliance obligations that shape facility investment and traceability systems. Stakeholders must monitor evolving equivalency agreements between major certifying jurisdictions, as diverging standards threaten to fragment supply chains and complicate cross-border sourcing strategies.
Market Dynamics
Mill-to-retailer traceability mandates and the EU Green Deal's tightening input standards are forcing organic wheat flour producers to reconfigure certification infrastructure and sourcing networks simultaneously.
Growth Catalysts
- EU Green Deal agricultural standards:Member states are accelerating conversion of conventional wheat acreage to certified organic cultivation, expanding raw material availability for milling operations.
- Clean-label packaged goods manufacturing:Bread and pasta producers are reformulating product lines to eliminate synthetic additives, creating procurement pull for certified organic flour with verified supply chains.
- Heritage wheat varietal revival:Artisan bakers are specifying ancient grains such as Red Fife and Turkey Red, diversifying premium product portfolios beyond commodity hard red wheat.
Market Restraints
- Organic nitrogen input cost volatility:Reliance on manure-based and legume-rotation fertility systems exposes farmers to fertilizer price swings that conventional growers avoid through synthetic alternatives.
- USDA National Organic Program compliance timeline:Three-year transition periods for conventional-to-organic acreage conversion create supply inelasticity that cannot respond quickly to demand spikes.
- Gluten-free and alternative grain substitution:Almond flour, cassava flour, and chickpea flour are capturing specialty baking segments that previously defaulted to organic wheat.
Strategic Opportunities
- Subscription-based direct-to-consumer channels:Regional mills are bypassing distributor markups through monthly flour delivery services targeting home bakers.
- EU F-Gas Regulation cold storage incentives:Low-global-warming-potential refrigeration retrofits qualify for green financing, reducing post-milling spoilage rates in organic whole wheat flour.
- Pasta and noodle manufacturing pivot:Durum wheat flour processors are expanding into organic soft wheat blends for fresh pasta applications previously dominated by conventional suppliers.
Industry Challenges
- Certified organic grain handling infrastructure:Segregated storage, milling, and transport systems require capital outlays that smaller regional mills struggle to finance without cooperative pooling arrangements.
- Multi-jurisdiction equivalency documentation:USDA-EU organic trade agreements require parallel record-keeping systems that complicate export documentation for cross-Atlantic flour shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Wheat Flour Market |
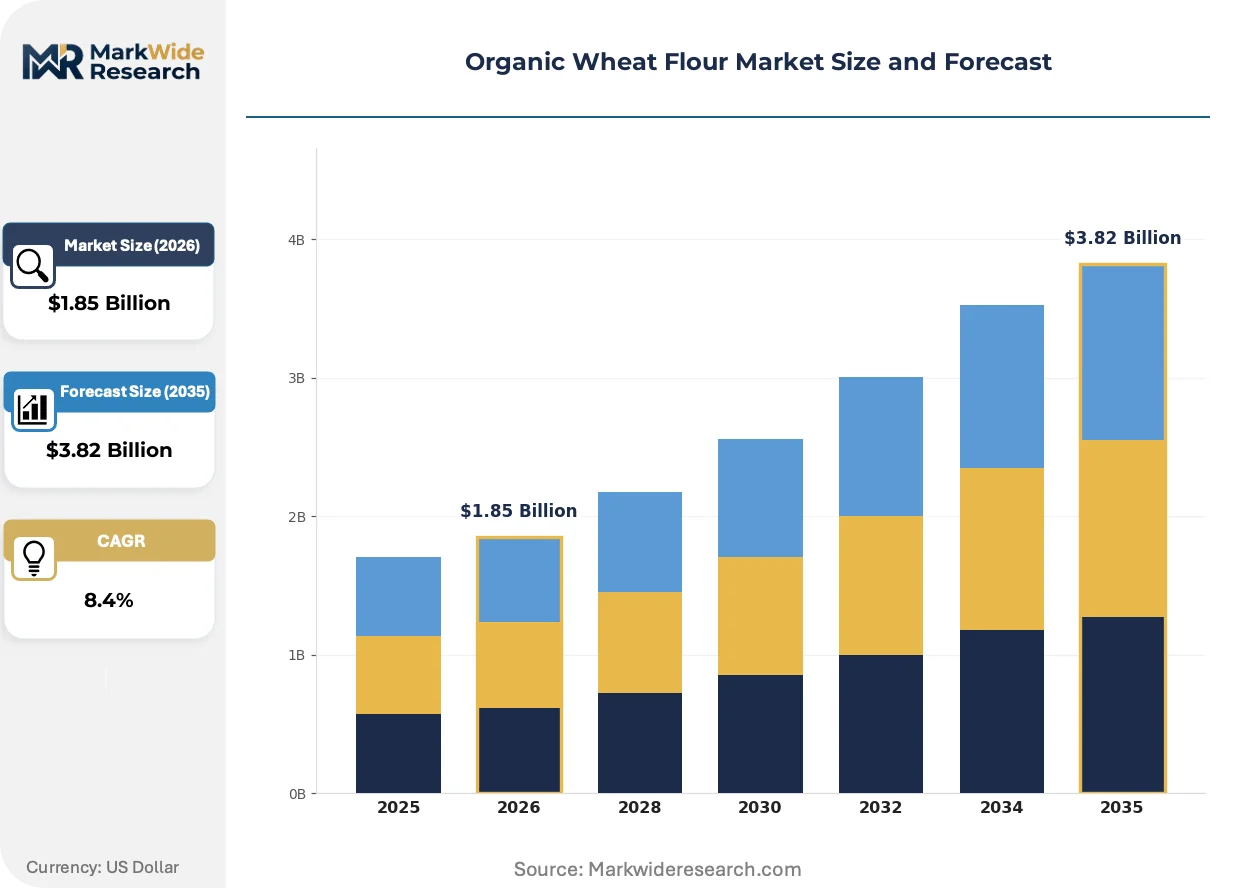
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Wheat, All-Purpose, Bread Flour, Pastry Flour Grade: Premium, Standard, Organic Certified, Conventional Application: Baking, Cooking, Thickeners, Specialty Foods Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Farmers' Markets |
| Companies Covered | Heartland Mill Inc., Bob’s Red Mill Natural Foods, Ardent Mills, Lindley Mills Inc., Daybreak Mill, Sunrise Flour Mill, Fairhaven Organic Flour Mill, Yorkshire Organic Millers Limited, The Hain Celestial Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Wheat Flour Market Emerging Trajectories
Near-infrared spectroscopy and blockchain lot-tracking are converging to transform how organic wheat flour quality and provenance are verified from field to finished product.
Optical sorting technology is absorbing contamination detection tasks previously handled through manual inspection and third-party laboratory testing. Large-scale organic millers in Germany and France are deploying hyperspectral imaging systems to identify mycotoxin indicators and foreign matter in real-time during intake. This compression of quality assurance timelines is enabling just-in-time milling schedules that reduce working capital requirements for high-volume bakeries.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigerated transport and storage facilities serving organic flour distribution networks. Cold chain operators across the Netherlands, Italy, and Spain are retrofitting warehouse climate systems with natural refrigerant alternatives to maintain compliance deadlines. Organic whole wheat flour, with its higher oil content in retained germ, faces elevated spoilage risk from temperature excursions, making this regulatory transition particularly consequential for margin preservation.
Home baking resurgence following pandemic-era habit formation has compressed the traditional distributor-retail channel for specialty flour. Direct mill websites and specialty grocery platforms are capturing volume previously routed through foodservice distributors and bakery supply houses. This channel disintermediation is most pronounced in urban clusters across the United Kingdom and Germany, where same-day delivery logistics have achieved sufficient density to support perishable flour shipments.
Organic Wheat Flour Market Segmentation
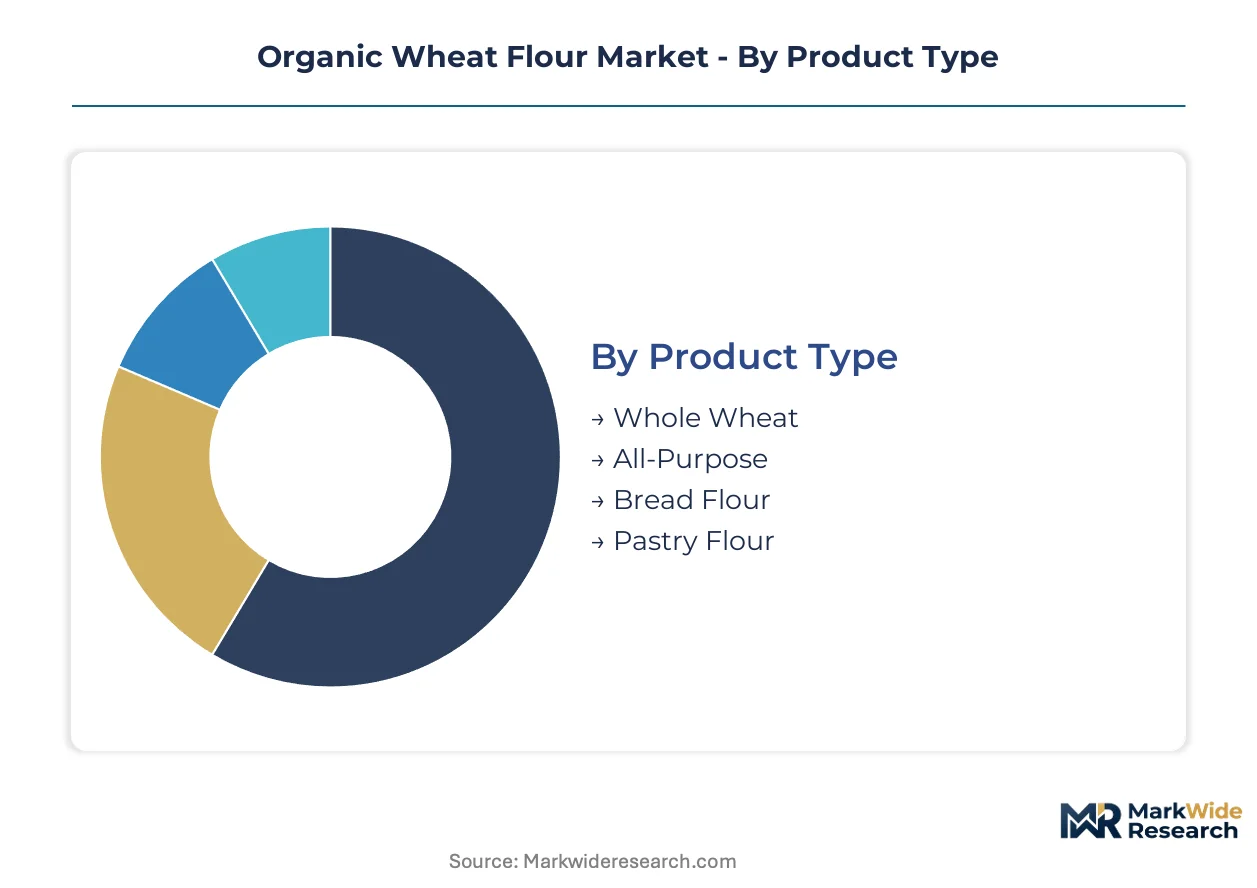
Organic wheat flour procurement patterns diverge sharply across product specifications and channel structures. Milling cooperatives and commercial bakeries prioritize different flour grades based on end-use certification requirements and margin sensitivity.
Product Type:
Supply concentration in stone-ground heritage milling favors whole wheat and bread flour categories, where German and French cooperatives have achieved processing scale.
- Whole Wheat:Contains milled endosperm, bran, and germ with protein content ranging from 11% to 14%. Artisan bakeries in Germany specify this grade for dense sourdough loaves where visible bran content signals authenticity to consumers.
- Bread Flour:High-gluten hard wheat varieties with protein levels exceeding 12% enable artisan producers to achieve dough elasticity without chemical conditioners. Clean-label packaged goods manufacturers in the United States source this grade for commercial loaf production.
- All-Purpose:Mid-range protein flour (9% to 11%) serves home bakers and small-scale foodservice operations seeking versatility across multiple applications.
- Pastry Flour:Soft wheat milling with lower protein (8% to 9%) targets laminated dough applications where gluten development must remain restrained.
Today's leader: Whole Wheat. Tomorrow's challenger: Bread Flour.
Grade:
Cost tier stratification separates certified organic premiums from conventional positioning, with EU Green Deal compliance costs widening the gap.
- Premium:Heritage varietals such as Red Fife and Turkey Red command price multiples through stone-ground processing and limited-batch availability. Specialty retailers in the United Kingdom stock these grades for discerning home bakers.
- Organic Certified:USDA National Organic Program or EU Organic Regulation compliance underpins supply contracts with commercial bakeries. Three-year transition timelines for conventional acreage conversion constrain raw material availability.
- Standard:Non-certified milling meets price-sensitive foodservice demand where organic labeling carries no consumer-facing value.
- Conventional:Synthetic input-dependent cultivation serves commodity baking applications with minimal margin contribution.
Certified grades dominate procurement volume. Premium heritage tiers capture margin expansion.
Application:
Volume concentration in industrial baking contrasts with specialty food growth trajectories.
- Baking:Commercial bread, pastry, and cracker production absorbs the majority of organic hard wheat flour volume. Ardent Mills maintains bulk supply contracts with United States bakery chains.
- Specialty Foods:Pasta and noodle manufacturing pivots toward organic soft wheat blends. Italian fresh pasta producers source these grades for retail distribution.
- Cooking:Home kitchen use for roux, coating, and sauce preparation represents steady but lower-margin demand.
- Thickeners:Food processing applications for soups and gravies prioritize cost efficiency over certification premiums.
Baking anchors current procurement. Specialty foods demonstrate the steepest expansion trajectory.
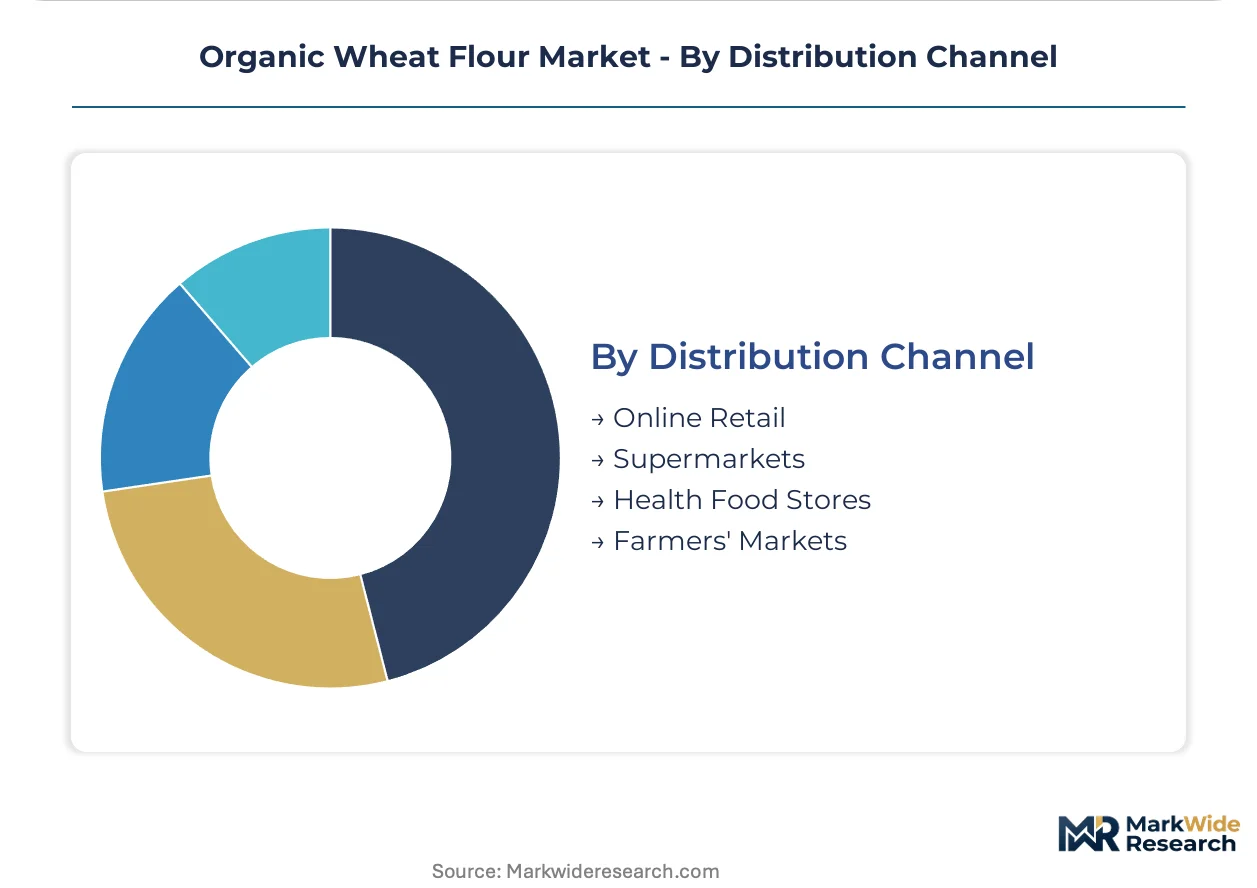
Distribution Channel:
Customer type fragmentation separates subscription-driven home bakers from institutional procurement.
- Online Retail:Direct mill-to-kitchen subscription models eliminate distributor markups. Regional mills in Germany and the United Kingdom achieve same-day delivery density in urban clusters.
- Supermarkets:Mass retail placement requires organic certification documentation and traceability systems that smaller mills struggle to finance without cooperative pooling.
- Health Food Stores:Independent retailers stock heritage varietals and local mill brands where consumer education justifies price premiums.
- Farmers' Markets:Direct producer sales capture margin but limit geographic reach to regional wheat belt proximity.
Supermarkets maintain volume leadership. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping organic wheat flour production geography. The EU Green Deal's input standards impose steeper compliance costs than USDA National Organic Program requirements, pushing some milling capacity toward North American wheat belts where transition timelines and certification overhead remain more manageable.
United States
Heartland Mill Inc. anchors procurement networks across Kansas and Nebraska through backward integration into certified organic wheat farming. The USDA National Organic Program governs domestic certification, though three-year transition periods constrain supply elasticity. Ardent Mills leverages multi-facility networks across the Great Plains to sustain bulk contracts with commercial bakeries.
Germany
Regional milling cooperatives have achieved substantial scale in organic wheat flour processing, particularly for whole wheat and bread flour grades. The EU Green Deal and F-Gas Regulation tighten input standards and cold storage requirements simultaneously. Bavaria and Baden-Württemberg host dense clusters of stone-ground heritage mills serving artisan bakery demand.
United Kingdom
Yorkshire Organic Millers Limited exemplifies regional supply chain concentration in northern England. The country's organic regulator enforces EU-equivalent standards post-Brexit through retained regulations. London and Southeast urban clusters support same-day delivery density for direct-to-consumer subscription models.
France
Italian fresh pasta producers source organic soft wheat blends from French millers expanding beyond traditional durum processing. EFSA guidelines on mycotoxin thresholds shape intake quality protocols. The Île-de-France region concentrates distribution infrastructure for cross-border shipments into Benelux markets.
Canada
Prairie Provinces wheat belts are expanding certified organic acreage to supply North American milling demand. Health Canada and PMRA coordinate organic integrity oversight with USDA equivalency agreements. Alberta and Saskatchewan host grain handling infrastructure that supports segregated organic supply chains.
Organic Wheat Flour Market Vendor Landscape
North American producers anchor the scale-driven tier; European specialists hold premium heritage positioning. The vendor base separates into multi-facility millers with bulk supply contracts, regional cooperatives with backward-integrated farming, and direct-to-consumer brands controlling stone-ground processing. Three archetypes dominate: scale-optimized bulk suppliers, heritage-variety specialists, and subscription-channel innovators. Competitive moves concentrate on M&A for geographic coverage and capacity expansion for certified organic grain handling infrastructure.
Within the heritage-specialist tier, Bob's Red Mill Natural Foods and Yorkshire Organic Millers Limited exemplify stone-ground differentiation through controlled channel access. At the scale-optimized end, Ardent Mills occupies a position defined by multi-facility network breadth. Heartland Mill Inc. represents backward-integrated archetypes with captive organic wheat supply.
| Leading Market Players |
|---|
| Heartland Mill Inc. |
| Bob's Red Mill Natural Foods |
| Ardent Mills |
| Lindley Mills Inc. |
| Daybreak Mill |
| Sunrise Flour Mill |
| Fairhaven Organic Flour Mill |
| Yorkshire Organic Millers Limited |
| The Hain Celestial Group Inc. |
| Others |
Supply Flow & Price Mechanics
Organic nitrogen input cost volatility cascades from Kansas and Nebraska wheat belts through stone-ground heritage tiers to supermarket shelf prices, compressing margins at every handling layer while EU Green Deal compliance costs widen certified-conventional spreads.
Pricing Analysis
Distributor margin compression reshapes how regional mills reach commercial bakeries. Three-tier pricing structure across premium heritage, certified organic, and conventional grades separates stone-ground Red Fife batches from commodity hard red wheat. Cost compression in certified organic tiers is intensifying because manure-based fertility systems expose farmers to fertilizer price swings that synthetic-dependent conventional growers avoid. Commercial bakeries sourcing bulk bread flour contracts demonstrate highest price sensitivity, while artisan producers specifying heritage varietals absorb premium multiples with minimal volume negotiation.
Supply Chain Analysis
Certified organic wheat supply rests on segregated handling infrastructure across Germany, France, and the United States. Raw material flows draw from Kansas-Nebraska wheat belts, Bavarian milling cooperatives, and Prairie Provinces expansion zones. Single-source vulnerability concentrates in heritage varietal seed stock where Turkey Red and Red Fife germplasm lacks diversified breeding programs. Distribution runs through multi-facility miller networks for bulk bakery contracts, direct-to-consumer subscription channels for urban home bakers, and cooperative pooling arrangements for regional health food stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in organic wheat flour hinges on backward integration into certified acreage and subscription channel capture that eliminates distributor markups.
For Market Incumbents: Lock in heritage varietal seed stock through exclusive germplasm agreements with university breeding programs. Expand certified organic grain handling infrastructure in Kansas and Nebraska to preempt supply inelasticity during demand spikes. Gluten-free almond and chickpea flour substitution threatens specialty baking segments previously defaulting to organic wheat. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and France opens a window for cold storage retrofit specialists serving organic whole wheat flour distribution. Target fresh pasta manufacturing pivots in Italy where soft wheat blend demand outpaces traditional durum supply. Launch direct mill-to-kitchen subscription models in London and Southeast England urban clusters where same-day delivery density already supports perishable shipments. For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative pooling arrangements struggle to finance segregated storage and transport systems independently. Five-to-ten year viability favors regional mills with backward-integrated farming and stone-ground processing equipment. Watch EU-USDA equivalency agreement negotiations as inflection indicator for cross-Atlantic flour shipment documentation burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Acreage | Heartland Mill Inc. anchors procurement networks through captive organic wheat supply in Kansas and Nebraska. |
| Subscription Channel Launch | German regional mills bypass distributor markups through monthly flour delivery services targeting home bakers. |
| Heritage Varietal Revival | Artisan bakers specifying Red Fife and Turkey Red diversify premium portfolios beyond commodity hard red wheat. |
| Cold Storage Retrofit | EU F-Gas Regulation compliance deadlines drive natural refrigerant adoption in Netherlands and Spain warehouse networks. |
| Blockchain Lot-Tracking Deployment | Near-infrared spectroscopy convergence with distributed ledger systems transforms provenance verification from field to finished product. |
Methodological Framework
Bottom-up baking and specialty foods modeling reconciled against top-down milling capacity and certified acreage tracking forms the analytical core. Primary interviews with milling cooperative managers, artisan bakery procurement leads, supermarket category buyers, and organic certification auditors combined with secondary validation from USDA National Organic Program filings, EU Organic Regulation compliance databases, and customs trade records. Triangulation across stakeholder perspectives and documentary sources ensures segment-level accuracy.
Historical trendline analysis of certified organic wheat acreage conversion, stone-ground processing capacity expansion, and direct-to-consumer channel penetration informs projection modeling across product type, grade, application, and distribution channel dimensions. CAGRs derive from segmented demand elasticity assessments and supply-side constraint analysis. Forecast inputs incorporate EU Green Deal implementation timelines and F-Gas Regulation phase-down schedules for refrigerated transport infrastructure.
Revisions become necessary when equivalency agreement negotiations between USDA and EU authorities diverge, when heritage varietal seed stock concentration triggers supply disruption, or when alternative grain substitution accelerates beyond current trajectory assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
United States Gluten-Free Oats Market
Grains
Europe Wheat Market
Grains
Dried Spent Grain Market
Grains
Torrified Wheat Market
Grains
South Africa Maize Market
Grains
Millets Market
Grains
Grain Bins Market
Grains
Asia-Pacific Guar Market
Grains
Global Cassava Flour Market
Grains
Grain Silos and Storage System Market
Grains
United States Maize Market
Grains
Mesquite Flour Market
Grains
00 Flour Market
Grains
Global Grain Mill Products Market
Grains
Asia Pacific Maize Market
Grains
Corn Gluten Feed Market