
 Corn Market | 2026-2036
Corn Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Market Analytics
North American seed production is shifting toward drought-tolerant trait stacks as climate volatility intensifies. Cargill leverages its river-terminal network to anchor origination volumes across the Mississippi Basin. Archer Daniels Midland sustains crushing margins through backward integration into oil refining and distillers grains. Corteva competes on germplasm innovation, while Syngenta Group specializes in crop protection bundling with seed platforms.
Corn is a C4 cereal grain with kernel composition of approximately 72% starch, 10% protein, and 4% oil, processed through wet or dry milling for food, feed, and industrial applications. Field corn dominates commercial volume due to its use in animal feed and ethanol production, where margin pools concentrate with processors achieving scale in fractionation. Sweet corn occupies premium retail and foodservice channels with higher per-unit pricing but smaller tonnage. Biofuel demand from the end use industry segment is expanding fastest as renewable fuel standards tighten across multiple jurisdictions.
The EPA administers Renewable Fuel Standard blending obligations that mandate minimum corn ethanol volumes in US transportation fuel. The USDA oversees crop insurance, export promotion, and biotechnology deregulation that shapes farmer planting decisions and seed market access. Stakeholders must monitor how the IRA biofuel tax credits and state-level low-carbon fuel standards redirect investment toward carbon capture and climate-smart agriculture verification systems.
Market Dynamics
Ethanol blending mandates across multiple jurisdictions are structurally redirecting corn origination toward fuel processors, compressing traditional feed and food channels while tightening basis relationships at river terminals.
Growth Catalysts
- Low-carbon fuel standards:State-level mandates in California and Oregon are creating premium pricing tiers for ethanol with verified carbon intensity scores. This pulls additional acreage into corn-for-fuel rotations.
- CRISPR trait commercialization:Drought-tolerant germplasm with stacked herbicide resistance is expanding plantable geography into marginal rainfall zones previously unsuitable for commercial production.
- Brazilian biofuel expansion:Government mandates displacing sugarcane feedstock are accelerating corn-based ethanol refinery construction in Mato Grosso and Goiás.
Market Restraints
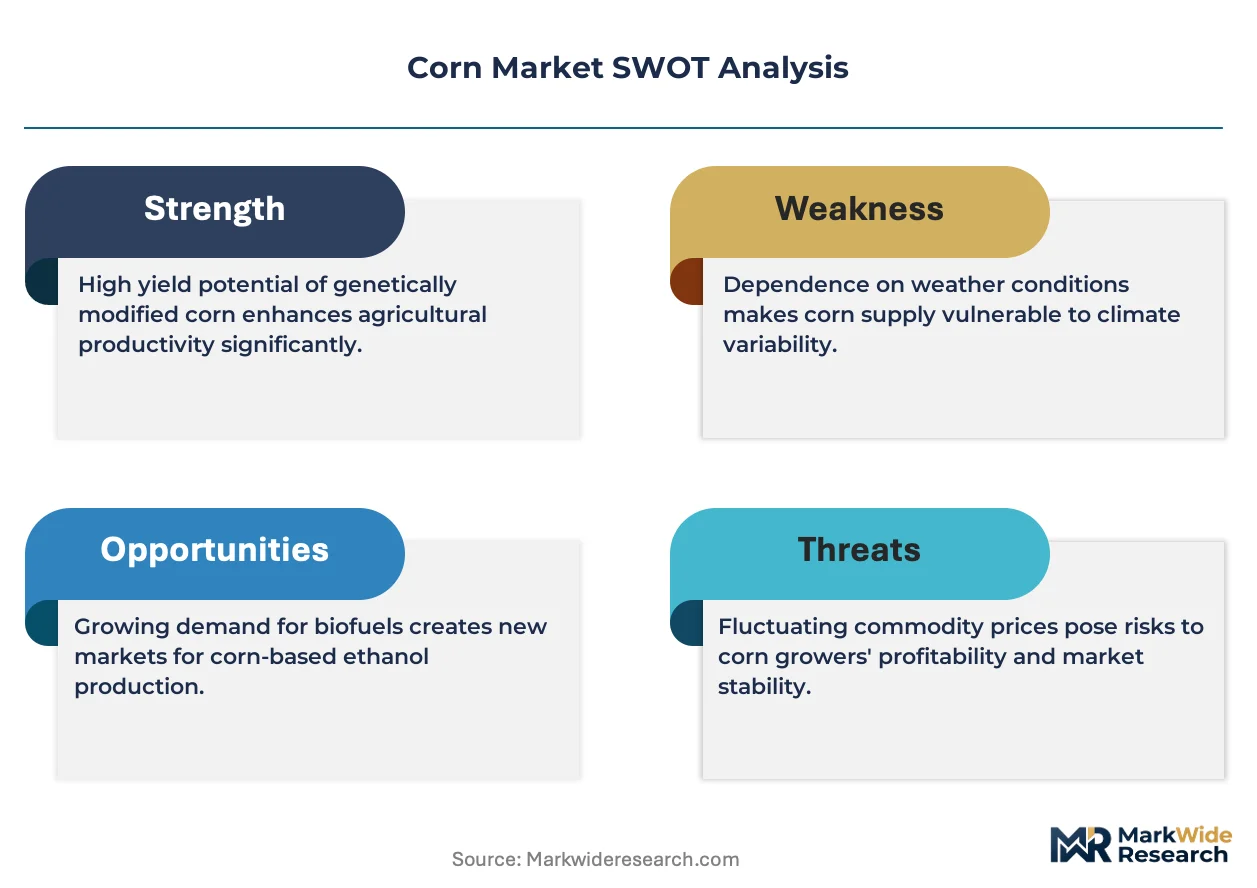
- Input cost volatility:Natural gas prices directly determine nitrogen fertilizer affordability, creating margin compression for farmers without forward-priced nutrient contracts.
- Supply concentration risk:Mississippi River barge logistics create single-point vulnerability during low-water events, as witnessed during the 2022-2023 shipping disruptions.
- Regulatory friction:EPA Renewable Fuel Standard litigation uncertainty delays refinery investment decisions and complicates long-term offtake contracting.
Strategic Opportunities
- Carbon capture verification:IRA biofuel tax credits reward ethanol plants with documented carbon sequestration, creating margin pools for climate-smart origination.
- Ukrainian export recovery:Black Sea corridor reopening presents origination arbitrage potential for traders with established Odessa port relationships.
- Precision fermentation feedstocks:Emerging synthetic biology applications for high-fructose corn syrup derivatives are creating specialty grade premiums outside commodity channels.
Industry Challenges
- Gene editing regulatory divergence:EU EFSA novel food assessments lag US USDA deregulation timelines, complicating synchronized trait launch strategies.
- Climate-smart certification complexity:Multiple competing verification frameworks (Field to Market, Climate FieldView Plus, third-party carbon registries) fragment farmer enrollment and audit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Market |
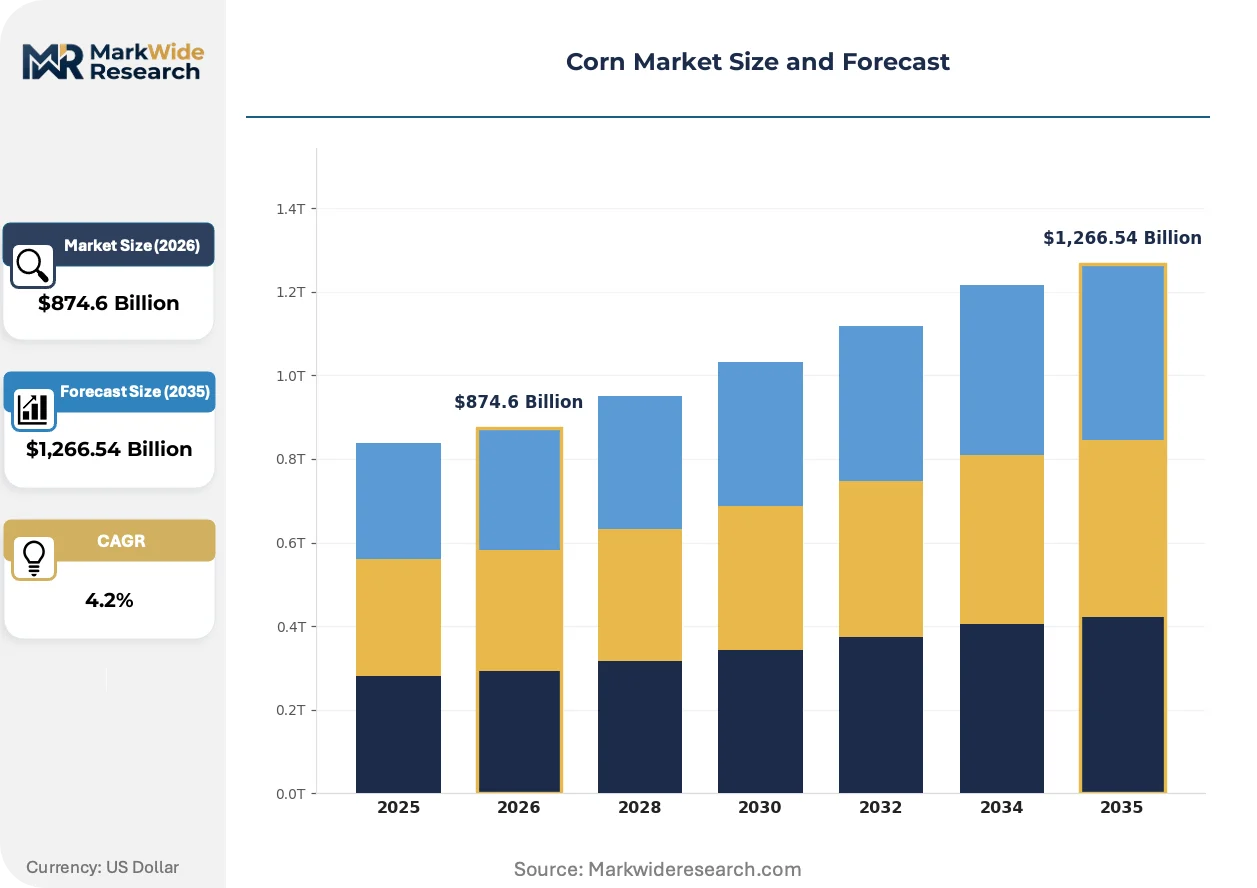
| Market Size in 2026 | $874.6 Billion |
| Market Size in 2035 | $1,266.54 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Corn, Field Corn, Popcorn, Baby Corn End Use Industry: Food & Beverage, Animal Feed, Biofuel, Starch Production Distribution Channel: Wholesale, Retail, Direct Sales, Export Packaging Type: Bulk Bags, Pouches, Cans, Cartons |
| Companies Covered | Archer Daniels Midland, Cargill, CHS, Corteva, Bayer, Syngenta Group, BASF, Công Ty Cổ Phần Khai Anh Bình Thuận, PT Sorini Agro Asia Corporindo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Market Evolving Landscape
Biotechnology convergence with digital agriculture platforms is compressing breeding cycles and enabling real-time agronomic prescription. This reshapes competitive advantage toward data-integrated seed systems rather than germplasm alone.
CRISPR-edited hybrids with multiplexed drought and nitrogen-use efficiency traits are electrifying yield stability across the Western Corn Belt. Farmers in Nebraska and Kansas are adopting these varieties at twice the rate of conventional replacements. The technology is compressing risk premiums for crop insurance underwriters and redirecting R&D budgets toward trait stacking rather than transgenic events.
EU Green Deal Farm to Fork targets are mandating 50% pesticide reduction by 2030, forcing European corn growers toward integrated pest management and biological control agents. This regulatory pressure is accelerating biocide registration pipelines at ECHA while shrinking the addressable market for synthetic crop protection. Eastern European farmers in Poland and Romania are responding through cooperative purchasing of precision application equipment to maintain efficacy at reduced chemical volumes.
Processor procurement is consolidating toward direct origination contracts with documented sustainability attributes, bypassing traditional elevator intermediaries. Large ethanol refiners in Iowa and Illinois now contract directly with farm operations exceeding 5,000 acres for identity-preserved delivery. This channel compression is most visible across the I-80 corridor where rail siding access determines contract eligibility and basis premiums.
Corn Market Segmentation
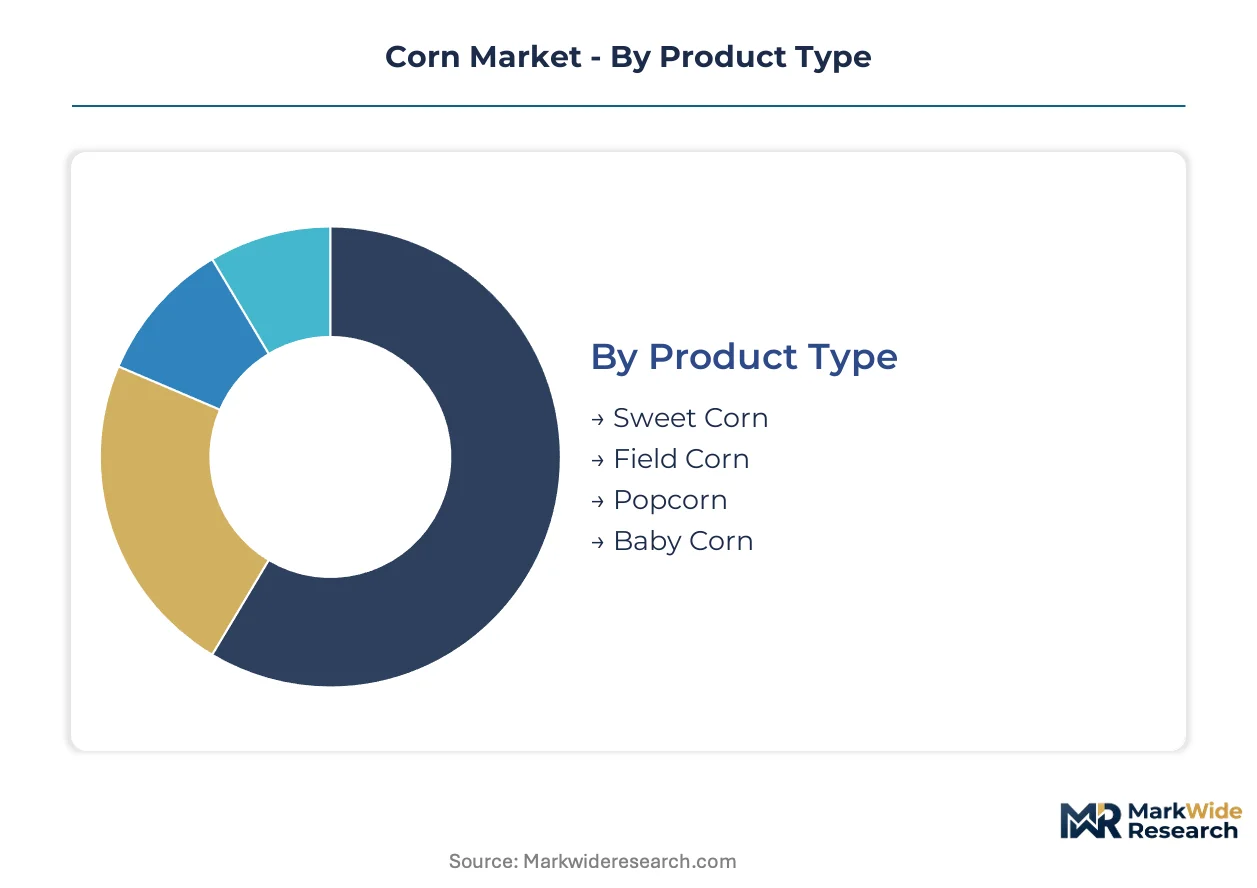
Corn market segmentation reveals how kernel composition and processing pathways create distinct margin pools across food, feed, and fuel applications. Each category channels procurement behavior toward specialized logistics, pricing structures, and regulatory compliance requirements.
Product Type:
Replacement cycles for corn varieties accelerate as CRISPR-edited germplasm delivers drought tolerance and nitrogen-use efficiency gains that obsolete conventional hybrids.
- Field Corn:Starch-dense kernels at 72% carbohydrate composition support dry milling for ethanol and wet milling for syrup derivatives. Demand concentrates across Iowa and Illinois where processor concentration and unit-train logistics anchor origination volumes for biofuel refiners.
- Sweet Corn:Higher sugar content at 18-20% brix commands premium retail pricing through fresh produce and frozen foodservice channels. Per-unit margins exceed field corn by 3-4x, though planted acreage remains below 1% of total corn hectares.
- Popcorn:Hard, dense endosperm with 14% moisture content creates explosive expansion characteristics for snack food applications.
- Baby Corn:Immature ear harvest at 2-4 inches delivers specialized Asian cuisine and canned vegetable markets.
Field Corn sits at the top of the volume ranking, with Sweet Corn climbing the fastest as fresh-to-frozen retail substitution accelerates.
End Use Industry:
Cost tier differentiation separates commodity processors from specialty chemical and pharmaceutical-grade fractionators.
- Biofuel:Dry-milled starch fermentation into ethanol consumes over 40% of US corn production under EPA Renewable Fuel Standard mandates. Brazilian corn-based ethanol expansion in Mato Grosso and Goiás is redirecting acreage from sugarcane feedstock.
- Animal Feed:Distillers dried grains and solubles provide 27% protein concentrate for cattle, swine, and poultry operations. Demand clusters near confined animal feeding operations in Nebraska, Kansas, and Iowa where rail delivery minimizes landed cost.
- Food & Beverage:Wet-milled derivatives include high-fructose corn syrup, dextrose, and modified starches for confectionery and beverage applications.
- Starch Production:Industrial-grade and food-grade starch fractions supply paper, textile, and adhesive manufacturers.
Animal Feed maintains the largest volume position, though Biofuel is expanding most quickly as low-carbon fuel standards tighten across California, Oregon, and Brazil.
Distribution Channel:
Customer type determines contract structure, with large-scale ethanol refiners bypassing traditional elevator intermediaries.
- Wholesale:Elevator aggregators and grain merchants consolidate farm deliveries for resale to processors, with basis pricing tied to Chicago Board of Trade futures.
- Direct Sales:Processor origination contracts with documented sustainability attributes now dominate volumes above 5,000 acres, compressing traditional channel margins.
- Retail:Bagged seed and specialty food-grade corn reach farmers and consumers through farm supply cooperatives and grocery channels.
- Export:Container and bulk vessel shipments from Gulf and Pacific Northwest ports serve Japanese, Mexican, and South Korean buyers.
Wholesale retains volume leadership, while Direct Sales is gaining share fastest as identity-preserved contracting expands.
Packaging Type:
Supply concentration favors bulk handling infrastructure, though food safety regulations drive packaged goods differentiation.
- Bulk Bags:One-ton flexible intermediate bulk containers dominate processor intake, with railcar and barge loading minimizing handling costs.
- Cans:Hermetically sealed containers for sweet corn and baby corn preserve shelf stability for retail and institutional foodservice.
- Pouches:Vacuum-sealed and retort pouches serve frozen and microwave-ready convenience segments.
- Cartons:Corrugated containers for fresh sweet corn and bagged popcorn reach produce departments and snack aisles.
Bulk Bags command the highest tonnage, with Cans showing the steepest expansion trajectory as ready-to-eat vegetable demand rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping corn production geography as biofuel mandates and carbon-intensity standards create divergent compliance costs across jurisdictions. Farmers and processors migrate toward regions with favorable low-carbon fuel policies and established fractionation infrastructure.
United States
Iowa and Illinois concentrate ethanol refining capacity along Mississippi River barge corridors. EPA Renewable Fuel Standard obligations lock in minimum blending volumes, while IRA biofuel tax credits reward carbon capture retrofits at Midwestern plants. Cargill and Archer Daniels Midland anchor origination networks through river-terminal ownership across the Corn Belt.
Brazil
Mato Grosso and Goiás are accelerating corn-based ethanol refinery construction as government mandates displace sugarcane feedstock. ANVISA biotechnology regulations govern CRISPR trait importation, while the RenovaBio program certifies carbon intensity scores for fuel exports. Brazilian processors leverage safrinha double-cropping to supply year-round feedstock to new distilleries.
China
Northeastern provinces including Heilongjiang and Jilin maintain strategic grain reserves while expanding wet-milling capacity for starch derivatives. SAMR oversees genetically modified variety approval timelines that lag domestic breeding programs. State-owned processors in Jilin Province dominate industrial corn procurement for modified starch and polyol production.
Argentina
Buenos Aires Province and Córdoba anchor export-oriented production through Rosario river-port complexes. The national agricultural regulator SENASA manages phytosanitary certification for Brazilian and Chinese buyers. Crushing margins at Up-River terminals attract multinational origination desks seeking Pacific Northwest arbitrage against US Gulf pricing.
France
Île-de-France and Grand Est cluster wet-milling facilities serving EU food and pharmaceutical starch demand. EFSA novel food assessments delay CRISPR-edited variety adoption against conventional hybrid planting. French cooperatives are redirecting acreage toward identity-preserved waxy corn contracts for specialty starch fractionators.
Corn Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue climate-smart certification and precision fermentation feedstock specialization. The vendor base stratifies across three tiers: integrated processors controlling origination logistics, germplasm innovators with trait-stacked portfolios, and regional aggregators serving localized food-grade channels. Dominant competitive moves include backward integration into carbon capture infrastructure and direct contracting with large-scale farm operations above 5,000 acres.
Within the integrated-processor archetype, Archer Daniels Midland and Cargill exemplify scale-driven origination through captive river-terminal and rail-siding networks. Corteva occupies a position representing germplasm innovation, with drought-tolerant CRISPR-edited hybrids penetrating the Western Corn Belt at accelerated replacement rates. These three entities anchor the competitive structure by controlling distinct value-chain segments: logistics infrastructure, biological intellectual property, and farmer-facing distribution.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Cargill |
| CHS |
| Corteva |
| Bayer |
| Syngenta Group |
| BASF |
| Công Ty Cổ Phần Khai Anh Bình Thuận |
| PT Sorini Agro Asia Corporindo |
| Others |
Value Network & Pricing Analysis
California's Low Carbon Fuel Standard gates qualified supply and premium-tier pricing access for corn ethanol producers, requiring verified carbon intensity scores that only processors with carbon capture retrofits can achieve. This regulatory filter bifurcates the market into certified premium channels and commodity spot markets, with compliance costs determining contract eligibility at major refineries.
Pricing Analysis
Distributor margins compress as ethanol refiners bypass elevator intermediaries for direct origination contracts with operations above 5,000 acres. Contract-based long-term offtake dominates biofuel procurement, with price differentiation driven by carbon intensity certification and rail siding access. Pricing pressure stems from nitrogen fertilizer cost volatility, with farmers lacking forward-priced nutrient contracts facing margin erosion. Large-scale processors demonstrate lowest price sensitivity due to captive logistics infrastructure, while smaller farm operations remain exposed to basis volatility at river terminals.
Supply Chain Analysis
Direct-to-processor channels handle hyperscale ethanol refinery demand across Iowa, Illinois, and Nebraska, consolidating origination volumes above traditional wholesale elevators. Geographic supply concentrates in the United States, Brazil, and Argentina, with raw material dependencies on nitrogen fertilizers, diesel fuel, and specialized railcar fleets. Single-point vulnerability at Mississippi River barge chokepoints creates structural risk during low-water events. Distribution runs through unit-train rail networks and river-terminal complexes, with identity-preserved contracting expanding fastest among sustainability-verified channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corn market functions as a regulatory compounder where EPA Renewable Fuel Standard blending obligations structurally mandate demand regardless of commodity price cycles.
For Market Incumbents: Extend carbon capture infrastructure investments to secure IRA biofuel tax credit eligibility before verification bottlenecks intensify. Deepen backward integration into nitrogen fertilizer production to hedge input cost volatility threatening farm-level origination volumes. Defensive positioning against CRISPR seed disruptors requires accelerated germplasm licensing partnerships. For New Entrants and Emerging Players: Precision fermentation feedstock suppliers represent the most penetrable white-space segment, with specialty high-fructose corn syrup derivatives commanding premiums outside commodity channels. Target Brazilian safrinha double-cropping regions where corn-based ethanol refinery construction outpaces domestic origination capacity. A go-to-market angle anchored in climate-smart certification compliance services bypasses capital-intensive processing infrastructure requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional grain elevator networks because direct origination contracting is compressing traditional intermediary margins and forcing consolidation. Five-to-ten year viability hinges on proximity to carbon capture-enabled ethanol plants with documented sequestration. The signal to watch is EPA litigation resolution timing, which will determine refinery investment confidence and long-term offtake contracting velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | IRA tax credits reward ethanol plants with documented sequestration at Iowa and Illinois facilities. |
| CRISPR Trait Licensing | Drought-tolerant germplasm stacks expand plantable geography into marginal rainfall zones across Nebraska. |
| Direct Origination Contracting | Processor procurement bypasses elevator intermediaries for identity-preserved delivery above 5,000 acres. |
| River Terminal Expansion | Cargill and ADM anchor origination networks through Mississippi Basin barge corridor ownership. |
| Climate-Smart Certification | Multiple verification frameworks fragment farmer enrollment, creating audit service consolidation opportunities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with seed development executives, ethanol plant operations managers, grain elevator procurement leads, and farm operations directors with secondary validation. USDA crop insurance databases, EPA Renewable Fuel Standard compliance filings, SEC 10-K disclosures from major processors, and customs export records anchored the data foundation. Bottom-up acreage and yield models triangulated against top-down consumption estimates from biofuel and feed channels.
Segment-weighting approaches distributed value across field corn, sweet corn, and popcorn product types, with end-use industry splits modeling biofuel, animal feed, and food processing demand separately. Regional production clusters, distribution channel structures, and packaging format requirements provided additional segmentation dimensions. CAGRs derived from historical volume trajectories and policy-mandated blending obligations across the projection horizon. Key inputs included EPA mandate litigation timelines, Brazilian RenovaBio carbon intensity scoring adoption, and CRISPR trait commercialization rates.
Revisions become necessary when EPA regulatory litigation resolves unexpectedly, Brazilian ethanol mandate acceleration displaces additional sugarcane acreage, or Mississippi River logistics disruptions persist beyond seasonal norms. Forecasts reflect assumptions regarding policy continuity, climate volatility patterns, and biotechnology regulatory convergence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Paraguay Grains Market
Grains
Grain Augers Market
Grains
Millets Market
Grains
Organic Cereals Market
Grains
Black Gram Market
Grains
Colombia Grains Market
Grains
Rice Flour Market
Grains
Uganda Grains Market
Grains
North America Pulses Market
Grains
Global Wheat Market
Grains
Dried Spent Grain Market
Grains
Grain-Based Flours Market
Grains
Soy Grits Market
Grains
Heritage Grain Market
Grains
Corn Flour Market
Grains
Rolled Oats Market