
 Fortified Rice Market | 2026-2036
Fortified Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Fortified Rice Market Analysis
Food service procurement is tilting toward pre-fortified bulk supply contracts as institutional nutrition standards tighten. Cargill Incorporated leverages its grain handling infrastructure to control inbound paddy quality for micronutrient retention. Koninklijke DSM N.V. sustains formulation leadership through its premix nutrient portfolio. LT Foods anchors South Asian brand equity with heritage basmati lines now entering fortified extensions.
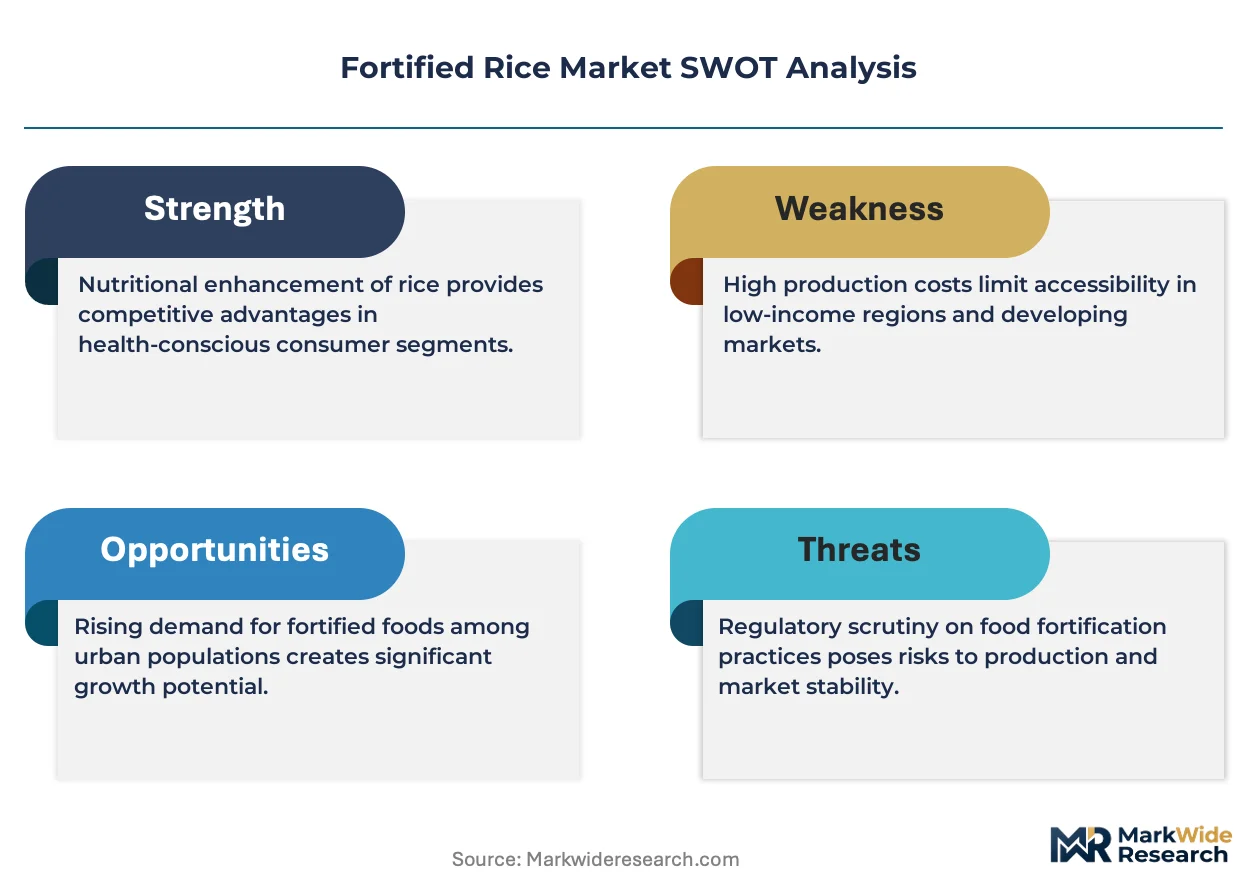
Fortified rice denotes ordinary milled grain infused with micronutrient premixes—typically iron, zinc, folic acid, and B vitamins—through coating, extrusion, or dusting processes that withstand washing and cooking losses. Its primary purpose is to combat dietary deficiency anemia and neural tube defects in populations where rice constitutes the caloric staple. White rice dominates current volume flows due to lower price elasticity among subsidy-dependent consumers, while minerals as a fortification type captures disproportionate policy funding because iron deficiency carries the highest documented disease burden. E-commerce channels represent the fastest-growing distribution vector for premium nutraceutical-fortified variants targeting urban households.
WHO guidelines on rice fortification shape national procurement mandates, while India's FSSAI enforces premix quality thresholds for public distribution system inclusion. Brazil's ANVISA governs bioavailability testing protocols that determine which suppliers qualify for school feeding tenders. Stakeholders must monitor evolving micronutrient premix patent landscapes and subsidy program qualification criteria as procurement centralization accelerates.
Market Dynamics
Government procurement centralization for public distribution systems is compressing supplier margins while mandating micronutrient bioavailability thresholds that reshape formulation economics across the fortified rice value chain.
Growth Catalysts
- India's FSSAI premix mandates:Mandatory iron-folic acid inclusion for Public Distribution System rice procurement creates guaranteed offtake volumes for compliant suppliers.
- Biofortification breeding advances:High-iron rice varieties developed through conventional breeding reduce post-harvest fortification costs and improve consumer sensory acceptance.
- School feeding program expansion:Brazil's National School Feeding Program now specifies fortified rice in 30% of meal compositions, institutionalizing demand from ANVISA-qualified processors.
Market Restraints
- Premix input concentration:Iron-EDTA and encapsulated vitamin suppliers cluster in Western Europe, exposing buyers to euro-denominated cost volatility and freight premiums.
- Extrusion equipment capex barriers:Hot-extrusion fortification lines require $2-4 million per installation, excluding small millers from government tender qualification.
- Consumer washing behavior:Traditional triple-wash practices in South Asian households degrade surface-applied fortificants before nutrient ingestion occurs.
Strategic Opportunities
- Indonesia's BULOG procurement reform:Planned shift from price-only tenders to nutrient-density scoring creates premium positioning for bioavailable premix suppliers.
- E-commerce direct-to-household channels:Urban middle-class consumers in São Paulo and Mumbai bypass subsidy systems for premium nutraceutical-fortified variants.
- Cold-chain independent distribution:Shelf-stable fortified rice kits penetrate last-mile rural networks where fresh food logistics fail.
Industry Challenges
- Premix analytical chemist scarcity:Validating micronutrient homogeneity and stability requires specialized food chemistry expertise concentrated in urban testing labs.
- Multi-jurisdiction certification stacking:Suppliers to WHO, FSSAI, and ANVISA simultaneously face conflicting bioavailability test protocols and audit timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Rice Market |
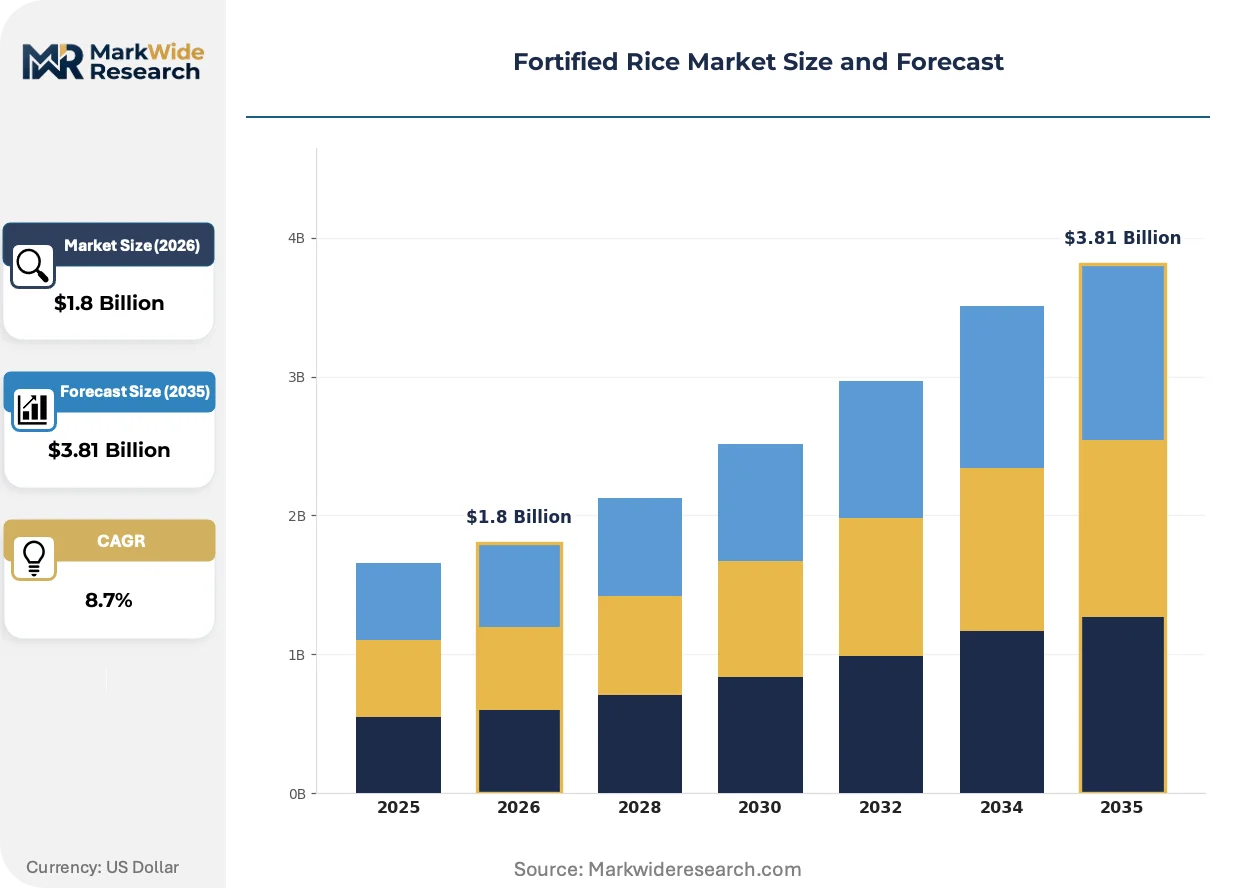
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rice, Brown Rice, Jasmine Rice, Basmati Rice Fortification Type: Vitamins, Minerals, Nutraceuticals, Probiotics Distribution Channel: Retail Stores, E-commerce, Food Service, Wholesale End User: Households, Restaurants, Institutions, Food Banks |
| Companies Covered | Cargill Incorporated, Koninklijke DSM N.V., BASF SE, Olam International Limited, LT Foods, General Mills Inc., Bunge Limited, Willmar International Ltd., Ebro Foods, S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Rice Market Emerging Trajectories
Fortification technology is pivoting from surface coating toward kernel-integrated approaches that withstand processing losses, while procurement digitization and consumer traceability demands reshape how nutritional claims are verified and monetized.
Extrusion-based kernel reconstruction is virtualizing the fortification process by grinding milled rice into flour, blending micronutrient premixes, and reconstituting fortified kernels that match natural grain morphology. Large-scale millers in India and Brazil are adopting these systems to meet FSSAI and ANVISA homogeneity standards. The technology is virtualizing quality assurance workflows by embedding nutrient distribution directly into grain structure rather than relying on post-milling surface application.
WHO guideline adoption into national procurement law is tightening supplier qualification frameworks across multiple geographies. India's 2023 rice fortification directive mandates iron, folic acid, and B12 inclusion for all PDS rice, with state-level food departments now enforcing premix batch testing. Brazil's ANVISA Resolution RDC 340 establishes bioavailability thresholds that disqualify coating-only fortificants from school feeding tenders, forcing technology migration toward extrusion or hot-soaking methods.
Institutional buyers are consolidating procurement through five-year supply agreements that bundle fortification, logistics, and monitoring services. State food departments in India and municipal school boards in Brazil now contract integrated service providers rather than buying commodity rice separately. This consolidation is most advanced in Maharashtra and Minas Gerais, where single-vendor contracts cover milling, fortification, warehousing, and last-mile distribution to ration shops and school kitchens.
Fortified Rice Market Segmentation
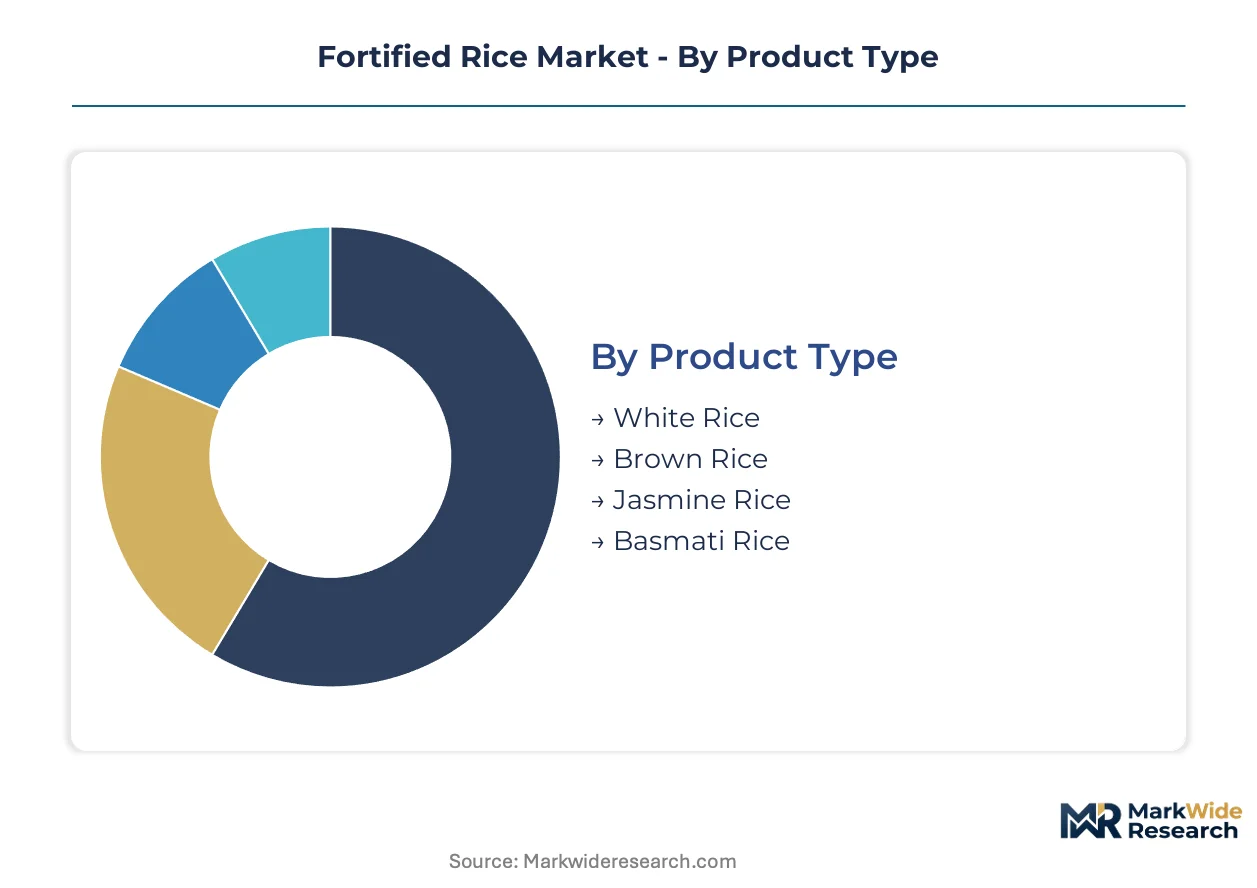
Segmentation in fortified rice reveals divergent margin structures and technology requirements across product grades and procurement channels. Each dimension exposes distinct vulnerability to micronutrient degradation, regulatory compliance costs, and price elasticity constraints that reshape supplier strategy.
Product Type:
Cycle times vary dramatically: polished white rice moves through public distribution channels within weeks, while aromatic specialty grades age in brand inventories for months.
- White Rice:Polished endosperm with bran and germ removed accepts surface-applied fortificants through dusting or coating at lowest unit cost. India's Public Distribution System channels this grade to subsidy-dependent households in Bihar and Uttar Pradesh, where FSSAI mandates iron-folic acid inclusion.
- Brown Rice:Intact bran layer retains natural micronutrients but requires extrusion-based kernel reconstruction to achieve homogenous fortification distribution. Brazil's ANVISA-qualified processors favor this grade for school feeding tenders where bioavailability testing protocols favor integrated nutrient matrices.
- Jasmine Rice:Thai-origin aromatic variety commands premium positioning in Southeast Asian export markets with fragrance-sensitive consumer bases.
- Basmati Rice:Long-grain heritage cultivar from Punjab and Haryana attracts urban middle-class demand through e-commerce direct-to-household channels.
White rice dominates installed base. Basmati and jasmine are where expansion concentrates.
Fortification Type:
Cost tiers separate commodity micronutrient premixes from premium bioactive formulations with patent-protected delivery systems.
- Minerals:Iron-EDTA and zinc oxide premixes constitute the policy-funded baseline for anemia reduction programs. Iron deficiency carries the highest documented disease burden, concentrating procurement investment in South Asian public health budgets.
- Vitamins:Folic acid and B-complex blends target neural tube defect prevention in maternal health programs. Indonesia's BULOG procurement reform weights nutrient-density scoring toward vitamin-fortified variants for school feeding expansion.
- Nutraceuticals:Omega-3 and antioxidant-enriched formulations target premium urban households in São Paulo and Mumbai through e-commerce channels.
- Probiotics:Viable culture integration requires cold-chain infrastructure that limits deployment to institutional catering with controlled logistics.
Minerals dominate installed base. Nutraceuticals are where expansion concentrates.
Distribution Channel:
Customer type determines margin structure: institutional buyers negotiate five-year supply agreements while e-commerce captures price-insensitive premium demand.
- Food Service:Pre-fortified bulk supply contracts bundle milling, nutrient application, and last-mile delivery to municipal school boards and hospital canteens. Maharashtra state food departments consolidate procurement through single-vendor agreements covering warehousing and distribution to ration shops.
- E-commerce:Direct-to-household platforms bypass subsidy systems for nutraceutical-fortified variants targeting urban middle-class consumers. Shelf-stable fortified rice kits penetrate last-mile rural networks where fresh food logistics fail.
- Retail Stores:Traditional kirana shops and supermarkets distribute standard-fortified grades to price-sensitive household segments.
- Wholesale:Bulk commodity traders supply small millers excluded from government tender qualification by extrusion equipment capex barriers.
Food service dominates installed base. E-commerce is where expansion concentrates.
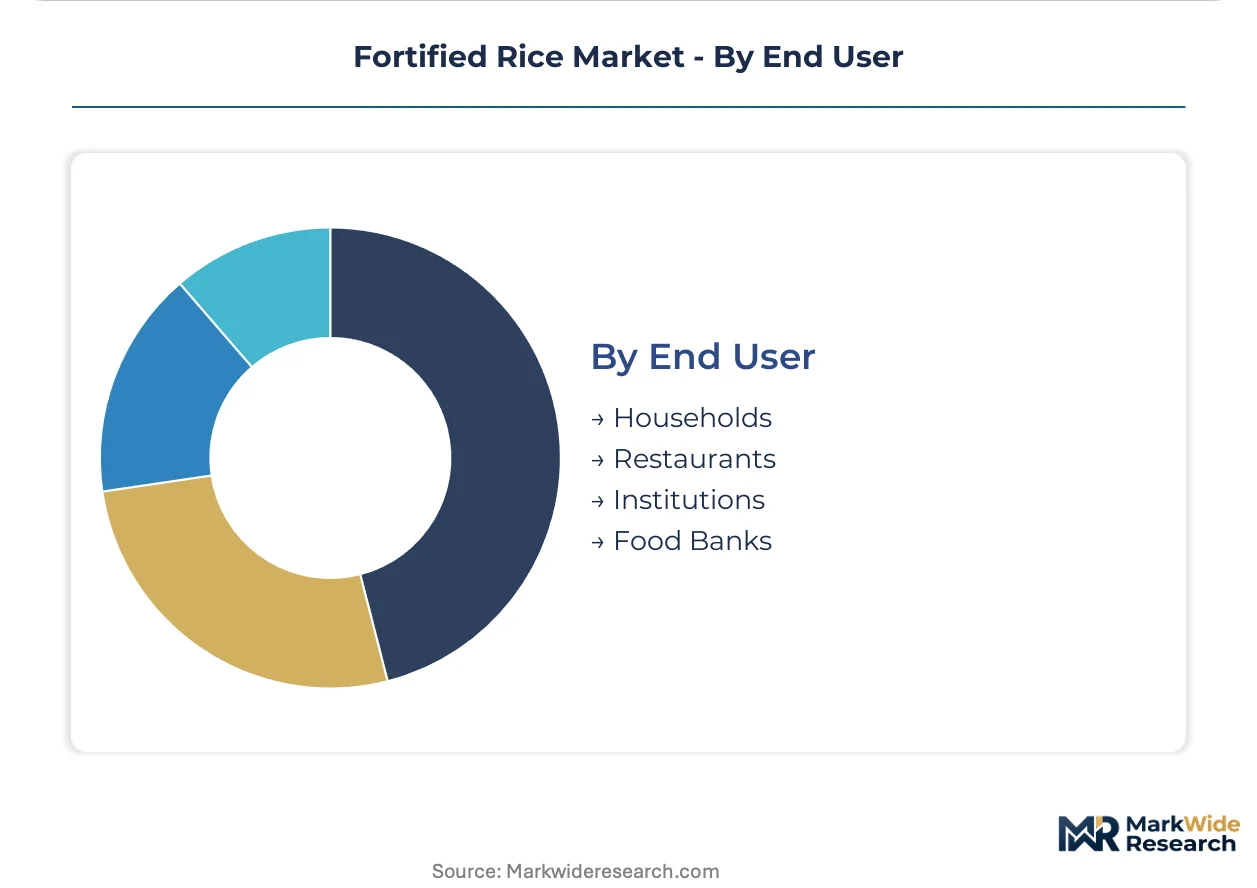
End User:
Application requirements split between volume-driven institutional procurement and quality-sensitive household consumption.
- Institutions:Government procurement centralization compresses supplier margins while mandating micronutrient bioavailability thresholds. Brazil's National School Feeding Program specifies fortified rice in meal compositions, institutionalizing demand from ANVISA-qualified processors.
- Households:Triple-wash practices in South Asian households degrade surface-applied fortificants, driving technology migration toward kernel-integrated extrusion methods that withstand processing losses.
- Restaurants:Commercial kitchens prioritize cooking stability and sensory neutrality over nutrient density claims.
- Food Banks:Emergency relief programs prioritize shelf stability and unit cost minimization over fortification sophistication.
Institutions dominate installed base. Households are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI mandates in India anchor procurement volumes across South Asia, while ANVISA protocols in Brazil and BULOG reforms in Indonesia reshape qualification standards for premix suppliers.
India
Maharashtra and Uttar Pradesh drive institutional procurement through the Public Distribution System. FSSAI mandates iron-folic acid inclusion for all PDS rice, with state food departments enforcing premix batch testing. Integrated service providers in Mumbai and Pune now bundle milling, fortification, and last-mile distribution under single-vendor contracts.
Brazil
Minas Gerais and São Paulo concentrate ANVISA-qualified processing capacity for school feeding programs. Resolution RDC 340 establishes bioavailability thresholds that disqualify coating-only fortificants, forcing technology migration toward extrusion methods. Municipal school boards in these states contract integrated providers covering warehousing and kitchen delivery.
Indonesia
Jakarta and Surabaya anchor BULOG procurement reform shifting from price-only tenders to nutrient-density scoring. Java-based millers adapt premix formulations to meet weighted scoring criteria favoring vitamin-fortified variants. State logistics agency restructuring creates premium positioning opportunities for bioavailable premix suppliers.
United States
California and Arkansas house grain handling infrastructure serving institutional nutrition programs. USDA school meal guidelines incorporate fortified grain standards, while FDA food additive regulations govern premix approval pathways. Rice millers in the Sacramento Valley and Mississippi Delta regions supply pre-fortified bulk contracts to district-level food service operations.
Thailand
Bangkok and Chiang Mai process jasmine rice exports with fragrance-preserving fortification protocols. The Thai Food and Drug Administration enforces micronutrient labeling standards for cross-border shipments. Exporters in these urban centers balance sensory neutrality requirements with nutrient retention specifications for Southeast Asian destination markets.
Fortified Rice Market Vendor Landscape
Integrated agribusiness conglomerates and specialized nutrient premix suppliers split the market between volume-driven institutional contracts and formulation-intensive premium segments. Supplier consolidation accelerates as five-year bundled service agreements displace commodity spot purchasing. Three archetypes dominate: grain handlers with captive milling infrastructure, premix specialists with patent-protected delivery systems, and heritage rice brands extending into fortified product lines. Competitive moves center on backward integration into paddy sourcing and technology licensing for extrusion-based kernel reconstruction.
Among grain-handling conglomerates, Cargill Incorporated exemplifies the infrastructure-heavy archetype through its integrated supply chain footprint. Koninklijke DSM N.V. occupies the premix formulation tier with its nutrient technology portfolio. LT Foods anchors the heritage-brand extension model, leveraging South Asian basmati equity into fortified product development. These three represent distinct strategic positions rather than direct segment overlap.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Koninklijke DSM N.V. |
| BASF SE |
| Olam International Limited |
| LT Foods |
| General Mills Inc. |
| Bunge Limited |
| Willmar International Ltd. |
| Ebro Foods, S.A. |
| Others |
Supply Flow & Price Mechanics
Western European premix supplier concentration anchors margin capture upstream, while downstream pricing power fragments across Indian state procurement offices, Brazilian municipal school boards, and Indonesian logistics agencies with divergent tender sophistication.
Pricing Analysis
Price spreads between euro-denominated premix inputs and rupee-denominated government tenders compress processor margins unevenly across geographies. Contract-based long-term offtake dominates institutional procurement, with price differentiation driven by FSSAI certification tier and volume scale in India, versus ANVISA bioavailability thresholds in Brazil. Cost compression in mid-tier processors is intensifying because extrusion equipment capex excludes smaller millers from qualification. Subsidy-dependent households in Bihar and Uttar Pradesh exhibit highest price sensitivity; urban e-commerce buyers in Mumbai and São Paulo show lowest.
Supply Chain Analysis
Extended payment terms from Indian state food departments and BULOG procurement cycles in Indonesia strain working capital for premix suppliers and millers alike. Supply concentration rests on India, Brazil, and Indonesia for paddy sourcing and extrusion processing, with Western Europe anchoring iron-EDTA and encapsulated vitamin production. Raw material dependencies include micronutrient premixes, hot-extrusion equipment, and homogeneity testing reagents. Single-source vulnerability runs through European premix suppliers exposed to freight volatility. Distribution runs through integrated service providers bundling milling, fortification, warehousing, and last-mile delivery under single-vendor contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fortified rice procurement is consolidating into platform-economy structures where integrated service providers bundle physical supply with compliance monitoring, creating interoperability premiums for vendors with digitized nutrient tracking systems.
For Market Incumbents: Harden formulation leadership through captive premix production or exclusive supply agreements with DSM and BASF, defending against commodity premix traders entering through Indonesian BULOG reform tenders. Deepen backward integration into high-iron paddy breeding programs to reduce post-harvest fortification costs and improve sensory acceptance margins.
For New Entrants and Emerging Players: Pursue white-space positioning in nutraceutical-fortified basmati and jasmine variants through e-commerce direct-to-household channels in São Paulo and Mumbai, where price elasticity is lowest and brand premiums are achievable. Target cold-chain independent shelf-stable kits for last-mile rural networks in Maharashtra and Minas Gerais as the most penetrable institutional segment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed grain handlers lacking premix formulation capabilities or ANVISA/FSSAI certification infrastructure. Long-term viability favors processors with integrated extrusion technology and five-year bundled service contracts with state food departments. Watch Indonesian BULOG nutrient-density scoring implementation as the signal for premium premix supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Extrusion Technology Licensing | Kernel reconstruction patents from DSM enable ANVISA-qualified processors to displace coating-only competitors in Brazil. |
| Backward Integration into Paddy Breeding | High-iron variety development reduces post-harvest fortification costs for Indian PDS suppliers facing FSSAI mandates. |
| Premix Supplier Consolidation | Captive nutrient production defends margin compression from euro-denominated input volatility and freight premiums. |
| E-commerce Direct-to-Household Launch | Urban middle-class channels in Mumbai and São Paulo bypass subsidy systems for nutraceutical-fortified premium variants. |
| Integrated Service Provider Contracts | Five-year bundled agreements with Maharashtra and Minas Gerais food departments lock out commodity spot competitors. |
Methodological Framework
Cross-validation between primary interviews with premix formulation chemists, state food department procurement officers, and ANVISA regulatory specialists anchors the qualitative findings against secondary validation from FSSAI batch testing records, ANVISA Resolution RDC 340 filings, and BULOG tender documentation. Mill operations managers at integrated service providers and distribution logistics coordinators in Maharashtra and Minas Gerais provided operational ground-truth. Bottom-up triangulation across processor capacity disclosures and top-down reconciliation against government procurement budget allocations shaped volume estimates.
Calibration against historical premix input cost trajectories and government subsidy program expansion timelines structured the analytical framework across the projection horizon. Segmentation dimensions modeled include rice grade tier, fortification type, distribution channel archetype, and end-user procurement sophistication. CAGRs were derived from elasticity-adjusted demand curves for subsidy-dependent versus premium household segments, incorporating bioavailability testing protocol adoption rates as a technology diffusion input.
The forecast holds incumbent behavior within observed patterns; aggressive moves by commodity premix traders or rapid biofortification breeding breakthroughs would shift outcomes. Macroeconomic currency volatility affecting euro-denominated input costs, regulatory deviation in FSSAI enforcement intensity, or technological disruption in cold-chain independent distribution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Asia-Pacific Wheat Market
Grains
00 Flour Market
Grains
Black Gram Market
Grains
Italy Rice Market
Grains
Grain Roller Market
Grains
Global Cassava Flour Market
Grains
Millet Flour Market
Grains
Europe Wheat Protein Market
Grains
Corn Silage Market
Grains
United States Maize Market
Grains
Grain-Based Flours Market
Grains
Wheat Flour Market
Grains
Asia-Pacific Rice Market
Grains
North America Wheat Market
Grains
South America Wheat Market
Grains
Africa Maize Market