
 Cadmium Market | 2026-2036
Cadmium Market Size, Share, and Industry Trends Forecast 2026-2036
Cadmium Market Analysis
Long-term offtake contracts for refined cadmium metal are decoupling spot pricing from actual consumption patterns in battery supply chains. Korea Zinc leverages its integrated zinc-lead smelting complex to sustain captive cadmium output. Young Poong Corp anchors Korean domestic supply through vertical control over concentrate sourcing. Dowa Metals and Mining differentiates via advanced hydrometallurgical refining that navigates tightening impurity specifications.
Cadmium is a soft, bluish-white d-block metal with atomic number 48, typically recovered as a byproduct of zinc refining through roast-leach-electrowinning or hydrometallurgical circuits; its primary commercial purpose centers on corrosion-resistant coatings, rechargeable battery electrodes, and semiconductor thin-films. Cadmium telluride dominates photovoltaic applications where its direct bandgap of 1.5 eV enables high absorption efficiency in thin-film solar modules. Battery manufacturing occupies the largest value pool among applications, though pigment production faces structural decline under chromatic substitution pressure. Electronics as an end user concentrates premium-grade demand for plating precision.
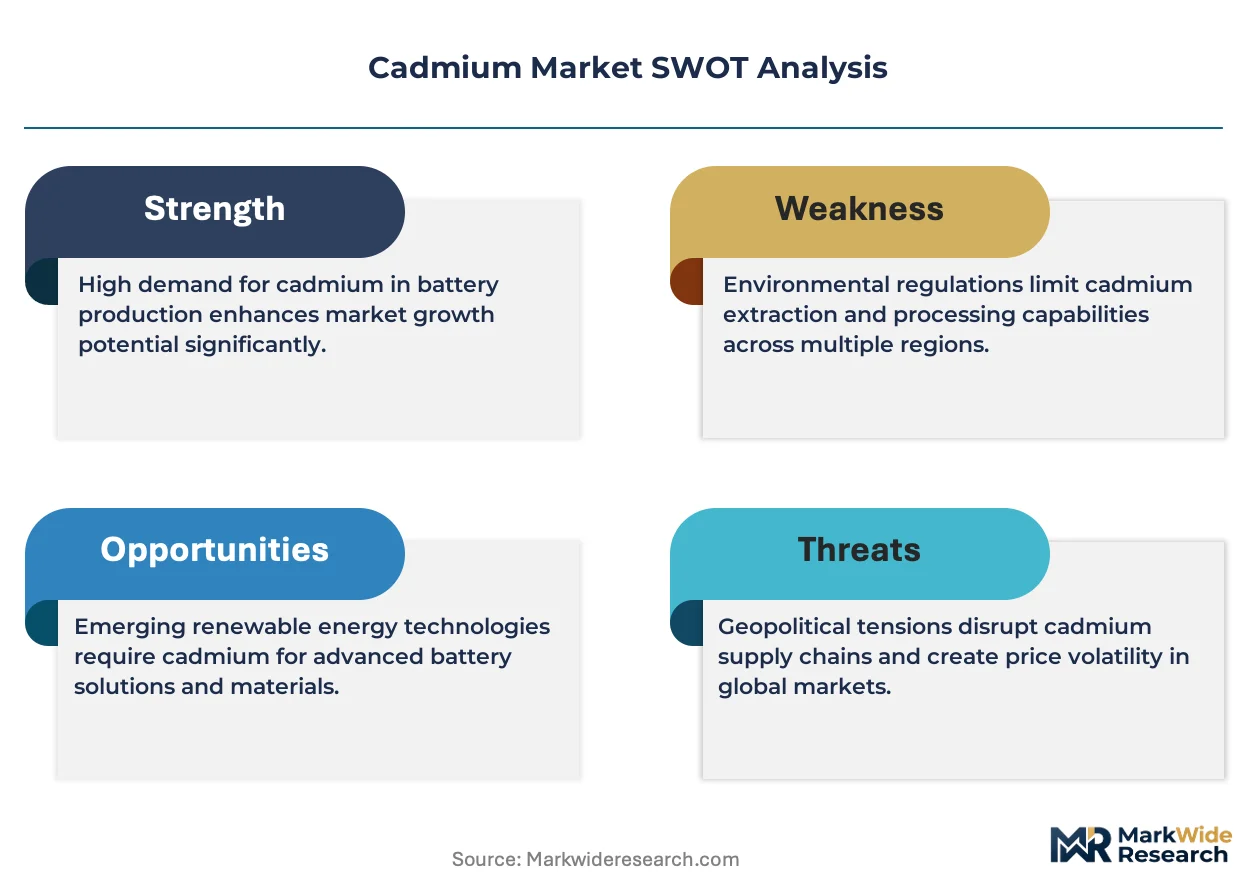
EPA hazardous waste regulations under RCRA and OSHA exposure limits shape US handling protocols, while REACH authorization requirements in Europe restrict cadmium use in plastics and coatings. China's MEE enforces discharge standards on zinc smelters that control byproduct cadmium flows. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where closed-loop recycling mandates will displace virgin metal demand.
Market Dynamics
REACH authorization requirements and EPA hazardous waste standards are forcing cadmium supply chains toward closed-loop recycling infrastructure, decoupling virgin metal flows from battery manufacturer demand.
Growth Catalysts
- Nickel-cadmium battery demand:Stationary backup power systems and industrial motive applications sustain offtake volumes despite lithium-ion encroachment in portable electronics.
- Cadmium-telluride photovoltaics:Utility-scale solar developers deploy thin-film modules where high-temperature performance and low-light efficiency offset silicon economics.
- Defense electronics plating:Aerospace and military specifications for corrosion-resistant coatings preserve premium-grade consumption against commercial substitution.
Market Restraints
- REACH authorization friction:ECHA restrictions on cadmium use in plastics and coatings eliminate consumer-accessible applications across the European Union.
- Zinc concentrate supply concentration:Primary cadmium recovery depends on Chinese and Korean zinc-lead smelting complexes, creating single-point vulnerabilities.
- Lithium-ion chemistry substitution:Energy density advantages in portable and electric vehicle batteries compress nickel-cadmium addressable market.
Strategic Opportunities
- Indian downstream processing expansion:Electronics manufacturing incentives under PLI schemes attract refining investment for defense and semiconductor applications.
- Closed-loop battery recycling mandates:Extended producer responsibility frameworks in Korea and Japan create captive metal recovery revenue streams.
- Cadmium-telluride tandem cell architectures:Perovskite integration research opens next-generation photovoltaic efficiency pathways for utility developers.
Industry Challenges
- Hydrometallurgical refining expertise scarcity:Advanced impurity separation capabilities concentrate among Japanese and Korean specialists, limiting capacity expansion.
- RCRA hazardous waste compliance timelines:US battery recyclers face capital-intensive facility upgrades to meet evolving EPA discharge and storage standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cadmium Market |
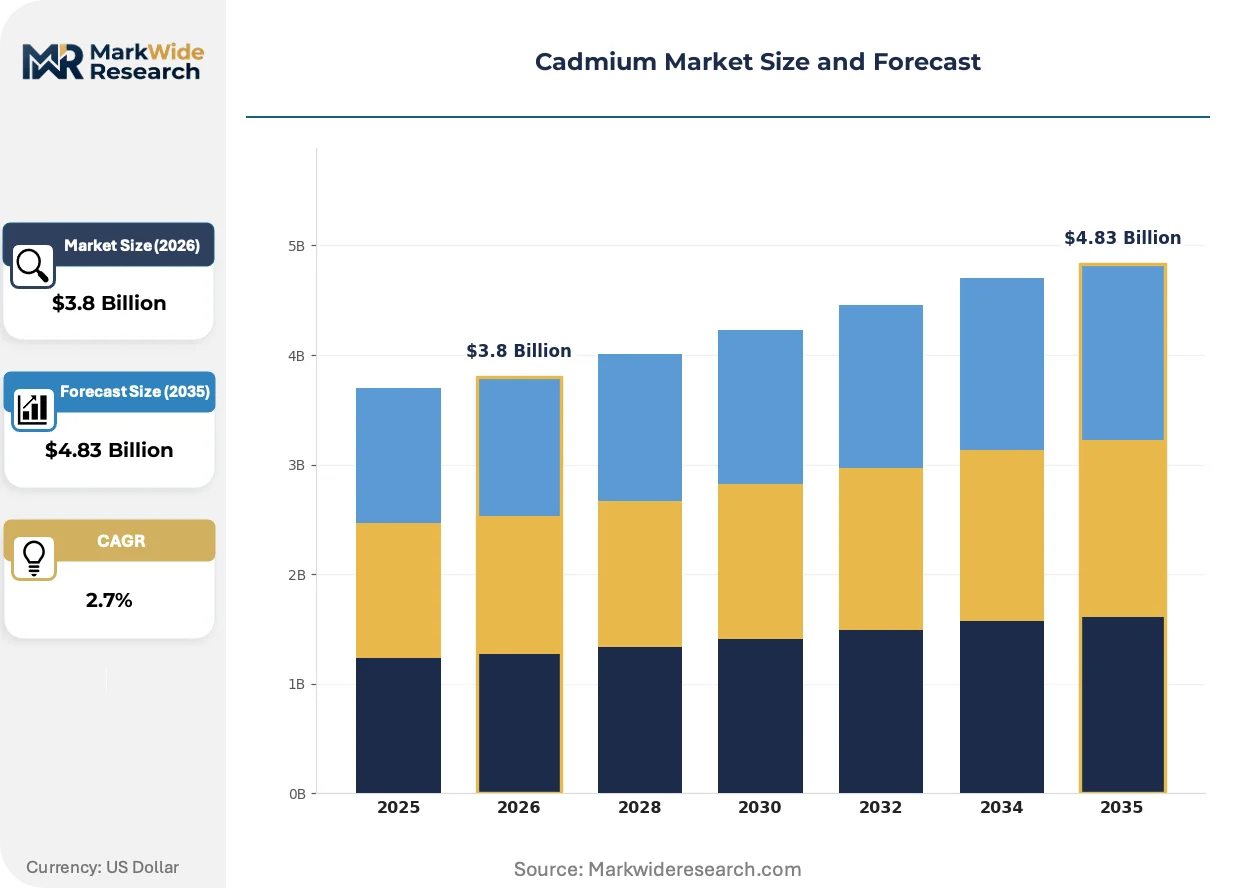
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.83 Billion |
| CAGR (2026 – 2036) | 2.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cadmium Oxide, Cadmium Sulfide, Cadmium Telluride, Cadmium Chloride Application: Battery Manufacturing, Coatings and Platings, Pigment Production, Pharmaceuticals End User: Electronics, Automotive, Aerospace, Healthcare Distribution Channel: Direct Sales, Online Sales, Wholesale, Retail |
| Companies Covered | Young Poong Corp, Huludao Zinc Industry, Korea Zinc, Dowa Metals and Mining, Mitsui Mining and Smelting, Nyrstar NV, Zhuzhou Smelter Group, JX Advanced Metals Corporation, Teck Resources Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cadmium Market Emerging Trajectories
Technology substitution, regulatory stringency, and supply chain reconfiguration are simultaneously compressing legacy applications while opening specialized high-value niches for refined cadmium metal.
Vacuum-deposited cadmium telluride thin-film technology is overtaking silicon in utility-scale desert solar installations where module temperature coefficients favor direct bandgap absorption. First Solar and emerging Chinese manufacturers expand manufacturing lines across Arizona and Malaysia. The technology is overtaking conventional crystalline silicon in specific irradiance conditions, compressing polysilicon demand in utility procurement portfolios.
China's MEE discharge standards on zinc smelters tighten cadmium effluent limits below 0.05 mg per liter, forcing hydrometallurgical circuit retrofits at concentrate processing facilities. Smelters in Hunan and Yunnan provinces invest in ion-exchange recovery systems to comply with January enforcement windows. Battery-grade cadmium output from Chinese refiners faces certification delays as laboratories clear accumulated compliance testing backlogs.
Battery OEM procurement contracts now specify recycled content minimums rather than virgin metal provenance, restructuring supplier qualification criteria. Korean and Japanese buyers consolidate vendor panels around recyclers with RCRA-equivalent certifications. This preference shift concentrates contract volumes among three certified refiners in South Korea, squeezing spot market liquidity for uncertified Chinese output.
Cadmium Market Segmentation
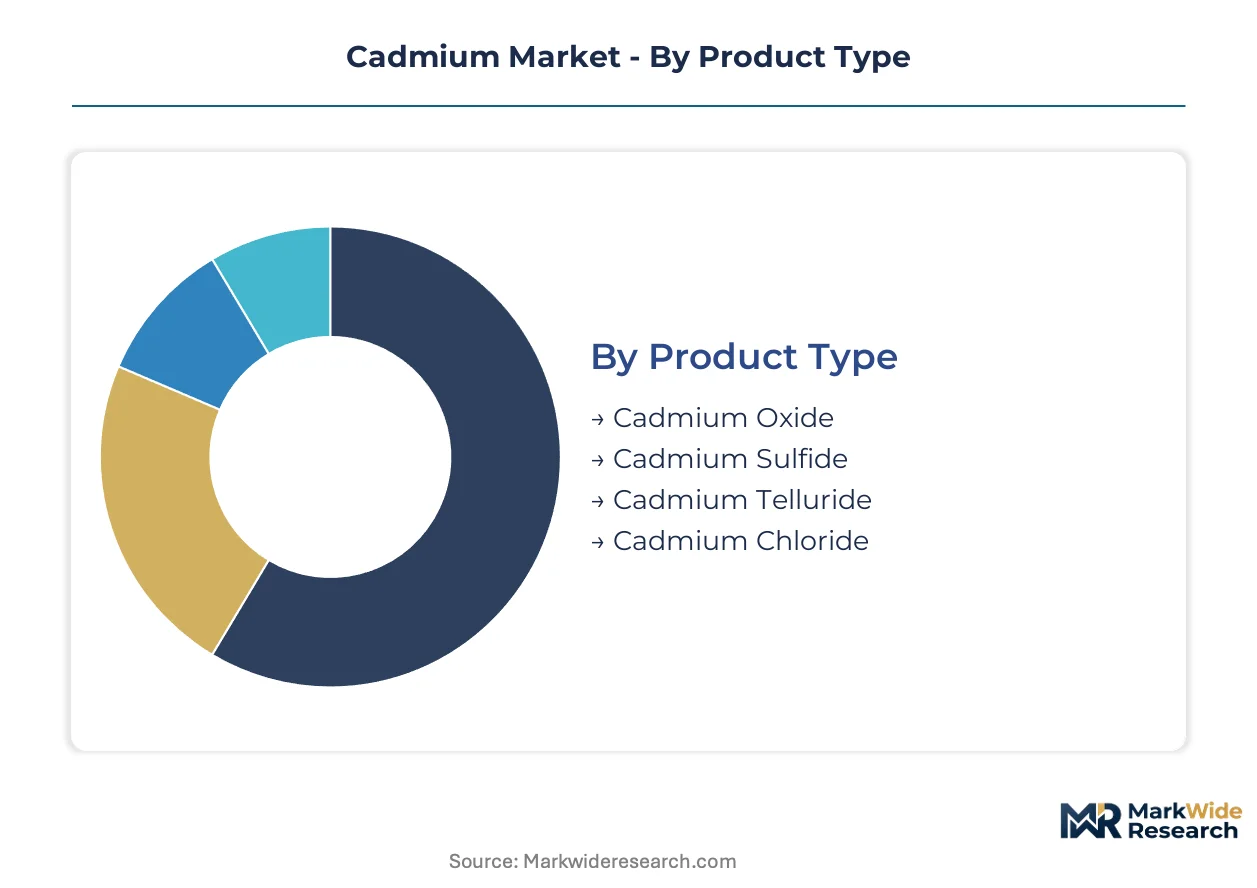
Cadmium's toxicological profile forces rigid specification tiers across product categories, while REACH and EPA regulations fragment addressable end-use markets. Segmentation clarity separates compliant from non-compliant revenue streams.
Product Type:
Integration depth varies sharply: cadmium telluride sits in standalone photovoltaic modules, while cadmium oxide and chloride embed predominantly into battery electrode chemistries and process intermediates.
- Cadmium Telluride:Direct bandgap semiconductor compound with 1.5 eV absorption edge, deposited via close-space sublimation in thin-film solar modules. Utility-scale developers in Arizona and Malaysia prioritize this technology for desert installations where temperature coefficients outperform silicon. First Solar's manufacturing expansion anchors demand concentration.
- Cadmium Oxide:Brown-black crystalline powder serving as electrode additive in nickel-cadmium battery formulations, typically 99.99% purity for electrochemical grade. Korean battery OEMs specify oxide-derived active material for stationary backup systems under domestic closed-loop recycling mandates.
- Cadmium Sulfide:Yellow pigment intermediate facing structural decline under chromatic substitution pressure from organic alternatives.
- Cadmium Chloride:Process chemical for telluride module activation and battery electrolyte formulation, consumed captively by integrated manufacturers.
Volume placements concentrate in cadmium oxide; the faster expansion belongs to cadmium telluride.
Application:
Cost tier stratification separates commodity-scale battery material demand from premium-grade coating specifications and declining pigment volumes.
- Battery Manufacturing:Nickel-cadmium electrode fabrication consumes high-purity metal and oxide compounds for industrial motive and stationary backup applications. Korean and Japanese OEM procurement contracts now mandate recycled content minimums, restructuring supplier qualification toward RCRA-equivalent certified refiners.
- Coatings and Platings:Electrodeposited cadmium layers specified in aerospace and defense corrosion protection where salt-spray performance exceeds zinc alternatives. US military specifications preserve this niche against REACH-driven commercial elimination.
- Pigment Production:Sulfide and selenide colorants for plastics and ceramics, collapsing under ECHA authorization restrictions across EU consumer applications.
- Pharmaceuticals:Trace analytical standards and radiopharmaceutical precursors, negligible volume but maximum purity requirements.
Revenue concentration sits with battery manufacturing; coatings and platings deliver the steepest margin premiums.
End User:
Customer type fragmentation splits between specification-intensive defense contractors and price-sensitive industrial battery assemblers.
- Electronics:Semiconductor plating and thin-film deposition for precision connectors and photovoltaic backplanes. Indian PLI scheme incentives attract downstream processing investment for defense and semiconductor applications.
- Automotive:Limited to specialty vehicle starter batteries and aftermarket industrial equipment, bypassed by lithium-ion in passenger electric vehicles.
- Aerospace:Corrosion-resistant fastener coatings meeting AMS-QQ-P-416 specifications, sole-sourced to qualified plating shops.
- Healthcare:Diagnostic imaging equipment shielding and laboratory reagents, governed by FDA device regulations.
Electronics commands the broadest specification range; aerospace maintains the most rigid qualification barriers.
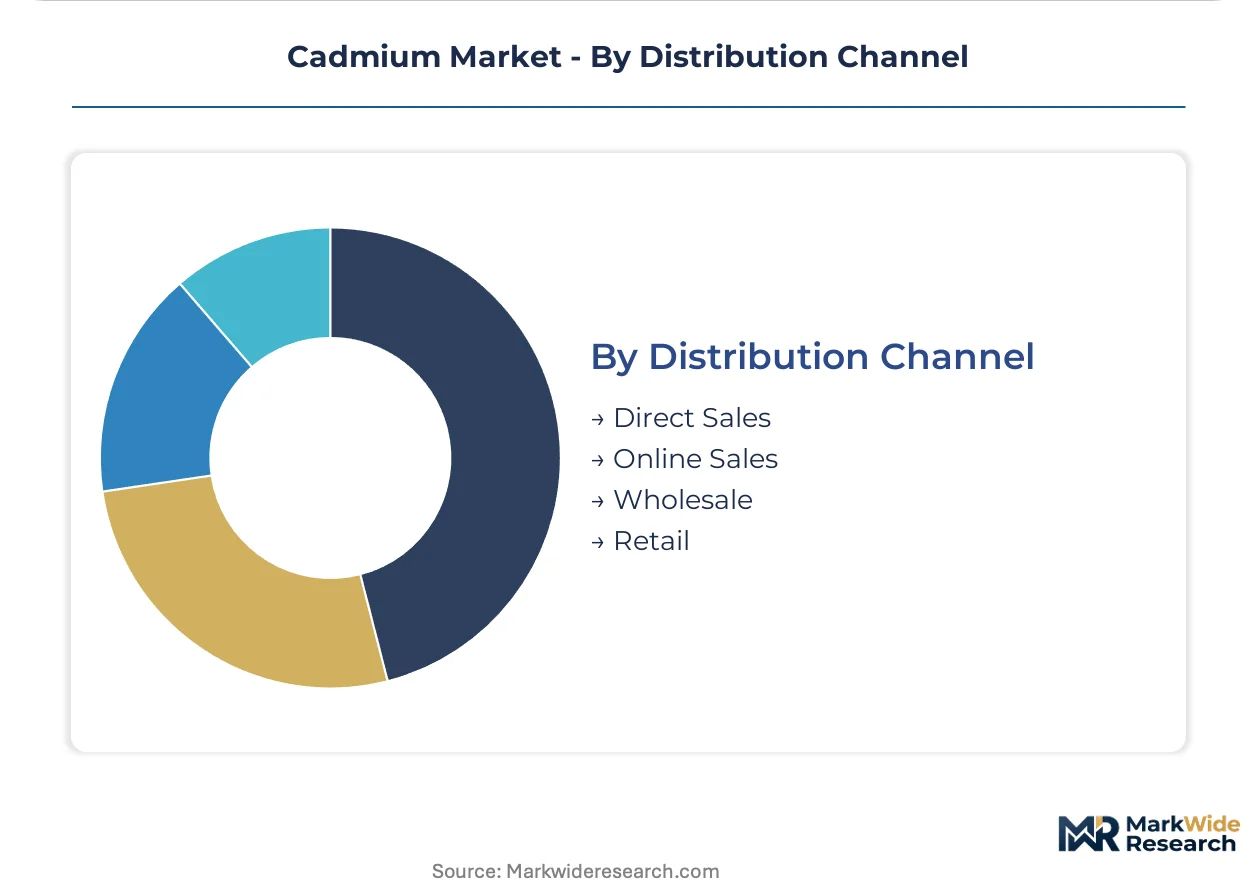
Distribution Channel:
Supply concentration shapes channel economics: captive smelter output flows direct, while spot-market metal requires certified intermediary handling.
- Direct Sales:Long-term offtake contracts from zinc-lead smelters to battery OEMs, decoupling spot pricing from actual consumption. Korea Zinc and Young Poong Corp anchor Korean domestic supply through concentrate sourcing control.
- Wholesale:Certified metal distributors serving plating shops and specialty chemical formulators with batch-lot traceability documentation.
- Online Sales:Laboratory reagent and analytical standard suppliers, minimal volume for cadmium given hazardous material shipping restrictions.
- Retail:Effectively eliminated for elemental cadmium under OSHA and EPA point-of-sale controls; pigment products only via professional trade channels.
Direct sales capture the dominant volume share; wholesale channels face margin compression from certification cost pass-through.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary cadmium smelting concentrates in Chinese and Korean zinc-lead complexes, while downstream processing for batteries and photovoltaics disperses across Korea, Japan, and India. Consumption patterns diverge sharply between industrial battery demand in Asia and defense-driven plating specifications in the United States.
China
Nickel-cadmium battery electrode demand and cadmium-telluride photovoltaic module production sustain offtake volumes from Hunan and Yunnan smelting clusters. MEE discharge standards enforce cadmium effluent limits below 0.05 mg per liter, forcing ion-exchange recovery retrofits at concentrate processing facilities. Zhuzhou Smelter Group anchors output from the central industrial corridor.
South Korea
Stationary backup power systems and industrial motive applications drive battery-grade cadmium consumption through domestic OEM procurement. Extended producer responsibility frameworks mandate closed-loop recycling minimums, restructuring supplier qualification toward RCRA-equivalent certified refiners. Korea Zinc and Young Poong Corp concentrate smelting capacity in the southeast metallurgical belt.
Japan
Advanced hydrometallurgical refining capabilities support premium-grade cadmium output for aerospace plating and semiconductor applications. METI industrial policy incentivizes battery recycling infrastructure investment. Dowa Metals and Mining and JX Advanced Metals Corporation occupy positions within the Kansai and Chubu processing corridors.
United States
Defense electronics and aerospace fastener specifications preserve premium-grade cadmium plating demand against REACH-driven commercial elimination. EPA RCRA hazardous waste standards and OSHA exposure limits shape handling protocols for battery recyclers. First Solar's Arizona manufacturing complex anchors cadmium-telluride photovoltaic deployment for utility-scale desert installations.
India
Electronics manufacturing incentives under PLI schemes attract downstream refining investment for defense and semiconductor applications. BIS standards govern cadmium content in imported battery assemblies. Processing capacity concentrates in Gujarat and Maharashtra industrial corridors serving domestic electronics OEMs.
Cadmium Market Vendor Landscape
Capital-heavy zinc-lead smelters compete with specialized hydrometallurgical refiners across the cadmium value chain. Market structure consolidates around integrated base metals producers with captive byproduct recovery, while independent refiners occupy niche premium-grade segments. Three archetypes dominate: integrated zinc smelters with captive cadmium output, advanced hydrometallurgical specialists, and battery-chemistry-integrated processors. Competitive positioning depends on concentrate sourcing control and recycling certification compliance rather than scale alone.
Among Korean and Japanese processors, Korea Zinc, Young Poong Corp, and Dowa Metals and Mining exemplify the integrated smelter archetype with captive byproduct recovery from zinc-lead circuits. These entities represent the concentration of primary refining capacity and closed-loop recycling infrastructure. Zhuzhou Smelter Group and Huludao Zinc Industry occupy corresponding positions within Chinese metallurgical clusters. Nyrstar NV and Teck Resources Ltd. anchor Western hemisphere output from European and North American zinc complexes respectively.
| Leading Market Players |
|---|
| Young Poong Corp |
| Huludao Zinc Industry |
| Korea Zinc |
| Dowa Metals and Mining |
| Mitsui Mining and Smelting |
| Nyrstar NV |
| Zhuzhou Smelter Group |
| JX Advanced Metals Corporation |
| Teck Resources Ltd. |
| Others |
Supply Flow & Price Mechanics
Vacuum-deposited cadmium telluride thin-film manufacturing is displacing conventional electrowinning methods, compressing processing costs while concentrating supply among three integrated Korean and Chinese smelter complexes. This technology shift simultaneously reduces unit production economics and tightens procurement options for battery-grade oxide buyers.
Pricing Analysis
Cost compression in battery-grade oxide reflects Korean OEM procurement contracts mandating recycled content minimums, squeezing spot market liquidity for uncertified Chinese output. Three-tier pricing structure across aerospace plating, battery electrode, and pigment grades separates premium AMS-QQ-P-416 certified metal from standard electrochemical grade and declining sulfide colorant tiers. Price differentiation hinges on RCRA-equivalent certification status and volume scale in long-term offtake agreements. Industrial battery assemblers exhibit highest price sensitivity; defense contractors accept steep premiums for qualified fastener coatings.
Supply Chain Analysis
Single-source vulnerability sits with Chinese zinc-lead smelting clusters in Hunan and Yunnan provinces, where MEE discharge enforcement controls global byproduct cadmium flows. Raw material dependencies center on zinc concentrate feedstock, sulfuric acid leaching circuits, and ion-exchange recovery resins. Supply chain risk manifests as regulatory restriction exposure from REACH authorization friction and EPA RCRA hazardous waste compliance timelines. Distribution runs through direct smelter-to-OEM contracts for battery manufacturers, with wholesale channels serving certified plating shops and specialty chemical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in cadmium is accelerating into a vertical-integration race, with concentrate sourcing control and closed-loop recycling infrastructure emerging as the decisive upstream levers.
For Market Incumbents: Extend hydrometallurgical refining capabilities to capture battery OEM recycled content mandates before certification bottlenecks harden. Korea Zinc and Young Poong Corp should deepen captive concentrate sourcing through zinc-lead complex expansion in the Korean southeast metallurgical belt. Lithium-ion substitution in portable electronics threatens nickel-cadmium volume; defense electronics plating specifications offer defensive moat preservation. For New Entrants and Emerging Players: PLI scheme incentives in India open a window for downstream processing investment targeting defense and semiconductor plating applications. White-space concentration sits in Gujarat and Maharashtra industrial corridors, where BIS standards create import substitution opportunities for battery-grade oxide. Go-to-market positioning should anchor on RCRA-equivalent certification acquisition to qualify for Korean and Japanese OEM vendor panels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated base metals producers seeking captive byproduct recovery. Long-term viability framing favors hydrometallurgical specialists with ion-exchange expertise and established recycling certifications over commodity-scale electrowinning operations. The signal to watch is cadmium-telluride tandem cell architecture commercialization, which would re-rate photovoltaic demand assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Concentrate Sourcing | Korea Zinc's concentrate control secures captive cadmium byproduct flows against Chinese supply disruption. |
| Hydrometallurgical Circuit Retrofit | Ion-exchange recovery system investment at Hunan smelters satisfies MEE effluent limits below 0.05 mg per liter. |
| RCRA-Equivalent Certification Acquisition | Korean battery OEM procurement contracts now mandate recycled content minimums, restructuring supplier qualification. |
| Cadmium-Telluride Tandem Cell Development | Perovskite integration research at First Solar and Chinese manufacturers opens next-generation photovoltaic efficiency pathways. |
| Indian Downstream Processing Expansion | PLI scheme incentives attract refining investment for defense electronics and semiconductor plating applications. |
Methodological Framework
Independent corroboration across primary interviews with zinc smelter operations managers, battery OEM procurement leads, and aerospace plating shop technical directors, combined with secondary validation from MEE discharge filings, Korean EPA recycling mandates, and SEC 10-K disclosures from integrated base metals producers, underwrites the qualitative findings. Bottom-up triangulation of smelter output capacities and top-down demand segmentation across battery, photovoltaic, and defense applications anchor volume estimates.
Rate-of-change decomposition across the analysis window separates volume growth in cadmium telluride photovoltaics from structural decline in pigment applications. Segmentation dimensions modeled include product type tier, application grade specification, end-user industry, and regional regulatory cluster. CAGRs derive from fitted growth curves against historical zinc-cadmium recovery ratios and projected nickel-cadmium battery deployment in stationary backup systems. Forecast inputs incorporate MEE enforcement timelines and Korean extended producer responsibility framework implementation.
The model assumes a particular technology adoption path; alternative pathways for cadmium-telluride tandem cell architectures would alter the outlook. Forecasts reflect assumptions regarding REACH authorization friction persistence and lithium-ion substitution rates in industrial motive applications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
Europe Silicon Carbide Market
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
ITO Nanoparticles Market
Semiconductor Material
Transparent Conductive Films Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Wet Chemicals for Electronics and Semiconductor Application Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Global Semiconductor Microelectronics Materials Market
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Silicon Base Paper Market