
 France Indoor LED Lighting Market | 2026-2036
France Indoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
France Indoor LED Lighting Market Insights
Specifiers' procurement channels is tilting toward integrated solution providers rather than component distributors. Signify (Philips) leverages its connected lighting platforms to anchor large-scale commercial contracts across French metropolitan areas. Schneider Electric SE controls building automation integration points, extending its influence over specification decisions in new construction. ams-OSRAM AG specializes in LED chip and module supply, sustaining its position upstream of fixture assembly.
France Indoor LED Lighting comprises solid-state luminaires utilizing semiconductor diodes with typical efficacy exceeding 100 lumens per watt, designed for enclosed interior environments where thermal management and color rendering index above 80 define performance thresholds. Panel lights and downlights dominate volume in commercial retrofit applications where uniform illumination and recessed integration matter most. Smart lighting technology captures expanding specification share as IoT-enabled control systems merge occupancy sensing with daylight harvesting protocols. Tunable white systems lead margin pools in hospitality and educational end-user segments where circadian lighting design influences wellness certification outcomes.
France's RE2020 regulation, CE marking requirements under EU Ecodesign directives, and ANSM/CNIL data governance standards for connected fixtures collectively reshape product compliance and data handling obligations. These frameworks mandate minimum efficacy thresholds and impose cybersecurity protocols on networked lighting infrastructure. Stakeholders must weigh retrofit timing against evolving efficiency benchmarks and interoperability standards before committing capital to multi-site rollouts.
Market Dynamics
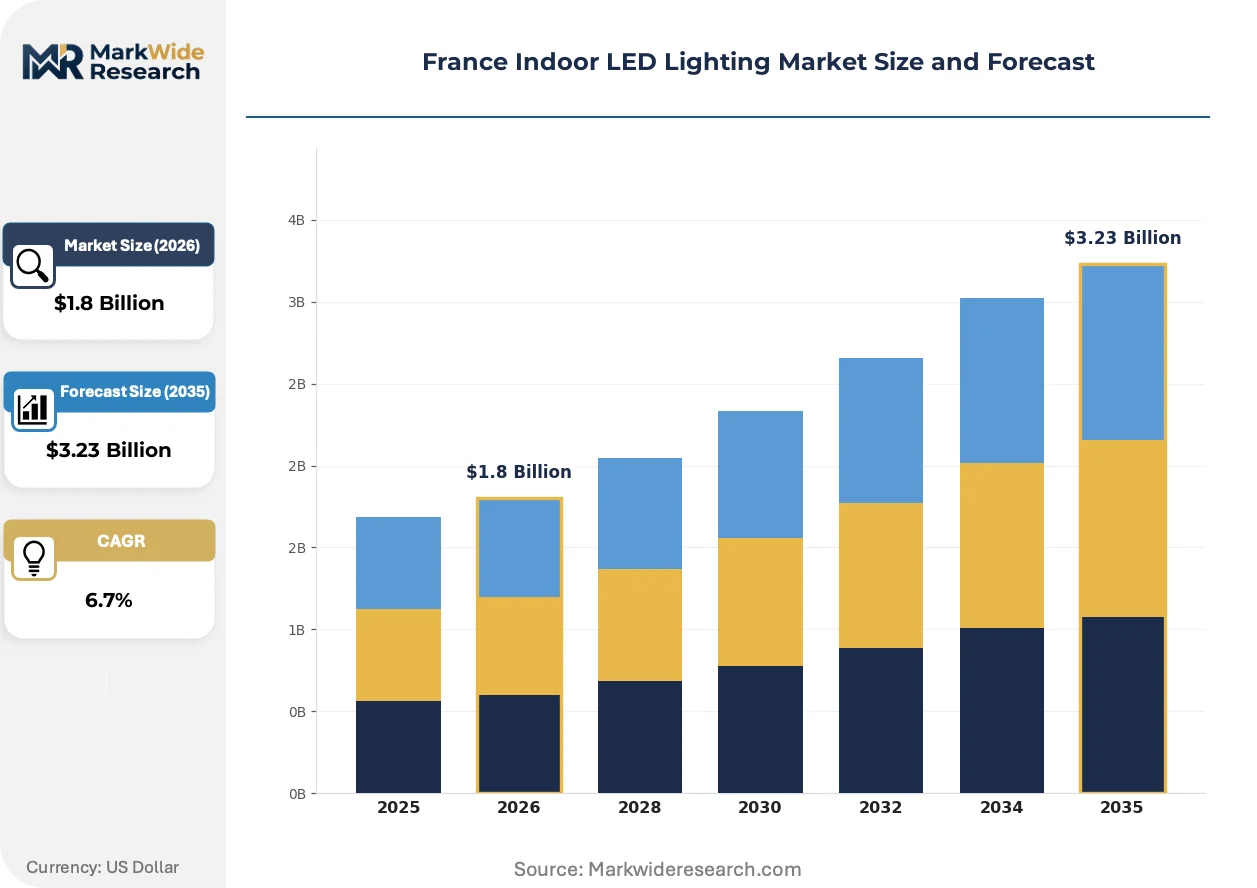
France's RE2020 environmental regulation is compressing replacement cycles across the commercial building stock, forcing specifiers to front-load capital expenditure into higher-efficacy fixtures before compliance deadlines harden. This regulatory pressure is reshaping procurement calendars and vendor selection criteria simultaneously.
Growth Catalysts
- RE2020 Mandates:France's building energy performance regulation requires all new construction and major renovations to meet stringent thermal and lighting efficacy thresholds, accelerating fixture replacement in Greater Paris office stock.
- Smart City Infrastructure:Ile-de-France regional authorities are bundling LED retrofits with IoT sensor networks, creating integrated procurement opportunities for connected lighting platforms.
- Circadian Wellness Certification:Hospitality and educational end-users are specifying tunable white systems to secure WELL Building Standard credits, expanding premium product demand beyond traditional efficiency metrics.
Market Restraints
- Upstream Chip Concentration:LED die and phosphor supply concentrates among Asian semiconductor foundries, exposing French fixture assemblers to input cost volatility and extended lead times.
- Technical Interoperability Gaps:Proprietary communication protocols between building automation systems and lighting controls create integration friction, delaying multi-site rollout decisions.
- Substitution from Natural Daylighting:Advanced building envelope designs and light-well configurations in new construction projects reduce aggregate luminaire density per square meter.
Strategic Opportunities
- Underpenetrated Secondary Cities:Lyon, Marseille, and Toulouse municipal retrofit programs lag Paris adoption curves by three to five years, offering first-mover positioning for integrated solution providers.
- Human-Centric Lighting Convergence:The intersection of tunable white technology with occupancy analytics enables wellness-focused service contracts in healthcare and senior living facilities.
- EU Green Deal Financing:Recovery and Resilience Facility subsidies for building decarbonization lower effective retrofit costs for public sector anchor tenants, expanding addressable project scale.
Industry Challenges
- Cybersecurity Compliance Burden:ANSM and CNIL data governance standards for connected fixtures impose encryption and data-localization requirements that extend product development timelines.
- Legacy System Integration Complexity:Deep replacement of fluorescent infrastructure in 1990s-era commercial stock requires simultaneous ballast bypass and control rewiring, inflating installed cost per point.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Indoor LED Lighting Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Lights, Downlights, Bulbs, Track Lights Technology: Dimmable, Smart Lighting, RGB, Tunable White End User: Residential, Commercial, Hospitality, Educational Control System: Manual, Remote, Automated, IoT-Enabled |
| Companies Covered | EGLO Leuchten GmbH, Airis LED, Signify (Philips), CisLED, BEGA Lighting, ams-OSRAM AG, Thorn Lighting Ltd (Zumtobel Group), Schneider Electric SE, LEDVANCE GmbH (MLS Co Ltd), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Indoor LED Lighting Market Trends and Innovations
Lighting control architecture is migrating from standalone systems toward embedded building management nodes, compressing the traditional separation between illumination and HVAC optimization. This convergence is redrawing competitive boundaries and procurement specifications.
LiFi optical wireless communication is hybridizing LED infrastructure into dual-purpose data transmission networks. Corporate campuses in La Défense and Bordeaux are piloting luminaire-integrated broadband as an electromagnetic-interference-free alternative to WiFi in sensitive manufacturing environments. The technology is hybridizing fixture specification criteria to include bandwidth density and latency benchmarks alongside traditional photometric performance.
France's transposition of EU Ecodesign directives into national law is tightening minimum efficacy thresholds for linear and downlight categories. Manufacturers must now certify products through accredited laboratories under accelerated timelines, compressing product refresh cycles. The commercial retrofit segment is responding by consolidating vendor relationships to reduce re-certification overhead.
Building operators are unbundling lighting maintenance from capital purchase contracts, shifting toward performance-guarantee agreements where providers retain ownership of installed assets. Facility management consortiums in Lyon and Nantes are pioneering this model, transferring technology obsolescence risk upstream. The education and healthcare verticals show strongest appetite for this arrangement, driven by constrained operational budgets and extended holding periods.
France Indoor LED Lighting Market Segmentation
France Indoor LED Lighting Market segmentation reflects divergent technical requirements across retrofit versus new construction contexts. Specifiers navigate efficacy mandates, connectivity protocols, and wellness certification criteria that reshape procurement priorities by installation type.
Product Type:
Commercial retrofit programs in Ile-de-France offices and hospitality venues drive specification diversity across form factors.
- Panel Lights:Edge-lit and back-lit flat panel configurations deliver uniform illumination through diffuser arrays with typical efficacy exceeding 120 lumens per watt. Demand concentrates in Greater Paris commercial office retrofits where RE2020 compliance deadlines accelerate fixture replacement cycles ahead of major renovation permits.
- Downlights:Recessed ceiling-mounted luminaires integrate thermal management systems to maintain color stability across operating temperatures. Hospitality operators in Lyon and Marseille specify premium COB downlights for lobby and corridor applications where beam control and dimming performance influence guest experience ratings.
- Bulbs:Retrofit lamp formats serve residential replacement demand and legacy socket compatibility in municipal buildings.
- Track Lights:Adjustable directional luminaires dominate retail and gallery applications requiring flexible accent illumination.
The dominant share belongs to Panel Lights, while Downlights is closing the gap fastest.
Technology:
Control sophistication separates cost tiers, with premium segments commanding specification in wellness-focused verticals.
- Smart Lighting:Networked luminaires embedding occupancy sensors, daylight harvesting algorithms, and API-accessible control interfaces. Ile-de-France smart city infrastructure bundles specify these systems for municipal buildings where ANSM data governance standards mandate encrypted local processing of sensor telemetry.
- Tunable White:CCT-adjustable systems spanning 2700K to 6500K with independent dimming channels. Educational institutions in Nantes and Toulouse deploy these for circadian lighting designs targeting WELL Building Standard certification and student performance optimization studies.
- Dimmable:Phase-cut and 0-10V control compatibility serving cost-sensitive retrofit applications.
- RGB:Multi-channel color mixing for experiential and architectural accent applications.
Smart Lighting holds the installed base advantage, though Tunable White is expanding most quickly in healthcare and education specifications.
End User:
Budget cycles and compliance exposure create distinct procurement behaviors across building ownership structures.
- Commercial:Corporate office portfolios and multi-tenant buildings where RE2020 renovation triggers mandate high-efficacy replacement. Greater Paris lease rollover schedules synchronize capital planning with regulatory deadlines.
- Hospitality:Hotels and restaurant groups specifying aesthetic performance alongside operational efficiency. Boutique properties in Bordeaux and Strasbourg prioritize tunable systems for guest room wellness differentiation.
- Residential:Single-family and multi-unit housing driven by retail replacement and new construction installation.
- Educational:Public and private school districts with extended holding periods and constrained maintenance budgets.
Commercial commands volume leadership, with Hospitality generating the steepest margin expansion trajectory.
Control System:
Integration depth with building automation platforms determines specification tier and vendor selection criteria.
- IoT-Enabled:Cloud-connected luminaires with edge computing capability and open protocol support. La Défense corporate campuses pilot these for LiFi data transmission and real-time space utilization analytics.
- Automated:Standalone sensor-driven systems with local control logic and BACnet integration.
- Remote:Wireless handheld or app-based dimming for flexible zone management.
- Manual:Wall-switch and basic dimmer configurations serving lowest-cost residential and small commercial applications.
IoT-Enabled systems anchor premium project value, while Automated controls are gaining specification share fastest in mid-market commercial retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France commands pricing premiums that secondary French regions cannot replicate, creating a two-tier procurement landscape where Paris Basin projects absorb connected lighting platforms while peripheral markets remain fixated on basic efficacy compliance.
Île-de-France
Greater Paris commercial office retrofits and smart city infrastructure bundles concentrate specification demand for IoT-enabled systems. ANSM and CNIL data governance standards for connected fixtures reshape vendor qualification requirements across municipal procurement. La Défense corporate campuses pilot LiFi optical wireless integration alongside traditional illumination functions.
Auvergne-Rhône-Alpes
Lyon municipal retrofit programs lag Paris adoption curves by three to five years, offering first-mover positioning for integrated solution providers. RE2020 renovation triggers in commercial building stock accelerate fixture replacement ahead of permit deadlines. Facility management consortiums pioneer performance-guarantee agreements transferring technology obsolescence risk upstream.
Provence-Alpes-Côte d'Azur
Marseille hospitality operators specify premium COB downlights for lobby and corridor applications where beam control influences guest experience ratings. EU Green Deal Recovery and Resilience Facility subsidies lower effective retrofit costs for public sector anchor tenants. Boutique properties prioritize tunable systems for wellness differentiation in competitive coastal markets.
Nouvelle-Aquitaine
Bordeaux educational institutions deploy tunable white systems for circadian lighting designs targeting WELL Building Standard certification. Regional authorities bundle LED retrofits with building automation integration in school district modernization programs. Student performance optimization studies drive specification beyond traditional efficiency metrics.
Occitanie
Toulouse municipal retrofit programs accelerate as RE2020 compliance deadlines harden across 1990s-era commercial stock. Deep replacement of fluorescent infrastructure requires simultaneous ballast bypass and control rewiring, inflating installed cost per point. Healthcare and senior living facilities show strongest appetite for human-centric lighting convergence with occupancy analytics.
France Indoor LED Lighting Market Competitive Landscape
Connected platform providers and component specialists split the market along the value chain integration axis. The vendor base concentrates around three strategic archetypes: multinational lighting platforms with building automation integration capability, European semiconductor and module suppliers controlling upstream LED die supply, and regional fixture assemblers serving cost-sensitive retrofit channels. Dominant competitive moves include strategic partnerships between platform providers and building management system vendors, plus portfolio diversification into wellness-certified tunable white systems.
Within the multinational platform tier, Signify and Schneider Electric SE exemplify divergent approaches to specification influence—Signify anchoring connected lighting platforms while Schneider Electric SE controls building automation integration points. ams-OSRAM AG occupies the upstream specialist position, supplying LED chip and module components to downstream fixture assemblers. These three entities represent the core competitive tension between integrated solution provision and component supply specialization.
| Leading Market Players |
|---|
| EGLO Leuchten GmbH |
| Airis LED |
| Signify (Philips) |
| CisLED |
| BEGA Lighting |
| ams-OSRAM AG |
| Thorn Lighting Ltd (Zumtobel Group) |
| Schneider Electric SE |
| LEDVANCE GmbH (MLS Co Ltd) |
| Others |
Pricing and Supply Chain Analysis
Dongguan and Shenzhen LED packaging clusters dictate cost trajectories for French fixture assemblers, with capacity utilization swings in these southern China hubs transmitting directly into module pricing power for European distributors. This geographic concentration compresses margin recovery timelines when input costs spike.
Pricing Analysis
Configured-to-order pricing for tunable white and LiFi-enabled systems commands spreads of 40-60 percent above standard panel light SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because Asian semiconductor foundries are prioritizing automotive and display allocations. Municipal procurement offices exhibit highest price sensitivity, while La Défense corporate campuses show lowest sensitivity due to wellness certification requirements.
Supply Chain Analysis
Hon Hai Precision, Luxshare, and other EMS providers in southern China and Vietnam hold dominant contract manufacturing capacity for LED module assembly. Die supply concentrates in Taiwan, South Korea, and China, while phosphor and substrate materials draw from Japanese and German specialty chemical producers. Single-source vulnerability in advanced LED die creates exposure to allocation decisions by upstream foundries. Distribution runs through integrated solution providers rather than component distributors, compressing traditional wholesale margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France Indoor LED Lighting is entering a cyclical recovery phase as RE2020 renovation triggers synchronize with EU Green Deal subsidy disbursement cycles, compressing replacement timelines across commercial building stock.
For Market Incumbents: Pre-empt margin erosion in standard panel categories by anchoring building automation integration points before Schneider Electric SE consolidates control layer specifications. Prioritize backward integration into LED module assembly to reduce exposure to Asian foundry allocation decisions. Defend specification influence in Ile-de-France municipal procurement by pre-certifying products under ANSM cybersecurity protocols ahead of compliance deadline hardening. For New Entrants and Emerging Players: Build out presence in Lyon, Marseille, and Toulouse municipal retrofit programs where integrated solution provider coverage remains thin. Target healthcare and senior living facilities for human-centric lighting service contracts, leveraging wellness certification gaps left by incumbent platform providers. Lead with performance-guarantee agreements that transfer technology obsolescence risk upstream, matching facility management consortium appetite in Auvergne-Rhône-Alpes. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with dormant lighting divisions lacking IoT platform connectivity. Five-to-ten year viability hinges on control layer software capabilities rather than fixture manufacturing scale. Monitor specification share shifts in La Défense corporate pilot programs as early indicator of which connected platforms achieve enterprise standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Building Automation | Schneider Electric SE's control layer dominance forces lighting vendors to embed BACnet and API compatibility as table stakes. |
| LiFi Optical Wireless Deployment | La Défense and Bordeaux pilots validate luminaire-integrated broadband as electromagnetic-interference-free alternative in sensitive environments. |
| Performance-Guarantee Contract Structuring | Lyon and Nantes facility management consortiums transfer technology obsolescence risk upstream through asset-retention models. |
| ANSM Cybersecurity Pre-Certification | Early compliance with data localization and encryption mandates secures municipal procurement eligibility ahead of deadline enforcement. |
| Tunable White Wellness Certification | WELL Building Standard credits drive premium specification in Bordeaux hospitality and Strasbourg educational verticals. |
Research Methodology
A standing panel of lighting specification engineers, facility management directors, municipal procurement officers, and building automation integrators provided ongoing calibration against field conditions. Primary interviews with these stakeholders combined with secondary validation through EU Ecodesign directive filings, ANSM cybersecurity guidance documents, and Ile-de-France regional infrastructure budgets. Bottom-up project pipeline analysis triangulated against top-down regulatory mandate tracking.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling across product type, technology tier, end-user vertical, and control system integration depth. CAGRs derived from installation volume trajectories weighted by regulatory deadline clustering and subsidy disbursement schedules. RE2020 permit approval data and Recovery and Resilience Facility obligation tracking supplied industry-specific forecast inputs.
Stress conditions across semiconductor allocation cycles, tariff exposure on Asian module imports, and municipal budget freeze scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and interoperability standard convergence. Quarterly review of RE2020 permit issuance rates and connected fixture specification share in Greater Paris municipal tenders is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Micro LED Display Market
LED
UK LED Lighting Market
LED
China Outdoor LED Lighting Market
LED
North America Commercial LED Lighting Market
LED
India Indoor LED Lighting Market
LED
LED and OLED Display Market
LED
LED Modules and Light Engines Market
LED
LED Lighting Controllers Market
LED
Monochrome Outdoor LED Display Market
LED
LED Flip Chip Market
LED
Led Video Walls Market
LED
Japan Outdoor LED Lighting Market
LED
LED Street Light Drivers Market
LED
LED Tube Market
LED
LED Panel Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market