
 5G Substrate Materials Market | 2026-2036
5G Substrate Materials Market Size, Share, and Industry Trends Forecast 2026-2036
5G Substrate Materials Market Analysis
UL 94 V-0 flame retardancy certification is reorganizing the competitive landscape for 5G substrate materials, as base station OEMs restrict qualified supplier lists to vendors meeting stringent fire safety and dielectric performance benchmarks. Rogers Corporation leverages its vertically integrated fluoropolymer resin operations to sustain premium positioning in PTFE-based laminates for millimeter-wave applications. Showa Denko Materials anchors Japanese supply security through captive alumina ceramic substrate capacity serving domestic telecom equipment manufacturers.
5G substrate materials comprise engineered laminates and ceramics engineered to transmit high-frequency signals with minimal dielectric loss, typically achieving dissipation factors below 0.002 at 28 GHz and thermal conductivities exceeding 1.5 W/m·K for thermal management in dense antenna arrays. Ceramic substrates dominate base station power amplifier modules where thermal dissipation requirements are most severe, while liquid crystal polymer films capture growing share in flexible antenna-in-package designs for smartphone mmWave modules. PTFE laminates retain margin concentration in radar and backhaul applications demanding the lowest signal attenuation across extended operational temperatures.
FCC Part 27 spectrum allocation rules in the United States and the EU Radio Equipment Directive's harmonized frequency access standards are mandating substrate performance verification across widened mmWave bands, compressing product development cycles for unqualified suppliers. Japan's METI and China's MIIT are each enforcing localized content thresholds in public 5G infrastructure tenders, fragmenting procurement patterns by geography. Stakeholders must monitor evolving substrate qualification protocols tied to Open RAN interoperability standards and country-specific supplier certification registries.
Market Dynamics
Millimeter-wave base station deployments are compressing substrate qualification timelines as telecom OEMs demand dielectric performance verification across 24-47 GHz bands before supplier onboarding.
Growth Catalysts
- Open RAN Interoperability Standards:Disaggregation of radio access networks is creating entry points for specialized substrate vendors who previously faced exclusion from integrated supplier lists.
- South Korea Telecom Infrastructure Buildouts:Government-backed 5G spectrum auctions are accelerating consumption of low-loss laminates for dense urban small cell networks.
- Japan METI Subsidy Frameworks:Domestic semiconductor supply chain incentives are redirecting procurement toward local ceramic substrate manufacturers serving NTT Docomo and KDDI.
Market Restraints
- Fluoropolymer Feedstock Concentration:PTFE resin supply concentrates among three chemical conglomerates, exposing laminate producers to input cost volatility and allocation constraints.
- UL 94 V-0 Certification Barriers:Flame retardancy testing protocols extend qualification cycles to 18-24 months, freezing out capital-constrained entrants from base station OEM approved vendor lists.
- Thermal Management Trade-offs:Ceramic substrates achieving thermal conductivity above 3 W/m·K sacrifice dielectric performance, limiting deployment in dual-function power amplifier and antenna modules.
Strategic Opportunities
- Antenna-in-Package Flexible Modules:Liquid crystal polymer films are capturing design wins in smartphone mmWave arrays where bend radius requirements exclude rigid ceramic alternatives.
- Germany Industrial 5G Private Networks:Manufacturing automation deployments at BASF and Siemens facilities are generating demand for ruggedized substrates in non-consumer frequency bands.
- China MIIT Localized Content Thresholds:Public infrastructure tenders mandate domestic substrate sourcing, creating captive demand for qualified Chinese laminate and ceramic producers.
Industry Challenges
- Electromagnetic Simulation Talent Scarcity:Full-wave modeling expertise for mmWave substrate design concentrates among aging specialists in Japan and the United States, constraining product development velocity.
- Multi-Physics Certification Complexity:Simultaneous UL, FCC Part 27, and EU Radio Equipment Directive compliance requires parallel testing tracks that strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Substrate Materials Market |
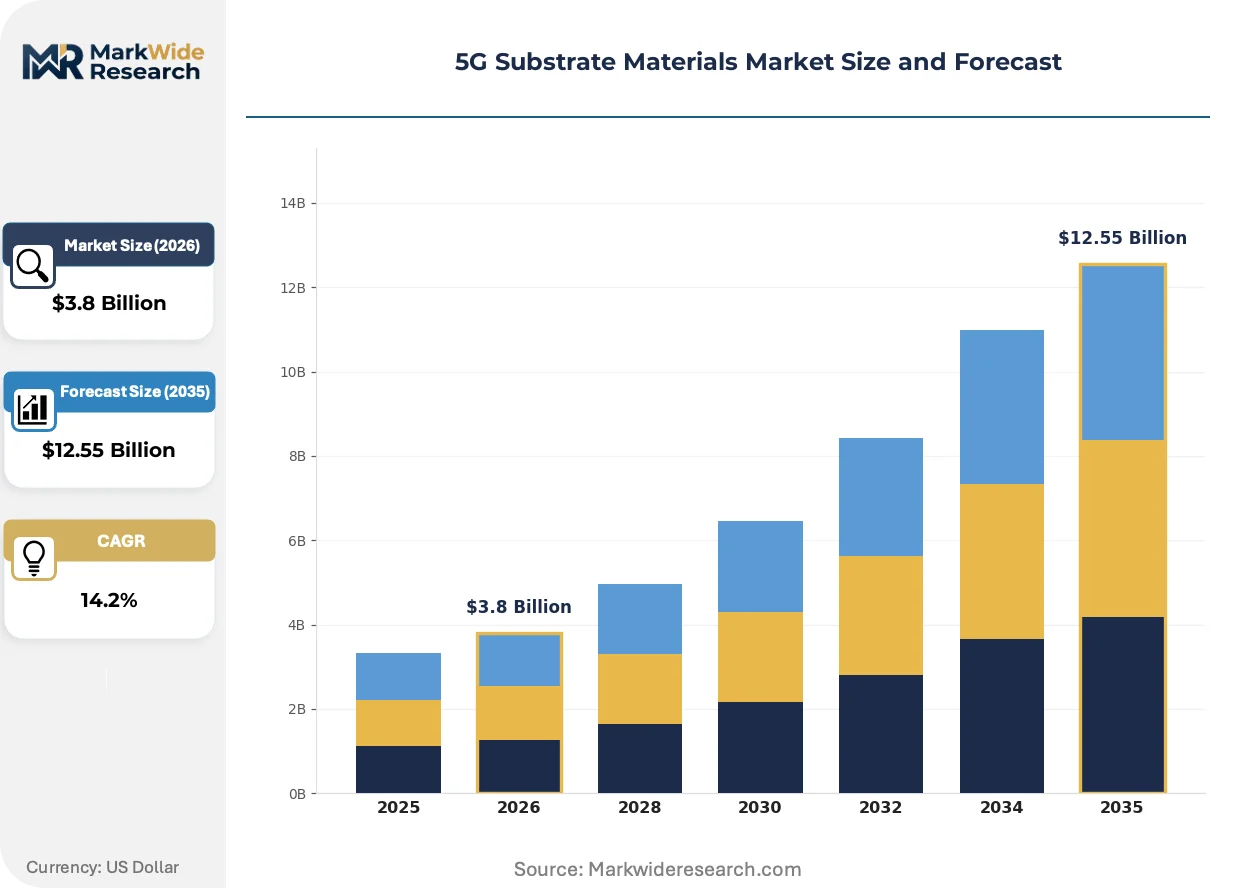
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Ceramic, PTFE, Polyimide, Liquid Crystal Polymer Application: Telecommunications, Consumer Electronics, Automotive, IoT Devices End User: Telecom Operators, Device Manufacturers, Automotive OEMs, Research Institutions Form Factor: Flexible, Rigid, Hybrid, Microstrip |
| Companies Covered | ITEQ Corporation, Rogers Corporation, Showa Denko Materials Co., Ltd., Taiwan Union Technology Corporation, Panasonic Corporation, DuPont de Nemours, Inc., Kaneka Corporation, Kuraray Co., Ltd., AGC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Substrate Materials Market Emerging Trajectories
Substrate architectures are bifurcating between thermal-first ceramic formulations for base station power amplifiers and signal-first polymer laminates for consumer device antennas.
Liquid crystal polymer substrates are miniaturizing antenna-in-package modules for smartphone mmWave arrays. Apple and Samsung procurement teams have accelerated design-in cycles from 24 months to 14 months for 2024-2025 handset generations. This compression is miniaturizing module footprints below 3mm thickness while maintaining sub-0.003 dissipation factors at 28 GHz.
FCC Part 27 spectrum allocation rules in the United States are mandating substrate performance documentation across widened mmWave bands. Base station OEMs now require third-party test reports for 37-47 GHz operation before contract award. Suppliers without pre-qualified materials face 12-18 month exclusion from Verizon and T-Mobile infrastructure tenders.
Chinese state-owned carriers are consolidating substrate procurement through centralized MIIT qualification registries. Approved vendor lists have contracted from 47 suppliers in 2022 to 23 in 2024, concentrating volume among domestic ceramic and PTFE laminate specialists. Tier-2 equipment manufacturers now face binding sole-source requirements for public network deployments.
5G Substrate Materials Market Segmentation
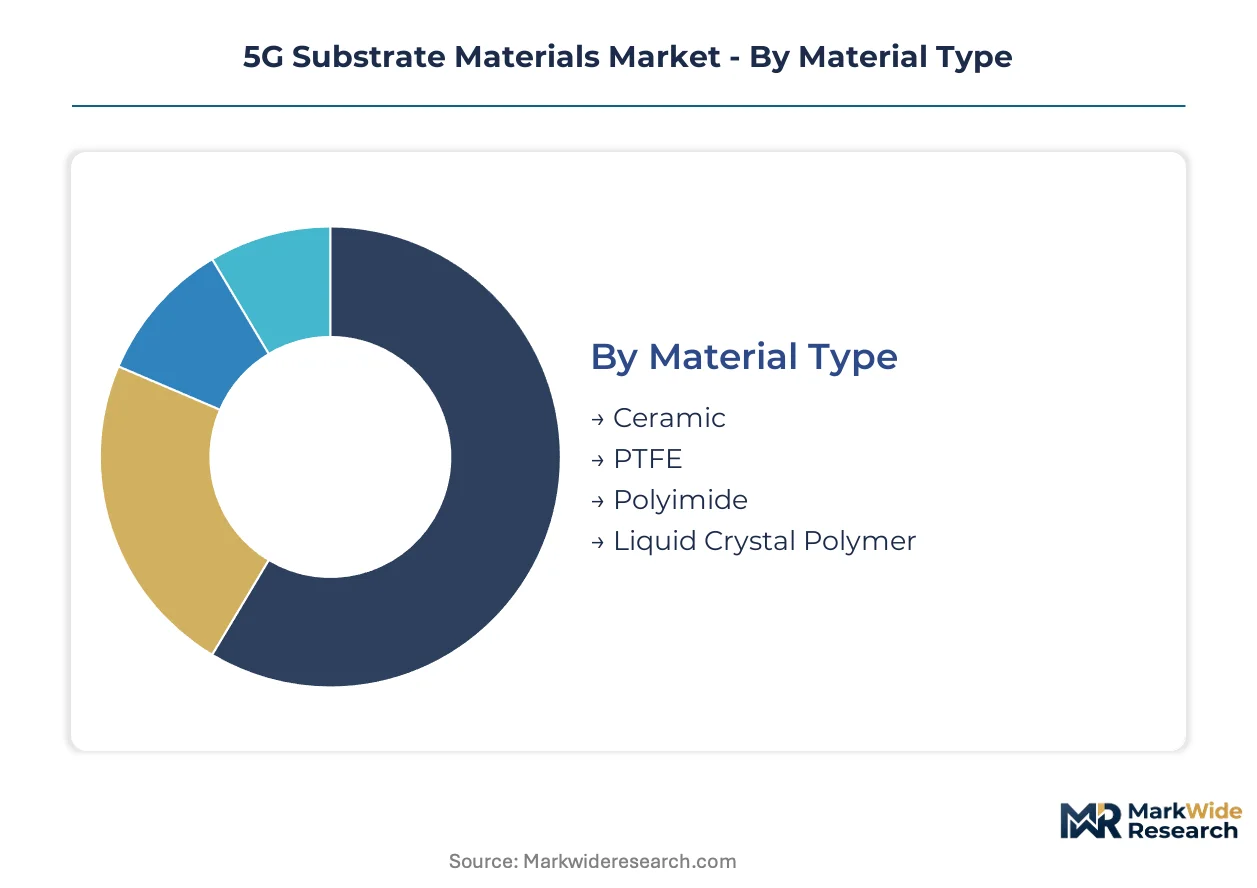
5G substrate materials fragment across four critical dimensions that determine pricing power and qualification barriers. Material chemistry governs thermal and dielectric performance ceilings. Application context dictates regulatory exposure and volume scalability.
Material Type:
Domestic production clusters in Japan and China supply ceramic and PTFE grades, while liquid crystal polymer films concentrate in South Korean and German export hubs.
- Ceramic:Alumina and aluminum nitride formulations achieve thermal conductivity above 3 W/m·K for base station power amplifier modules. Demand concentrates in China and Japan where MIIT and METI procurement rules favor domestic ceramic suppliers for public infrastructure tenders.
- PTFE:Fluoropolymer laminates deliver dissipation factors below 0.001 at 28 GHz through vertically integrated resin operations. Rogers Corporation and Taconic anchor North American supply for radar and backhaul applications demanding minimal signal attenuation across temperature extremes.
- Polyimide:High-temperature stability suits aerospace and military communications hardware with extended operational lifecycles.
- Liquid Crystal Polymer:Thermotropic films enable sub-3mm bend radius for smartphone antenna-in-package modules. Samsung and Apple procurement teams drive specification tightening for 2024-2025 handset generations.
Ceramic holds the largest share; momentum sits with liquid crystal polymer as flexible module designs displace rigid alternatives in consumer devices.
Application:
Cost tier stratification separates qualification-intensive telecommunications infrastructure from price-sensitive consumer electronics volumes.
- Telecommunications:Millimeter-wave base stations and small cell networks demand UL 94 V-0 certified substrates with verified performance across 24-47 GHz bands. Verizon and T-Mobile infrastructure tenders require third-party test documentation before contract award, compressing supplier onboarding timelines.
- Consumer Electronics:Smartphone mmWave modules prioritize miniaturization and bend radius over thermal performance. Design-in cycles have compressed from 24 months to 14 months, accelerating procurement velocity for qualified flexible substrate vendors.
- Automotive:V2X communication modules and autonomous driving sensor arrays require automotive-grade temperature cycling validation.
- IoT Devices:Low-power wide-area network hardware tolerates higher dissipation factors in exchange for cost minimization at scale.
Telecommunications commands premium pricing; consumer electronics delivers volume expansion.
End User:
Procurement concentration varies sharply between consolidated telecom operators and fragmented device manufacturing ecosystems.
- Telecom Operators:China Mobile, Verizon, and Deutsche Telekom centralize substrate qualification through approved vendor lists with binding sole-source requirements. Chinese state-owned carriers have consolidated procurement registries from 47 suppliers to 23, concentrating volume among domestic specialists.
- Device Manufacturers:Apple and Samsung procurement teams accelerate design-in cycles while tightening dissipation factor specifications. Module suppliers face dual pressure from OEM cost targets and substrate vendor minimum order quantities.
- Automotive OEMs:BMW and Tesla V2X programs require automotive-qualified laminates with extended temperature range validation.
- Research Institutions:National laboratories and university consortia drive early-stage material validation for next-generation frequency bands.
Telecom operators control infrastructure pricing; device manufacturers shape flexible substrate roadmaps.
Form Factor:
Manufacturing maturity separates established rigid substrate processes from emerging hybrid architectures.
- Flexible:Liquid crystal polymer and modified polyimide films enable antenna-in-package bending for smartphone mmWave arrays. South Korean laminate producers capture design wins through proximity to Samsung display and semiconductor operations.
- Rigid:Ceramic and PTFE laminates dominate base station power amplifiers where thermal dissipation requirements exclude polymer alternatives. Japanese suppliers anchor supply security through captive alumina capacity.
- Hybrid:Multi-layer constructions combine rigid thermal cores with flexible signal layers for complex module integration.
- Microstrip:Precision-etched transmission line structures serve phased array antennas with controlled impedance matching.
Rigid substrates retain revenue concentration; flexible formats climb fastest as smartphone mmWave penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaesong Industrial Complex rail link and Incheon Port container terminals underwrite South Korea's position as the primary logistics backbone for 5G substrate materials moving across Northeast Asia.
United States
Verizon and T-Mobile infrastructure tenders drive millimeter-wave base station deployments across the Sun Belt corridor. FCC Part 27 spectrum allocation rules mandate substrate performance documentation across 37-47 GHz bands. Phoenix and Dallas-Fort Worth host the densest concentrations of telecom equipment manufacturing campuses.
China
China Mobile and China Tower centralize procurement through MIIT qualification registries that consolidated approved vendor lists from 47 to 23 suppliers. The Yangtze River Delta anchors domestic ceramic substrate production for public network deployments. Shenzhen and Shanghai house the largest concentrations of flexible laminate module assembly.
Japan
NTT Docomo and KDDI procurement teams enforce localized content thresholds in 5G infrastructure tenders. METI subsidy frameworks redirect supply chain procurement toward domestic ceramic substrate manufacturers. Nagoya and Osaka host captive alumina production facilities serving telecom equipment makers.
Germany
BASF and Siemens manufacturing automation deployments generate demand for ruggedized substrates in industrial 5G private networks. EU Radio Equipment Directive harmonized frequency access standards compress product development cycles for unqualified suppliers. Munich and Stuttgart anchor the densest clusters of automotive-qualified laminate validation labs.
South Korea
Samsung procurement teams accelerate design-in cycles for smartphone mmWave antenna-in-package modules. Government-backed 5G spectrum auctions accelerate consumption of low-loss laminates for dense urban small cell networks. Suwon and Pyeongtaek host the largest concentrations of liquid crystal polymer film processing capacity.
5G Substrate Materials Market Vendor Landscape
Listed leaders compete with private specialists across certification-intensive substrate tiers. The vendor base concentrates among vertically integrated resin producers and captive ceramic manufacturers. Three archetypes dominate: fluoropolymer resin integrators, alumina ceramic specialists, and liquid crystal polymer film processors. Capacity expansion and strategic partnerships represent the dominant competitive vectors as qualification timelines compress.
Among North American laminate producers, Rogers Corporation exemplifies the fluoropolymer integration archetype. Taiwan Union Technology Corporation occupies a position within the high-frequency laminate tier. Showa Denko Materials Co., Ltd. anchors the ceramic substrate specialist segment through its Japanese manufacturing base.
| Leading Market Players |
|---|
| ITEQ Corporation |
| Rogers Corporation |
| Showa Denko Materials Co., Ltd. |
| Taiwan Union Technology Corporation |
| Panasonic Corporation |
| DuPont de Nemours, Inc. |
| Kaneka Corporation |
| Kuraray Co., Ltd. |
| AGC Inc. |
| Others |
Supply Flow & Price Mechanics
Liquid crystal polymer substitution for rigid ceramic substrates in smartphone antenna modules simultaneously shifts procurement gravity toward South Korean film processors and compresses margin structures for Japanese alumina specialists serving legacy base station demand.
Pricing Analysis
Certification level creates the primary spread between qualified and unqualified substrate tiers. Three-tier pricing structure across UL 94 V-0 certified, FCC Part 27 pre-qualified, and uncertified grades governs millimeter-wave laminate transactions. Cost compression in uncertified tiers is intensifying because Chinese MIIT procurement registries have halved approved vendor lists, concentrating volume among domestic specialists. Consumer electronics procurement teams at Samsung and Apple exhibit the highest price sensitivity, while telecom operators accept premium positioning for infrastructure-grade thermal ceramics.
Supply Chain Analysis
Inventory buffers for fluoropolymer resin feedstock have compressed to eight-week coverage as PTFE allocation constraints ripple through North American laminate producers. Supply concentrates in Japan for alumina ceramic substrates, South Korea for liquid crystal polymer films, and the United States for PTFE laminates. Raw material dependencies rest on fluorspar concentrate from China, high-purity alumina from Australia, and thermotropic liquid crystal polymers from German chemical specialists. Single-source vulnerability in fluoropolymer resin supply exposes laminate producers to input cost volatility. Distribution runs through captive direct contracts between substrate manufacturers and base station OEMs, bypassing merchant distributors for qualified materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Millimeter-wave spectrum allocation acceleration across FCC Part 27 and EU Radio Equipment Directive jurisdictions positions 5G substrate materials for sustained expansion as infrastructure deployment outpaces material qualification capacity.
For Market Incumbents: Shield premium positioning in PTFE laminates by deepening captive fluoropolymer resin operations before feedstock allocation constraints tighten further. Accelerate UL 94 V-0 certification investments for emerging 37-47 GHz bands to preempt exclusion from Verizon and T-Mobile infrastructure tenders. Consolidate Japanese alumina ceramic capacity through METI-subsidized supply chain partnerships to defend against Chinese MIIT-mandated domestic sourcing requirements.
For New Entrants and Emerging Players: Differentiate on flexible liquid crystal polymer formulations for smartphone antenna-in-package modules where Samsung and Apple procurement teams have compressed design-in cycles. Target Germany's industrial 5G private network segment at BASF and Siemens facilities, where ruggedized substrate specifications diverge from consumer frequency bands and face less entrenched incumbent competition. Pursue Open RAN interoperability qualification as the primary go-to-market pathway to bypass integrated supplier list exclusion.
For Investors and Strategic Acquirers: FCC Part 27 spectrum expansion reshapes the acquisition landscape by privileging substrate vendors with pre-qualified 37-47 GHz test documentation. Long-term viability favors vertically integrated fluoropolymer resin producers and South Korean liquid crystal polymer film specialists with Samsung supply proximity. Watch Chinese MIIT qualification registry contractions as the signal for further consolidation among domestic ceramic and laminate producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | Rogers Corporation sustains margin concentration through captive PTFE supply against allocation volatility. |
| UL 94 V-0 Certification Investment | Pre-qualified laminate vendors capture Verizon infrastructure tenders before 18-24 month testing cycles complete. |
| Liquid Crystal Polymer Capacity Expansion | South Korean producers secure Samsung antenna-in-package design wins through proximity to display operations. |
| Open RAN Interoperability Qualification | Specialized substrate vendors bypass integrated supplier list exclusion in disaggregated radio access networks. |
| METI Subsidy Partnership Formation | Japanese ceramic producers anchor NTT Docomo supply security through localized content threshold compliance. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, MIIT procurement registries, and FCC Part 27 spectrum allocation documentation. Interviews with base station OEM procurement directors, laminate plant managers, and telecom operator network planning officers informed demand-side validation. Technical discussions with ceramic substrate R&D leads and liquid crystal polymer film process engineers supplied supply-side perspectives. Bottom-up volume modeling triangulated against top-down infrastructure deployment forecasts across the analysis window.
Segmentation dimensions modeled include material chemistry tier, application context, end-user procurement concentration, and form factor manufacturing maturity. CAGRs were derived through iterative reconciliation of deployment timelines against substrate qualification cycle compression. Forecast inputs incorporated Open RAN interoperability standard adoption curves and country-specific localized content threshold enforcement patterns throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained millimeter-wave infrastructure investment or accelerated smartphone mmWave penetration would require recalibration. Forecasts reflect documented assumptions regarding spectrum allocation timing and regulatory qualification protocol stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Silicon Dioxide Market
Semiconductor Material
Tellurium Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
Europe Semiconductor Materials Market
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
EV Capacitor Films Market
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
Global Semiconductor Gallium Oxide Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
Polyvinylidene Fluoride (PVDF) Market