
 LED Light Market | 2026-2036
LED Light Market Size, Share, and Industry Trends Forecast 2026-2036
LED Light Market Outlook
China is tilting toward dominant LED chip and package manufacturing capacity. Signify NV leverages its vertical integration across components to finished luminaires. Osram GmbH sustains technology leadership in automotive and specialty applications. Cree Lighting anchors North American supply through silicon carbide substrate expertise.
LED light denotes a solid-state electroluminescent device utilizing a semiconductor p-n junction that emits visible light when forward-biased, typically operating at 2-4 volts with luminous efficacy exceeding 150 lumens per watt in premium packages. The technology replaces incandescent and fluorescent sources across general illumination, display backlighting, and horticultural applications. Bulbs and fixtures command the largest product volume pools, while smart LED systems capture expanding margin pools through connected controls and energy management. Commercial and outdoor applications lead absolute demand, with industrial retrofit cycles accelerating replacement velocity.
FDA oversees photobiological safety standards for LED medical and consumer devices, while EPA Energy Star certification shapes procurement specifications across federal and utility rebate programs. China's MEE enforces dual carbon targets that mandate efficiency thresholds in public lighting tenders. Stakeholders must monitor regulatory divergence between efficiency mandates and circular economy requirements for semiconductor-containing waste streams.
Market Dynamics
China's dual carbon mandates from MEE are compressing municipal tender timelines and forcing rapid technology transitions across public lighting infrastructure, while silicon carbide substrate supply concentration in North America creates procurement bottlenecks for premium packages.
Growth Catalysts
- MEE dual carbon goals:China's Ministry of Ecology and Environment enforces efficiency thresholds in public lighting tenders, accelerating LED retrofits in municipalities and urban renewal projects.
- Silicon carbide substrates:Wide-bandgap semiconductor materials enable higher efficacy and thermal performance in premium automotive and horticultural applications.
- Commercial building retrofits:India's commercial real estate sector concentrates demand for connected LED systems with integrated energy management controls.
Market Restraints
- Epitaxial wafer supply concentration:Limited qualified suppliers of sapphire and silicon carbide substrates in Japan and the United States create input cost volatility for chip manufacturers.
- RoHS substance restrictions:European REACH and RoHS compliance adds certification friction for phosphor-converted white LED packages containing rare earth elements.
- OLED panel substitution:Organic electroluminescent displays displace LED backlighting in premium television and mobile device segments.
Strategic Opportunities
- Human-centric lighting:Circadian rhythm-tunable systems converge with IoT building automation, opening specification channels in healthcare and education verticals.
- Horticultural SSL expansion:Controlled environment agriculture in the Netherlands and Canada drives demand for spectral-tunable grow light systems.
- India PLI scheme:Production-linked incentives for electronics manufacturing attract component assembly and fixture production investments.
Industry Challenges
- Photobiological safety certification:IEC 62471 testing timelines and FDA device classification create launch delays for medical and consumer proximity lighting products.
- Legacy control protocol fragmentation:DALI, Zigbee, and proprietary mesh networks require complex integration engineering for retrofit projects.
- Thermal management talent scarcity:Shortage of opto-thermal engineers with compound semiconductor packaging expertise constrains product development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Light Market |
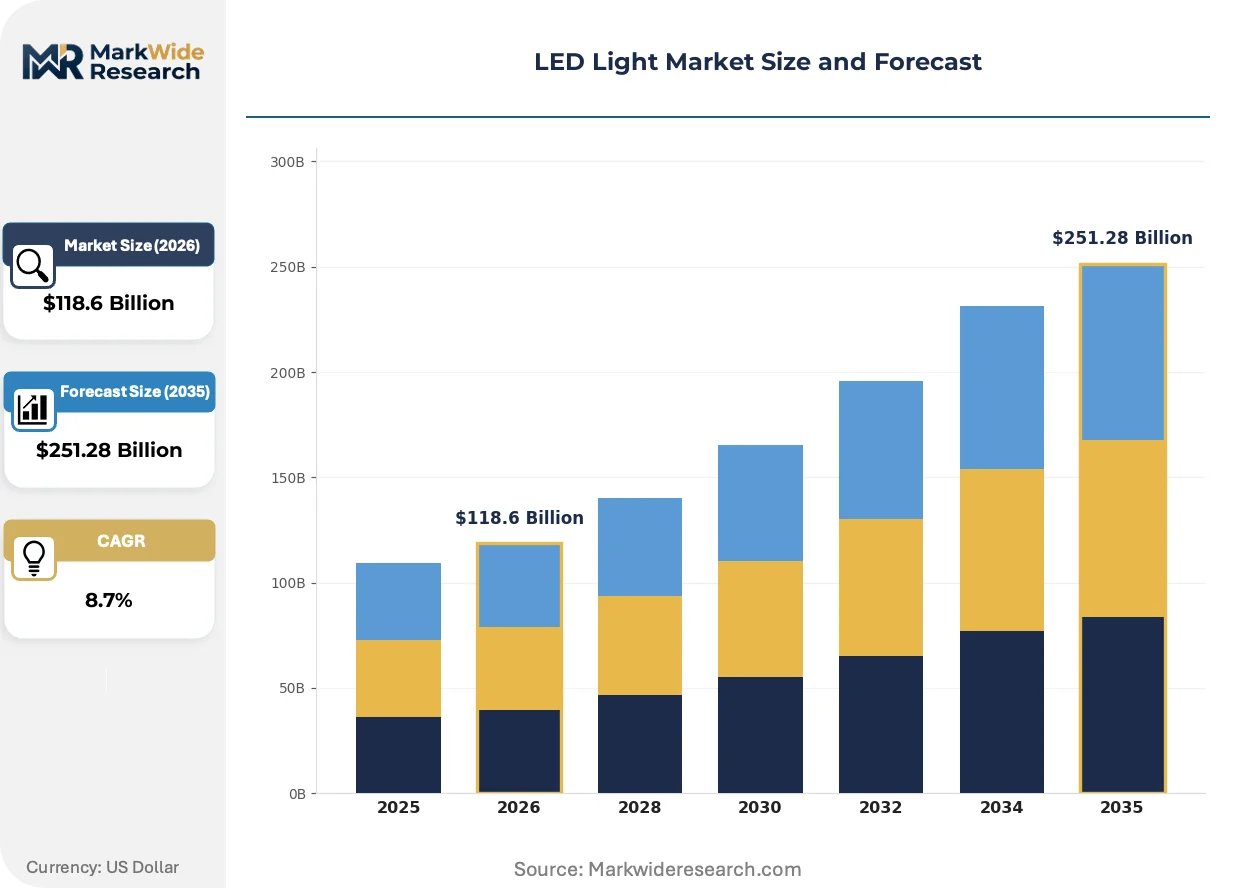
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $251.28 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Strips, Downlights Application: Residential, Commercial, Outdoor, Industrial Technology: Standard LED, Smart LED, RGB LED, High Power LED End User: Contractors, Retailers, OEMs, Distributors |
| Companies Covered | Signify NV, Osram GmbH, Cree Lighting, Acuity Brands Inc., Eaton Corporation, Hubbell Incorporated, Zumtobel Group AG, Wipro Lighting, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Light Market Strategic Shifts
Light-emitting diode technology is hybridizing with sensing and communication functions, transforming fixtures into distributed infrastructure nodes. Three developments are compressing traditional component boundaries and reshaping competitive positioning.
Mini-LED backlighting is hybridizing with quantum dot color conversion, enabling zone-dimmed liquid crystal displays with contrast ratios approaching emissive technologies. Television manufacturers in South Korea and China are adopting this architecture at scale for premium product tiers. The convergence is compressing demand for conventional edge-lit LED strips while expanding specification requirements for precision die-bonding equipment.
EPA Energy Star certification criteria are tightening efficacy thresholds and adding networked lighting control requirements for luminaire qualification. Federal procurement specifications and utility rebate programs are aligning with these updated standards. Commercial building owners in the United States are responding by bundling connected controls into retrofit specifications, shifting vendor evaluation criteria toward software interoperability.
Specification-grade buyers are unbundling lighting design from fixture procurement, engaging independent lighting designers through fee-for-service contracts rather than manufacturer-direct channels. This disintermediation is compressing traditional agent-distributor margins and forcing luminaire brands to invest in direct specification support capabilities. The pattern is most visible in commercial office and hospitality projects across Germany and the United Kingdom.
LED Light Market Segmentation
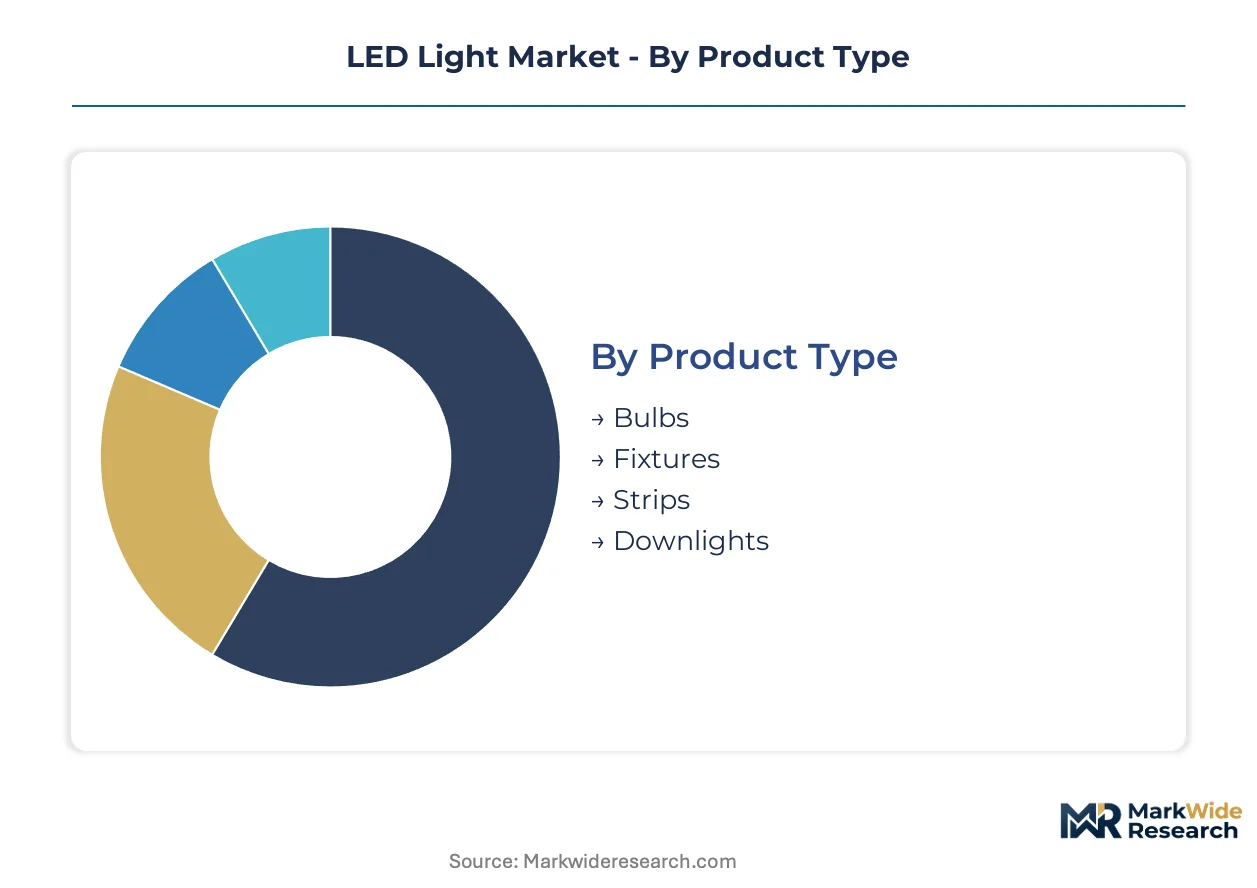
LED light market segmentation reveals how technology specialization and procurement channel dynamics create distinct margin profiles. Product architecture and connectivity specifications drive specification complexity across end-use verticals.
Product Type:
Cost tier differentiation separates commodity replacement volumes from specification-grade architectural installations.
- Bulbs:Standard A19, PAR, and MR16 form factors dominate residential retrofit volumes with Edison-base compatibility driving interchangeability. India's urban electrification programs and North American utility rebate schemes concentrate demand for basic efficacy packages.
- Fixtures:Integrated luminaire designs with thermal management systems and optical control command premium positioning in commercial new construction. China's municipal tender specifications for street and area lighting anchor volume concentration in outdoor infrastructure.
- Strips:Flexible linear arrays with adhesive backing serve cove, accent, and signage applications through low-voltage DC architectures.
- Downlights:Recessed ceiling modules with integrated drivers and trim systems target residential and hospitality retrofit markets.
Fixtures hold installed capacity. Bulbs are rotating up the share rankings.
Application:
End-use environment dictates thermal specification, ingress protection, and control integration requirements.
- Commercial:Office, retail, and hospitality installations specify connected systems with daylight harvesting and occupancy sensing. India's commercial real estate expansion in Bengaluru and Mumbai concentrates demand for tunable white and human-centric lighting systems.
- Outdoor:Street, area, and flood lighting applications require IP66+ ratings and surge protection for utility-scale deployments. China's MEE dual carbon mandates accelerate municipal retrofit timelines across tier-one and tier-two cities.
- Residential:Consumer replacement cycles and smart home integration drive volume through big-box retail and e-commerce channels.
- Industrial:High-bay and hazardous location fixtures specify extreme temperature tolerance and vibration resistance for manufacturing environments.
Commercial commands specification influence. Outdoor is climbing the fastest.
Technology:
Connectivity and spectral control capabilities separate premium system architectures from basic illumination functions.
- Smart LED:Networked luminaires with embedded sensors and wireless protocols enable IoT building automation integration. EPA Energy Star certification now mandates connected control compatibility for federal procurement eligibility.
- High Power LED:Chip-on-board and multi-die packages deliver kilolumen outputs for sports lighting and horticultural applications. Netherlands greenhouse operators specify spectral-tunable systems for controlled environment agriculture.
- Standard LED:Basic diode packages without communication capability serve cost-sensitive replacement markets.
- RGB LED:Multi-chip architectures with independent color channels enable dynamic color mixing for entertainment and architectural effects.
Standard LED holds installed capacity. Smart LED is gaining share fastest.
End User:
Procurement authority and technical specification capability determine channel economics and service bundling requirements.
- Contractors:Electrical installation firms bundle luminaire procurement with labor services for commercial and industrial projects. Germany's specification-grade market shows accelerating disintermediation as contractors engage independent lighting designers directly.
- OEMs:Original equipment manufacturers integrate LED modules into appliances, automotive assemblies, and display backlighting systems. Automotive tier-one suppliers in Japan and Germany specify Osram and Nichia packages for headlamp and interior applications.
- Distributors:Electrical and lighting wholesalers maintain inventory breadth and credit facilities for contractor accounts.
- Retailers:Big-box and specialty channels serve residential replacement and small commercial projects through immediate availability.
Contractors hold installed capacity. OEMs are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE dual carbon mandates are compressing municipal tender timelines across public lighting infrastructure, while silicon carbide substrate concentration in North America and India's commercial real estate expansion create distinct procurement dynamics.
China
Municipal street lighting retrofits and urban renewal projects drive volume demand. The Ministry of Ecology and Environment enforces efficiency thresholds that accelerate technology transitions in public tenders. Tier-one and tier-two cities are executing rapid LED conversions to meet dual carbon targets.
United States
Federal procurement specifications and utility rebate programs concentrate demand for connected LED systems. EPA Energy Star certification mandates networked lighting control compatibility for qualification. Commercial building owners in California and Texas are bundling smart controls into retrofit specifications.
India
Commercial real estate expansion in Bengaluru and Mumbai concentrates demand for tunable white and human-centric lighting systems. The PLI scheme for electronics manufacturing attracts component assembly investments. Maharashtra and Gujarat host emerging fixture production clusters serving domestic specification-grade markets.
Germany
Specification-grade commercial and hospitality projects drive premium luminaire demand. Independent lighting designers are disintermediating traditional agent-distributor channels through fee-for-service contracts. The Netherlands and Belgium import German-engineered horticultural SSL systems for controlled environment agriculture.
Japan
Automotive tier-one suppliers specify precision LED packages for headlamp and interior applications. METI efficiency standards shape industrial retrofit specifications. The Kansai and Chubu regions maintain concentrated optoelectronics manufacturing for display backlighting and specialty illumination.
LED Light Market Competitive Environment
Vertically integrated conglomerates and component-specialist independents split the market across distinct value capture layers. The vendor base organizes around three strategic archetypes: captive substrate producers controlling upstream semiconductor supply, luminaire assemblers bundling thermal and optical engineering, and application-focused specialists serving automotive and horticultural niches. Dominant competitive moves include backward integration into epitaxial wafer capacity and geographic expansion through municipal tender participation in Asia-Pacific growth corridors.
Among Netherlands-based lighting conglomerates, Signify NV exemplifies the vertically integrated archetype spanning chips to finished luminaires. Osram GmbH anchors the component-specialist tier with sustained technology positioning in automotive and specialty segments. Cree Lighting occupies a position within the substrate-anchored tier, leveraging silicon carbide expertise for North American supply security.
| Leading Market Players |
|---|
| Signify NV |
| Osram GmbH |
| Cree Lighting |
| Acuity Brands Inc. |
| Eaton Corporation |
| Hubbell Incorporated |
| Zumtobel Group AG |
| Wipro Lighting |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide substrate concentration in North America and Japan funnels margin capture toward premium automotive and horticultural package tiers, while commoditized bulb volumes face relentless cost compression from China's integrated chip-to-fixture manufacturers. This upstream asymmetry forces specification-grade luminaire brands to differentiate through thermal engineering and connected control bundling rather than component sourcing alone.
Pricing Analysis
China-to-Europe price spreads on standard A19 bulbs exceed three-to-one ratios, reflecting divergent labor and energy input costs. Three-tier pricing structure across premium, standard, and economy levels separates EPA Energy Star-certified connected systems from basic efficacy packages and unbranded commodity replacements. Price erosion runs through residential retrofit channels as China's municipal tender volumes absorb domestic fixture capacity. Contractors exhibit highest price sensitivity in commercial bidding, while OEM automotive buyers prioritize thermal performance and qualification timelines over unit economics.
Supply Chain Analysis
Extended payment terms from European luminaire brands to Taiwanese and Chinese contract manufacturers now stretch ninety to one-hundred-twenty days, straining working capital for mid-tier assemblers. Epitaxial wafer supply concentrates in Japan, the United States, and Taiwan, with sapphire and silicon carbide substrates drawing from rare earth processing facilities in China and Australia. Single-source vulnerability in qualified silicon carbide substrate suppliers creates procurement bottlenecks for premium automotive packages. Distribution runs through electrical wholesalers in mature markets and direct municipal tender participation in China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across control protocol standards and specification channel disintermediation creates niche entry points for specialized players. The unbundling of lighting design from fixture procurement generates fee-for-service opportunities independent of manufacturing scale.
For Market Incumbents: Harden specification influence by acquiring independent lighting design practices in Germany and the United Kingdom before competitor brands replicate direct designer engagement. Deepen captive silicon carbide substrate supply through joint ventures with North American wafer producers, insulating premium automotive and horticultural portfolios from input cost volatility driven by Japan-U.S. supply concentration. For New Entrants and Emerging Players: India's Maharashtra and Gujarat fixture production clusters offer underpenetrated specification-grade assembly capacity for European and North American private-label contracts. Target spectral-tunable horticultural systems for Netherlands and Canadian controlled environment agriculture operators, leveraging the Netherlands' import dependency for German-engineered SSL systems. Pursue direct-to-grower sales models bypassing traditional agricultural distribution channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed luminaire assemblers in North American commercial lighting, where sponsor exits face compressed multiples from protocol fragmentation and software interoperability demands. Prioritize targets with embedded IoT control platforms and recurring service revenue streams over pure hardware manufacturers. Watch EPA Energy Star networked control mandates as inflection signal for connected system qualification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Capacity | Captive silicon carbide supply secures premium automotive and horticultural package margins against Japan-U.S. concentration. |
| Acquisition of Independent Lighting Design Practices | Direct designer relationships counter agent-distributor disintermediation in German and UK specification-grade markets. |
| Joint Venture in Indian Fixture Production Clusters | Maharashtra and Gujarat assembly capacity serves PLI-scheme electronics manufacturing incentives for domestic and export demand. |
| Spectral-Tunable Horticultural System Launch | Netherlands greenhouse operators and Canadian controlled environment agriculture drive replacement cycles for LED grow light retrofits. |
| EPA Energy Star Connected Control Certification | Federal procurement eligibility and utility rebate program access hinge on networked lighting control compatibility mandates. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, utility procurement databases, municipal tender records, and EPA Energy Star certification registries. Interviews with commercial lighting contractors, electrical wholesalers, municipal procurement officers, opto-thermal engineers, and greenhouse operations managers informed demand-side validation. Bottom-up luminaire shipment estimates and top-down energy efficiency retrofit spending flows were cross-referenced for triangulation.
Forecast inputs include product type segmentation across bulbs, fixtures, strips, and downlights; application verticals spanning commercial, outdoor, residential, and industrial; technology tiers separating smart, high-power, standard, and RGB architectures; and end-user channels distinguishing contractors, OEMs, distributors, and retailers. CAGRs were derived from fitted growth curves calibrated to historical retrofit penetration rates and regulatory mandate timelines. China's MEE dual carbon enforcement intensity and India's PLI scheme uptake velocity served as scenario-weighting variables.
Practitioners should monitor silicon carbide substrate qualification expansions, EPA Energy Star criteria revisions, and India PLI scheme beneficiary announcements for early signals of supply and demand inflection. Forecasts reflect assumptions about municipal tender execution rates, automotive LED content per vehicle trajectories, and horticultural SSL adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
7 Segment LED Displays Market
LED
Monochrome Outdoor LED Display Market
LED
Linear LED Strip Fixture Market
LED
UK LED Lighting Market
LED
Global Outdoor LED Lighting Market
LED
LED Lamp Market
LED
Germany Outdoor LED Lighting Market
LED
East Africa LED Lighting Market
LED
LED Light Bar Market
LED
LED Display Market
LED
Egypt LED Lighting Market
LED
UV-C LED Market
LED
Europe LED Lighting Market
LED
South America Indoor LED Lighting Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
Global Chip on Board (COB) Light Emitting Diode Market