
 Silicon Epitaxial Wafer Market | 2026-2036
Silicon Epitaxial Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Epitaxial Wafer Market Analytics
PhD-level epitaxy process engineers is redrawing competitive boundaries across the Silicon Epitaxial Wafer landscape. Siltronic AG leverages its Dresden-based R&D campus to sustain technology leadership in 300mm epitaxial stacks for logic devices. SUMCO Corporation anchors Japanese supply security through captive polysilicon-to-epitaxy integration at its Chitose and Yonezawa facilities. SK Siltron Co. Ltd. competes aggressively in SiC-adjacent silicon epitaxy for power module customers.
Silicon epitaxial wafers are single-crystal silicon substrates with thin, crystallographically aligned layers deposited via chemical vapor deposition, typically achieving defect densities below 0.1 per square centimeter for advanced node applications; these wafers serve as the foundational platform for transistor fabrication where carrier mobility and layer uniformity determine device yield. The 12-inch wafer size segment dominates value capture as foundry transitions to 5nm and 3nm nodes consume larger diameter epitaxial blanks. Double-sided epitaxial configurations are gaining fastest traction in power device applications where backside layer quality impacts thermal performance. Integrated Circuits remains the most mature application segment with entrenched qualification cycles, while Power Devices concentrates margin pools through automotive electrification and renewable energy inverter demand.
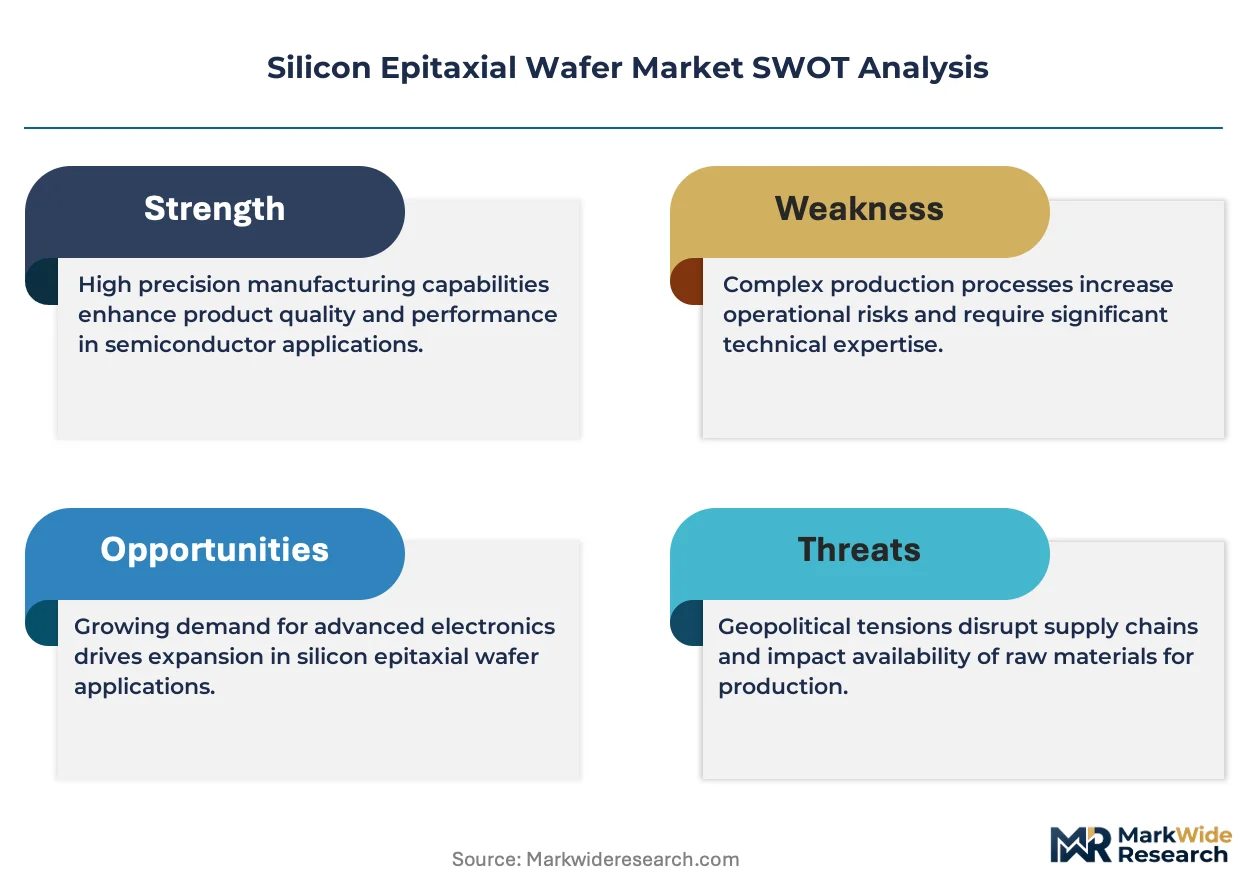
Japan's METI semiconductor revitalization subsidies, South Korea's K-Semiconductor Belt tax incentives, and China's GB/T silicon wafer standards collectively shape capital allocation and technology transfer protocols across the supply base. REACH compliance in Europe and EPA emissions rules in the United States constrain trichlorosilane and dichlorosilane precursor chemistries used in epitaxial deposition reactors. Stakeholders must monitor polysilicon precursor cost trajectories and regional cleanroom construction timelines before committing to greenfield epitaxy capacity.
Market Dynamics
Automotive electrification is compressing qualification cycles for power-grade epitaxial wafers, forcing foundries to synchronize process validation with Tier 1 inverter module roadmaps. This demand synchronization is redrawing capacity allocation decisions across deposition equipment fleets.
Growth Catalysts
- China's dual carbon goals:MIIT semiconductor localization mandates redirect capital toward domestic epitaxy capacity expansion, creating captive demand for 300mm silicon blanks.
- Power device foundries:Automotive inverter manufacturers accelerate procurement of double-sided epitaxial configurations to optimize thermal performance in high-voltage modules.
- Renewable energy deployment:Solar inverter and wind converter installations concentrate demand for thick epitaxial layers in East Asian fabrication clusters.
Market Restraints
- Polysilicon precursor volatility:Trichlorosilane and dichlorosilane feedstock costs fluctuate with chlorosilane plant operating rates in Xinjiang and Inner Mongolia.
- Deposition equipment concentration:Single-wafer reactor supply concentrates among three Japanese and German tool vendors, creating bottleneck risk for greenfield capacity.
- REACH chemical compliance:ECHA restrictions on chlorinated precursor handling add capital burden to European epitaxy operations.
Strategic Opportunities
- India's PLI scheme:Semiconductor fabrication incentives create first-mover advantage for epitaxial wafer suppliers qualifying with domestic foundry projects.
- SiC-adjacent silicon epitaxy:Hybrid power module designs converge silicon control circuits with silicon carbide switches, opening qualification pathways for specialized epi stacks.
- Direct OEM contracting:Automotive power module makers bypass traditional distribution to secure dedicated epitaxial wafer allocation through long-term offtake agreements.
Industry Challenges
- PhD-level process engineering scarcity:Atomic layer epitaxy and defect characterization expertise concentrates at Dresden, Chitose, and Hsinchu talent pools, constraining global capacity expansion.
- Multi-year qualification timelines:Automotive AEC-Q100 and inverter-grade reliability testing extends customer onboarding to 18-24 months, delaying revenue recognition for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Epitaxial Wafer Market |
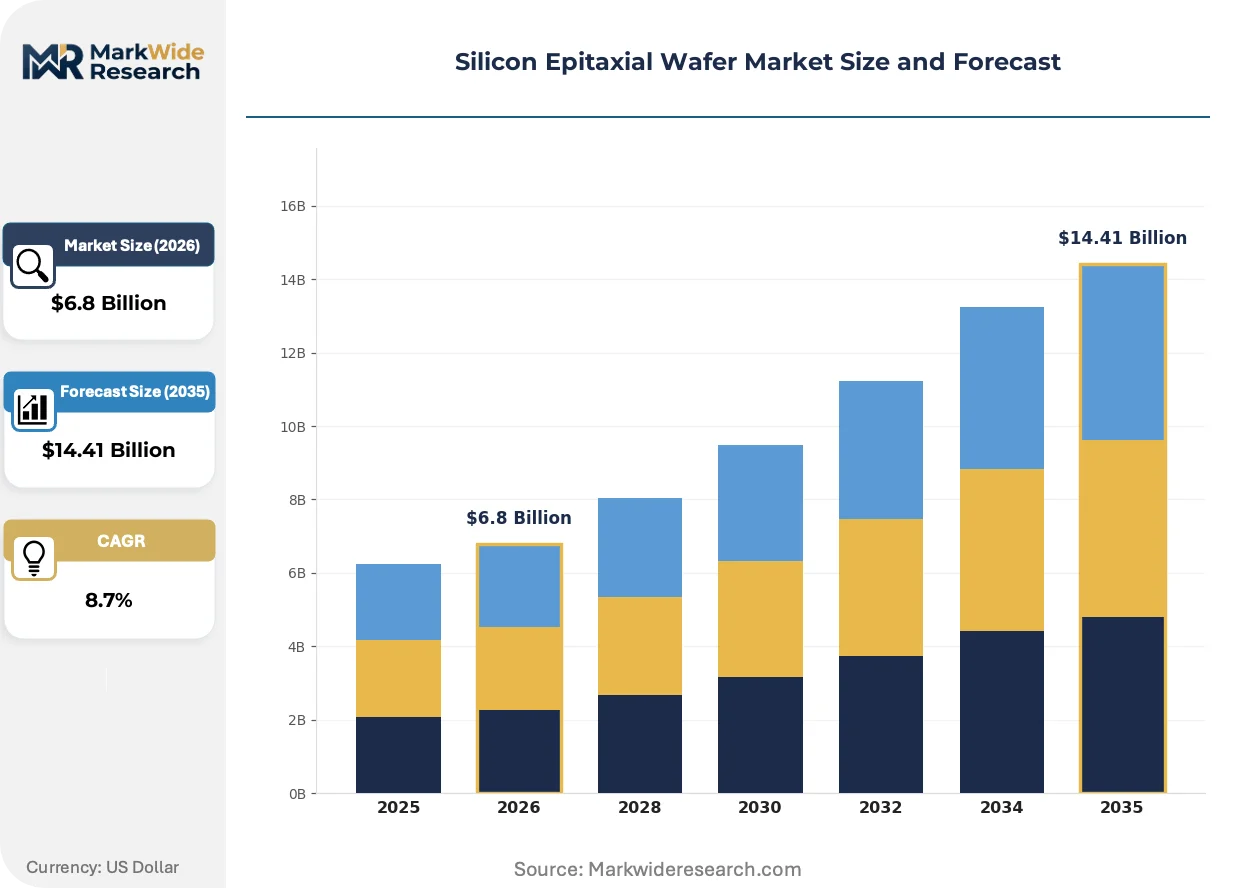
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Multi-Layer, Epitaxial Application: Integrated Circuits, Power Devices, Photovoltaic Cells, Sensors Wafer Size: 4-inch, 6-inch, 8-inch, 12-inch End User: Consumer Electronics, Automotive, Telecommunications, Aerospace |
| Companies Covered | Siltronic AG, IQE PLC, SUMCO Corporation, SHOWA DENKO K.K., II-VI Incorporated, Shin-Etsu Handotai Co. Ltd., SK Siltron Co. Ltd., SweGaN AB, GlobalWafers Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Epitaxial Wafer Market Evolving Landscape
Epitaxial deposition control systems are converging with in-situ metrology, compressing process development cycles and enabling real-time thickness uniformity correction. This integration is redefining yield management economics across logic and power device segments.
Atomic layer deposition integration with conventional chemical vapor epitaxy is miniaturizing transition region thickness in superjunction device structures. Power discrete manufacturers in Japan and Germany adopt these stacks for next-generation MOSFET platforms. The technology is miniaturizing the trade-off between breakdown voltage and on-resistance that has constrained silicon power device performance.
EPA emissions rules governing chlorosilane vent handling are tightening discharge thresholds for epitaxial reactor exhaust systems. Equipment vendors must retrofit scrubber architectures or risk operational shutdowns at US-based deposition facilities. Power device foundries with California and Texas operations face the steepest compliance cost escalation.
Automotive power module buyers now mandate source-level traceability for polysilicon feedstock and crystal growth records, displacing certificate-of-analysis documentation that previously sufficed. Tier 1 suppliers in Germany and South Korea enforce this through supplier audit programs. The shift is most visible in electric vehicle inverter supply chains where battery-electric platform launches require full material genealogy.
Silicon Epitaxial Wafer Market Segmentation
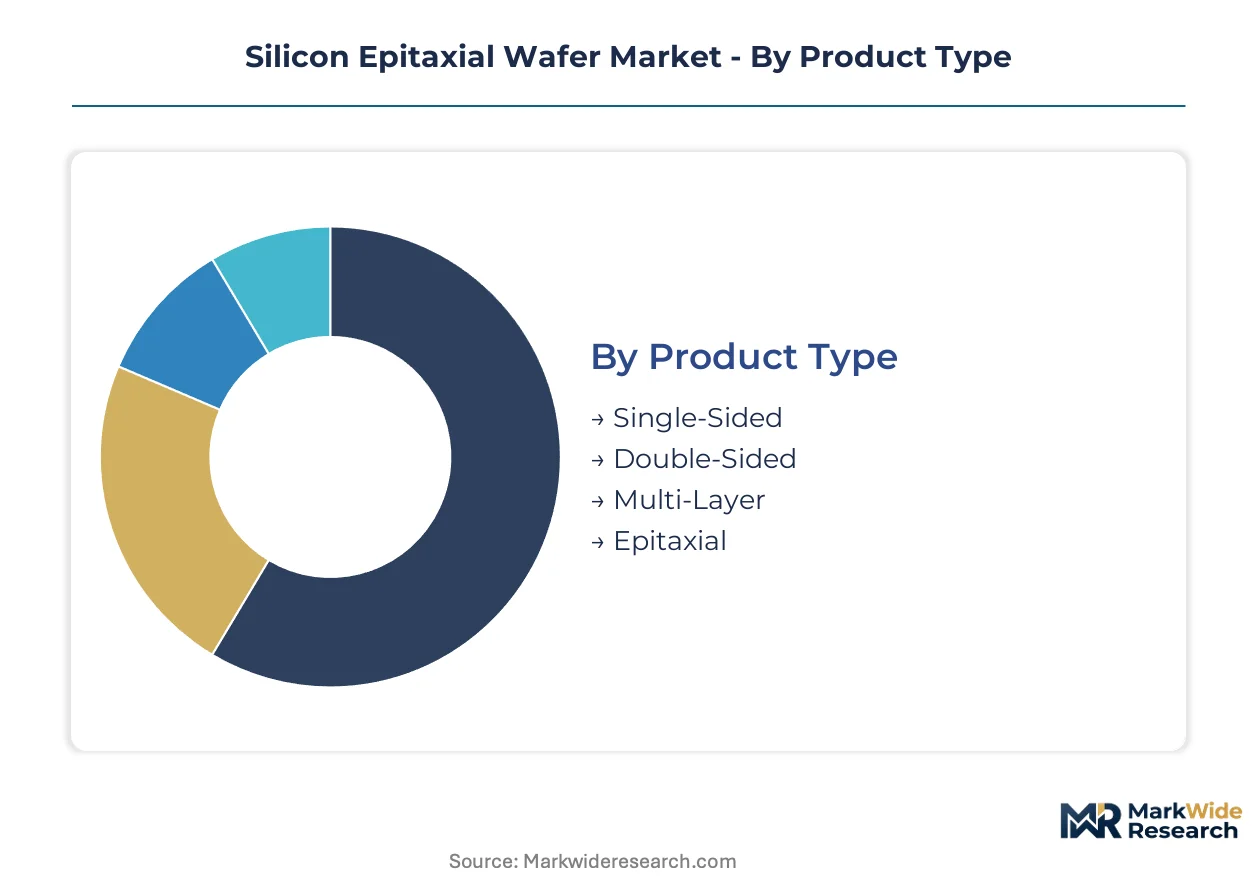
Silicon epitaxial wafer procurement channels diverge sharply by product complexity and end-use qualification requirements. Automotive power module buyers demand direct foundry contracting with full material traceability, while consumer electronics flows through distributor networks with standardized specifications.
Product Type:
Channel-mix patterns separate commodity-grade single-sided wafers from premium double-sided configurations requiring direct technical support.
- Single-Sided:One epitaxial layer deposited on the polished front surface with the backside remaining as-processed from crystal growth. Logic device foundries in Taiwan and South Korea standardize on this configuration for cost-sensitive node migrations.
- Double-Sided:Symmetrical epitaxial layers on both wafer surfaces enable balanced thermal expansion and improved heat dissipation in high-voltage power modules. Automotive inverter manufacturers in Germany and Japan now mandate this architecture for 800V electric vehicle platforms.
- Multi-Layer:Sequential deposition of alternating doped and intrinsic layers creates complex vertical device structures. Specialized foundries serving RF and analog segments specify these stacks for mixer and oscillator applications.
- Epitaxial:Generic designation for standard epitaxial deposition without specialized layer engineering. Legacy fab equipment and research institutions procure through catalog distributors with minimal technical engagement.
By volume, Single-Sided leads. By growth pace, Double-Sided is expanding most quickly.
Application:
Cost tier stratification separates mature integrated circuit applications from emerging power device segments commanding premium pricing.
- Integrated Circuits:Established qualification protocols and entrenched supplier relationships dominate this mature segment. Logic and memory foundries in Japan, South Korea, and Taiwan consume the majority of 300mm epitaxial blanks for advanced node production.
- Power Devices:Superjunction MOSFETs and IGBT platforms require thick, low-defect epitaxial layers with precise doping profiles. Renewable energy inverter deployments and electric vehicle powertrains are compressing procurement cycles for these specialized wafers.
- Photovoltaic Cells:High-efficiency solar cell architectures utilize epitaxial silicon for carrier collection optimization. Chinese module manufacturers integrate these wafers into premium residential and utility-scale installations.
- Sensors:MEMS pressure and inertial sensors demand controlled epitaxial layer thickness for mechanical structure definition. Automotive safety system suppliers in Germany specify these for tire pressure monitoring and stability control modules.
Integrated Circuits retains the largest revenue base. Power Devices is climbing the fastest as electrification accelerates.
Wafer Size:
Customer type segmentation separates research institutions and specialty fabs from high-volume foundries based on diameter requirements.
- 4-inch:Legacy diameter serving compound semiconductor research and small-batch prototyping. University cleanrooms and defense contractors in the United States maintain limited procurement for radiation-hardened device development.
- 6-inch:Power discrete and automotive sensor manufacturers standardize on this diameter for mature process nodes. European and Japanese suppliers concentrate capacity here for industrial and traction inverter applications.
- 8-inch:Mixed-signal and analog foundries balance cost and area efficiency at this diameter. Chinese domestic fab construction is expanding 200mm epitaxial capacity under MIIT localization mandates.
- 12-inch:Advanced logic and memory production requires 300mm epitaxial blanks with sub-0.1 defect densities. Foundry transitions to 5nm and 3nm nodes are concentrating demand among East Asian fabrication clusters.
12-inch commands the highest unit economics. 8-inch is gaining share fastest as Chinese capacity expansion accelerates.
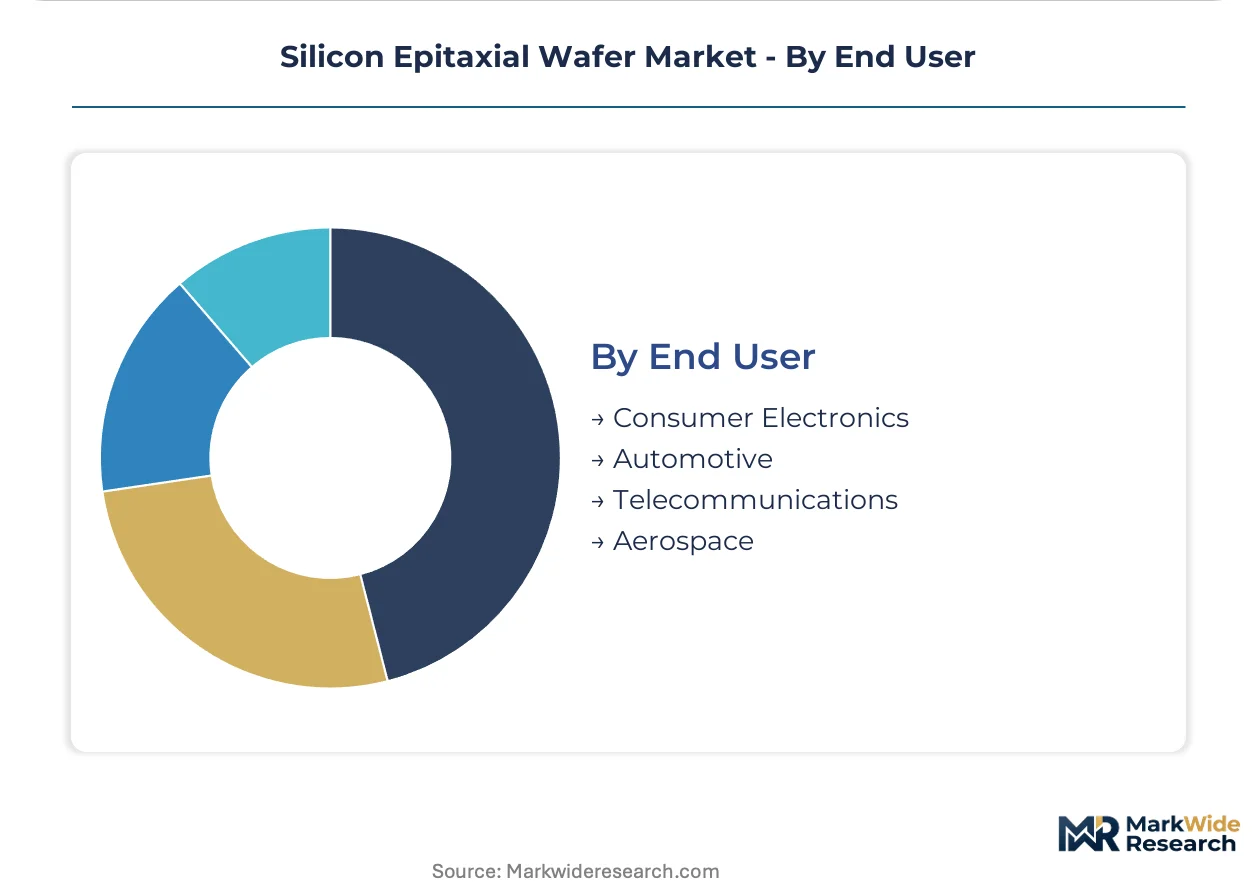
End User:
Geography-driven supply concentration shapes regional procurement patterns and qualification requirements.
- Consumer Electronics:Smartphone and personal computing OEMs drive high-volume, price-sensitive procurement through consolidated foundry relationships. Assembly operations in Vietnam and India are redirecting some regional demand flows.
- Automotive:Tier 1 inverter and power module suppliers enforce source-level traceability and AEC-Q100 reliability certification. German and South Korean automotive suppliers are bypassing traditional distribution for direct epitaxial wafer allocation.
- Telecommunications:5G base station and optical transceiver manufacturers specify low-noise epitaxial layers for high-frequency performance. Network equipment vendors in Finland and Sweden qualify specialized suppliers for RF front-end modules.
- Aerospace:Radiation-hardened and high-reliability applications demand extended qualification and heritage supplier status. Satellite manufacturers in the United States and France maintain captive supply agreements with certified epitaxy vendors.
Consumer Electronics leads by wafer volume. Automotive is expanding most quickly as electrification penetrates vehicle platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT semiconductor localization mandates anchor China's central role in redirecting epitaxial wafer supply chains. Regional capacity investments concentrate in East Asian fabrication clusters spanning Japan, South Korea, and Taiwan, with regulatory incentives reshaping capital allocation across deposition equipment and polysilicon feedstock networks.
China
Dual carbon goals and MIIT mandates accelerate domestic 300mm epitaxy capacity construction for captive logic and power device demand. GB/T silicon wafer standards enforce quality benchmarks that redirect procurement toward qualified local suppliers. Yangtze River Delta fabrication clusters in Shanghai and Hsinchu-adjacent zones concentrate greenfield cleanroom investments under provincial semiconductor funds.
Japan
METI semiconductor revitalization subsidies sustain deposition equipment and polysilicon-to-epitaxy integration at Chitose and Yonezawa facilities. JIS standards govern precursor chemistry handling alongside REACH-aligned export protocols for chlorosilane feedstocks. Kyushu and Nagoya industrial corridors anchor captive supply chains for automotive power module customers requiring AEC-Q100 traceability.
South Korea
K-Semiconductor Belt tax incentives compress qualification timelines for power-grade epitaxial wafers serving Hyundai and Kia electrification platforms. MFDS chemical handling regulations align with EPA-tier emissions controls for dichlorosilane reactor exhaust. Seoul Capital Area and Busan-Ulsan clusters concentrate foundry partnerships with direct OEM contracting for 800V inverter modules.
Germany
ECHA REACH restrictions on trichlorosilane handling add capital burden to Dresden-based R&D campuses sustaining 300mm epitaxial stack leadership. KBA automotive certification requirements enforce source-level polysilicon traceability for Tier 1 inverter suppliers. Bavaria and Saxony fabrication zones anchor European power device qualification pathways alongside SiC-adjacent silicon epitaxy development.
United States
EPA emissions rules tighten chlorosilane vent discharge thresholds for California and Texas deposition facilities serving aerospace radiation-hardened applications. NHTSA electric vehicle safety standards propagate backward through supply chains demanding extended material genealogy. Greater Boston and Pacific Northwest research corridors sustain university cleanroom procurement for defense contractor prototyping programs.
Silicon Epitaxial Wafer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Silicon Epitaxial Wafer competitive hierarchy. Backward integration into polysilicon feedstock and captive crystal growth separates the upper tier from deposition-only operators. Three archetypes dominate: polysilicon-to-epitaxy integrated conglomerates, pure-play epitaxial deposition specialists, and diversified materials science groups with adjacent compound semiconductor exposure. Capacity expansion and strategic partnerships constitute the dominant competitive vectors, with qualification timeline compression emerging as a secondary battleground for automotive power module allocation.
Among German-integrated leaders, Siltronic AG occupies a position exemplifying captive R&D-to-production control over 300mm logic-grade stacks. Japanese conglomerates SUMCO Corporation and Shin-Etsu Handotai Co. Ltd. anchor the polysilicon-integrated archetype through Chitose and Yonezawa facility networks. SK Siltron Co. Ltd. represents the Korean specialist tier competing on SiC-adjacent silicon epitaxy proximity to power module foundries. IQE PLC and II-VI Incorporated sit within the diversified materials science grouping with compound semiconductor adjacencies. GlobalWafers Co. Ltd. exemplifies scale-driven expansion through acquisition-led capacity aggregation.
| Leading Market Players |
|---|
| Siltronic AG |
| IQE PLC |
| SUMCO Corporation |
| SHOWA DENKO K.K. |
| II-VI Incorporated |
| Shin-Etsu Handotai Co. Ltd. |
| SK Siltron Co. Ltd. |
| SweGaN AB |
| GlobalWafers Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four month qualification timelines for automotive AEC-Q100 certification concentrate pricing power with incumbent suppliers possessing established foundry relationships, while polysilicon precursor volatility in Xinjiang and Inner Mongolia feeds cost uncertainty through contract structures. This lead-time rigidity separates captive long-term offtake agreements from spot-market transactions in a supply chain shaped by deposition equipment concentration among Japanese and German tool vendors.
Pricing Analysis
East Asian fabrication clusters command premium pricing over European and North American delivery points due to proximity to 300mm logic and memory foundries. Three-tier pricing structure across automotive-qualified, industrial-grade, and research-tier specifications segments buyer access, with AEC-Q100 traceability requirements enabling margin capture at the top tier. Cost compression in industrial-grade single-sided wafers is intensifying because Chinese domestic capacity expansion under MIIT mandates adds volume competition. Consumer electronics OEMs exhibit highest price sensitivity through consolidated foundry procurement, while automotive power module makers accept premium positioning for source-level material genealogy.
Supply Chain Analysis
Forty-five to sixty days of polysilicon precursor inventory buffers epitaxial deposition facilities against chlorosilane plant operating rate fluctuations in Xinjiang and Inner Mongolia. Manufacturing concentrates in Japan, South Korea, and Taiwan, with feedstock sourcing anchored in Chinese polysilicon purification and German precursor chemistry engineering. Raw material dependencies span trichlorosilane and dichlorosilane feedstocks, high-purity quartz crucibles, and single-wafer reactor components. Single-source vulnerability in deposition equipment creates bottleneck risk for greenfield capacity timelines. Distribution runs through direct foundry contracting for automotive and logic segments, with distributor networks serving research institutions and legacy fab equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon epitaxial wafer demand sits in early-cycle expansion as automotive electrification and renewable energy inverter deployment compress qualification timelines and redirect capacity investments toward power-grade specifications.
For Market Incumbents: Compound technology leadership in 300mm epitaxial stacks through captive R&D-to-production integration at Dresden or Chitose campuses, while securing polysilicon-to-epitaxy backward integration to buffer feedstock volatility threatening margin stability in long-term automotive contracts. For New Entrants and Emerging Players: AEC-Q100 certification fast-track partnerships with German or South Korean Tier 1 automotive suppliers open qualification pathways bypassing traditional 18-24 month timelines. Target India's PLI scheme semiconductor fabrication incentives as the most penetrable geography, with direct OEM contracting for 800V inverter modules as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified materials science conglomerates with adjacent compound semiconductor exposure but underoptimized silicon epitaxy operations. Five-to-ten year viability hinges on deposition equipment access and captive polysilicon supply. Watch for MIIT localization mandate enforcement intensity as the inflection signal for Chinese domestic capacity absorption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Feedstock | Captive supply from Xinjiang or Inner Mongolia precursors buffers margin against chlorosilane volatility. |
| Automotive Certification Fast-Track Investment | AEC-Q100 qualification compression aligns revenue recognition with Hyundai and Kia platform launches. |
| Deposition Equipment Partnership | Single-wafer reactor allocation agreements with Japanese tool vendors secure greenfield capacity timelines. |
| Direct OEM Contracting Structure | Long-term offtake with German inverter suppliers displaces distributor dependency and captures premium positioning. |
| SiC-Adjacent Silicon Epitaxy Development | Hybrid power module designs with silicon control circuits open qualification pathways at SK Siltron proximity. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with epitaxy process engineers, foundry procurement managers, automotive Tier 1 supplier quality directors, and deposition equipment specialists; and secondary validation through MIIT semiconductor policy filings, METI subsidy disbursement records, EPA emissions rule dockets, and SEC 10-K disclosures from publicly traded wafer manufacturers. Bottom-up wafer consumption estimates by application segment triangulated against top-down capacity build-out projections across East Asian fabrication clusters.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning wafer size tier, epitaxial layer configuration, end-use application, and regional regulatory cluster alignment. CAGRs derived from installed base depreciation schedules and foundry node transition roadmaps incorporated polysilicon precursor cost trajectories and cleanroom construction timelines as industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of sustained MIIT localization enforcement and stable chlorosilane plant operating rates in Chinese production zones; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Chip Crusher Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
T-Con Board Market
Semiconductor Devices
Coated Silicon Wafer Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Field Effect Transistor Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
Global Inp Wafer Market
Semiconductor Devices
Mobile Phone Semiconductor Market
Semiconductor Devices
Gan Transistor Market
Semiconductor Devices
Embedded Multimedia Card Market
Semiconductor Devices
AMD Motherboards Market