
 Video Wall Display Market | 2026-2036
Video Wall Display Market Size, Share, and Industry Trends Forecast 2026-2036
Video Wall Display Market Intelligence
Display-as-a-service leasing is rewriting competitive access in the video wall industry, lowering capital barriers for mid-tier integrators and expanding the addressable customer base. Barco leverages its vertical integration in image processing to sustain premium positioning in mission-critical control rooms. Samsung Electronics anchors large-scale manufacturing scale for LCD and LED modules, while Leyard specializes in fine-pitch LED architectures for broadcast studios and corporate lobbies.
A video wall display comprises multiple display panels tiled with minimal bezel gaps to form a unified, high-resolution visual surface, typically driven by synchronized processors managing color calibration and content distribution across hundreds of millions of pixels. The primary purpose spans real-time data visualization, public information dissemination, and immersive brand experiences in environments where single-display dimensions prove inadequate. LED technology dominates volume in outdoor and high-brightness applications, while LCD retains cost advantages in indoor corporate and retail environments where viewing distances are shorter. Control rooms and command centers represent the most structurally entrenched application segment, with long replacement cycles and stringent uptime requirements that create sticky supplier relationships and higher service-margin pools.
The FCC in the United States enforces electromagnetic interference standards that shape product certification timelines for imported display assemblies, while the EU's RoHS and REACH frameworks restrict hazardous substances in electronic components and affect material sourcing across the supply chain. China's SAMR administers national standards for display energy efficiency and safety certification that manufacturers must obtain for domestic market access. Stakeholders must monitor how evolving energy-efficiency regulations in multiple jurisdictions interact with the thermal management demands of increasingly dense pixel pitches.
Market Dynamics
Energy-efficiency mandates from Brussels to Beijing are compressing thermal design tolerances while pixel densities climb, forcing manufacturers to reengineer power architectures without sacrificing brightness uniformity across tiled arrays.
Growth Catalysts
- China's tier-one smart-city budgets:Municipal procurement of public information systems in Shanghai, Beijing, and Shenzhen is accelerating deployments of narrow-bezel LED arrays for transit hubs and emergency operations centers.
- Ecodesign standby power limits:The EU's tightening standby consumption thresholds for large-format displays is pulling forward replacement cycles in corporate and retail installations across Germany, France, and the Netherlands.
- Fine-pitch LED maturation:Advances in chip-on-board packaging are extending indoor LED viability into conference rooms and broadcast studios previously served by LCD dominance.
Market Restraints
- Indium and gallium supply concentration:Critical LED phosphor and driver semiconductor feedstocks face extraction bottlenecks concentrated in Chinese refining operations, exposing cost volatility for non-integrated assemblers.
- RoHS substance restrictions:The EU's hazardous substance framework complicates solder and coating material selection, extending qualification timelines for new product introductions by 6-12 months.
- Projection mapping substitution:Large-venue immersive applications in museums and theme parks are diverting capital toward laser projection systems that eliminate bezel interruption entirely.
Strategic Opportunities
- India's underpenetrated control room sector:State-level disaster management authorities and power grid operators are initiating first-generation video wall procurements with limited incumbent supplier relationships.
- Display-as-a-service leasing:Subscription-based hardware provisioning is opening mid-tier integrator access to municipal and education buyers previously blocked by upfront capital requirements.
- AI-driven content automation:Convergence of computer vision and real-time data pipelines is creating new attach-rate potential for software-layer recurring revenue in security and transportation command centers.
Industry Challenges
- Color calibration technician scarcity:The specialized skill set for multi-panel uniformity matching across millions of pixels is concentrated among aging specialists in Japan and Germany, constraining deployment velocity for large-scale projects.
- FCC electromagnetic certification timelines:Pre-market authorization procedures for imported LED driver assemblies are extending time-to-revenue for Asian manufacturers targeting North American defense and energy sector buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Wall Display Market |
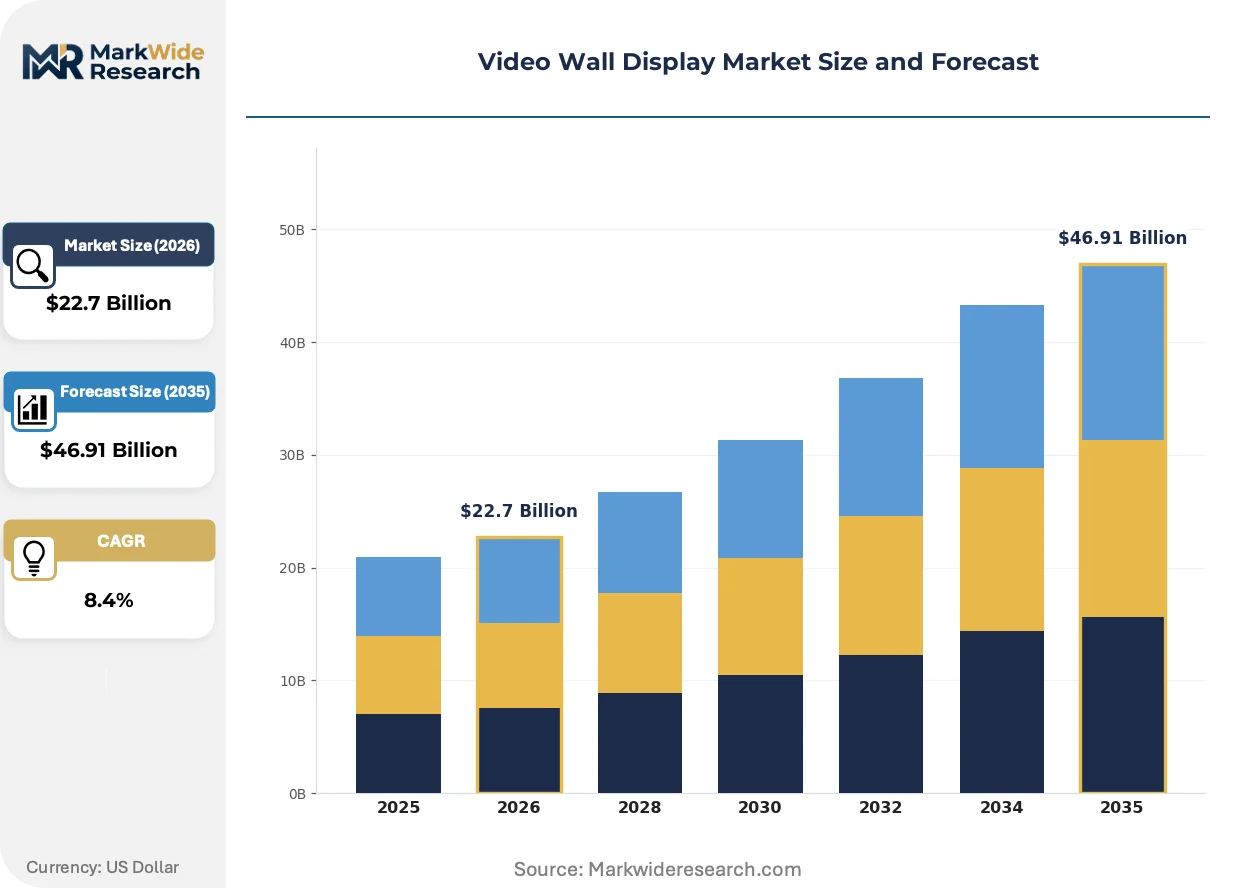
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $46.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LED, LCD, OLED, DLP, Projection, MicroLED Application: Control Rooms, Broadcast Studios, Command Centers, Retail Environments, Sports Arenas, Museums End User: Government Agencies, Corporate Offices, Educational Institutions, Transportation Hubs, Entertainment Venues, Telecommunications Firms Display Size: Small Scale, Medium Scale, Large Scale, Extra Large Scale |
| Companies Covered | Barco, Unilumin, Samsung Electronics, SiliconCore, Liantronics, Leyard, Planar Systems, Watchfire Signs, Daktronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Wall Display Market Strategic Shifts & Innovations
Pixel pitch compression and thermal management innovation are redefining competitive differentiation, while procurement models and regulatory compliance frameworks reshape how value migrates across the supply chain.
Mini-LED backlighting with thousands of local dimming zones is rendering obsolete conventional edge-lit LCD architectures in broadcast color-grading suites and medical imaging review stations. Post-production facilities in Los Angeles and London are specifying these panels for HDR mastering workflows. The technology is rendering obsolete the brightness uniformity compromises that previously forced a choice between LCD cost and LED performance in controlled ambient environments.
The EU's Ecodesign for Energy-related Products Directive is imposing maximum standby power thresholds that cascade through component sourcing decisions. Display assemblers must now qualify power supply units from a shrinking approved vendor list or invest in custom designs. Outdoor and high-brightness indoor products destined for European corporate campuses and public infrastructure face the steepest redesign requirements.
Control room operators are unbundling hardware procurement from multi-year service agreements, compressing supplier selection criteria toward response-time guarantees and spare-inventory proximity. Systems integrators in Texas and Singapore are building regional depot networks to capture this attach-rate shift. Defense and energy sector buyers in the United States and Saudi Arabia are driving the fastest adoption of this disaggregated purchasing structure.
Video Wall Display Market Segmentation
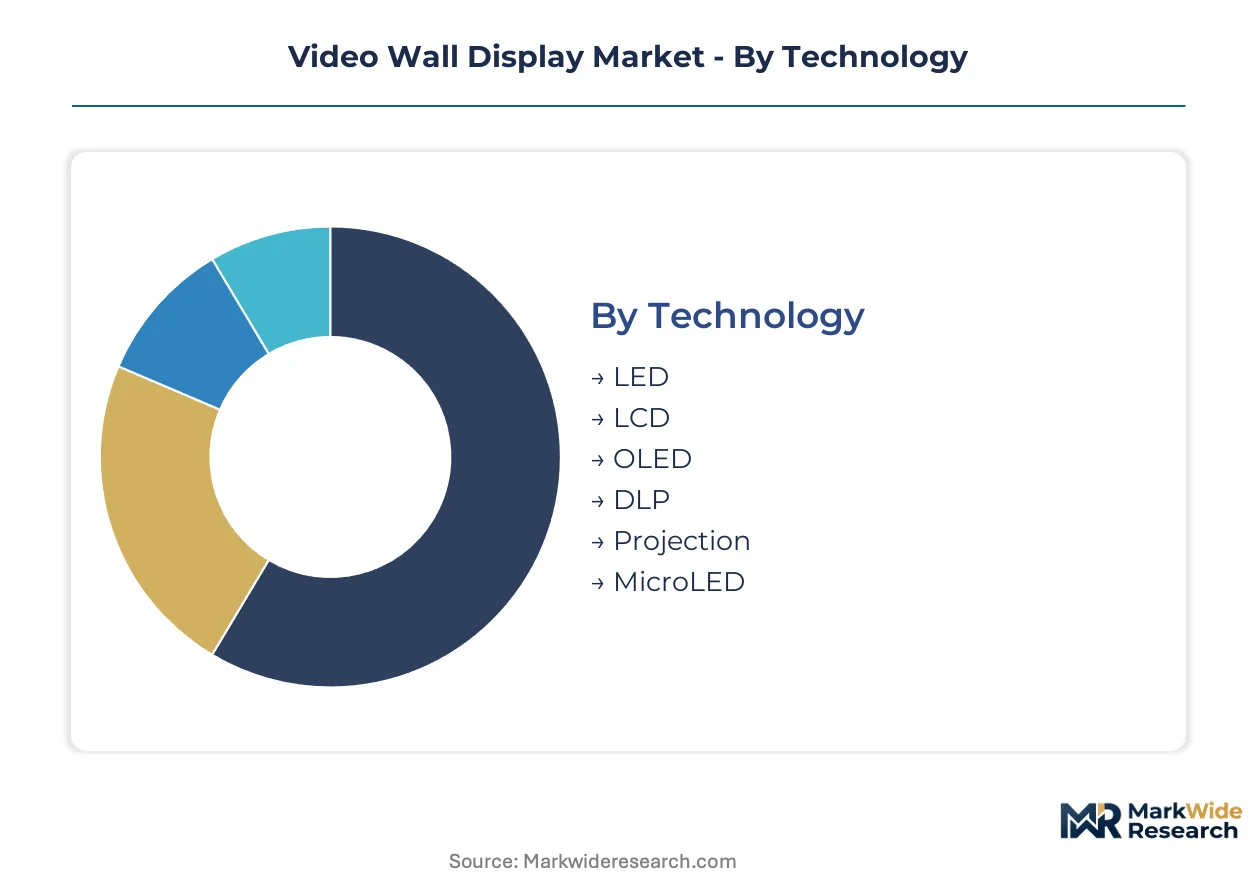
Technology selection in video wall deployments determines thermal budgets, pixel density ceilings, and service life expectations across radically different use environments. Application context and procurement authority further stratify supplier access and margin structures.
Technology:
Mature backplane technologies coexist with emerging emissive architectures, creating a bifurcated supplier landscape between scale manufacturers and specialty fabricators.
- LED:Direct-view LED tiles with chip-on-board packaging deliver 5000+ nit brightness for outdoor transit installations and daylight-viewable corporate lobbies. Municipal procurement in China's tier-one cities concentrates demand for narrow-bezel arrays in emergency operations centers.
- LCD:Thin-film transistor backplanes with LED edgelight or full-array backlighting retain cost advantages in conference rooms and retail environments where viewing distances exceed three meters. The EU's Ecodesign standby power limits are accelerating replacement cycles in German and French corporate campuses.
- OLED:Organic electroluminescent layers enable true black levels and sub-2mm bezel gaps for broadcast color-grading suites in Los Angeles and London post-production facilities.
- DLP:Digital micromirror device rear-projection cubes persist in legacy control rooms where 24/7 reliability requirements favor field-replaceable light engines.
- Projection:Laser phosphor and RGB laser systems eliminate bezel interruption entirely in museum immersive installations and theme park dark rides.
- MicroLED:Chip-scale LED transfer onto TFT substrates promises sub-100 micron pixel pitches for medical imaging review stations and high-end residential installations.
LCD retains volume leadership in indoor corporate deployments; MicroLED holds the steepest expansion curve as transfer yields improve.
Application:
Procurement authority and replacement cadence vary sharply across mission-critical infrastructure versus experiential marketing budgets.
- Control Rooms:Multi-source visualization surfaces for power grid operators and pipeline controllers demand 99.999% uptime with hot-swappable components. Long replacement cycles and stringent service-level agreements create sticky supplier relationships in Texas and Singapore energy hubs.
- Broadcast Studios:Color-accurate reference displays for on-air talent and production galleries require factory calibration to BT.2020 color space. Fine-pitch LED maturation is displacing conventional LCD dominance in London and New York broadcast facility upgrades.
- Command Centers:Unified situational awareness walls for defense and emergency management integrate radar, video feed, and data visualization streams. Saudi Arabia and United States defense sector buyers are unbundling hardware from multi-year service agreements.
- Retail Environments:Brand storytelling surfaces in flagship stores and shopping malls prioritize seamless bezel gaps over absolute color accuracy. Display-as-a-service leasing is opening mid-tier integrator access previously blocked by capital requirements.
- Sports Arenas:Jumbotron and ribbon board installations combine live action replay with advertising inventory for venue operators. High-brightness LED dominates outdoor and partially enclosed stadium configurations.
- Museums:Curatorial storytelling and immersive exhibition design are diverting capital toward laser projection systems that eliminate tiled bezel interruption entirely.
Control Rooms anchor the highest service-margin pools; Museums are gaining share fastest as experiential budgets recover.
End User:
Budget authority and technical specification sophistication diverge between public procurement frameworks and private capital deployment.
- Government Agencies:Municipal smart-city budgets in Shanghai, Beijing, and Shenzhen fund public information systems with standardized tender requirements favoring established certification holders.
- Corporate Offices:Headquarters lobby installations and executive briefing centers balance aesthetic integration with IT procurement governance.
- Educational Institutions:University research visualization labs and campus emergency operations centers represent emerging demand with limited incumbent supplier relationships.
- Transportation Hubs:Airport operations centers and rail control rooms require 24/7 reliability with regional depot proximity for spare inventory.
- Entertainment Venues:Casino operations centers and live event production companies prioritize rapid deployment flexibility over decade-long service contracts.
- Telecommunications Firms:Network operations centers for 5G infrastructure monitoring are specifying fine-pitch LED for multi-source data visualization density.
Government Agencies concentrate the largest transaction sizes; Telecommunications Firms are expanding most quickly with 5G infrastructure buildouts.
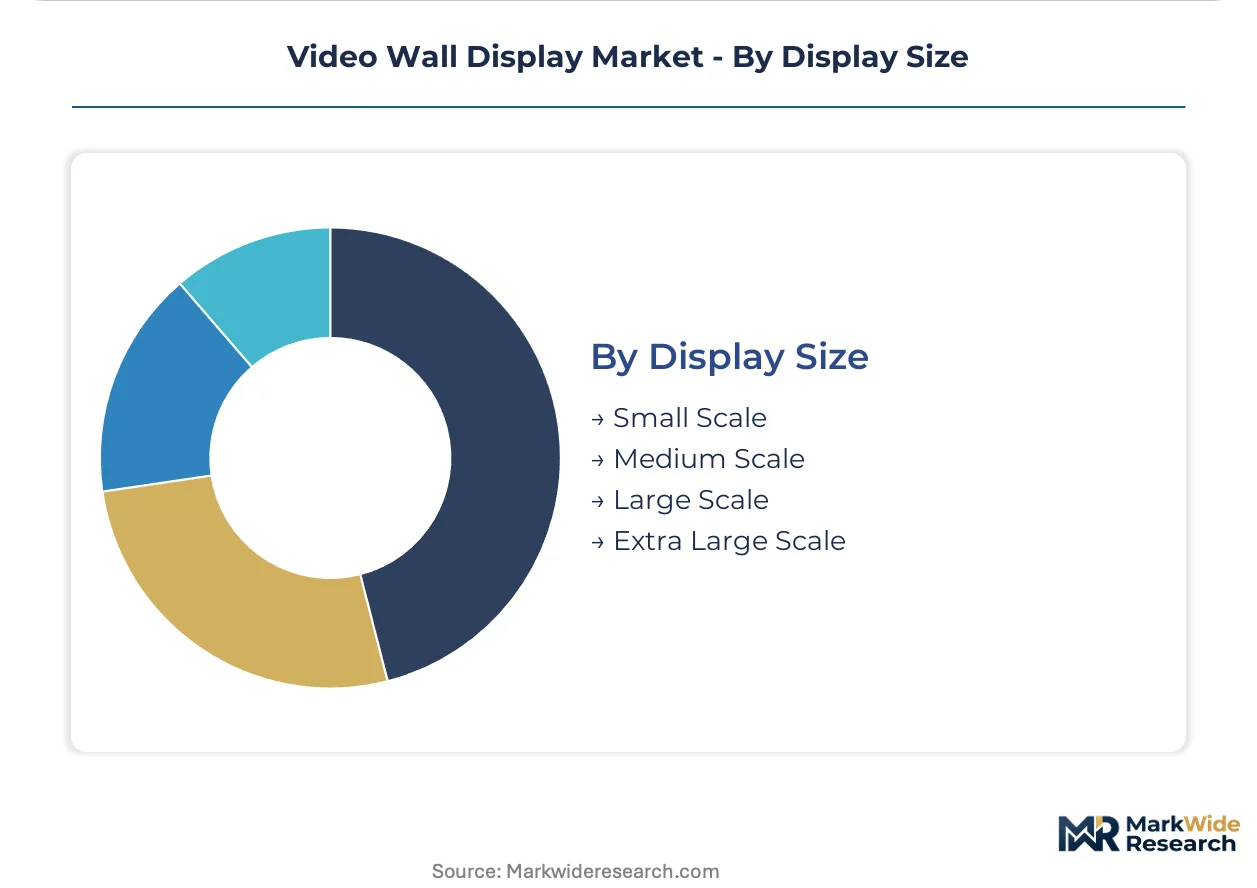
Display Size:
Physical scale determines power distribution architecture, structural mounting requirements, and installation crew specialization.
- Small Scale:Sub-100 diagonal inch configurations for conference rooms and medical imaging review stations favor LCD cost structures and standard VESA mounting.
- Medium Scale:100-300 diagonal inch arrays for corporate lobbies and broadcast production galleries balance pixel density with viewing distance optimization.
- Large Scale:300-600 diagonal inch installations for control rooms and command centers require custom structural engineering and dedicated HVAC integration.
- Extra Large Scale:600+ diagonal inch surfaces for sports arenas and public infrastructure demand modular tile architectures with field-serviceable power supplies.
Medium Scale dominates transaction volume; Extra Large Scale commands the highest project values per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ecodesign mandates in Brussels and procurement incentives in Beijing are redrawing deployment maps for large-format display infrastructure. Municipal smart-city budgets concentrate demand in specific metropolitan clusters while regulatory compliance timelines shape manufacturer market entry sequencing.
United States
Defense sector command centers and energy grid operators in Texas and the Southeast are unbundling hardware procurement from multi-year service agreements. The FCC enforces electromagnetic interference standards that extend certification timelines for imported LED driver assemblies. Houston and Dallas anchor the largest concentration of power utility control room deployments.
Germany
Industrial automation headquarters and automotive engineering centers in Bavaria and Baden-Württemberg are accelerating LCD replacement cycles. The EU's Ecodesign Directive imposes maximum standby power thresholds that cascade through component sourcing decisions. Munich and Stuttgart concentrate corporate campus deployments subject to the steepest redesign requirements.
China
Municipal smart-city budgets in Shanghai, Beijing, and Shenzhen are funding public information systems and emergency operations centers. SAMR administers national standards for display energy efficiency certification that manufacturers must obtain for domestic market access. The Yangtze River Delta and Pearl River Delta host the densest concentration of narrow-bezel LED array production.
India
State-level disaster management authorities and power grid operators are initiating first-generation video wall procurements with limited incumbent supplier relationships. BIS certification requirements for electronic safety standards shape import qualification timelines. Mumbai and Delhi-NCR represent the primary emerging demand clusters for control room infrastructure.
Saudi Arabia
Defense sector buyers and national oil company operations centers are specifying large-scale visualization surfaces with stringent uptime requirements. The country's national standards body administers conformity assessment procedures for imported electronic assemblies. Riyadh and the Eastern Province concentrate command center deployments with disaggregated purchasing structures.
Video Wall Display Market Key Industry Players
On the supply side, the industry is bifurcated between scale manufacturers commanding LCD and LED module volume and specialty fabricators focused on fine-pitch architectures. Korean and Chinese electronics conglomerates anchor manufacturing scale, while Belgian and American firms occupy premium positioning in mission-critical visualization. Three archetypes dominate: vertically integrated display assemblers, image processing specialists, and regional system integrators. Competitive moves center on backward integration into driver semiconductor sourcing and geographic expansion through regional depot networks.
Among the named players, Barco exemplifies the premium-tier specialist archetype through its positioning in control room visualization, while Samsung Electronics anchors the scale-driven manufacturing tier. Leyard occupies a position bridging specialty LED architecture with broadcast and corporate applications. These three represent distinct competitive vectors: image processing depth, manufacturing scale, and fine-pitch technology specialization.
| Leading Market Players |
|---|
| Barco |
| Unilumin |
| Samsung Electronics |
| SiliconCore |
| Liantronics |
| Leyard |
| Planar Systems |
| Watchfire Signs |
| Daktronics |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Chinese indium and gallium refining operations creates pricing tier spreads between integrated and non-integrated assemblers while forcing supply chain restructuring toward dual-source qualification programs. The concentration of LED phosphor feedstock extraction in Chinese state-controlled operations compresses margins for European and North American display manufacturers while elevating procurement risk premiums.
Pricing Analysis
Certification level (CE/FCC/CCC-grade) creates the primary spread between premium mission-critical tiers and economy municipal procurement bands. Project-based transactional pricing dominates large-scale deployments, with customization level and after-sales service bundling as secondary differentiation factors. Cost compression in the economy tier is intensifying because of indium price volatility and extended qualification timelines for RoHS-compliant solder alternatives. Municipal buyers in China's tier-one cities exhibit the highest price sensitivity due to standardized tender requirements, while defense sector buyers in Saudi Arabia and the United States prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from tier-one integrators are squeezing working capital for mid-scale LED tile assemblers and accelerating consolidation toward supplier-financing facilities. Manufacturing gravity centers on China, South Korea, and Taiwan for TFT backplanes and driver semiconductors, with Mexico emerging as a final-assembly alternative for North American defense contracts. The supply chain draws from indium phosphide substrates, gallium nitride wafers, and rare-earth phosphor compounds. Single-source vulnerability in Chinese rare-earth processing creates structural exposure to export restriction scenarios. Distribution runs through regional systems integrators with depot networks in Texas, Singapore, and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The video wall display market rewards specialized calibration expertise that is concentrated among aging technician cohorts in Japan and Germany, creating acquisition premiums for firms with captive training pipelines and proprietary uniformity-matching protocols.
For Market Incumbents: Build regional depot networks as a service-moat against disaggregated procurement trends. Samsung Electronics and Barco should expand spare-inventory proximity in Saudi Arabia and India's emerging control room markets before local integrators capture service-attach rates. Backward integration into driver semiconductor sourcing protects margin structures against Chinese feedstock volatility. Certification investment in EU Ecodesign compliance creates tender eligibility moats for European municipal smart-city contracts. For New Entrants and Emerging Players: Establish a beachhead in India's state-level disaster management procurement, where limited incumbent relationships and first-generation deployments create white-space access. Target educational institution research visualization labs with display-as-a-service leasing to bypass capital-governance barriers. Pursue casino operations centers and live event production companies in entertainment venues where rapid deployment flexibility outweighs decade-long contract requirements. Partner with regional integrators in Mumbai and Delhi-NCR to navigate BIS certification timelines. For Investors and Strategic Acquirers: The EU's Ecodesign standby power threshold enforcement reshapes the acquisition landscape toward power-supply design capabilities and approved vendor list relationships. Long-term viability over a multi-year horizon rests on software-layer recurring revenue from AI-driven content automation in security and transportation command centers. Target acquisition archetypes include fine-pitch LED specialists with broadcast studio relationships and regional integrators with established depot networks. Monitor FCC pre-market authorization timeline extensions as an inflection signal for Asian manufacturer market entry sequencing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver Semiconductors | Captive sourcing of gallium nitride wafers insulates margin structures from Chinese rare-earth volatility. |
| Regional Depot Network Expansion | Spare-inventory proximity in Texas and Singapore captures service-attach revenue from unbundled procurement. |
| Display-as-a-Service Leasing Launch | Subscription hardware provisioning opens municipal and education buyers blocked by upfront capital requirements. |
| AI Content Automation Platform Development | Computer vision convergence creates recurring software revenue in security and transportation command centers. |
| Dual-Source Rare-Earth Qualification | Non-Chinese indium and gallium sourcing programs reduce single-source dependency exposure. |
Research Approach
A spread of perspectives from control room operators, broadcast engineering directors, municipal procurement officers, and LED tile manufacturing executives converged on the working assumptions driving this analysis. Primary interviews with systems integrators in Texas, Singapore, and Germany were cross-validated against secondary sources including FCC equipment authorization databases, EU Ecodesign implementing measure texts, SAMR national standard filings, and customs records for display panel trade flows. Bottom-up triangulation of project-level deployment data with top-down manufacturer revenue segmentation anchored the market sizing framework.
Demand-supply balance dynamics across the projection horizon were modeled through technology-specific adoption curves and replacement cycle analysis. Segmentation dimensions include display technology (LED/LCD/OLED/MicroLED), application context (control room/broadcast studio/command center/retail), end-user procurement authority (government agency/corporate/telecommunications), and physical scale tier. CAGRs were derived from installed base evolution and average selling price trajectory analysis. Industry-specific forecast inputs encompassed municipal smart-city budget allocations in China's tier-one cities and defense sector unbundled procurement adoption rates.
Stress conditions across indium price volatility bands, FCC certification timeline extensions, and EU standby power threshold enforcement scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology substitution rates and regulatory implementation schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Electrochromic Window Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Rental Outdoor LED Display Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Flexible Display Market
Display Technologies
Portable Projector Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Gaming Monitors Market
Display Technologies
Global Display Panel Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
Smart Privacy Glass Market
Display Technologies
Transparent Digital Signage Market
Display Technologies
Display Material Market
Display Technologies
Flat Panel Display (FPD) Market