
 High Voltage Commercial Switchgear Market | 2026-2036
High Voltage Commercial Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Commercial Switchgear Market Insights
Project finance and power purchase agreement-backed leasing structures is tilting competitive dynamics toward firms with balance-sheet capacity to underwrite long-term service contracts. Siemens leverages its digital twin platform to anchor service revenue streams across installed base fleets. ABB sustains leadership in gas insulated systems through captive supply of high-voltage components and in-house production of switchgear enclosures. Mitsubishi Electric dominates the Asia-Pacific project pipeline with localized manufacturing scale and utility channel control.
High voltage commercial switchgear encompasses electrical apparatus rated above 36 kV designed to control, protect, and isolate power circuits in commercial and industrial infrastructure, typically employing SF6, vacuum, or air as interrupting mediums within metal-clad enclosures. These systems perform critical fault clearance and load switching functions that preserve grid stability across transmission and primary distribution networks. Gas insulated switchgear commands the premium tier due to compact footprint requirements in dense urban substations, while vacuum circuit breakers gain share in renewable integration projects where maintenance minimization drives procurement criteria. Digital control and microprocessor based protection technologies are capturing margin pools as utilities prioritize predictive diagnostics over conventional electromechanical relay systems.
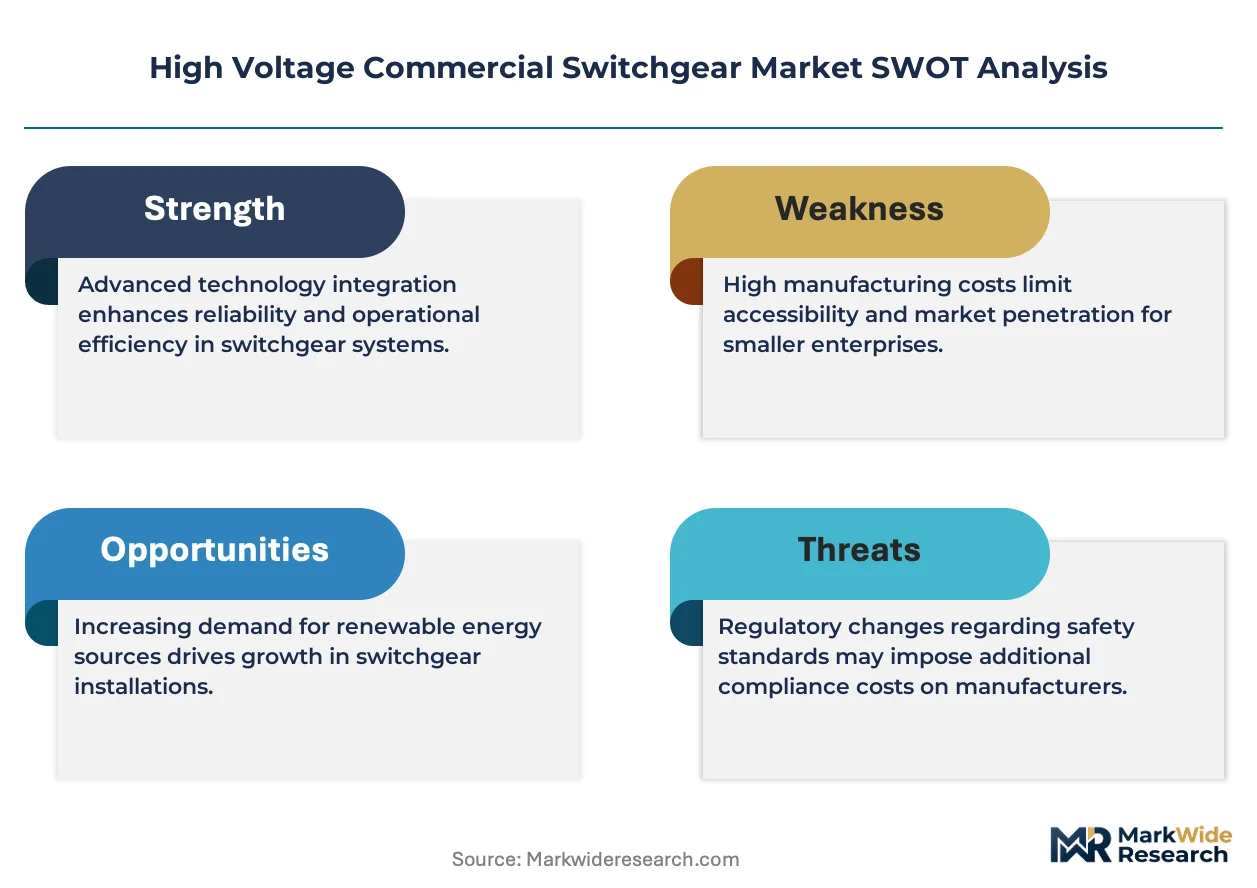
EPA regulations targeting SF6 emission reductions are forcing product redesign timelines across North American manufacturers, while IEC 62271 standards govern dielectric withstand and short-circuit certification requirements for international market access. ECHA scrutiny under REACH protocols is accelerating European development of fluoronitrile-based insulating alternatives to sulfur hexafluoride. Grid operators and EPC contractors must monitor regulatory divergence between EPA phase-down schedules and EU F-Gas Regulation amendment timelines when specifying switchgear procurement standards.
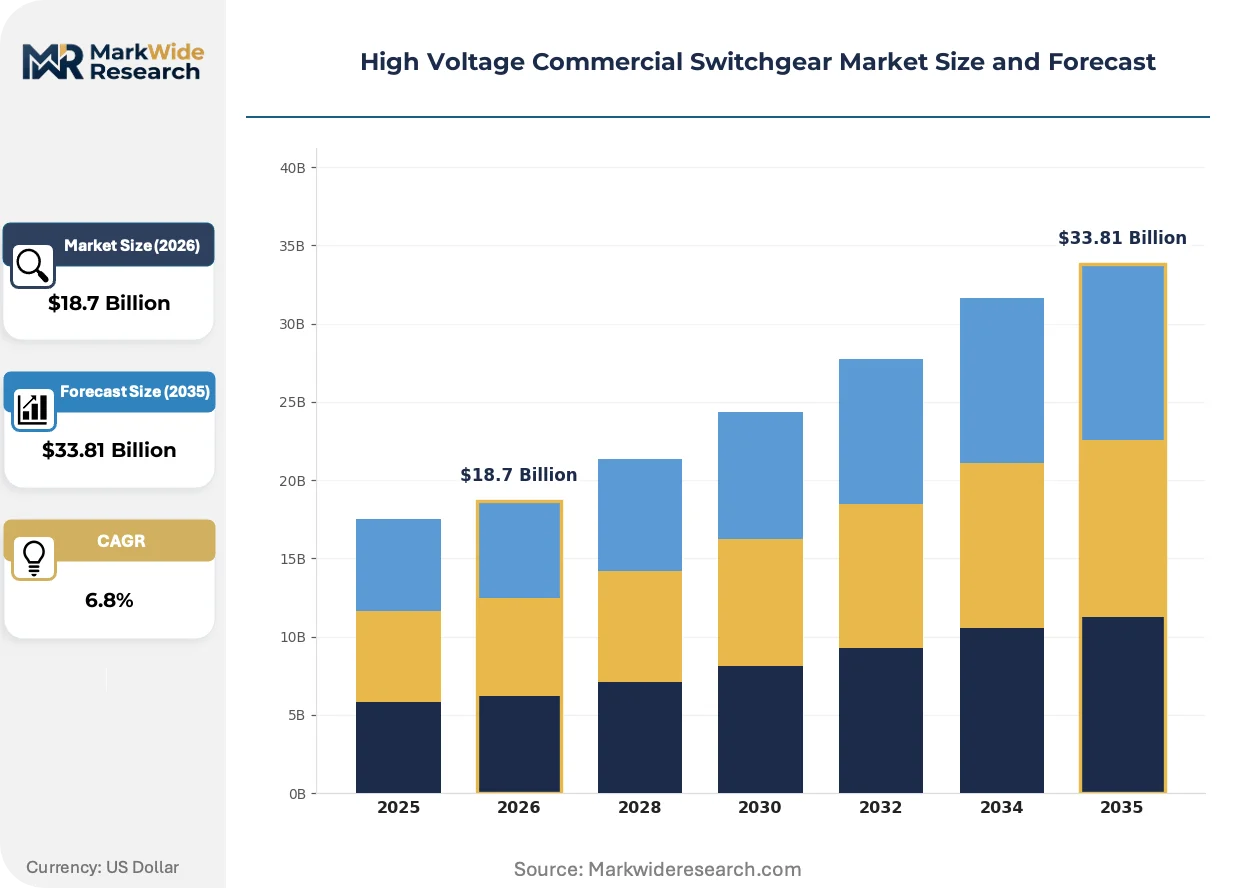
Market Dynamics
EPA emission curbs on SF6 and EU F-Gas Regulation amendments are forcing simultaneous product redesign across North American and European manufacturing footprints, compressing development timelines while elevating R&D recovery requirements.
Growth Catalysts
- Data center power density thresholds:Hyperscale cloud operators in Northern Virginia and Frankfurt are specifying gas insulated switchgear to manage load concentrations exceeding 50 MW per facility, creating dedicated procurement pipelines for compact substation designs.
- EU Green Deal grid modernization mandates:Transmission system operators in Germany and Spain must replace electromechanical protection systems with digital controls by statutory deadlines, accelerating replacement cycles across installed base fleets.
- Fluoronitrile dielectric commercialization:ECHA scrutiny under REACH protocols is validating alternative insulating mediums that eliminate sulfur hexafluoride dependence, opening certification pathways for next-generation product lines.
Market Restraints
- Copper and aluminum price volatility:Conductive material costs constitute 35-45% of switchgear bill-of-materials, exposing margin structures to London Metal Exchange commodity swings without pass-through mechanisms in legacy contracts.
- SF6 banked inventory depreciation risk:Utilities holding substantial sulfur hexafluoride reserves face stranded asset exposure as EPA phase-down schedules accelerate, forcing write-downs against maintenance-dependent revenue models.
- Vacuum interrupter ceramic supply concentration:High-purity alumina ceramic production for vacuum circuit breaker bottles clusters in Japanese and Chinese supplier networks, creating single-source vulnerability for Western OEMs.
Strategic Opportunities
- India transmission investment acceleration:Central Electricity Authority mandates for 765 kV network expansion are generating tender volumes exceeding $4 billion annually, with localization requirements favoring joint-venture manufacturing structures.
- Predictive diagnostics service unbundling:Digital twin platforms enabling remote thermal monitoring and partial discharge detection are creating recurring revenue streams separate from hardware procurement, extending customer lifetime value.
- Offshore wind collector platform electrification:North Sea and US Atlantic Coast lease rounds are specifying 66 kV and 132 kV gas insulated switchgear for offshore substations, opening marine-certified product categories with premium pricing.
Industry Challenges
- IEC 62271-200 type test certification bottlenecks:Dielectric withstand and internal arc classification protocols require 12-18 month validation cycles at accredited laboratories, delaying product launches and freezing design iterations.
- Legacy electromechanical relay skill attrition:Utilities face technician shortages for maintaining installed base protection systems while simultaneously recruiting digital control specialists, compressing workforce transition timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Commercial Switchgear Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Insulated, Air Insulated, Vacuum Circuit Breakers, SF6 Circuit Breakers, Oil Circuit Breakers Technology: Electromechanical Mechanism, Digital Control, Remote Monitoring, Automatic Transfer, Microprocessor Based Protection Application: Power Generation Plants, Renewable Power Stations, Heavy Industry, Transmission Networks, Large Infrastructure Projects End User: Utility Companies, Industrial Enterprises, EPC Contractors, Government Authorities, Power Distributors |
| Companies Covered | ABB, Siemens, Schneider Electric, Eaton, Hitachi Energy, Mitsubishi Electric, General Electric, Toshiba, Fuji Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Commercial Switchgear Market Trends and Innovations
Digital control architectures and fluorinated gas alternatives are converging to redefine product specifications, with regulatory compliance emerging as the primary design constraint rather than pure technical performance.
Hybrid insulating systems combining vacuum interrupters with fluoronitrile buffer gases are hybridizing conventional gas insulated switchgear designs. Offshore wind developers in the North Sea and US Atlantic Coast are specifying these configurations for platform applications where maintenance access is restricted. The technology is hybridizing procurement criteria across European transmission operators, compressing the market for pure SF6-dependent product lines.
EU F-Gas Regulation amendment timelines are accelerating faster than EPA phase-down schedules, creating divergent certification requirements for multinational OEMs. Manufacturers must maintain parallel product portfolios or accept market exclusion from one regulatory jurisdiction. Grid operators in Germany and France are advancing procurement specifications that anticipate 2030 fluorinated gas bans, forcing design commitments ahead of regulatory certainty.
Asset performance guarantees are displacing conventional equipment sales across utility procurement departments. Siemens and ABB are restructuring offerings around uptime commitments and predictive maintenance outcomes rather than unit-based pricing. This transformation is most visible in United Kingdom and Netherlands distribution network operator tenders, where 15-20 year service contracts now accompany primary switchgear awards.
High Voltage Commercial Switchgear Market Segmentation
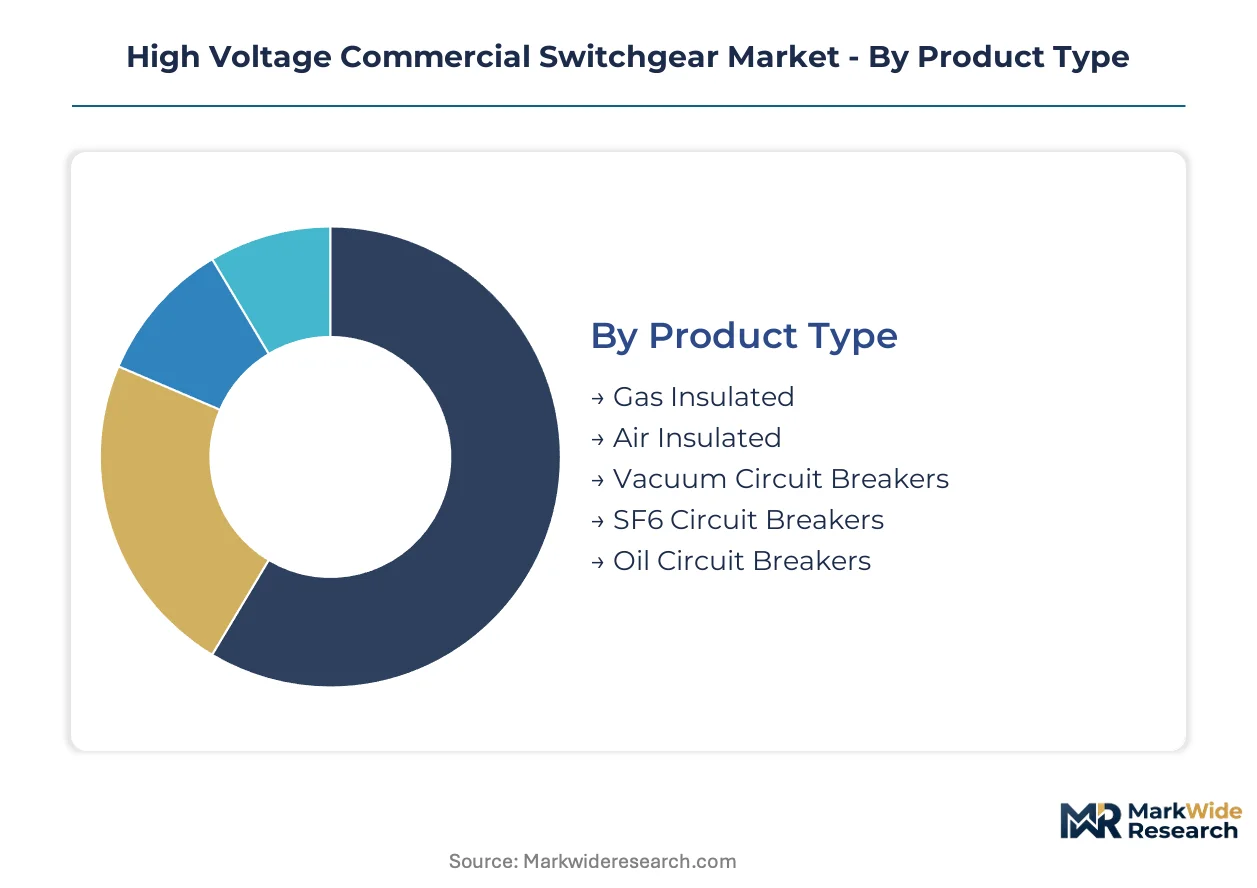
Segmentation in high voltage commercial switchgear reveals how technology maturity, regulatory pressure, and end-use specialization create distinct commercial battlegrounds. Product architecture and control technology choices now determine margin sustainability more than raw capacity ratings.
Product Type:
Mature SF6-dependent designs coexist with emerging alternatives across this spectrum, with footprint constraints and emission regulations driving portfolio transitions.
- Gas Insulated:Compact metal-enclosed designs employ pressurized sulfur hexafluoride or fluoronitrile alternatives as dielectric mediums, achieving 90% space reduction versus air-insulated equivalents. Hyperscale data centers in Northern Virginia and Frankfurt specify these systems for substations handling loads exceeding 50 MW per facility.
- Vacuum Circuit Breakers:Ceramic-bottled vacuum interrupters eliminate atmospheric dependence, offering maintenance intervals exceeding 15 years. Renewable integration projects in Spain and Germany favor these for remote wind and solar sites where service access is costly.
- Air Insulated:Conventional open-air designs with porcelain insulators dominate retrofit markets and cost-sensitive utility procurement.
- SF6 Circuit Breakers:Legacy sulfur hexafluoride technology retains installed base relevance despite EPA phase-down pressures.
- Oil Circuit Breakers:Mineral oil interruption systems persist in aging transmission infrastructure requiring minimal capital outlay.
Gas insulated retains volume leadership; vacuum circuit breakers hold the steepest expansion curve.
Technology:
Control architecture sophistication separates premium procurement tiers from commodity replacement cycles.
- Digital Control:Microprocessor-based protection relays with IEC 61850 communication protocols enable real-time fault coordination and remote configuration. German transmission operators under EU Green Deal mandates must deploy these systems by statutory deadlines, accelerating replacement of electromechanical predecessors.
- Microprocessor Based Protection:Embedded algorithms process current and voltage transients for selective tripping, reducing outage scope. Indian utilities expanding 765 kV networks specify these for new substations to minimize cascading failure risk.
- Electromechanical Mechanism:Spring-charged or solenoid-operated tripping systems persist in legacy installations.
- Remote Monitoring:Sensor networks transmitting thermal and partial discharge data to centralized diagnostics platforms.
- Automatic Transfer:Source switching logic for dual-feed reliability in critical infrastructure.
Digital control commands the premium tier; remote monitoring is climbing the fastest as utilities unbundle service contracts from hardware sales.
Application:
Load characteristics and reliability requirements shape specification intensity across deployment contexts.
- Transmission Networks:Ultra-high voltage switching stations rated 245 kV and above manage inter-regional power flows with fault clearance times under 100 milliseconds. China's State Grid and India's Power Grid Corporation drive tender volumes exceeding billions annually for network expansion.
- Renewable Power Stations:Collector substations for wind and solar farms require frequent switching cycles and harmonic tolerance. North Sea offshore wind developers specify marine-certified gas insulated switchgear for 66 kV and 132 kV collector platforms.
- Power Generation Plants:Generator circuit breakers and unit auxiliary switchgear for thermal and nuclear facilities.
- Heavy Industry:Arc furnace and motor starting applications demanding high mechanical endurance.
- Large Infrastructure Projects:Metro systems, airports, and hospitals requiring dual-source reliability.
Transmission networks retain volume leadership; renewable power stations hold the steepest expansion curve.
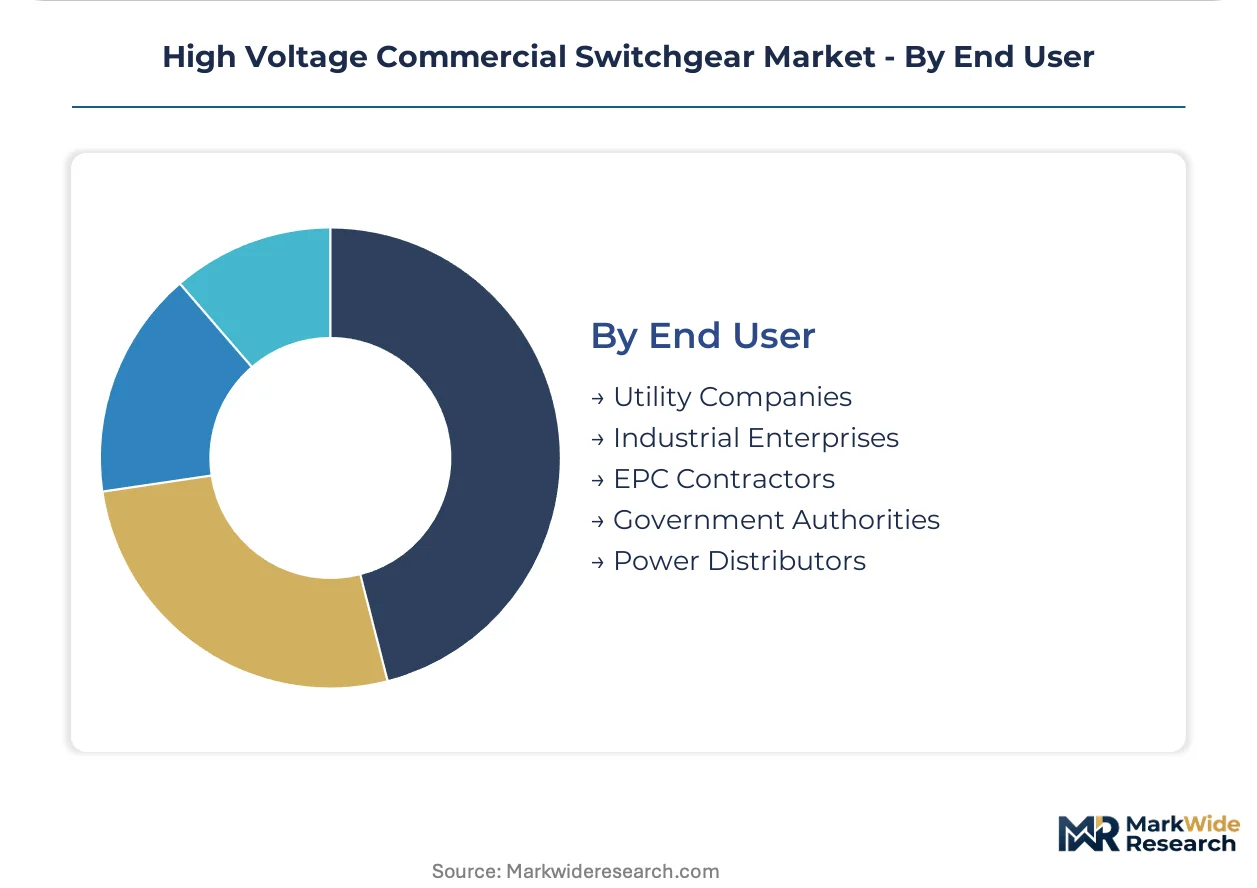
End User:
Procurement sophistication and contract structure preferences segment the customer base.
- Utility Companies:Vertically integrated transmission and distribution operators with standardized technical specifications and multi-year framework agreements. United Kingdom and Netherlands distribution network operators now bundle 15-20 year service contracts with primary switchgear awards.
- EPC Contractors:Engineering-procurement-construction firms executing turnkey substation projects with lump-sum risk transfer. These buyers prioritize equipment availability and documentation compliance over unit economics.
- Industrial Enterprises:Self-supplied manufacturers and mining operations with captive generation.
- Government Authorities:Public infrastructure agencies with procurement governed by public tender regulations.
- Power Distributors:Regional and municipal utilities with fragmented purchasing authority.
Utility companies retain volume leadership; EPC contractors hold the steepest expansion curve as project finance structures concentrate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in high voltage commercial switchgear tilt toward import-dependent markets with aggressive grid expansion programs, while manufacturing concentration in Germany, Japan, and China shapes regional supply availability. Export volumes from these production centers service utility procurement across emerging markets where domestic fabrication capacity remains underdeveloped. Currency volatility and localized content mandates increasingly determine contract award outcomes.
United States
Data center load growth in Northern Virginia and Texas drives 50 MW-plus substation deployments requiring compact gas insulated designs. EPA phase-down schedules for SF6 force product redesign commitments ahead of regulatory deadlines. Chicago and Phoenix utility corridors concentrate procurement authority for transmission network upgrades.
Germany
Transmission system operators under EU Green Deal mandates must replace electromechanical protection with digital controls by statutory deadlines. ECHA scrutiny of fluorinated gases accelerates fluoronitrile dielectric validation programs. Industrial clusters in Bavaria and North Rhine-Westphalia anchor manufacturing scale for 765 kV-rated systems.
China
State Grid Corporation tenders exceed billions annually for ultra-high voltage network expansion across western provinces. MIIT localization requirements favor joint-venture structures for foreign OEMs seeking market access. Yangtze River Delta manufacturing bases supply domestic and export demand for gas insulated switchgear.
India
Central Electricity Authority mandates for 765 kV transmission expansion generate annual tender volumes concentrated in western and southern states. BIS certification requirements and PLI scheme incentives shape procurement specifications. Gujarat and Maharashtra industrial corridors host joint-venture manufacturing for localized production compliance.
Japan
High-purity alumina ceramic supply for vacuum interrupter bottles concentrates production networks serving domestic and export OEM demand. METI efficiency standards drive digital control adoption in utility replacement cycles. Osaka-Nagoya industrial zones maintain specialized component fabrication for circuit breaker assemblies.
High Voltage Commercial Switchgear Market Competitive Landscape
On the supply side, the industry is consolidating around integrated electrical equipment conglomerates with captive high-voltage component production and long-term service contract capabilities. Three strategic archetypes dominate: full-system integrators with digital twin platforms, gas insulation specialists with fluoronitrile alternative pipelines, and vacuum interrupter manufacturers with ceramic supply chain control. Competitive dynamics center on backward integration into switchgear enclosures and predictive diagnostics service unbundling.
Among European-based industrial conglomerates, ABB and Siemens occupy positions exemplifying the integrated-system archetype, anchoring premium-tier competition through balance-sheet capacity for long-term service underwriting. Mitsubishi Electric represents the Asia-Pacific manufacturing scale model, with localized production networks aligned to regional utility procurement channels. These three entities illustrate how geographic manufacturing footprint and regulatory anticipation capabilities separate market tiers.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Eaton |
| Hitachi Energy |
| Mitsubishi Electric |
| General Electric |
| Toshiba |
| Fuji Electric |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta freight corridors transmit cost volatility from Chinese manufacturing clusters into European and North American procurement decisions, compressing margin structures for gas insulated switchgear while amplifying price differentiation between SF6-dependent legacy systems and fluoronitrile-certified alternatives.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that stratifies across premium, standard, and economy tiers. Price differentiation rests on IEC 61850 certification grade and volume scale commitments, with hyperscale data center operators showing least price sensitivity due to uptime guarantee requirements. Cost compression in the standard tier is intensifying because copper and aluminum commodity exposure lacks pass-through mechanisms in legacy framework agreements. Municipal utilities with fragmented purchasing authority exhibit highest price sensitivity, driving procurement toward air-insulated retrofit options.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for Western OEMs sourcing high-purity alumina ceramic bottles. Manufacturing gravity centers on Germany, Japan, and China for vacuum interrupter assemblies and gas-insulated enclosure fabrication. Raw material dependencies draw from copper cathode, high-grade aluminum, and sulfur hexafluoride reserves facing EPA phase-down restrictions. Single-source vulnerability concentrates in Japanese ceramic suppliers for vacuum circuit breaker bottles. Distribution runs through EPC contractor networks and utility framework agreements with multi-year equipment scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry opportunities as EU F-Gas Regulation divergence from EPA timelines splits product certification requirements, generating parallel demand streams for region-specific switchgear designs.
For Market Incumbents: Pre-empt fluoronitrile alternative certification bottlenecks by accelerating IEC 62271-200 type test submissions at accredited laboratories before statutory deadlines compress validation windows. Captive supply of high-voltage components and in-house production of switchgear enclosures defends margin position against commodity cost volatility. Balance-sheet capacity for 15-20 year service contract underwriting anchors customer retention against emerging digital twin platform competitors. For New Entrants and Emerging Players: Establish a beachhead in India's 765 kV transmission expansion pipeline through joint-venture manufacturing structures satisfying BIS certification and PLI scheme localization requirements. Vacuum circuit breaker segments for renewable integration projects offer lowest incumbent density, with remote monitoring service unbundling providing recurring revenue entry without capital-intensive hardware fabrication. Target EPC contractor procurement channels with equipment availability guarantees and documentation compliance speed. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core electrical equipment divisions amid portfolio rationalization pressures. Long-term viability over the medium-term projection horizon rests on digital control architecture capabilities and fluoronitrile alternative pipelines rather than SF6-dependent installed base maintenance. Monitor EPA enforcement intensity and EU F-Gas Regulation amendment ratification as inflection indicators for stranded asset risk in legacy technology portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Supply | Japanese alumina bottle production concentration creates acquisition targets for vacuum interrupter OEMs seeking supply security. |
| Fluoronitrile Certification Acceleration | ECHA validation timelines determine market access eligibility across EU Green Deal procurement mandates in Germany and Spain. |
| Digital Twin Platform Deployment | Siemens' predictive diagnostics service unbundling demonstrates recurring revenue capture from utility fleet management contracts. |
| Joint Venture Manufacturing Localization | MIIT requirements in China and CEA mandates in India necessitate domestic production partnerships for tender eligibility. |
| Offshore Wind Marine Certification | North Sea and US Atlantic Coast lease rounds specify 66 kV and 132 kV gas insulated switchgear with premium pricing potential. |
Research Methodology
A standing panel of utility planning officers, EPC contractor procurement leads, switchgear maintenance directors, and grid operator protection engineers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from IEC certification databases, EPA regulatory filings, ECHA REACH substance evaluations, and customs trade data for copper and aluminum imports. Bottom-up equipment shipment tracking and top-down transmission investment budget analysis enabled triangulation across independent estimation approaches.
Scenario-bracketing framed analytical development across the projection horizon, with CAGRs derived from regression analysis against historical tender volumes and capital expenditure commitments. Segmentation dimensions modeled include product architecture, control technology sophistication, application voltage tier, and end-user procurement structure. Forecast inputs incorporated data center power density trajectories, renewable integration targets, and regulatory phase-down schedules without assuming technology substitution rates.
Sensitivities concentrate around EPA enforcement intensity, EU F-Gas Regulation amendment timing, and copper price volatility transmission through contract structures. Forecasts reflect assumptions about certification pathway availability and utility workforce transition capacity for digital control adoption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
Waveguide Market
Electrical Equipment
High Voltage Electric Capacitor Market
Electrical Equipment
Global EMC Filtration Market
Electrical Equipment
Alligator Clips Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
Low Voltage Electric Motor Market
Electrical Equipment
United States Frequency Converter Market
Electrical Equipment
Surface Mounting Distribution Panel Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
Capacitor Bank Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
Flexible Heating Element Market
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market