
 Asia Pacific Graphene Market | 2026-2036
Asia Pacific Graphene Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Graphene Market Insights
Electric vehicle battery makers are redrawing procurement priorities away from legacy carbon additives, pulling graphene nanoplatelets into high-volume cathode formulations. The Sixth Element Materials Technology Co., Ltd anchors production scale in Changzhou with tonnage-grade output for composite manufacturers. Xiamen Knano Graphene Technology Corporation Limited specializes in thermal interface materials for semiconductor packaging. Applied Graphene Materials competes on liquid-phase exfoliation purity grades that satisfy European automotive Tier 1 specifications.
Graphene denotes a single-atom-thick hexagonal lattice of sp2-bonded carbon atoms with electron mobility exceeding 200,000 cm2/V·s, manufactured via chemical vapor deposition on copper foils or liquid-phase exfoliation of graphite for conductive inks and structural reinforcement. Graphene nanoplatelets currently dominate volume shipments due to lower production costs and established dispersion protocols in polymer masterbatch operations. Graphene oxide retains premium pricing in biomedical and membrane separation applications where surface functionalization controls selectivity. Chemical vapor deposition capacity expansion in South Korea and Taiwan is tightening equipment lead times for graphene film deposition systems.
China's MIIT enforces GB standards for graphene powder purity and flake size distribution, while Japan's METI coordinates JIS certification pathways for electronics-grade material qualification. South Korea's MFDS maintains separate biocompatibility protocols for graphene-enabled medical devices, fragmenting regulatory compliance burdens across the region. Stakeholders must track evolving national standards divergence to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Electronics manufacturers in South Korea and Taiwan are accelerating procurement of graphene films for flexible display backplanes, while China's dual carbon goals and Japan's METI green technology standards tighten material traceability requirements across the supply chain.
Growth Catalysts
- Flexible Display Backplane Demand:South Korean and Taiwanese electronics manufacturers are pulling graphene films into OLED and foldable screen production lines at accelerating rates.
- Dual Carbon Goals:China's national decarbonization framework is mandating lightweight composite adoption in transportation and construction end-uses.
- GB Standards Enforcement:MIIT-mandated purity and flake size specifications are standardizing quality benchmarks, reducing buyer qualification friction.
Market Restraints
- Copper Foil Input Volatility:Chemical vapor deposition feedstock costs fluctuate with battery-grade copper demand, compressing film producer margins.
- Equipment Lead Time Concentration:Graphene film deposition system manufacturers in South Korea face 18-month order backlogs, throttling capacity expansion.
- Liquid-Phase Extraction Purity Ceiling:Scalable graphite exfoliation methods struggle to achieve electronics-grade defect densities below 10^12 cm^-2.
Strategic Opportunities
- Indian Battery Supply Chain:PLI scheme incentives for domestic cell manufacturing create virgin demand for graphene nanoplatelet conductive additives.
- Semiconductor Thermal Interface Penetration:Advanced packaging architectures in Taiwan and South Korea are opening specification slots for graphene-enhanced heat spreaders.
- Biocompatibility Protocol Harmonization:MFDS medical device pathways in South Korea could extend to regional mutual recognition, reducing multi-country filing costs.
Industry Challenges
- Dispersion Chemistry Expertise Gap:Polymer masterbatch formulators lack trained technicians for stable graphene nanoplatelet suspension in high-shear compounding operations.
- Cross-Border Certification Timelines:Divergent JIS, GB, and MFDS testing protocols force producers to maintain parallel qualification inventories.
- Legacy Carbon Black Integration Friction:Battery cathode lines require revalidation of entire slurry mixing workflows when substituting graphene for conventional conductive additives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Graphene Market |
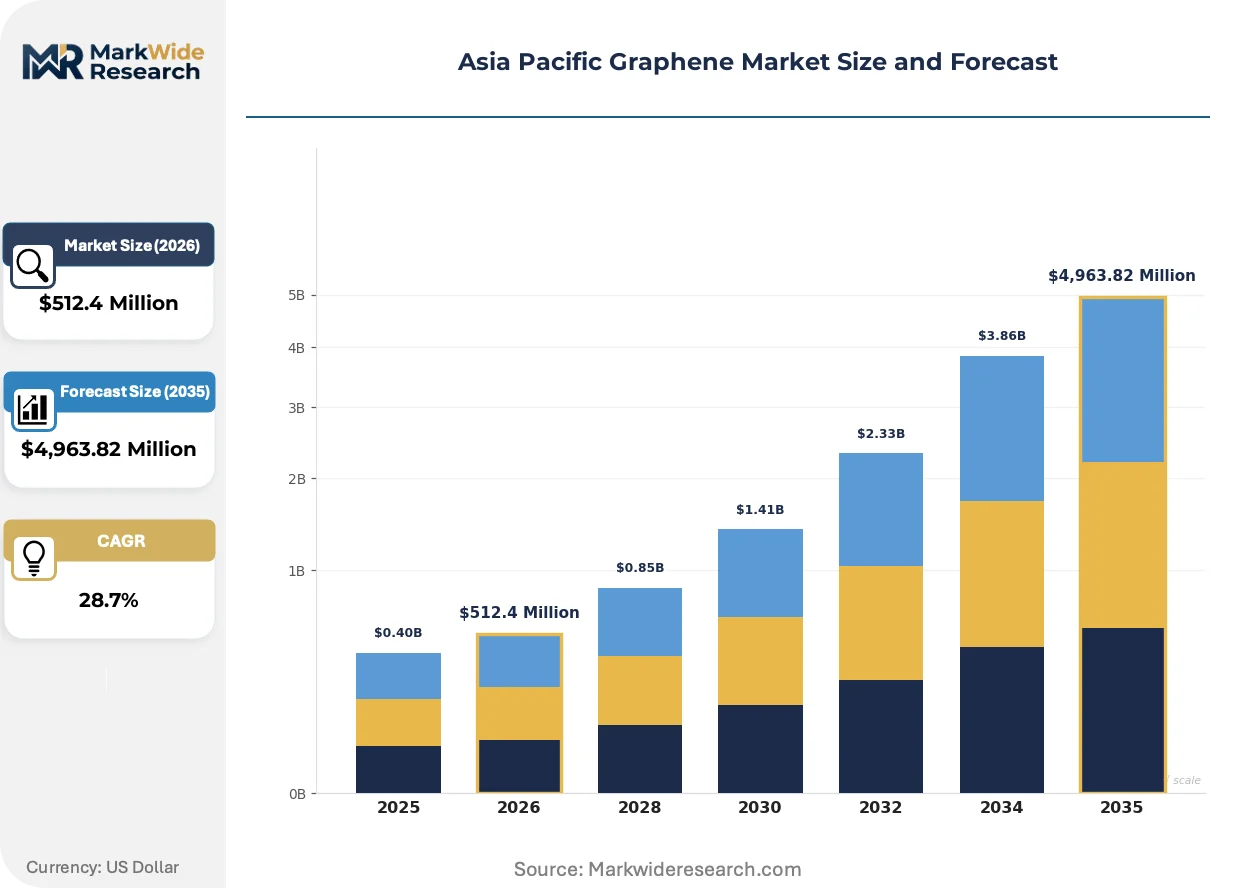
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $4,963.82 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphene Oxide, Reduced Graphene Oxide, Graphene Nanoplatelets, Graphene Films Application: Electronics, Energy Storage, Composites, Coatings End User: Automotive, Aerospace, Consumer Electronics, Healthcare Technology: Chemical Vapor Deposition, Liquid Phase Exfoliation, Mechanical Exfoliation, Others |
| Companies Covered | Miraculum Graphene Pvt. Ltd, Applied Graphene Materials, The Sixth Element Materials Technology Co., Ltd, Global Graphene Group, XFNANO Materials Tech Co., Ltd, Xiamen Knano Graphene Technology Corporation Limited, NeoGraf Solutions, Graphene NanoChem plc, Platonic Nanotech, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Graphene Market Trends and Innovations
Production methodologies are diverging between premium film applications and mass-market powder segments, with regulatory fragmentation forcing parallel technical development tracks across the region.
Chemical vapor deposition graphene is bifurcating into two quality tiers: copper-foil-grown monolayers for transparent electrodes and multi-layer stacks for structural reinforcement. Display manufacturers in Taiwan specify single-domain films exceeding 30 cm width, while composite producers accept polycrystalline material at one-fifth the unit cost. This split is compressing equipment utilization rates as deposition tool configurations specialize.
METI's green technology standards are mandating lifecycle carbon accounting for imported graphene materials, with traceability documentation required from graphite feedstock through final synthesis. Japanese automotive Tier 1 suppliers now exclude Chinese-origin material lacking ISO 14064-verified emission footprints. South Korean battery producers are responding by qualifying domestic chemical vapor deposition capacity to preserve Japan market access.
Specification-driven procurement is displacing spot-market purchasing as cathode manufacturers consolidate supplier bases to three qualified graphene nanoplatelet sources per plant. Long-term offtake agreements with minimum volume commitments now dominate Yangtze River Delta chemical supply negotiations. This concentration is most visible in Changzhou, where composite masterbatch producers have abandoned merchant market sourcing entirely.
Asia Pacific Graphene Market Segmentation
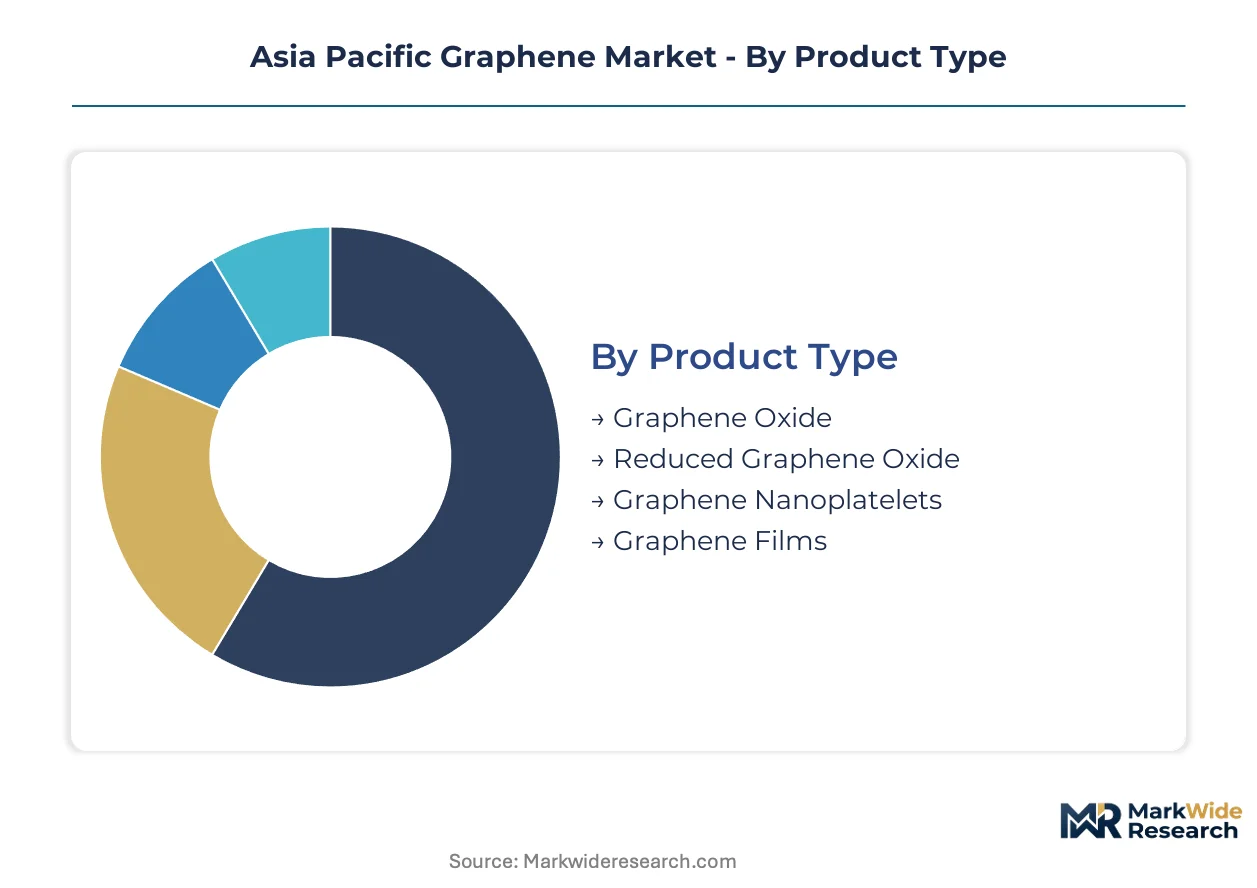
Product differentiation in Asia Pacific graphene markets tracks sharply divergent purity requirements and manufacturing scale economics. Electronics-grade film commands premium positioning against tonnage-grade powder applications, while regulatory fragmentation across MIIT, METI, and MFDS jurisdictions forces parallel qualification tracks.
Product Type:
Graphene nanoplatelets capture the widest margin pools through established polymer masterbatch integration, while graphene oxide retains specialty pricing power in biomedical membrane applications.
- Graphene Nanoplatelets:These multi-layer carbon structures stack 5-10 nm thick with lateral dimensions from 0.3-50 micrometers, offering the optimal cost-performance ratio for conductive polymer formulations. Battery cathode manufacturers in South Korea and Taiwan are consolidating procurement around three qualified suppliers per plant, locking in volume commitments that stabilize producer margins.
- Graphene Films:Monolayer and few-layer sheets grown via chemical vapor deposition on copper foils achieve electron mobility exceeding 200,000 cm2/V·s, enabling transparent electrode applications. Display backplane demand from Taiwanese and South Korean OLED producers is stretching equipment lead times to 18 months, constraining capacity expansion despite price premiums.
- Graphene Oxide:Oxygen-functionalized derivative enables aqueous dispersion and surface chemistry control for membrane separations.
- Reduced Graphene Oxide:Thermally or chemically restored conductivity bridges powder and film performance tiers at intermediate cost points.
Graphene nanoplatelets hold installed capacity across eastern China's Yangtze River Delta cluster. Graphene films are rotating up the share rankings on flexible display procurement acceleration.
Application:
Electronics applications concentrate value capture in semiconductor thermal interface materials, while energy storage scales fastest on electric vehicle battery cathode reformulation.
- Electronics:Thermal spreaders and transparent conductors exploit graphene's anisotropic heat conduction and optical transparency. Advanced packaging architectures in Taiwan and South Korea are opening specification slots for graphene-enhanced heat spreaders as chip power densities climb.
- Energy Storage:Conductive additives in lithium-ion cathodes and emerging solid-state electrolyte composites drive volume procurement. China's dual carbon goals are mandating lightweight composite adoption that pulls nanoplatelets into high-volume cathode formulations, displacing legacy carbon black.
- Composites:Structural reinforcement in automotive and aerospace components leverages specific strength advantages over carbon fiber.
- Coatings:Anti-corrosion and conductive surface treatments target industrial infrastructure and electronic enclosure applications.
Electronics maintains qualification depth across Japanese automotive Tier 1 suppliers. Energy storage is climbing the fastest on cathode manufacturer consolidation.
End User:
Automotive procurement is restructuring around battery supply chain localization, while consumer electronics retains specification leadership through display technology iteration.
- Automotive:Electric vehicle battery packs and lightweight structural components absorb the majority of regional nanoplatelet output. India's PLI scheme incentives for domestic cell manufacturing are creating virgin demand for conductive additives as battery makers redraw procurement priorities.
- Consumer Electronics:Foldable display backplanes and thermal management solutions specify the highest-purity film grades. South Korean and Taiwanese manufacturers are accelerating procurement of graphene films for flexible OLED production lines at rates that outstrip current deposition capacity.
- Aerospace:Lightning strike protection and radar-transparent structures exploit electrical conductivity and electromagnetic shielding properties.
- Healthcare:Biocompatibility protocols under South Korea's MFDS and targeted drug delivery applications sustain premium pricing for functionalized derivatives.
Automotive anchors volume through Yangtze River Delta masterbatch producers. Consumer electronics is gaining share fastest on display technology roadmaps.
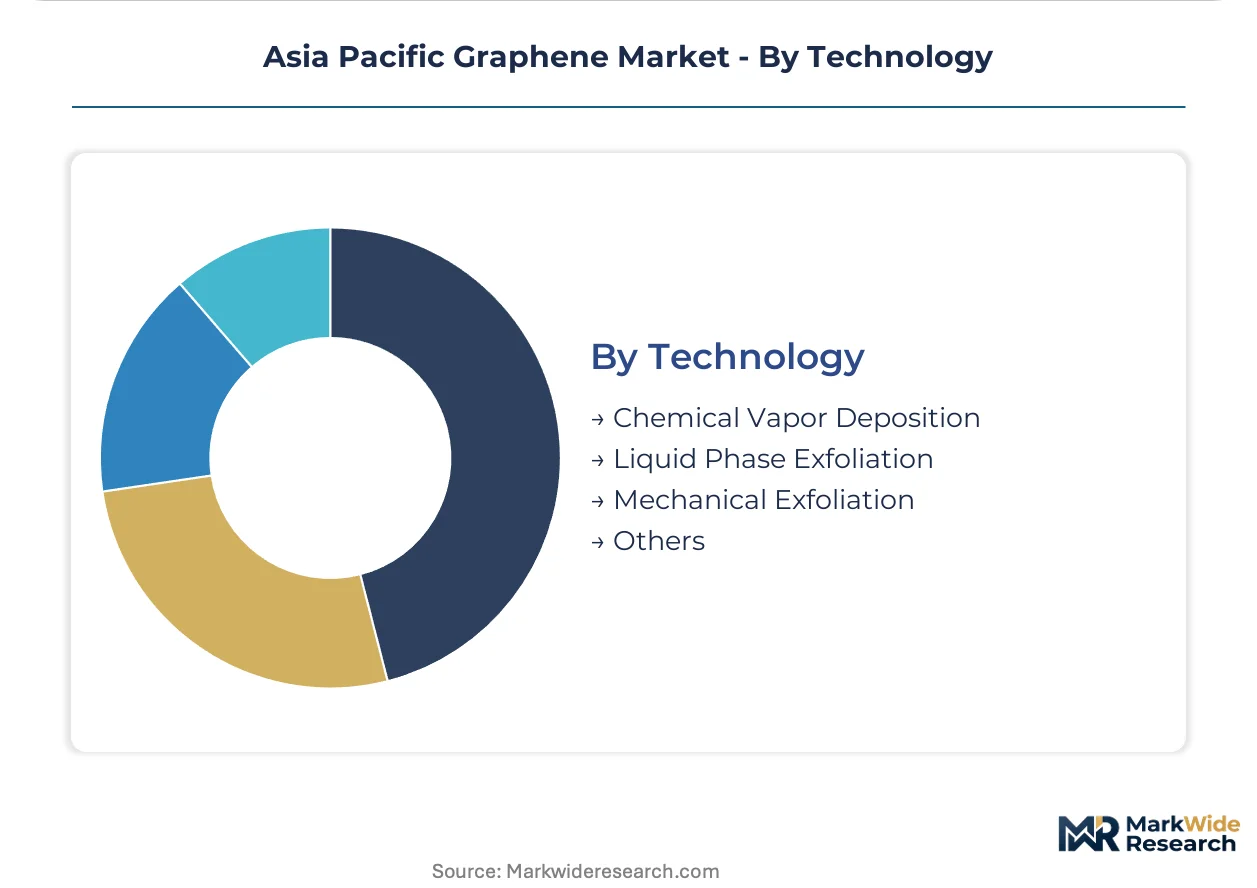
Technology:
Chemical vapor deposition equipment utilization determines film supply elasticity, while liquid phase exfoliation scales through continuous-flow reactor improvements.
- Chemical Vapor Deposition:Copper-catalyzed growth of monolayer films achieves the defect densities required for transparent electrodes. South Korean and Taiwanese capacity expansion is tightening equipment lead times for deposition systems as display manufacturers qualify domestic sources to preserve Japan market access under METI traceability requirements.
- Liquid Phase Exfoliation:Sonication and shear-force dispersion of graphite into few-layer flakes enables tonnage-scale production. Changzhou-based producers have achieved tonnage-grade output that satisfies European automotive specifications through liquid-phase exfoliation purity grades.
- Mechanical Exfoliation:Scotch-tape and ball-milling methods retain laboratory-scale relevance for research samples.
- Others:Electrochemical exfoliation and plasma synthesis occupy niche positions for specific functionalization requirements.
Chemical vapor deposition holds installed capacity concentration in South Korea and Taiwan. Liquid phase exfoliation is rotating up the share rankings on cost-competitive battery additive qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors graphene feedstock flows into eastern China, while the Kaohsiung-Taichung manufacturing corridor underwrites Taiwanese chemical vapor deposition capacity. Busan's container terminals handle South Korean film exports bound for Japanese display fabs.
China
MIIT-enforced GB standards for powder purity and flake size distribution are standardizing procurement benchmarks across battery cathode manufacturers. The dual carbon goals framework mandates lightweight composite adoption in transportation and construction end-uses. Changzhou anchors tonnage-grade graphene nanoplatelet output through liquid-phase exfoliation operations serving Yangtze River Delta masterbatch producers.
South Korea
MFDS biocompatibility protocols for medical devices are fragmenting regulatory compliance burdens alongside electronics-grade material qualification. Display manufacturers are accelerating procurement of graphene films for flexible OLED backplanes at rates exceeding deposition capacity expansion. Seoul Capital Area chemical vapor deposition equipment faces 18-month order backlogs as domestic producers qualify sources to preserve Japan market access.
Japan
METI green technology standards enforce lifecycle carbon accounting and ISO 14064-verified emission traceability from graphite feedstock through final synthesis. Automotive Tier 1 suppliers now exclude Chinese-origin material lacking documented emission footprints. Kanto region display and semiconductor packaging clusters are driving specification slots for graphene-enhanced thermal interface materials.
Taiwan
OLED and foldable screen production lines are pulling single-domain graphene films exceeding 30 cm width at accelerating procurement rates. The Kaohsiung-Taichung corridor concentrates chemical vapor deposition capacity expansion as equipment lead times stretch. Domestic qualification efforts aim to preserve supply chain access under Japanese METI traceability requirements.
India
PLI scheme incentives for domestic lithium-ion cell manufacturing are creating virgin demand for graphene nanoplatelet conductive additives. Battery makers are redrawing procurement priorities away from legacy carbon black as cathode formulation reformulation accelerates. Maharashtra and Gujarat industrial corridors are emerging as qualification sites for imported nanoplatelet masterbatch integration.
Asia Pacific Graphene Market Competitive Landscape
Concentration sits with tonnage-grade powder producers and premium film specialists operating on divergent scale economics. The vendor base stratifies between Changzhou-based liquid-phase exfoliation operations and South Korean-Taiwanese chemical vapor deposition equipment networks. Two strategic archetypes dominate: scale-driven nanoplatelet suppliers serving battery cathode consolidation, and purity-focused film growers qualified for display backplane specifications. Competitive moves center on long-term offtake agreements with minimum volume commitments and backward integration into copper foil feedstock sourcing.
Among Asia Pacific-based producers, The Sixth Element Materials Technology Co., Ltd and Xiamen Knano Graphene Technology Corporation Limited occupy positions within the scale-driven tier, while Applied Graphene Materials represents the liquid-phase exfoliation purity grade segment. These entities exemplify the regional split between eastern China's Yangtze River Delta manufacturing concentration and European-automotive-facing specification compliance. Miraculum Graphene Pvt. Ltd sits within the emerging Indian battery supply chain qualification wave. Company suffixes indicate limited liability structures across Chinese, British, and Indian jurisdictions, reflecting the geographic dispersion of regulatory compliance burdens.
| Leading Market Players |
|---|
| Miraculum Graphene Pvt. Ltd |
| Applied Graphene Materials |
| The Sixth Element Materials Technology Co., Ltd |
| Global Graphene Group |
| XFNANO Materials Tech Co., Ltd |
| Xiamen Knano Graphene Technology Corporation Limited |
| NeoGraf Solutions |
| Graphene NanoChem plc |
| Platonic Nanotech |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month equipment lead times for chemical vapor deposition systems concentrate pricing power with South Korean and Taiwanese film growers serving display backplane specifications, while Changzhou-based nanoplatelet producers compete on volume-scale contract terms. This divergence between premium film scarcity and powder commoditization shapes procurement negotiations across battery cathode and polymer masterbatch segments.
Pricing Analysis
Three-tier pricing structure across electronics-grade film, industrial-grade powder, and commodity carbon additive levels separates qualified suppliers from merchant market sources. Price differentiation rests on MIIT certification status and METI traceability documentation, with Japanese automotive Tier 1 buyers paying premiums for ISO 14064-verified emission footprints. Cost compression in liquid-phase exfoliation nanoplatelets is intensifying because Changzhou capacity expansion outstrips Yangtze River Delta masterbatch absorption rates. Battery cathode manufacturers exhibit highest price sensitivity, while foldable display procurement teams prioritize defect density over unit cost.
Supply Chain Analysis
Inventory cycles stretching 90-120 days for copper foil feedstock tether film producers to battery-grade metal demand fluctuations. Geographic supply concentration centers on South Korea, Taiwan, and eastern China's Yangtze River Delta cluster, with Busan container terminals handling Japanese-bound exports. Raw material dependencies span copper foils, high-purity graphite, and chemical precursor reagents. Single-source vulnerability runs through South Korean deposition equipment manufacturers facing order backlogs. Distribution runs through long-term offtake agreements with minimum volume commitments rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment via divergent MIIT, METI, and MFDS certification pathways creates switching costs that lock in qualified supplier relationships.
For Market Incumbents: Compound qualification depth by backward integration into copper foil sourcing and simultaneous capacity expansion in Taiwan's Kaohsiung-Taichung corridor. Emerging Indian battery producers under PLI scheme incentives threaten volume concentration in eastern China; defend by locking Changzhou nanoplatelet output into exclusive cathode supply agreements before domestic Indian qualification completes.
For New Entrants and Emerging Players: Lead with biocompatibility protocol specialization under South Korea's MFDS medical device pathways, where regulatory fragmentation sustains premium pricing power against commoditized powder competition. India's Maharashtra and Gujarat industrial corridors offer the most penetrable geography for imported masterbatch integration. Pursue qualification partnerships with European automotive Tier 1 suppliers seeking liquid-phase exfoliation purity alternatives to Chinese-origin material.
For Investors and Strategic Acquirers: Long-term, this sits as a materials-scarcity play because deposition equipment lead times and certification timeline barriers protect incumbent returns across the projection horizon. Target acquisition archetypes include mid-scale liquid-phase exfoliation operators with proven European automotive qualification and underutilized Changzhou-area production assets. Watch for MFDS-JIS mutual recognition protocols as the inflection signal that would compress multi-country filing costs and unlock regional consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Foil | Secures feedstock supply against battery-grade metal demand volatility and METI traceability requirements. |
| MFDS Biocompatibility Certification | Opens premium pricing tiers in medical device applications beyond commoditized battery additive competition. |
| Kaohsiung-Taichung Capacity Expansion | Positions film producers to capture Taiwanese OLED backplane procurement acceleration and preserve Japan market access. |
| Long-term Offtake Agreements | Locks in Yangtze River Delta cathode manufacturer volume commitments and displaces merchant market sourcing. |
| PLI Scheme Qualification in India | Captures virgin demand from domestic cell manufacturing incentives before local production scales. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating cathode procurement directors at South Korean battery makers, polymer masterbatch formulators in Changzhou, chemical vapor deposition equipment engineers in Seoul, and METI compliance officers at Japanese automotive Tier 1 suppliers. Secondary validation drew from MIIT GB standard filings, METI green technology certification registries, Korean customs export data, and Taiwan's Industrial Technology Research Institute graphene industry reports. Bottom-up capacity estimates from identified production facilities were triangulated against top-down demand projections from end-use sector consumption models.
Across the analysis window, volume and value outputs reflect segmentation modeling across product type, application, end user, and technology dimensions, with additional layering by regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year market sizing, incorporating capacity expansion timelines, equipment lead time constraints, and qualification pathway duration assumptions specific to graphene film and nanoplatelet production economics.
Underlying assumptions cover sustained electric vehicle battery cathode reformulation, continued METI traceability enforcement, and stable copper foil feedstock availability, with deviation risk concentrated in regulatory protocol harmonization or deposition equipment supply chain disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Fullerene Market
Semiconductor Material
Wet Chemicals for Electronics and Semiconductor Application Market
Semiconductor Material
Tellurium Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Semiconductor Silicon Material Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Silicon Carbide (Sic) Coating Market
Semiconductor Material
Zinc Oxide Nanoparticles Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
ITO Nanoparticles Market
Semiconductor Material
Silicon Hydride Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
Germanium Market