
 LED Lighting Market | 2026-2036
LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
LED Lighting Market Intelligence
China's expanding manufacturing capacity for LED components is reconfiguring the global supply chain for finished luminaires. Signify NV leverages its extensive distribution network to maintain a strong presence across multiple countries. Nichia Corporation specializes in the development of high-efficacy LED chips, supplying many downstream manufacturers. Acuity Brands Inc. focuses on integrated lighting systems for large commercial projects primarily in the United States.
LED lighting is a solid-state illumination technology that utilizes a semiconductor die to produce light when an electrical current is applied. This process, known as electroluminescence, creates highly efficient and durable light sources. The commercial spaces and street lighting segments dominate application-based demand. Within product categories, LED panels and tubes are reaching maturity, while smart-enabled LED bulbs connected to IoT platforms represent a key growth frontier.
Regulatory frameworks are critical in shaping product standards and market entry. The European Union's RoHS directive limits the use of certain hazardous materials in electronics, including LED products. In parallel, the US Environmental Protection Agency's ENERGY STAR program sets voluntary efficiency and performance benchmarks. Future competitive positioning depends on the successful integration of IoT connectivity and advanced lighting controls.
Market Dynamics
The global transition towards energy efficiency, enforced by stringent regulatory frameworks, is the central structural force shaping the LED lighting market. Government mandates like the EU Green Deal and large-scale infrastructure projects in India accelerate the obsolescence of legacy lighting technologies, creating a mandatory replacement cycle.
Growth Catalysts
- Regulatory Mandates:The European Union's RoHS directive restricts hazardous substances, while the US ENERGY STAR program provides a benchmark for efficiency, collectively pushing markets toward safer and more performant LED products.
- Infrastructure Modernization:National-level programs in countries like India are driving massive deployments of LED street lighting, improving public safety and reducing municipal energy consumption.
- Smart City Integration:The convergence of LED lighting with IoT platforms creates demand for connected luminaires that form the backbone of smart city data and control networks.
Market Restraints
- High Initial Investment:The upfront capital expenditure required for large-scale commercial or municipal LED retrofits remains a significant barrier compared to the lower purchase price of conventional lighting technologies.
- Component Dependency:Heavy reliance on a concentrated group of manufacturers in China and Taiwan for critical components like high-efficacy LED chips introduces supply chain vulnerabilities and price volatility.
- Interoperability Issues:A lack of universal standards for smart lighting controls and communication protocols creates integration complexity and vendor lock-in risk for building managers.
Strategic Opportunities
- Horticultural Lighting:The expansion of controlled environment agriculture and indoor vertical farming creates a substantial new application for specialized, spectrum-tuned LED grow lights.
- Human-Centric Lighting:Developing tunable LED systems that mimic natural daylight patterns to enhance occupant well-being and productivity in offices and healthcare facilities opens a premium, value-added market segment.
- African Urbanization:Rapid growth in urban centers across nations like Nigeria and Ethiopia presents an underpenetrated market for new street lighting, commercial, and industrial illumination projects.
Industry Challenges
- Evolving Performance Standards:The rapid pace of change in efficiency benchmarks, such as updates to DesignLights Consortium (DLC) requirements, necessitates continuous R&D investment and frequent product recertification.
- Intense Patent Litigation:The dense patent landscape surrounding core LED technologies, particularly for blue light emitters and phosphors, results in costly intellectual property disputes among major manufacturers.
- Legacy System Integration:Connecting advanced LED control systems with older building management systems (BMS) in retrofit projects often proves complex and costly for facility operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Lighting Market |
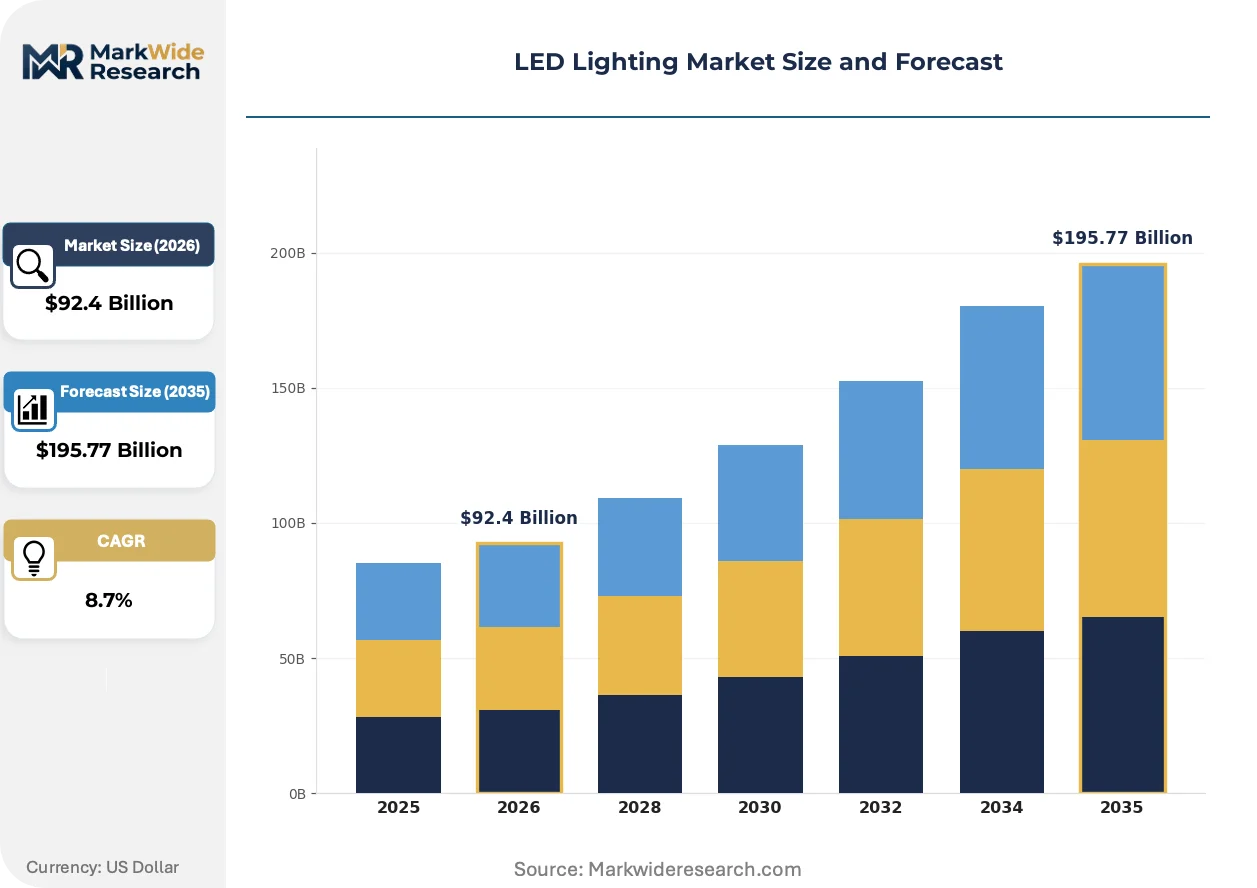
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $195.77 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Bulbs, LED Tubes, LED Panels, LED Strips, LED Floodlights, LED Downlights Technology: SMD, COB, Filament, High-Power, Mid-Power, Chip on Board Application: Commercial Spaces, Outdoor Lighting, Street Lighting, Residential Areas, Sports Venues, Architectural Lighting End User: Construction Firms, Municipal Authorities, Event Organizers, Hospitality Chains, Educational Institutes, Warehousing Operators |
| Companies Covered | Signify NV, General Electric Company, OSRAM Licht AG, Cree Inc., Acuity Brands Inc., Panasonic Corporation, Nichia Corporation, Samsung LED, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Lighting Market Strategic Shifts & Innovations
The fundamental function of lighting is expanding from simple illumination to a networked digital utility. This shift transforms luminaires into intelligent nodes capable of data collection and dynamic environmental control, altering how commercial spaces are managed and experienced.
Light Fidelity (Li-Fi) technology embeds high-speed data communication capabilities within the visible light spectrum emitted by LED luminaires. Commercial and secure government environments are early adopters, seeking secure, high-bandwidth alternatives to radio-frequency-based Wi-Fi. This integration of data transmission with illumination is digitizing the physical luminaire into a dual-function piece of network infrastructure.
The European Union's updated Ecodesign and Energy Labelling regulations impose stricter requirements on energy efficiency, reparability, and circularity for light sources. These rules are pushing manufacturers to redesign products, making components like drivers and LED modules replaceable rather than integrated. The commercial luminaire segment is most affected, as facility managers prioritize products with longer operational lifespans and lower total cost of ownership.
A notable shift in purchasing behavior involves enterprise customers moving from direct capital expenditure on lighting hardware toward service-based models. This trend favors Lighting-as-a-Service (LaaS) contracts, where providers manage installation, maintenance, and energy for a recurring fee, displacing traditional one-time sales. This service-oriented model is most visible in the large-scale retail and logistics sectors in North America and Europe.
LED Lighting Market Segmentation
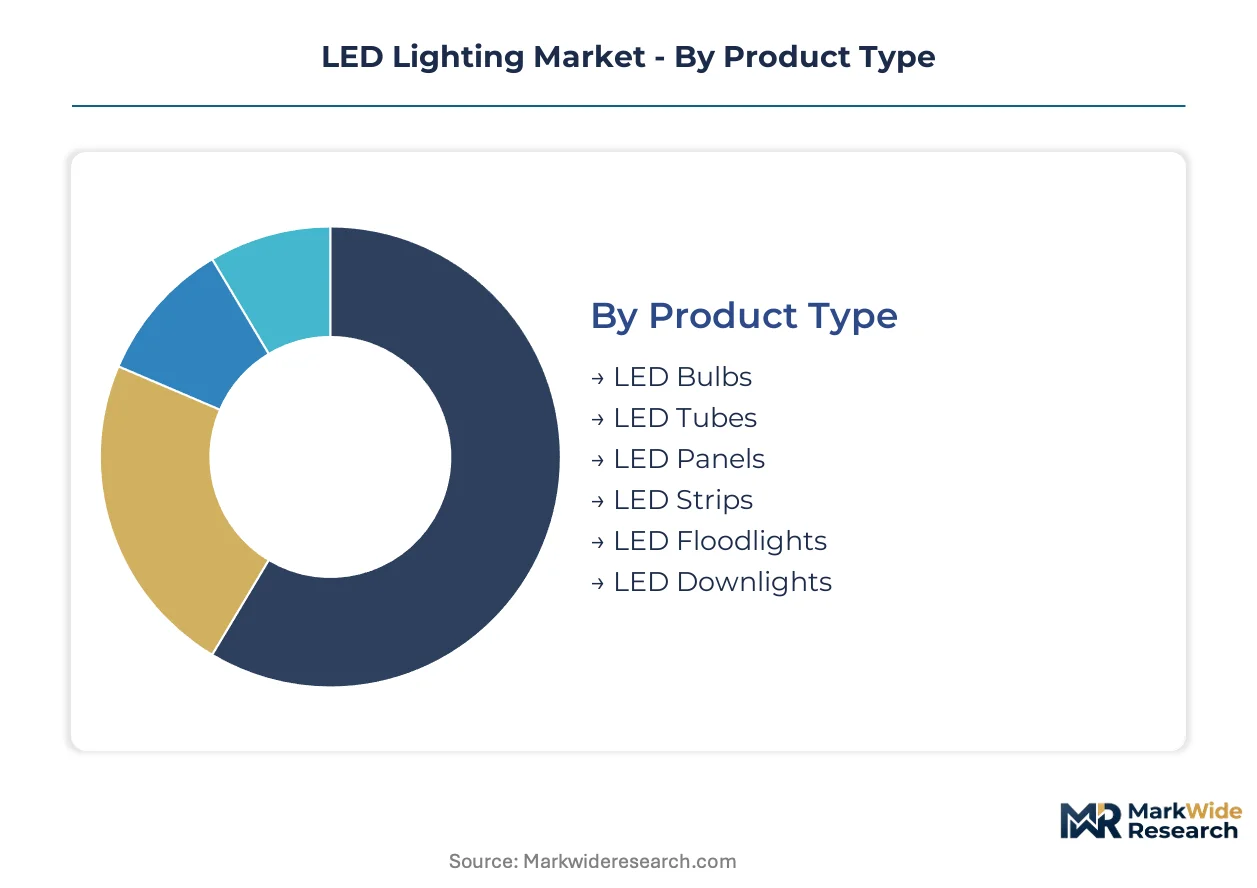
The LED lighting market is fundamentally segmented to reflect its diverse applications and technological underpinnings, allowing for a granular analysis of demand drivers and competitive dynamics. Understanding these categories is crucial for identifying specific growth pockets and evolving end-user requirements across the industry.
Product Type:
The LED lighting market categorizes products by their form factor and intended application, ranging from general illumination to specialized decorative and functional uses.
- LED Bulbs:These replace traditional incandescent or CFL lamps, offering omnidirectional light from standard bases. Residential and smart home integration drives demand for energy savings.
- LED Panels:Flat, integrated luminaires provide uniform, diffused light, often with integrated drivers. Commercial offices and healthcare facilities demand these for aesthetics and efficiency.
- LED Tubes:Linear light sources replacing fluorescent tubes in commercial and industrial settings.
- LED Strips:Flexible, adhesive-backed lighting for accent, cove, or task illumination in retail.
- LED Floodlights:High-output fixtures for broad, powerful outdoor illumination, security, and sports venues.
- LED Downlights:Recessed fixtures providing focused, downward light, popular in commercial and residential interiors.
The dominant share belongs to LED Tubes, while LED Bulbs are closing the gap fastest, particularly with smart-enabled variants.
Technology:
LED lighting technologies differentiate based on chip packaging, power output, and optical properties, influencing efficiency and application suitability for various needs.
- SMD:Surface-Mounted Device LEDs feature multiple small chips mounted individually, offering uniform light and thermal management. Panels and strips drive demand due to versatility.
- COB:Chip-on-Board technology integrates multiple LED chips directly onto a single substrate, creating a compact, high-lumen-density source. Spotlights and downlights demand focused illumination.
- Filament:Mimics traditional incandescent bulbs with visible filaments for aesthetic appeal in decorative uses.
- High-Power:LEDs engineered for maximum light output, suitable for demanding applications like street lighting.
- Mid-Power:These LEDs balance efficiency and cost, widely used in general illumination products like tubes.
- Chip on Board:Direct mounting of bare LED chips onto a circuit board, optimizing heat dissipation and light output.
Performance benchmarks are primarily set by SMD technology, with COB expanding its footprint significantly in high-intensity applications.
Application:
The market for LED lighting is driven by diverse application areas, each contributing significant volume and requiring specific illumination characteristics and control.
- Commercial Spaces:This segment includes offices, retail, and hospitality, demanding integrated lighting systems for energy savings and enhanced occupant experience. Smart controls drive demand.
- Street Lighting:Large-scale public infrastructure projects utilize durable, high-lumen LED fixtures for public safety and energy reduction. India drives significant demand.
- Outdoor Lighting:Encompasses area lighting, pathways, and facades, requiring weather-resistant and robust LED solutions.
- Residential Areas:Focuses on home illumination, including decorative, task, and ambient lighting.
- Sports Venues:Requires high-power, flicker-free LED lighting for optimal visibility and broadcast quality.
- Architectural Lighting:Emphasizes aesthetic enhancement, using LEDs for facade illumination and artistic installations.
The largest volume contributions come from Commercial Spaces, with Street Lighting also maintaining substantial demand through government initiatives.
End User:
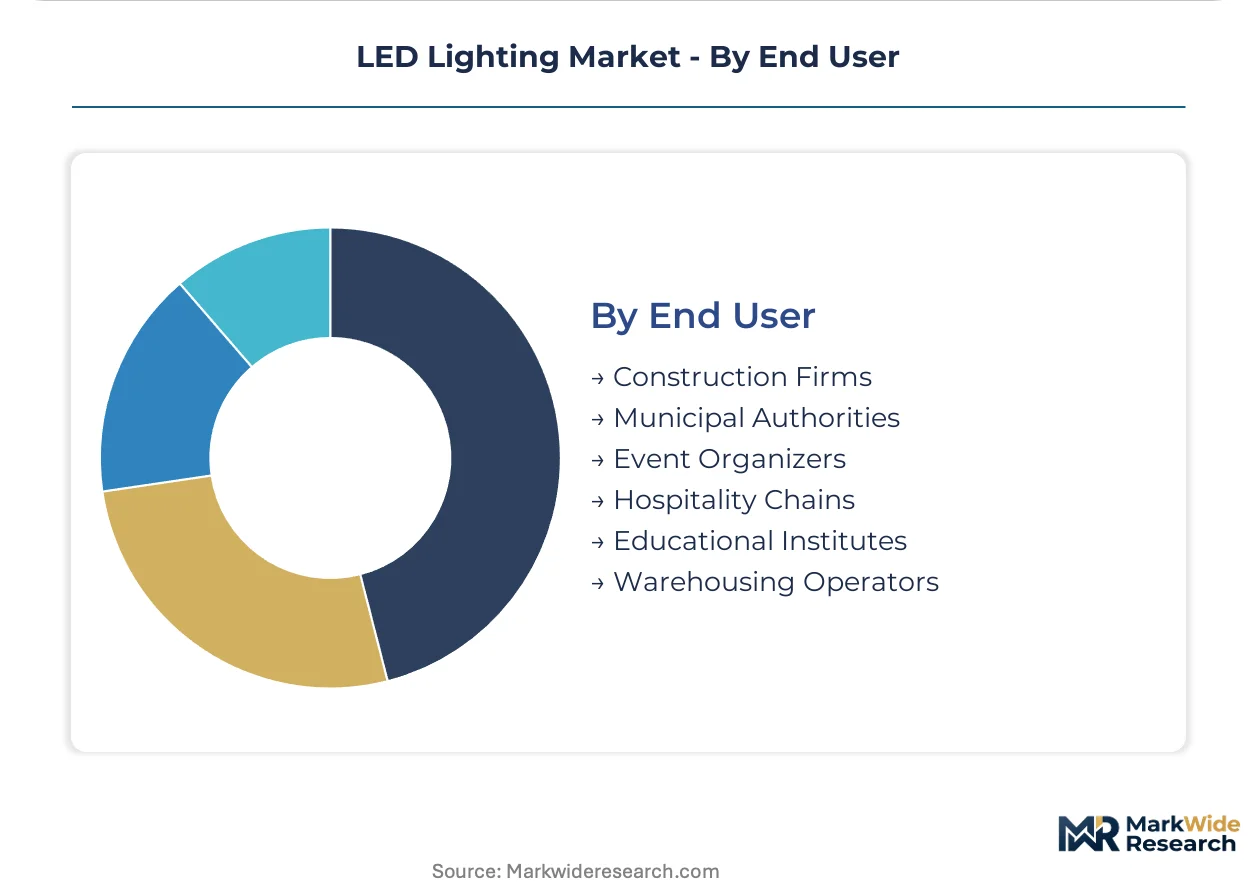
End-user segments dictate distinct procurement patterns and project requirements, influencing product specifications and service models for LED lighting.
- Construction Firms:These entities integrate LED lighting into new building projects and large-scale renovations, driven by energy codes and modern design. Commercial and residential developments concentrate demand.
- Municipal Authorities:Government bodies procure LEDs for street lighting, parks, and public buildings. Energy efficiency mandates and smart city integration drive procurement in Europe.
- Event Organizers:Require flexible, high-performance LED lighting for temporary installations and atmospheric illumination.
- Hospitality Chains:Seek aesthetic and energy-efficient LED solutions for hotels, enhancing guest experience and operational savings.
- Educational Institutes:Adopt LED lighting for classrooms and campuses, focusing on improved learning environments.
- Warehousing Operators:Utilize high-bay and task-specific LED lighting for efficiency, safety, and automation integration.
Procurement volumes are highest among Construction Firms, with Warehousing Operators increasingly adopting advanced LED solutions for operational efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption-mix differentials across geographies influence LED lighting market dynamics, with developing nations prioritizing foundational infrastructure while developed economies focus on smart integration. Regulatory frameworks and national investment programs significantly shape demand patterns in specific regions. This varied approach drives distinct growth trajectories and technological adoption rates globally.
India
National infrastructure modernization programs drive substantial demand for LED street lighting, improving public safety and reducing municipal energy costs. The Indian government's UJALA scheme has significantly accelerated LED bulb adoption in residential sectors. Delhi and Mumbai are witnessing large-scale smart city projects, integrating connected LED luminaires for advanced urban management.
China
Expanding manufacturing capacity for LED components fundamentally reconfigures the global supply chain for finished luminaires. The dual carbon goals set by the Chinese government promote energy-efficient lighting solutions across industrial and commercial sectors. Shenzhen and Guangzhou, key manufacturing hubs, continue to innovate in LED chip and luminaire production.
United States
Commercial projects, particularly large-scale facilities, represent a significant demand segment for integrated LED lighting systems. The US Department of Energy's efficiency standards and the EPA's ENERGY STAR program push for high-performance products. California and New York lead in smart building development, integrating advanced LED controls with IoT platforms.
Germany
The European Union's Green Deal and Ecodesign regulations impose stringent energy efficiency and circularity requirements on LED products. Demand concentrates in commercial offices and healthcare facilities seeking human-centric lighting solutions. Cities like Berlin and Munich are early adopters of smart street lighting and advanced building management systems.
Nigeria
Rapid urbanization across African nations presents an underpenetrated market for new street lighting and commercial illumination projects. Government initiatives to upgrade public infrastructure are slowly catalyzing demand for durable, energy-efficient LED solutions. Lagos and Abuja represent growing urban centers with significant potential for future LED deployments.
LED Lighting Market Key Industry Players
Capability concentration sits with one tier of the market, focusing on specialized component innovation, while scale advantage sits with another, emphasizing extensive distribution and integrated systems. The market structure exhibits a tiered consolidation, with major global players alongside numerous regional specialists. Strategic partnerships and continuous portfolio diversification are dominant competitive moves among these entities.
Companies like Signify NV exemplify the archetype of a global leader leveraging extensive distribution networks to maintain strong market presence across diverse countries. Nichia Corporation represents a specialized component manufacturer, anchoring the high-efficacy LED chip segment of the supply chain. Acuity Brands Inc. occupies a position as an integrated systems provider, primarily focusing on large commercial projects in specific regions.
| Leading Market Players |
|---|
| Signify NV |
| General Electric Company |
| OSRAM Licht AG |
| Cree Inc. |
| Acuity Brands Inc. |
| Panasonic Corporation |
| Nichia Corporation |
| Samsung LED |
| Eaton Corporation |
| Others |
Cost & Logistics Intelligence
The trans-Pacific shipping lanes' volatility directly influences component pricing, which in turn shapes the final cost differentiation of LED luminaires across global markets.
Pricing Analysis
Significant price variances for LED lighting products exist between Asian manufacturing hubs and Western consumer markets. Project-based pricing dominates large commercial and municipal procurements, often integrating long-term service contracts. Price differentiation stems from certification levels like ENERGY STAR, geographic delivery costs, and the volume scale of orders. Downward pricing pressure originates from intense competition among Chinese component manufacturers. Municipal authorities exhibit high price sensitivity for large-scale street lighting projects, while specialized horticultural lighting commands premium pricing.
Supply Chain Analysis
The upstream supply of rare earth elements and specialized semiconductor materials forms the foundation of LED lighting production. Manufacturing for high-efficacy LED chips and phosphors concentrates heavily in China, Taiwan, and Japan. The market relies on a concentrated group of manufacturers for critical components like semiconductor dies and specialized optical materials. This component dependency introduces single-source vulnerability and potential price volatility across the supply chain. Downstream distribution runs through extensive global networks for general illumination and direct project-based models for integrated systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LED lighting market is experiencing a cyclical recovery, primarily driven by renewed infrastructure spending and commercial construction after economic slowdowns.
For Market Incumbents: Entrench existing market share by deepening vertical integration into LED chip manufacturing and enhancing proprietary control systems. Invest in continuous R&D for advanced IoT connectivity and human-centric lighting solutions to counter emerging specialized entrants. This strategy mitigates margin erosion from commodity product segments and defends against price-focused competitors. Leverage existing extensive distribution networks for faster market penetration of new smart-enabled products.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated segments like horticultural lighting or specialized architectural installations. Focus on African urban centers, where foundational infrastructure projects offer significant growth potential. Differentiate through value-added services such as Lighting-as-a-Service models, reducing upfront capital expenditure for clients. Prioritize interoperability with diverse IoT platforms to avoid vendor lock-in issues for building managers.
For Investors and Strategic Acquirers: The EU Green Deal and US Department of Energy efficiency standards reshape the acquisition landscape, favoring companies with strong ESG credentials. Long-term viability across the next decade hinges on intellectual property in advanced controls and energy management software. Target acquisition profiles include vertically integrated mid-cap specialists in smart lighting platforms or niche application providers. The signal to watch for market inflection is the widespread adoption rate of Li-Fi technology in secure commercial environments.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance IoT Platform Integration | Improves luminaire functionality as intelligent data nodes for smart city applications. |
| Expand LaaS Offerings | Shifts customer procurement from CAPEX to OPEX, aligning with enterprise purchasing trends. |
| Invest in Horticultural Lighting R&D | Captures new demand from controlled environment agriculture and vertical farming. |
| Secure Critical Component Supply | Mitigates supply chain vulnerabilities from concentrated chip manufacturing in Asia. |
| Pursue Human-Centric Lighting Solutions | Addresses premium market segments focused on occupant well-being in commercial spaces. |
Research Approach
A standing panel of R&D directors, procurement specialists, facility managers, and urban planners provided ongoing calibration for primary insights. This involved combining in-depth interviews with industry stakeholders and secondary validation from sources like the US Department of Energy reports and EU Ecodesign regulations. Bottom-up and top-down triangulation ensured robust data integrity.
Scenario bracketing defined the plausible range of outcomes, incorporating variables such as regulatory shifts and technological adoption rates. The analytical framework modeled segmentation dimensions including product type, application, end-user, and regional demand patterns over the projection horizon. Compound annual growth rates were derived from historical data trends and projected market dynamics. Key forecast inputs included smart city integration rates and energy efficiency mandate enforcement levels.
Stress conditions across geopolitical trade tensions and raw material price volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding market evolution. Cross-checking against national energy consumption benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Global LED Phosphor Market
LED
Asia Pacific LED Lighting Market
LED
LED Phosphor Materials Market
LED
LED Driver Market
LED
Led Video Walls Market
LED
Programmable LED Drivers Market
LED
LED Floodlight Drivers Market
LED
China Indoor LED Lighting Market
LED
North America Micro-LED Display Market
LED
GCC LED Lighting Market
LED
Japan Indoor LED Lighting Market
LED
LED Light Bar Market
LED
Pixel Pitch LED Market
LED
Japan LED Lighting Market
LED
UAE LED Lights Market
LED
Surface Mount PLCC Leds Market