
 LED Floodlight Drivers Market | 2026-2036
LED Floodlight Drivers Market Size, Share, and Industry Trends Forecast 2026-2036
LED Floodlight Drivers Market Analytics
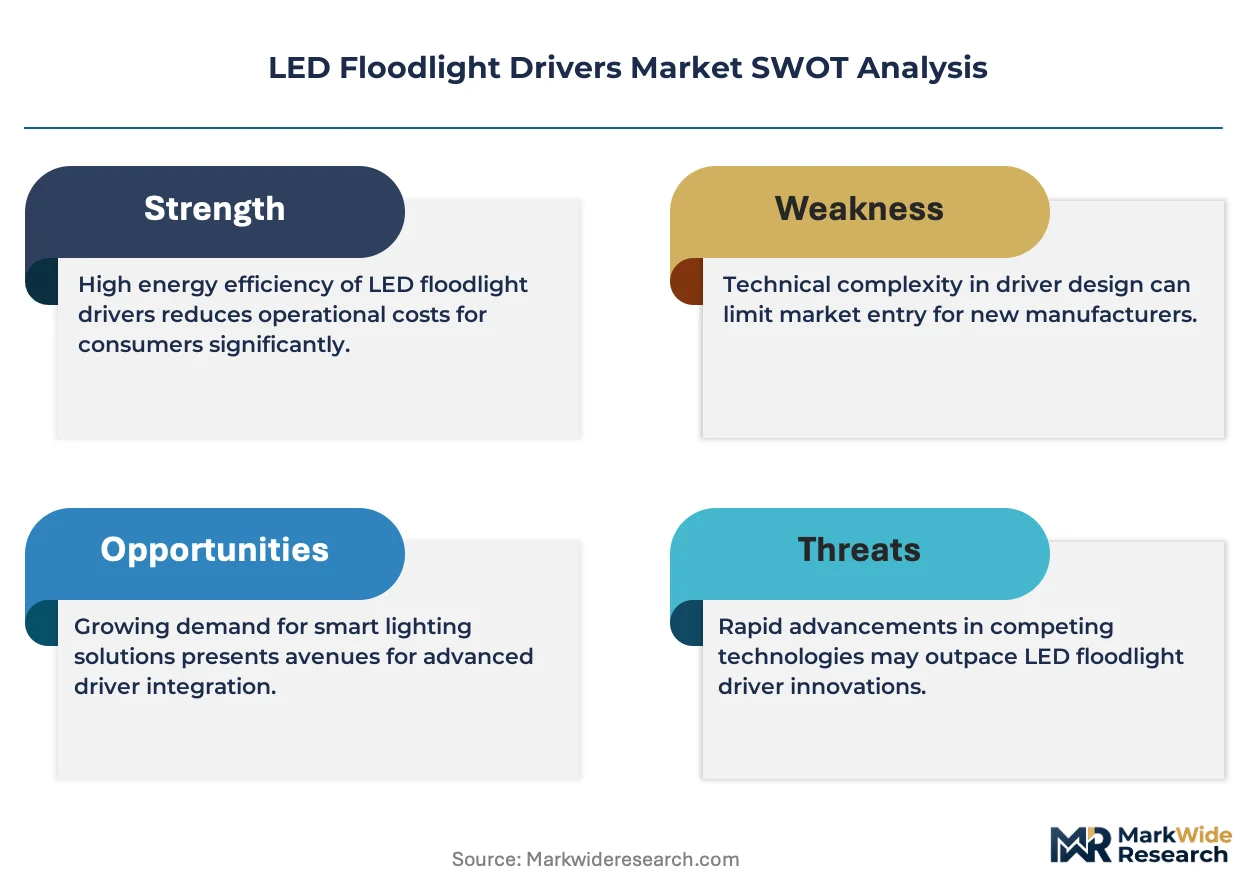
Subscription-based remote diagnostics for driver health monitoring is repositioning how lighting OEMs monetize hardware relationships. Mean Well leverages its extensive distributor network to sustain aftermarket service revenue across Asia-Pacific installations. Signify anchors its competitive stance through proprietary Interact software integration that locks in driver compatibility. Texas Instruments competes by supplying programmable IC architectures that enable tier-one manufacturers to differentiate on dimming precision.
LED floodlight drivers are power-electronics modules that convert mains AC input to regulated DC output, typically operating between 100W and 1000W with power-factor correction above 0.9 and surge protection rated to 6kV. These devices govern current stability across high-lumen LED arrays deployed in sports venues, port terminals, and perimeter security installations. Constant current products dominate unit shipments due to their compatibility with high-power COB emitters, while programmable segments capture disproportionate margin pools as venues adopt DALI-2 control infrastructure. Smart technology variants are displacing analog architectures in new construction, though hybrid designs persist in retrofit applications where legacy dimming compatibility governs procurement decisions.
Europe's Ecodesign Directive and RoHS substance restrictions shape product material selection and minimum efficiency thresholds for drivers sold within EU member states. China's GB 7000 standards and India's BIS certification requirements create divergent compliance burdens that fragment supplier qualification pathways. The US EPA Energy Star program and FCC Part 15 emissions rules add further testing layers for North American market entry. Stakeholders must monitor how interoperability standards between DALI, Zhaga, and proprietary wireless protocols resolve, as this convergence will determine which driver architectures retain platform value across the next replacement cycle.
Market Dynamics
Programmable driver architectures are compressing replacement cycles as venue operators retrofit legacy analog systems to meet tightening efficacy mandates and enable central management integration.
Growth Catalysts
- China's GB 7000 standards:Minimum efficacy thresholds for outdoor lighting are compelling port terminal operators to accelerate driver upgrades ahead of compliance deadlines.
- Smart city infrastructure:India's municipal procurement programs are prioritizing DALI-2 compatible drivers that integrate with central lighting management platforms across urban corridors.
- High-power COB emitters:Constant current driver demand from sports venue retrofits in the Middle East is expanding as FIFA and AFC tournament standards mandate broadcast-quality illumination uniformity.
Market Restraints
- Power semiconductor cost volatility:Silicon carbide MOSFET and IGBT pricing fluctuations are compressing margins for driver manufacturers serving price-sensitive municipal segments.
- Supply concentration in East Asian foundries:Wafer fabrication for driver ICs clusters in Taiwan and South Korea, exposing procurement timelines to geopolitical disruption risks.
- Technical limitation in surge protection:6kV protection ratings struggle to protect drivers in coastal installations where lightning strike frequency exceeds design baselines.
Strategic Opportunities
- Underpenetrated Southeast Asian stadiums:Vietnam and Indonesia host under 15% of regional sports venues with LED floodlight retrofits completed, creating first-mover positioning for programmable driver suppliers.
- Technology convergence:Integration of DALI-2 control with Zhaga Book 18 mechanical interfaces is enabling tool-free driver replacement that reduces venue maintenance downtime.
- India's PLI scheme:Production-linked incentives for LED component manufacturing are attracting driver assembly investments that reduce import dependency for domestic infrastructure projects.
Industry Challenges
- Certification timeline compression:BIS approval processes for driver safety testing are extending lead times for suppliers targeting India's smart city tenders.
- Legacy dimming protocol fragmentation:0-10V, DALI, and proprietary wireless control coexistence is forcing hybrid driver designs that increase firmware complexity and failure modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Floodlight Drivers Market |
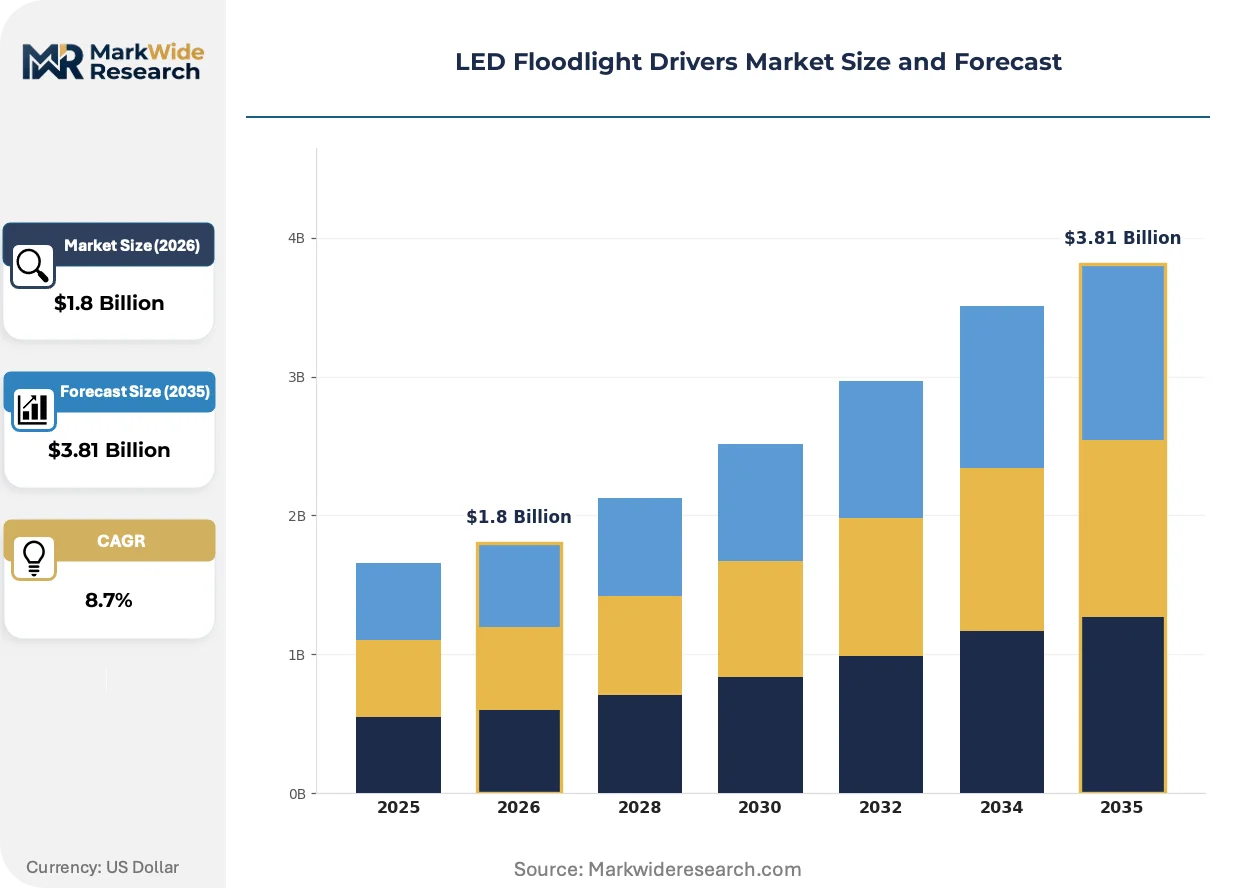
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Constant Current, Constant Voltage, Programmable, DALI Technology: Analog, Digital, Hybrid, Smart End User: Commercial, Industrial, Residential, Outdoor Installation Type: Surface Mounted, Recessed, Suspended, Integrated |
| Companies Covered | Signify, ams OSRAM, Mean Well, Tridonic, Inventronics, Lifud Technology, Eaglerise, Acuity Brands Lighting, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Floodlight Drivers Market Evolving Landscape
Driver intelligence is migrating from discrete analog control toward embedded processing architectures that enable predictive maintenance and real-time efficacy optimization across distributed lighting networks.
GaN-based switching topologies are electrifying driver power density capabilities, enabling 1000W-class units in compact form factors that reduce thermal management overhead. Sports venue operators in Qatar and Saudi Arabia are specifying these architectures for new FIFA-compliant installations. The technology is electrifying competitive differentiation around form factor and thermal performance as legacy silicon designs face obsolescence pressure.
Europe's Ecodesign Directive is tightening minimum efficiency thresholds and standby power limits for outdoor lighting drivers sold within EU member states. Manufacturers must redesign thermal management and standby circuits to meet 2027 requirements. Commercial and industrial segments are responding by accelerating specification of next-generation drivers in current procurement cycles to avoid stranded asset risk.
Subscription-based remote diagnostics are unbundling hardware margins from ongoing service relationships. Lighting OEMs are capturing recurring revenue through driver health monitoring platforms that predict failure before lumen depreciation impacts venue operations. This model is most visible in German and Dutch municipal contracts where total-cost-of-ownership procurement frameworks dominate evaluation criteria.
LED Floodlight Drivers Market Segmentation
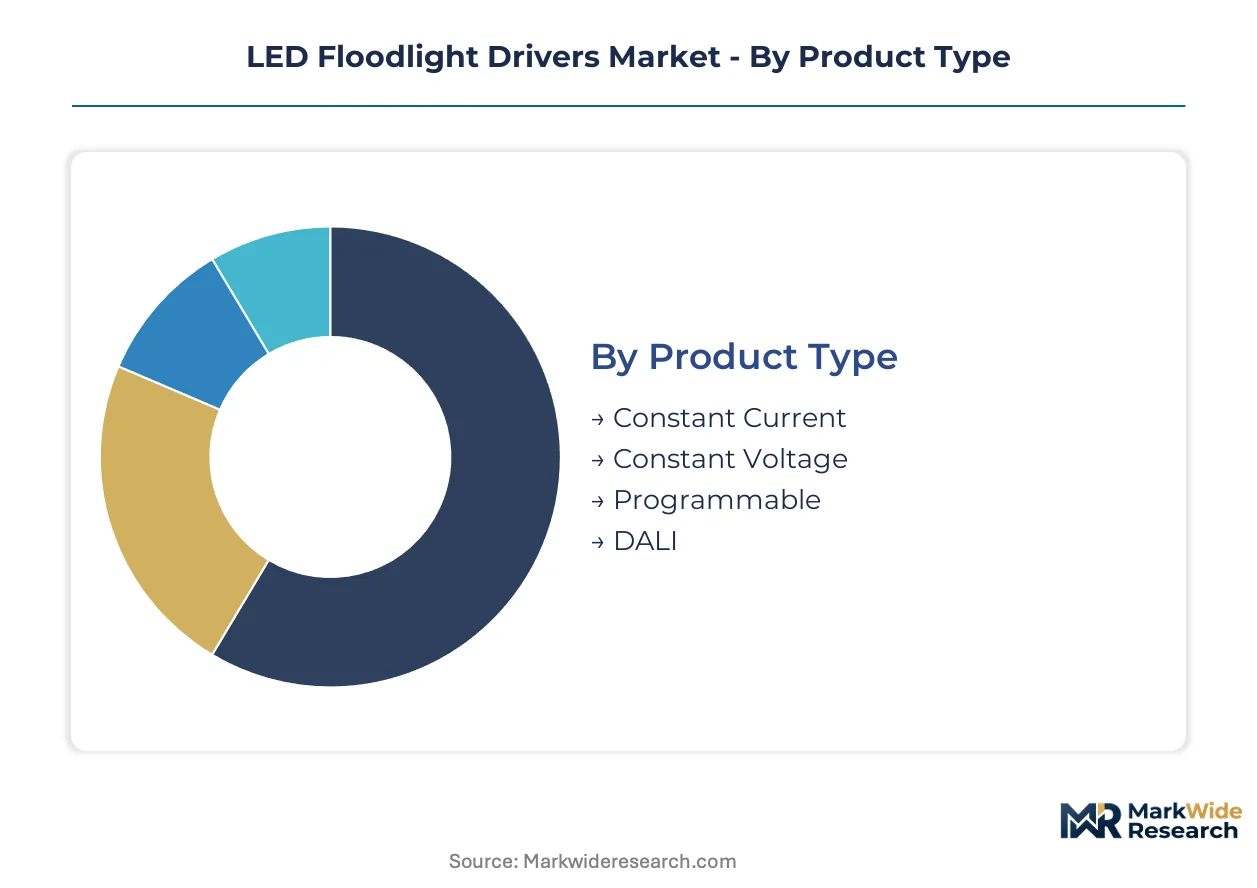
LED floodlight driver segmentation reveals how power electronics architectures align with diverging procurement priorities across venue types and regulatory environments. Supply concentration in programmable and smart variants is reshaping competitive positioning as municipalities and sports operators upgrade legacy infrastructure.
Product Type:
Supply concentration favors programmable architectures as port terminal operators and stadium managers seek dimming precision and central management compatibility.
- Constant Current:These drivers deliver fixed current output optimized for high-power COB emitters, maintaining lumen stability across temperature fluctuations. Demand concentrates in Middle Eastern sports venue retrofits where FIFA and AFC tournament standards mandate broadcast-quality illumination uniformity.
- Programmable:Embedded microcontroller architectures enable firmware-configurable output curves and DALI-2 protocol compliance. India's smart city infrastructure programs prioritize these drivers for integration with central lighting management platforms across urban corridors.
- Constant Voltage:Fixed voltage output modules suit linear LED arrays in perimeter security and facade lighting applications. Procurement clusters in Southeast Asian commercial developments.
- DALI:Native digital addressable lighting interface compatibility enables individual fixture control in large-scale installations. Specification is expanding in German and Dutch municipal contracts.
Today's leader: Constant Current. Tomorrow's challenger: Programmable.
Technology:
Cost tier separation is pronounced between legacy analog designs and premium smart architectures with predictive maintenance capabilities.
- Smart:Embedded processing enables real-time efficacy optimization and remote health monitoring across distributed networks. Subscription-based diagnostics are repositioning how lighting OEMs monetize hardware relationships in German municipal contracts.
- Digital:Discrete logic-based control provides programmable dimming curves without full smart functionality. Demand is climbing the fastest in India's BIS-certified infrastructure tenders.
- Hybrid:Dual analog-digital architectures preserve legacy 0-10V dimming compatibility while enabling partial digital control. Retrofit applications in Europe's Ecodesign compliance drives favor these designs.
- Analog:Discrete component-based regulation offers lowest unit cost for price-sensitive segments. Share is contracting as efficacy mandates tighten.
Premium smart architectures command service attach revenue. Hybrid designs bridge the transition.
End User:
Application-specific requirements fragment procurement specifications across venue types with diverging uptime and control priorities.
- Industrial:Heavy-duty drivers with 6kV surge protection serve port terminals and logistics hubs. China's GB 7000 standards are compelling acceleration of driver upgrades ahead of compliance deadlines.
- Commercial:Mid-power programmable units dominate retail and office exterior lighting. DALI-2 specification is expanding in corporate campus developments.
- Outdoor:Weather-hardened architectures with enhanced thermal management serve street and area lighting. India's municipal procurement programs prioritize central management compatibility.
- Residential:Lower-wattage constant voltage products serve estate and perimeter security applications. Volume concentrates in suburban developments across Southeast Asia.
Industrial specifications set the reliability benchmark. Outdoor segments are gaining share fastest in smart city deployments.
Installation Type:
Volume distribution tracks construction method preferences across new-build and retrofit project pipelines.
- Surface Mounted:External driver housings enable rapid field replacement and thermal isolation. Sports venue retrofits in Qatar and Saudi Arabia specify these for FIFA-compliant installations.
- Integrated:Driver-emitter co-packaging reduces wiring complexity in new construction. Adoption is expanding in Vietnam and Indonesian stadium developments.
- Recessed:Flush-mount architectures suit aesthetic-sensitive commercial facades. Specification clusters in European heritage lighting projects.
- Suspended:Pendant-mounted drivers serve temporary and event lighting infrastructure. Demand tracks Middle Eastern tournament and exhibition calendars.
Surface mounted dominates retrofit economics. Integrated architectures are climbing fastest in new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping driver manufacturing footprints as compliance cost differentials between jurisdictions widen. Assembly operations are migrating toward markets where BIS certification, GB standards, and Ecodesign enforcement create localized production incentives that offset logistics expenses.
China
Port terminal operators along the Yangtze River Delta are accelerating driver upgrades ahead of GB 7000 efficacy deadlines. MIIT enforcement of dual carbon goals is tightening standby power limits for outdoor lighting exports. Shenzhen and Dongguan manufacturing clusters dominate programmable driver assembly for Middle Eastern stadium contracts.
Germany
Municipal procurement frameworks in the Ruhr and Rhine-Ruhr metropolitan regions prioritize total-cost-of-ownership metrics that favor smart driver architectures. Ecodesign Directive efficiency thresholds are compelling early replacement of legacy analog systems. Bavarian industrial zones concentrate DALI-2 integration expertise for European sports venue retrofits.
India
Smart city infrastructure tenders in Maharashtra and Gujarat specify programmable drivers compatible with central management platforms. BIS certification timelines are extending procurement lead times for imported components. Delhi-NCR municipal programs are driving volume concentration in DALI-2 compliant outdoor lighting corridors.
United States
EPA Energy Star specifications and FCC Part 15 emissions rules layer compliance costs on driver imports serving commercial exterior lighting. Texas and California utility rebate programs are accelerating specification of high-efficiency architectures in retail and logistics hub developments. Southeast municipal procurement is shifting toward predictive maintenance capabilities in street lighting networks.
Saudi Arabia
FIFA tournament standards are mandating broadcast-quality illumination uniformity across Riyadh and Jeddah stadium developments. SFDA and SASO alignment with international efficacy benchmarks is filtering import eligibility. Eastern Province industrial zones are emerging as assembly locations serving Gulf Cooperation Council port terminal retrofits.
LED Floodlight Drivers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium programmable architectures concentrating among integrated lighting OEMs while price-sensitive municipal tenders fragment toward independent driver suppliers. The vendor base organizes into three tiers: multinational electronics conglomerates with captive semiconductor supply, mid-scale power electronics specialists with regional certification expertise, and contract assemblers serving private-label requirements. Dominant competitive moves include backward integration into GaN switching component sourcing and strategic partnerships with stadium lighting contractors securing multi-year service contracts.
Among Asian power electronics fabricators, Mean Well and Inventronics exemplify the mid-scale specialist archetype with extensive distributor networks sustaining aftermarket service revenue. Signify anchors the integrated OEM tier through proprietary software ecosystems that lock in driver compatibility across lighting portfolios. Texas Instruments occupies a component-supplier position enabling tier-one manufacturers to differentiate on dimming precision through programmable IC architectures.
| Leading Market Players |
|---|
| Signify |
| ams OSRAM |
| Mean Well |
| Tridonic |
| Inventronics |
| Lifud Technology |
| Eaglerise |
| Acuity Brands Lighting |
| Texas Instruments |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists across Taiwan and South Korea anchor programmable driver production, translating captive semiconductor relationships into pricing discipline that resists commoditization pressure from contract assemblers. Their ownership structure enables long-term foundry commitments that stabilize input costs while municipal tenders in India and Southeast Asia force margin compression on standardized constant-current units.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for constant-current drivers serving Southeast Asian commercial developments. Pricing stratifies across premium programmable architectures with DALI-2 certification, mid-tier digital units for Indian BIS compliance, and economy analog designs for residential perimeter lighting. Cost compression in the economy tier is intensifying as Chinese contract manufacturers absorb GB 7000 compliance expenses to maintain port terminal share. Municipal procurement teams in India exhibit highest price sensitivity, while German stadium operators prioritize total-cost-of-ownership metrics that accommodate smart driver premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Middle Eastern stadium contractors, while distributor networks sustain aftermarket service revenue for Mean Well and Inventronics across Asia-Pacific installations. Wafer fabrication for driver ICs clusters in Taiwan, South Korea, and China, drawing from silicon carbide substrates, copper magnet wire, and aluminum heat sink extrusions. Single-source vulnerability in Taiwan foundry capacity exposes procurement timelines to geopolitical disruption risks. Distribution runs through authorized distributors serving lighting OEMs and direct contracts with municipal procurement authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between India's BIS certification timelines and China's MIIT enforcement of dual carbon goals creates assembly cost differentials favoring localized production investments. This geographic spread enables margin capture across diverging compliance environments.
For Market Incumbents: Deploy subscription-based remote diagnostics platforms to lock in recurring revenue from German and Dutch municipal contracts. Deepen backward integration into GaN switching component sourcing to defend programmable driver margins against silicon carbide MOSFET price volatility. Mean Well's distributor network model offers template for aftermarket service capture that resists commoditization from contract assemblers.
For New Entrants and Emerging Players: Capture underpenetrated stadium retrofit opportunities in Vietnam and Indonesia where under 15% of regional venues complete LED floodlight upgrades. Target DALI-2 programmable architectures for India's smart city infrastructure tenders, leveraging PLI scheme incentives to offset BIS certification lead times. Partner with local lighting contractors securing multi-year service contracts as primary go-to-market channel.
For Investors and Strategic Acquirers: Valuations sit cheapest among contract assemblers serving private-label requirements without captive semiconductor supply. Long-term viability over the next replacement cycle hinges on DALI-2 and Zhaga protocol convergence determining platform value. Watch interoperability standard resolution between proprietary wireless and open protocols as inflection indicator for which driver architectures retain pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Switching Topology Adoption | Enables compact 1000W-class drivers for FIFA-compliant Qatar and Saudi stadiums. |
| DALI-2 Protocol Integration | Locks in compatibility with German and Dutch central lighting management platforms. |
| Backward Integration into Driver ICs | Reduces exposure to Taiwan and South Korea foundry concentration risks. |
| Subscription Diagnostics Launch | Captures recurring revenue from total-cost-of-ownership procurement frameworks. |
| PLI Scheme Assembly Investment | Offsets import dependency for India's smart city infrastructure projects. |
Research Methodology
Direct dialogue with lighting OEM procurement directors, power electronics plant managers, municipal tender evaluation committees, and semiconductor distribution channel heads anchored qualitative assessment. Secondary validation drew from MIIT dual carbon policy filings, BIS certification timelines, Ecodesign Directive efficiency threshold documents, and FIFA stadium illumination standards. Bottom-up and top-down triangulation cross-referenced driver shipment data against venue retrofit project pipelines.
Bottom-up modeling segmented volume and value across constant current, programmable, constant voltage, and DALI product types, further disaggregated by smart, digital, hybrid, and analog technology tiers. End-use splits across industrial, commercial, outdoor, and residential applications captured diverging uptime and control priorities. CAGRs were derived from replacement cycle compression analysis and efficacy mandate enforcement timelines. GaN adoption curves and DALI-2 penetration rates served as technology-specific forecast inputs across the projection horizon.
Power semiconductor cost volatility, BIS approval timeline extensions, and interoperability standard fragmentation are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and venue operator procurement behavior. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Europe Indoor LED Lighting Market
LED
UK LED Lighting Market
LED
Arrow LED Displays Market
LED
Dot-Matrix LED Displays Market
LED
Brazil LED Market
LED
LED Panel Market
LED
Global Chip Scale Package (CSP) LED Market
LED
Vietnam LED Lighting Market
LED
Middle East LED Lighting Market
LED
LED Light Market
LED
Global Waterproof LED Module Market
LED
Germany Outdoor LED Lighting Market
LED
Mini LED Display Market
LED
Saudi Arabia LED Lights Market
LED
United States Micro LED Market
LED
Global LED Phosphor Market