
 China Indoor LED Lighting Market | 2026-2036
China Indoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
China Indoor LED Lighting Market Insights
E-commerce distribution channels are reshaping how indoor LED lighting reaches buyers across China's tiered city hierarchy. Opple Lighting leverages its direct-to-contractor platform to sustain margins in commercial projects. NVC Lighting anchors its position through extensive offline distributor networks in second and third-tier cities. Zhejiang Yankon Group competes on manufacturing scale, operating one of the largest LED chip-to-fixture facilities in Zhejiang province.
China indoor LED lighting encompasses solid-state luminaires engineered with gallium nitride chips, aluminum heat sinks, and polycarbonate diffusers rated for correlated color temperatures between 2700K and 6500K, designed primarily for enclosed interior environments requiring controlled illuminance and energy efficiency. Panel lights dominate volume in commercial office fit-outs where uniform glare-free output commands premium positioning. Smart lighting technology is displacing conventional switching in hospitality retrofits as property operators prioritize occupancy-based automation and remote diagnostics. Downlights retain the largest installed base across residential applications, though margin pools have compressed amid commoditization of basic COB packages.
China's national standardization body, BIS equivalent technical committees, and MIIT enforce GB 7000 series safety standards and energy efficiency grades that determine market access for domestic sales. The dual carbon goals from MEE are forcing manufacturers to disclose lifecycle carbon data and accelerate transition to low-temperature solder processes. Stakeholders must monitor how forthcoming efficiency tier revisions redistribute procurement eligibility across government and commercial tender pools.
Market Dynamics
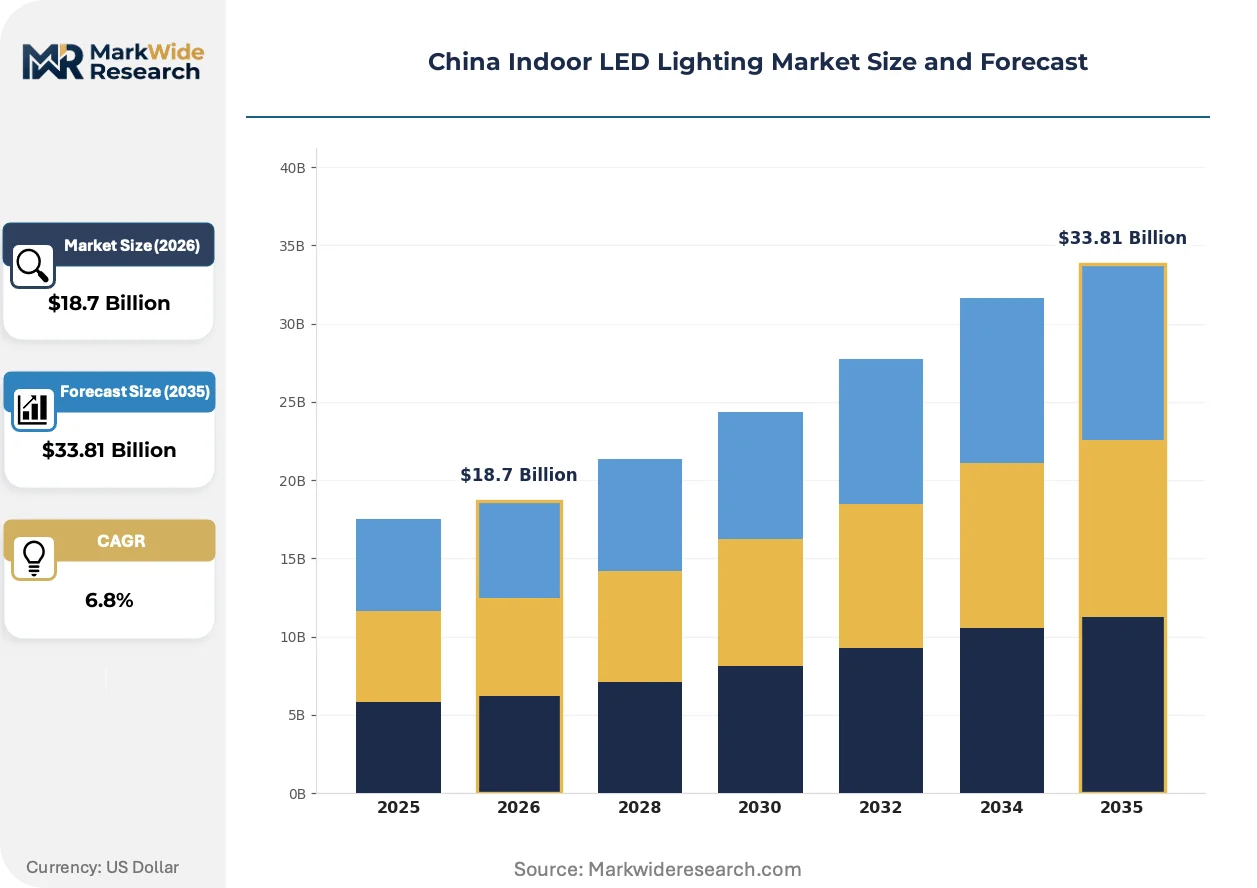
China's dual carbon goals from MEE are compressing fixture replacement cycles in commercial real estate while tightening compliance thresholds for luminous efficacy and lifecycle carbon disclosure across domestic production clusters.
Growth Catalysts
- GB Standard Elevation:Revisions to GB 7000 series safety standards and energy efficiency grades are disqualifying legacy fluorescent inventory from government and commercial tender pools, forcing wholesale upgrade cycles.
- Yangtze River Delta Concentration:Integrated chip-to-fixture production clusters in Zhejiang and Jiangsu provinces are shortening lead times for domestic and export buyers through captive supply of gallium nitride wafers and aluminum heat sinks.
- Smart Building Integration:Hospitality and office operators in Shanghai and Beijing are prioritizing occupancy-based automation and remote diagnostics, pulling demand toward connected luminaire platforms with embedded sensors.
Market Restraints
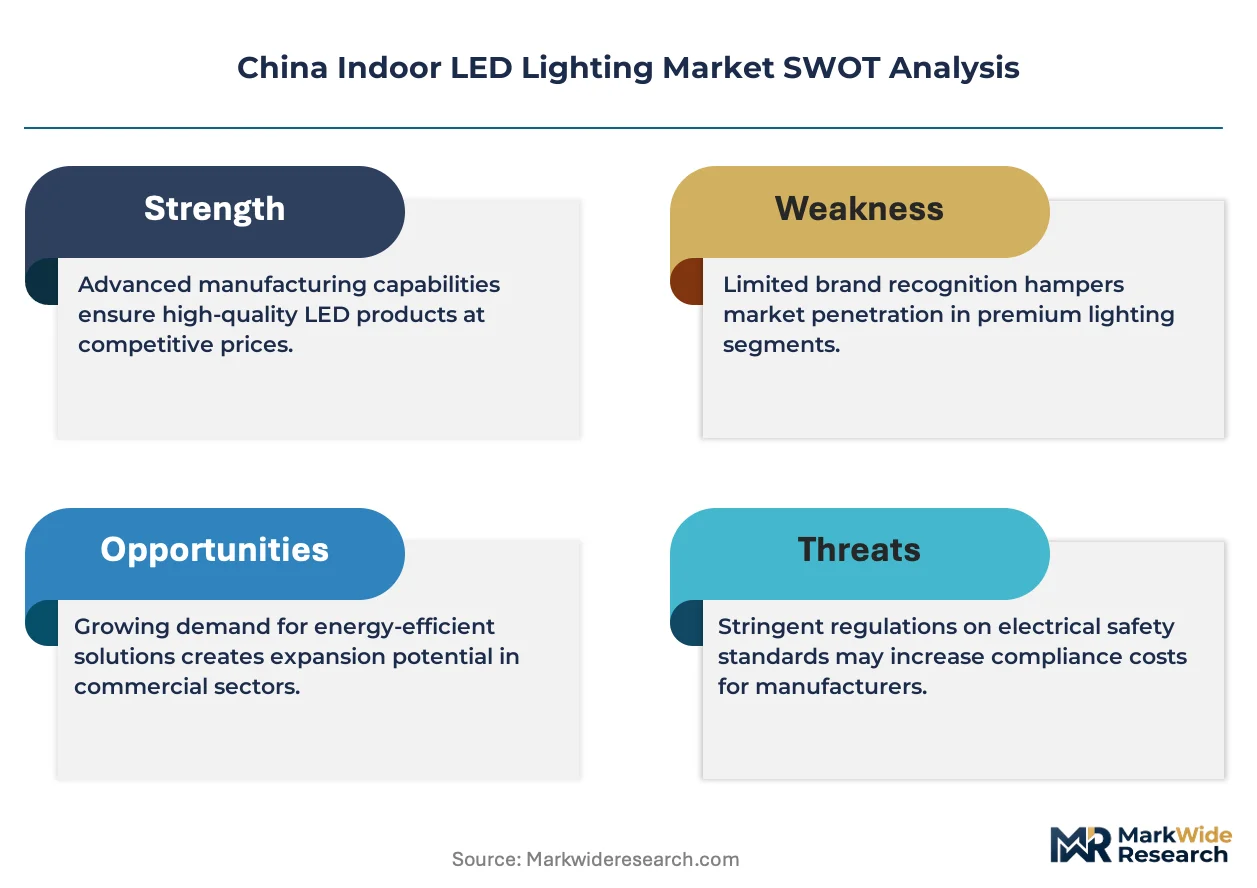
- Epoxy Resin Volatility:Polycarbonate diffuser and encapsulant input costs fluctuate with petrochemical feedstock pricing, compressing margin pools on economy-grade panel light SKUs.
- Chip Supply Concentration:Domestic gallium nitride epitaxy capacity concentrates among three Zhejiang-based foundries, creating vulnerability to regional power rationing or environmental compliance shutdowns.
- Fluorescent Substitute Persistence:T5 and T8 linear fluorescent tubes retain installed base in cost-sensitive industrial warehousing applications in inland provinces where payback period sensitivity delays LED conversion.
Strategic Opportunities
- Western Region Underpenetration:Sichuan and Shaanxi provinces exhibit fixture density gaps of 40-60% versus coastal benchmarks, creating whitespace for distributor network expansion and localized SKU development.
- Agricultural Application Emergence:Vertical farming and controlled-environment horticulture in Guangdong and Fujian are specifying tunable spectrum LED arrays for photoperiod manipulation, opening specialty luminaire demand.
- MEE Carbon Disclosure Mandate:Manufacturers who accelerate transition to low-temperature solder processes and publish verified lifecycle data will secure preferential eligibility in state-owned enterprise procurement frameworks.
Industry Challenges
- Optical Engineering Talent Scarcity:Human-centered lighting design and glare modeling expertise concentrates among senior specialists in Shanghai and Shenzhen, constraining product development velocity for mid-tier manufacturers.
- Legacy Control System Integration:Smart luminaire deployments in Beijing and Guangzhou commercial retrofits face friction with existing building management system protocols, extending commissioning timelines and eroding project IRRs.
- GB Certification Timeline Compression:Accelerated efficiency tier revisions are shortening valid certification windows, forcing manufacturers to maintain parallel testing pipelines and redundant documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Indoor LED Lighting Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Lights, Downlights, Troffers, High Bay Lights Technology: Smart Lighting, Dimmable, RGB, Human-Centric End User: Residential, Commercial Offices, Retail Spaces, Hospitality Installation: Surface Mounted, Recessed, Suspended, Track |
| Companies Covered | Zhejiang Yankon Group Co., Ltd., ams OSRAM AG, Opple Lighting Co., Ltd., Midea Lighting, TCL Lighting, NVC Lighting Holding Limited, Signify Holding B.V., Sansi LED, Foshan Lighting, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Indoor LED Lighting Market Trends and Innovations
Human-centric and circadian lighting specifications are penetrating healthcare and education verticals while miniaturized driver electronics enable fixture form factors previously constrained by thermal management requirements.
Mini-LED backlighting derived from display manufacturing is collapsing the cost curve for high-density chip-on-board arrays in downlight and spotlight applications. Five-star hotel operators in Shanghai and Sanya are specifying these packages for lobby and corridor retrofits where beam precision and dimming fidelity command premium positioning. The technology is collapsing differentiation between architectural specification-grade and volume commercial-grade product lines.
MIIT enforcement of GB 30255-2019 energy efficiency limits for indoor lighting is disqualifying basic COB packages below 100 lumens per watt from domestic sales channels. Manufacturers in Ningbo and Zhongshan are reconfiguring production lines to prioritize mid-power LED platforms with ceramic substrates. Commercial office fit-outs in Beijing's CBD district are now specifying Grade 1 or Grade 2 efficiency tiers exclusively, compressing procurement eligibility for lower-tier suppliers.
Direct-to-contractor e-commerce platforms are fragmenting procurement authority away from traditional distributor networks in second and third-tier cities. Project contractors in Chengdu and Wuhan are comparing real-time inventory and technical specifications through mobile interfaces, compressing the specification window and eroding offline distributor margin capture. This channel rotation is most visible in residential renovation and small commercial retrofit segments where project scale does not justify dedicated specification support.
China Indoor LED Lighting Market Segmentation
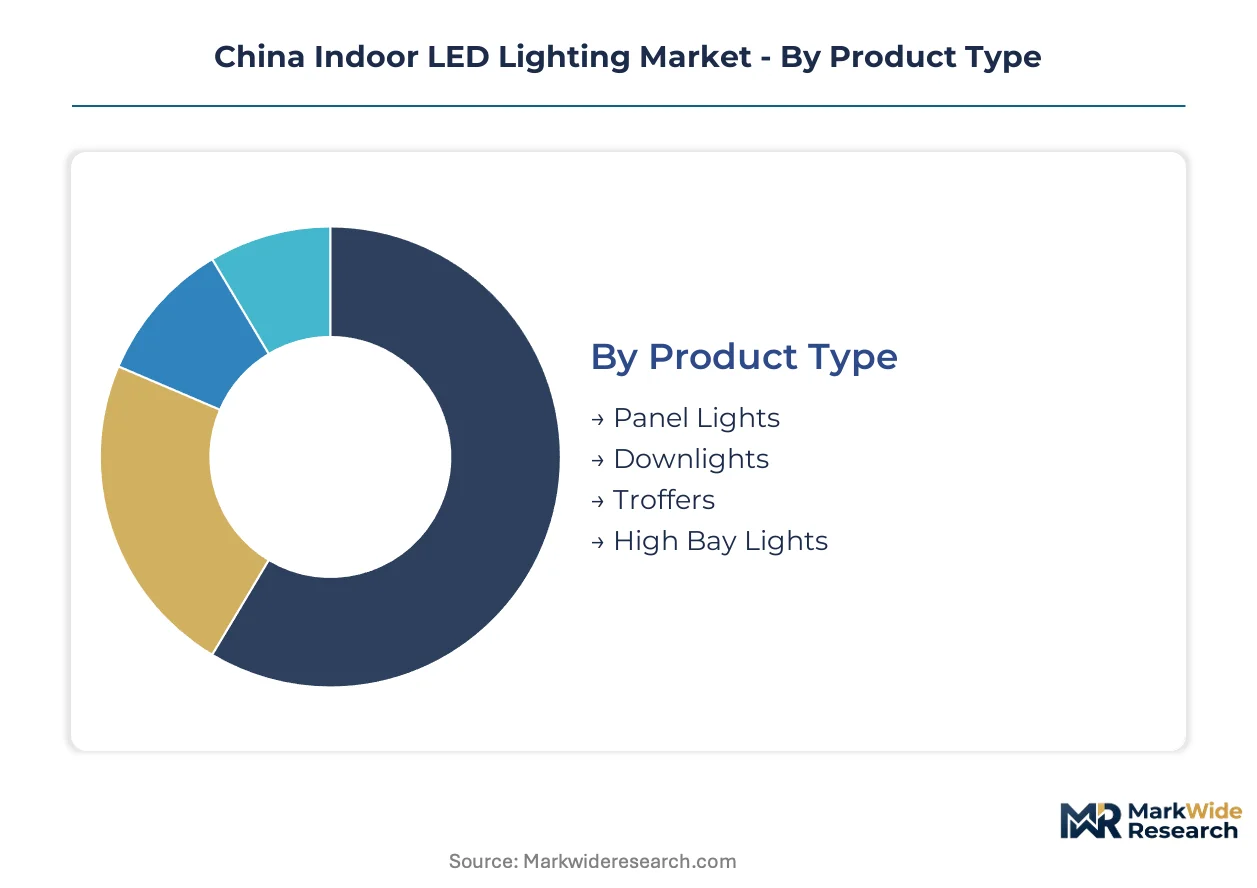
Segmentation in China's indoor LED lighting market reveals how procurement patterns diverge across fixture types, control technologies, and installation environments. These divisions expose where margin pools concentrate and which specifications command premium positioning versus commodity treatment.
Product Type:
After-sales service intensity varies sharply across fixture categories, with panel lights requiring minimal field support while high bay installations demand ongoing maintenance contracts.
- Panel Lights:Edge-lit and backlit flat panels with aluminum frames and PMMA diffusers deliver uniform illuminance for suspended ceiling grids. Demand concentrates in Beijing and Shanghai commercial office fit-outs where Grade 1 energy efficiency tiers are now mandatory.
- Downlights:COB and SMD recessed modules with beam angles from 15 to 60 degrees dominate residential renovation channels. Volume clusters in Guangdong province manufacturing corridors, though margin compression from basic package commoditization forces suppliers toward ceramic substrate upgrades.
- Troffers:Integrated lensed fixtures for T-bar ceiling systems serve retrofit markets in aging commercial building stock across second-tier cities.
- High Bay Lights:Industrial-grade fixtures with die-cast aluminum housings and high-lumen SMD arrays target warehousing applications in inland provinces where fluorescent conversion lags coastal benchmarks.
Panel lights hold the largest share; momentum sits with downlights as smart retrofit penetration accelerates in residential channels.
Technology:
Control sophistication determines pricing tiers, with basic dimmable units occupying volume segments while integrated smart platforms capture specification-grade margins.
- Smart Lighting:Connected luminaires with embedded occupancy sensors, daylight harvesting, and BMS integration command premium positioning in hospitality and Class A office retrofits. Shanghai property operators prioritize these platforms for remote diagnostics and energy compliance reporting.
- Dimmable:Phase-cut and 0-10V analog dimming modules serve cost-sensitive commercial segments where basic illuminance control satisfies regulatory minimums without connectivity overhead.
- RGB:Multi-channel LED engines with independent red, green, and blue die address architectural accent and entertainment venue applications in tier-one cities.
- Human-Centric:Tunable white and circadian-optimized spectra with melanopic lux targeting penetrate healthcare and education verticals where GB standards now reference biologic impact metrics.
Dimmable platforms retain the broadest installed base; human-centric specifications are expanding most quickly as healthcare retrofit standards tighten.
End User:
Customer procurement authority shapes channel strategy, with commercial offices consolidating through specification consultants while residential buyers fragment across e-commerce and contractor networks.
- Residential:Renovation-driven demand in tier-two and tier-three cities concentrates through direct-to-contractor platforms that compress traditional distributor margins.
- Commercial Offices:Grade 1 efficiency tier mandates in Beijing's CBD and Shanghai's Lujiazui district disqualify lower-tier suppliers from new build and major retrofit tenders.
- Retail Spaces:Brand-conscious operators in Shenzhen and Guangzhou specify high-CRI downlight and track combinations for merchandise presentation.
- Hospitality:Five-star hotel operators in Sanya and Shanghai deploy smart lighting with scene preset programming for lobby and corridor environments.
Commercial offices generate the highest revenue concentration; hospitality is gaining share fastest as occupancy-based automation becomes standard in premium properties.
Installation:
Mounting method dictates fixture form factor and thermal management architecture, with recessed designs requiring the most complex housing engineering.
- Surface Mounted:Direct-ceiling applications in concrete slab construction dominate retrofit markets where plenum access is limited.
- Recessed:Downlight and panel formats for suspended gypsum or mineral fiber ceilings serve new commercial construction across the Yangtze River Delta.
- Suspended:Pendant-mounted linear and high bay fixtures address industrial and atrium applications with high ceiling clearances.
- Track:Three-circuit and DALI-compatible rail systems enable flexible retail and gallery lighting repositioning.
Recessed installation holds the largest share; suspended configurations are climbing the fastest as industrial LED conversion penetrates inland warehousing markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB 30255-2019 efficiency mandates and MEE's dual carbon disclosure requirements are redistributing procurement eligibility across China's provincial markets. Provincial governments in coastal manufacturing corridors enforce stricter compliance windows than inland counterparts.
Yangtze River Delta
Shanghai commercial office fit-outs now require Grade 1 efficiency tiers exclusively. Jiangsu and Zhejiang provincial authorities coordinate with MIIT to accelerate low-temperature solder process adoption across integrated chip-to-fixture clusters. Ningbo and Zhongshan manufacturing bases supply gallium nitride wafers and aluminum heat sinks to domestic and export buyers with shortened lead times.
Pearl River Delta
Guangdong's vertical farming installations in Shenzhen and Guangzhou specify tunable spectrum LED arrays for photoperiod manipulation. The provincial quality supervision bureau enforces GB 7000 series safety standards with accelerated inspection cycles. Foshan and Zhongshan fixture manufacturing corridors concentrate COB and SMD package production for residential renovation channels.
Beijing-Tianjin-Hebei
Beijing's CBD district mandates connected luminaire platforms with embedded sensors for Class A office retrofits. MEE carbon disclosure requirements force manufacturers to publish verified lifecycle data for state-owned enterprise procurement eligibility. Tianjin port infrastructure serves as the primary export gateway for fixtures bound to Belt and Road markets.
Sichuan-Chongqing
Chengdu contractor networks are migrating procurement to direct-to-contractor e-commerce platforms that compress traditional distributor margins. The provincial development and reform commission offers efficiency retrofit subsidies for commercial building stock. Chongqing's manufacturing base supplies economy-grade panel lights to western China markets where fixture density trails coastal benchmarks.
Shandong Peninsula
Qingdao and Jinan hospitality operators deploy smart lighting with scene preset programming as occupancy-based automation becomes standard. Provincial market supervision administrations align GB certification timelines with MIIT national schedules. Local production clusters focus on high bay fixtures for industrial warehousing applications in inland provinces.
China Indoor LED Lighting Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers distinguished by manufacturing scale and specification-grade capability. Vertically integrated chip-to-fixture operators capture government and commercial tender pools through captive gallium nitride supply. Mid-scale specialists compete on ceramic substrate upgrades and rapid GB certification turnaround. Pure-play distributors face margin compression as e-commerce platforms fragment procurement authority in tier-two and tier-three cities. Capacity expansion and strategic partnerships represent the dominant competitive moves across all tiers.
Among Zhejiang-based integrated manufacturers, Zhejiang Yankon Group Co., Ltd. exemplifies the scale-driven archetype with chip-to-fixture production concentration. Opple Lighting Co., Ltd. and NVC Lighting Holding Limited represent contrasting channel strategies—direct-to-contractor platforms versus extensive offline distributor networks. These three entities anchor the competitive structure that smaller regional fabricators and international technology licensors must navigate.
| Leading Market Players |
|---|
| Zhejiang Yankon Group Co., Ltd. |
| ams OSRAM AG |
| Opple Lighting Co., Ltd. |
| Midea Lighting |
| TCL Lighting |
| NVC Lighting Holding Limited |
| Signify Holding B.V. |
| Sansi LED |
| Foshan Lighting |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride epitaxy concentration among three Zhejiang-based foundries determines both pricing tier spreads and supply chain shape, compressing margin pools when regional power rationing or environmental compliance shutdowns disrupt wafer supply to downstream fixture manufacturers.
Pricing Analysis
GB energy efficiency grade creates the primary spread across pricing tiers, with Grade 1 certified luminaires commanding premium positioning in Beijing and Shanghai commercial tenders while Grade 3 products serve price-sensitive inland renovation channels. Three-tier pricing structure across premium, standard, and economy levels reflects ceramic substrate differentiation, smart control integration, and after-sales service bundling. Cost compression in economy-grade panel light SKUs is intensifying because polycarbonate diffuser input costs fluctuate with petrochemical feedstock pricing. Residential renovation contractors in tier-two cities exhibit highest price sensitivity, whereas five-star hospitality operators in Shanghai demonstrate lowest sensitivity when specifying human-centric lighting platforms.
Supply Chain Analysis
Sanan Optoelectronics, HC SemiTek, and Changelight hold dominant gallium nitride epitaxy capacity serving downstream fixture fabricators. Supply concentrates in Zhejiang and Jiangsu provinces for chip-to-fixture integration, with aluminum heat sink sourcing anchored in Guangdong die-casting clusters. Raw material dependencies span gallium nitride wafers, polycarbonate diffusers, and low-temperature solder alloys. Single-source vulnerability concentrates in Zhejiang epitaxy foundries where environmental compliance shutdowns cascade through captive supply chains. Distribution runs through direct-to-contractor e-commerce platforms that fragment traditional offline distributor networks in second and third-tier cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart lighting platform economics are reshaping procurement authority, as interoperability between luminaire sensors and building management systems determines specification eligibility in Class A office retrofits across Shanghai and Beijing.
For Market Incumbents: Harden GB certification pipelines against accelerated efficiency tier revisions by maintaining parallel testing workflows and redundant documentation systems. Deepen upstream control over gallium nitride wafer supply through captive foundry partnerships or long-term offtake agreements with Zhejiang epitaxy operators. Defensive positioning requires preemptive investment in low-temperature solder process transition before MEE carbon disclosure mandates tighten procurement eligibility for state-owned enterprise tenders. For New Entrants and Emerging Players: Mid-market commercial buildings in Sichuan and Shaanxi provinces represent the most penetrable entry point, where fixture density gaps of 40-60% versus coastal benchmarks create whitespace for localized SKU development. Agricultural applications in Guangdong vertical farming installations offer specialty luminaire demand with limited incumbent saturation. Direct-to-contractor platform partnerships provide the most viable go-to-market angle, bypassing entrenched offline distributor networks that dominate tier-two and tier-three city procurement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated chip-to-fixture operators with captive gallium nitride supply and Grade 1 certification velocity. Long-term viability over the next decade hinges on carbon disclosure compliance and smart platform interoperability rather than pure manufacturing scale. Acquisition targets should demonstrate low-temperature solder process maturity and verified lifecycle data publication capabilities. Monitor MEE efficiency tier revision announcements as the primary inflection indicator for procurement eligibility redistribution across government and commercial tender pools.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Temperature Solder Process Transition | MEE carbon disclosure mandates will disqualify manufacturers lacking verified lifecycle data from state-owned enterprise procurement frameworks. |
| Direct-to-Contractor Platform Expansion | E-commerce migration in Chengdu and Wuhan compresses traditional distributor margins and fragments specification authority in residential renovation segments. |
| Captive Gallium Nitride Epitaxy Investment | Backward integration into wafer production insulates against Zhejiang foundry concentration risk from regional power rationing or environmental shutdowns. |
| Human-Centric Lighting R&D Acceleration | Healthcare and education verticals in Shanghai and Beijing now reference biologic impact metrics in GB standards for melanopic lux targeting. |
| Western Region Distributor Network Buildout | Sichuan and Shaanxi fixture density gaps create whitespace for localized SKU development and contractor relationship cultivation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MIIT regulatory filings, GB standard revision documents, and provincial development commission retrofit subsidy records. The research team conducted structured interviews with commercial property operators in Shanghai and Beijing, lighting fixture procurement managers at state-owned enterprises, distributor network heads in Chengdu and Wuhan, and technical directors at Zhejiang manufacturing clusters. Secondary validation drew from customs export data, Yangtze River Delta industrial park production statistics, and MEE carbon disclosure compliance registries. Bottom-up fixture shipment estimates triangulated against top-down market sizing across the analysis window.
Forecast inputs include modeled penetration rates for smart lighting platforms in hospitality and commercial office verticals, efficiency tier adoption curves mandated by GB 30255-2019 revisions, and regional fixture density convergence patterns between coastal and inland provinces. Segmentation dimensions span product type, control technology sophistication, end-user procurement authority, and installation method. CAGRs were derived from regression analysis of historical shipment data against regulatory compliance deadlines and carbon policy implementation timelines. Industry-specific inputs incorporate gallium nitride wafer supply forecasts and low-temperature solder process adoption rates across integrated manufacturing clusters.
Stress conditions across Zhejiang foundry power rationing severity, polycarbonate feedstock price volatility bands, and GB certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding MEE dual carbon goal enforcement consistency and MIIT efficiency tier revision cadence. Specific risk factors that could revise projections include abrupt environmental compliance shutdowns at epitaxy facilities, accelerated fluorescent phase-out mandates in inland provinces, and interoperability standard fragmentation in building management system protocols. Quarterly review of MEE carbon disclosure mandate expansion and MIIT GB revision announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Gan Micro LED Market
LED
North America LED Lighting Market
LED
North America Commercial LED Lighting Market
LED
Dot-Matrix LED Displays Market
LED
LED Light Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
Europe LED Packaging Market
LED
Europe LED Lighting Market
LED
Bi-Color LED Ring Light Market
LED
Infrared (IR) LED Market
LED
LED Street Light Drivers Market
LED
US Outdoor LED Lighting Market
LED
LED Floodlight Drivers Market
LED
Monochrome Outdoor LED Display Market
LED
Led Video Walls Market
LED
Light Emitting Diode (LED) Backlight Display Market