
 Pixel Pitch LED Market | 2026-2036
Pixel Pitch LED Market Size, Share, and Industry Trends Forecast 2026-2036
Pixel Pitch LED Market Analytics
Leasing and project-finance arrangements for large-format LED deployments is reconfiguring competitive access across the Pixel Pitch LED landscape. Unilumin Group leverages captive manufacturing in Shenzhen to anchor premium indoor contracts. Barco competes through specialized visualization systems for broadcast and control-room environments. Absen Optoelectronic sustains channel control across mid-tier international markets with standardized outdoor panel platforms.
Pixel pitch LED denotes direct-view display technology where the distance between adjacent LED centers, measured in millimeters, determines resolution density and optimal viewing distance; sub-2mm configurations suit close-proximity indoor applications while 4mm and above serve distant-viewing outdoor installations. Indoor LED commands the dominant margin pool as broadcast, corporate, and retail buyers prioritize fine-pitch clarity for confined spaces. Transparent LED occupies a narrow but expanding niche in architectural integration and luxury retail facades where physical sightlines must persist behind digital content. COB technology leads structural innovation by eliminating individual LED encapsulation, improving thermal performance and enabling tighter pixel densities than conventional SMD mounting permits.
FCC equipment authorization rules in the United States constrain electromagnetic emissions from dense LED driver circuitry, shaping product design cycles for North American-bound inventory. The EU Ecodesign Framework and CE marking requirements filter market access for displays sold across European member states, particularly on standby power thresholds. China's MIIT certification mandates energy-label compliance that influences both domestic procurement and export eligibility from Shenzhen and Dongguan production bases. Stakeholders must monitor how regional efficiency standards diverge and whether certification harmonization or fragmentation determines factory-level product variant strategies.
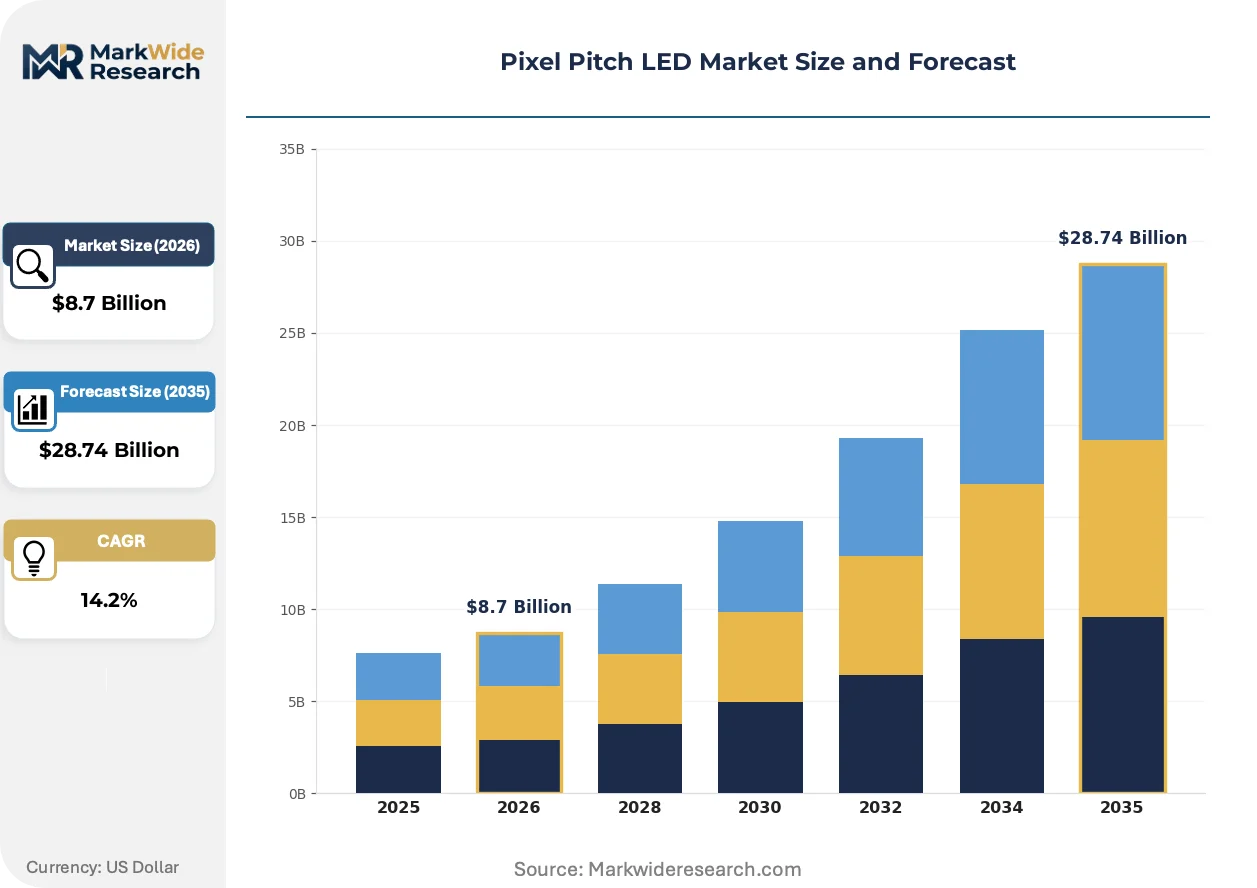
Market Dynamics
COB technology is compressing pixel densities below 1mm while MIIT energy-label mandates in Shenzhen and Dongguan production bases force factory-level product variant strategies that bifurcate domestic and export inventory streams.
Growth Catalysts
- MIIT Certification Directives:China's tightening energy-efficiency standards for display products are filtering import eligibility and accelerating domestic procurement of certified sub-2mm panels for command centers and broadcast studios.
- Guangdong Manufacturing Corridor:Panel assembly clusters in Shenzhen and Dongguan concentrate captive production capacity serving both domestic buyers and export markets with shortened lead times.
- Sub-2mm Indoor Deployments:Broadcast studios and corporate control rooms in the United States are accelerating procurement of fine-pitch LED for close-proximity viewing applications where LCD alternatives fail.
Market Restraints
- Driver IC Supply Concentration:Dense LED driver circuitry relies on concentrated semiconductor foundry capacity in East Asia, exposing North American and European integrators to allocation risk during demand spikes.
- FCC Authorization Friction:Electromagnetic emissions testing for dense driver configurations extends product design cycles by 4-8 weeks for North American-bound inventory, compressing competitive response windows.
- Micro-LED Substitution Threat:Emerging micro-LED architectures promise superior thermal performance and pixel density for premium indoor segments above 100-inch diagonal, threatening COB LED's technology roadmap.
Strategic Opportunities
- Transparent LED Architectural Integration:Luxury retail facades and museum installations in Western Europe are adopting transparent LED where physical sightlines must persist behind digital content, opening premium pricing tiers.
- EU Ecodesign Standby Power Thresholds:Tightening CE marking requirements for standby consumption are creating competitive separation between compliant and non-compliant suppliers across European member states.
- Leasing and Project-Finance Models:Large-format deployment contracts are shifting from capital purchase to operational expenditure structures, enabling vendor capture of recurring revenue streams and customer lock-in.
Industry Challenges
- COB Thermal Management Expertise Gap:Chip-on-board manufacturing requires specialized die-bonding and phosphor-coating talent concentrated in Guangdong province, limiting replication elsewhere.
- Multi-Certification Parallel Tracking:Simultaneous FCC, CE marking, and MIIT compliance for global product lines demands dedicated regulatory affairs capacity that mid-tier manufacturers struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pixel Pitch LED Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor LED, Outdoor LED, Transparent LED, Flexible LED Application: Advertising, Entertainment, Sports, Retail End User: Event Organizers, Retailers, Corporate, Stadiums Technology: SMD, COB, OLED, Micro LED |
| Companies Covered | Liantronics, AOTO Electronics, Leyard Optoelectronic, SiliconCore Technology, Barco, Unilumin Group, Samsung Electronics, Planar Systems, Absen Optoelectronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pixel Pitch LED Market Evolving Landscape
Virtual production stages and extended reality broadcast environments are redefining pixel pitch requirements, while regulatory fragmentation across major economies forces modular product architectures.
COB (Chip-on-Board) technology is virtualizing traditional SMD mounting by eliminating individual LED encapsulation, enabling direct die attachment to substrate. Broadcast studios in Los Angeles and London are adopting COB panels for virtual production volumes where camera proximity demands sub-1.5mm pitch without moiré artifacts. This architecture is virtualizing the supply chain by collapsing封装 (packaging) tiers and concentrating value capture at the die-bonding stage.
China's MIIT energy-label compliance mandates are tightening certification requirements for display products sold domestically and exported from Shenzhen production bases. The industrial consequence is factory-level SKU proliferation, with separate bill-of-materials for MIIT-compliant domestic inventory versus FCC-authorized North American shipments. Guangdong-based manufacturers are responding with modular driver designs that accommodate regional certification swaps without full panel redesign.
Leasing structures for large-format LED deployments are displacing traditional capital purchase models in corporate and broadcast verticals. Systems integrators are bundling installation, content management software, and preventive maintenance into multi-year contracts that shift buyer preference toward vendor financial stability over upfront hardware cost. This pattern is most visible in United States broadcast network upgrades, where operational expenditure treatment aligns with content production budget cycles.
Pixel Pitch LED Market Segmentation
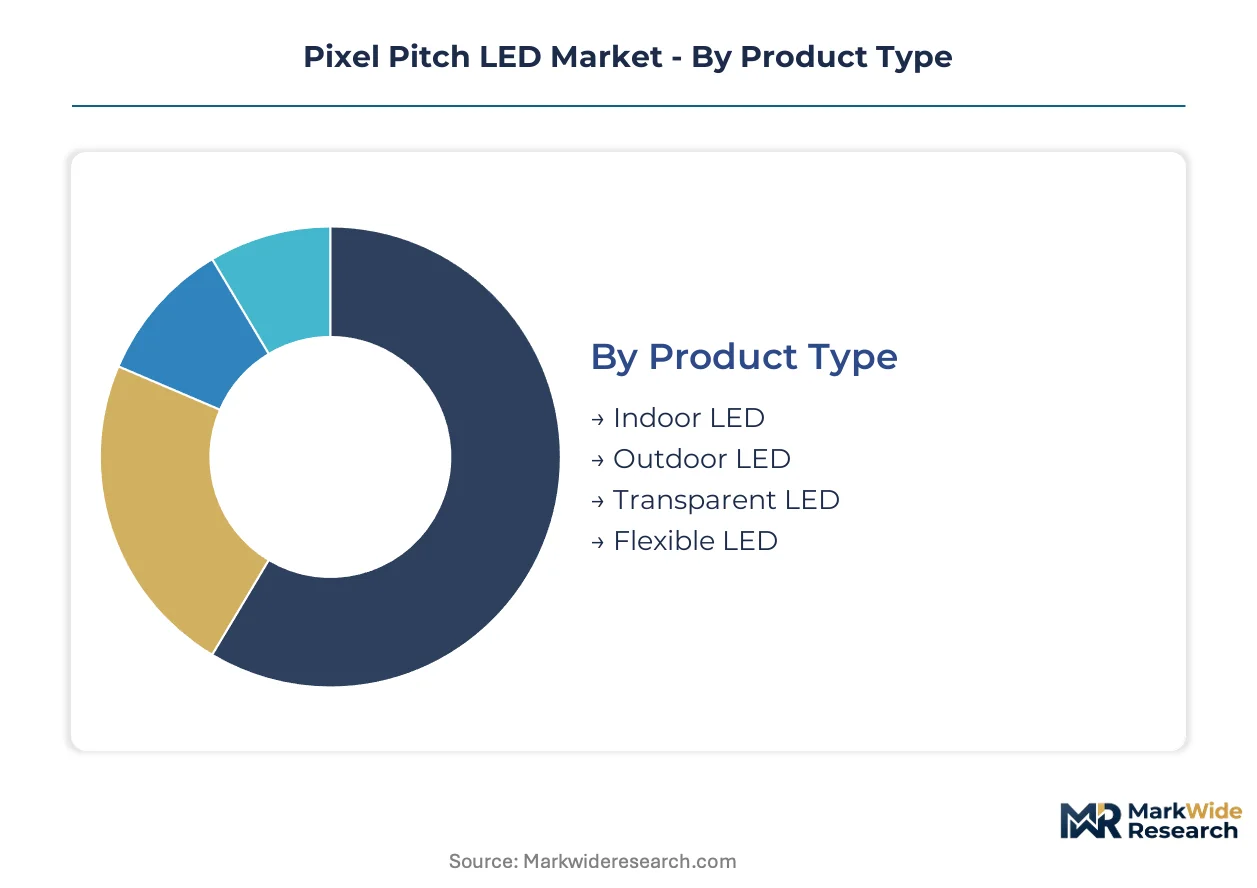
Pixel pitch LED configurations diverge sharply by environmental exposure, mechanical flexibility, and resolution density. Each product and technology category carries distinct certification burdens and margin profiles that reshape procurement patterns across broadcast, retail, and architectural verticals.
Product Type:
Mature indoor and outdoor formats anchor procurement volumes while emerging transparent and flexible architectures unlock premium pricing tiers for specialized installations.
- Indoor LED:Sub-2mm pitch configurations dominate broadcast studios and corporate command centers where camera proximity demands moiré-free clarity. Guangdong manufacturers concentrate COB production for this segment to satisfy MIIT energy-label compliance and FCC electromagnetic authorization for North American exports.
- Outdoor LED:Weather-sealed enclosures with 4mm and above pitch serve stadium perimeters and highway advertising where viewing distances exceed 50 meters. Shenzhen assembly clusters optimize driver IC thermal management for extended temperature cycling in exposed environments.
- Transparent LED:Mesh architectures preserve physical sightlines behind digital content for luxury retail facades and museum atriums.
- Flexible LED:Polymer substrate mounting enables curved and cylindrical installations for immersive environments and architectural integration.
Indoor LED retains volume leadership; transparent LED holds the steepest expansion curve.
Application:
Cost tier stratification separates high-frequency content refresh advertising from capital-intensive permanent installations in sports and entertainment venues.
- Advertising:Digital out-of-home networks prioritize rapid deployment and remote content management over resolution density. Leasing structures dominate procurement as media operators shift capital expenditure to operational treatment.
- Entertainment:Virtual production stages in Los Angeles and London demand sub-1.5mm COB panels for camera-proximity shooting without artifacts. Extended reality broadcast environments are compressing replacement cycles as studios refresh volumes for streaming content pipelines.
- Sports:Perimeter ribbon and center-hung installations require 24/7 reliability ratings and rapid module swap capability.
- Retail:Flagship stores blend transparent LED facades with interactive floor displays to merge physical and digital merchandising.
Advertising commands the broadest installed base; entertainment applications are gaining share fastest through virtual production adoption.
End User:
Customer type determines procurement velocity, with event-driven organizers prioritizing rental flexibility against permanent infrastructure buyers.
- Event Organizers:Rental inventory managers prioritize rapid rigging and module interchangeability for touring productions and temporary installations.
- Retailers:Luxury brands commission transparent LED facades in Western Europe where CE marking standby power thresholds filter supplier eligibility.
- Corporate:Control room and broadcast facility buyers demand sub-2mm pitch with 24/7 reliability warranties and embedded maintenance contracts.
- Stadiums:Sports venue operators specify weather-hardened outdoor panels with centralized diagnostics and five-year module replacement guarantees.
Corporate buyers concentrate premium procurement; event organizers drive rental market liquidity.
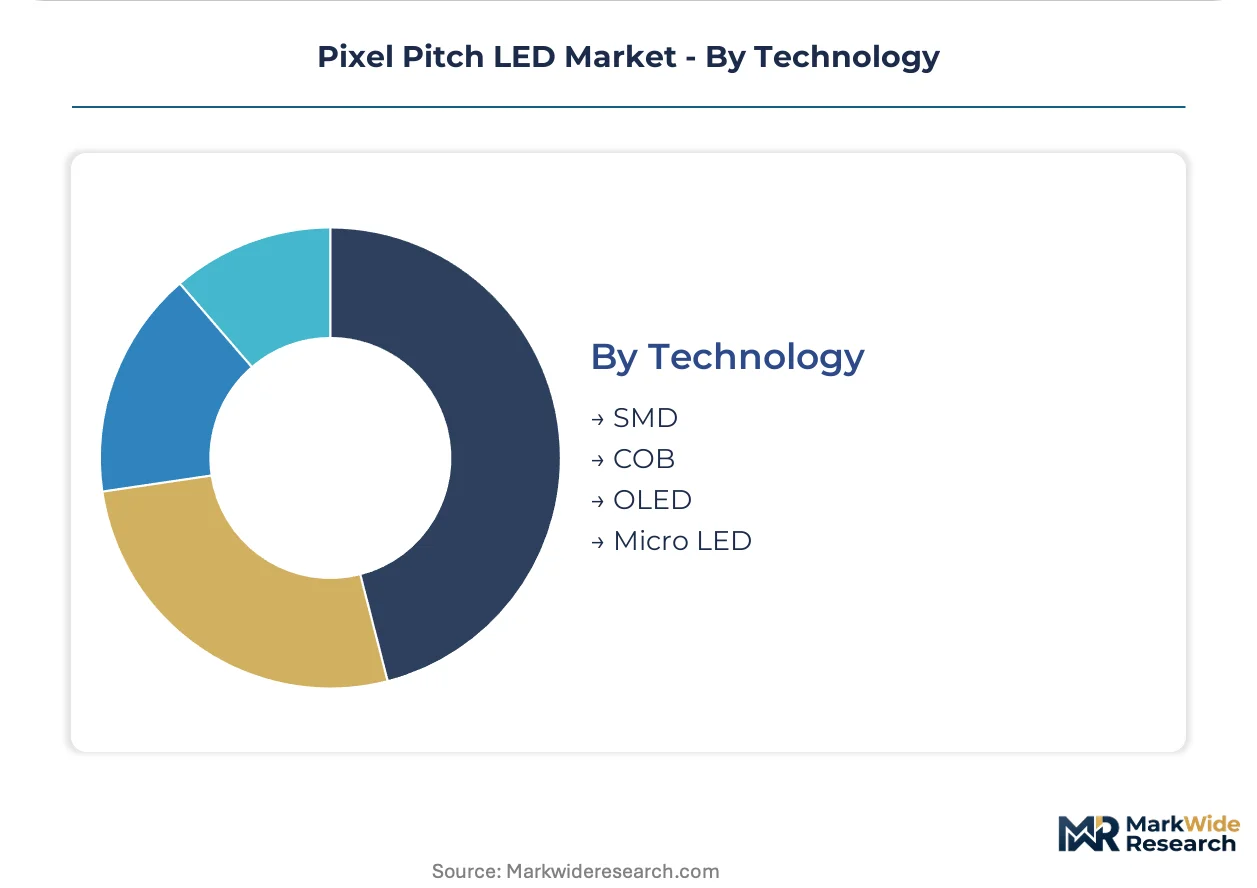
Technology:
Supply concentration around die-bonding expertise in Guangdong province limits replication of advanced architectures outside established manufacturing corridors.
- SMD:Surface-mount device packaging remains the cost-optimized standard for outdoor and mid-tier indoor applications where pixel density requirements stay above 2mm.
- COB:Chip-on-board eliminates individual LED encapsulation, enabling sub-1mm pitch and superior thermal performance for broadcast virtual production. Shenzhen manufacturers capture value at the die-bonding stage, collapsing traditional packaging tiers.
- OLED:Organic emissive layers compete in sub-100-inch diagonal segments where self-emissive contrast ratios outweigh LED brightness advantages.
- Micro LED:Mass transfer yields and repair economics currently constrain deployment to premium segments above 100-inch diagonal, threatening COB's roadmap for highest-density applications.
SMD retains volume leadership; COB holds the steepest expansion curve through broadcast studio adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT energy-label mandates are filtering import eligibility and accelerating domestic procurement across major manufacturing economies. Regulatory divergence between FCC, CE marking, and MIIT certification regimes is forcing modular product architectures and factory-level SKU proliferation.
United States
Broadcast studios in Los Angeles and corporate command centers in New York Metro are accelerating sub-2mm indoor deployments. FCC equipment authorization rules constrain electromagnetic emissions from dense LED driver circuitry, extending design cycles for North American-bound inventory. Systems integrators in the Southeast are bundling installation and maintenance into multi-year operational expenditure contracts.
China
Guangdong province's LED manufacturing corridor concentrates panel assembly clusters serving domestic and export buyers with shortened lead times. MIIT certification mandates energy-label compliance that influences both domestic procurement and export eligibility from Shenzhen and Dongguan production bases. Shenzhen manufacturers are responding with modular driver designs that accommodate regional certification swaps without full panel redesign.
Germany
Luxury automotive showrooms in Bavaria and museum installations in Berlin are adopting transparent LED facades where physical sightlines must persist behind digital content. EU Ecodesign Framework and CE marking requirements filter market access, particularly on standby power thresholds. Industrial buyers in Baden-Württemberg prioritize compliant suppliers for permanent architectural integrations.
United Kingdom
Virtual production stages in London and extended reality broadcast environments are compressing replacement cycles as studios refresh volumes for streaming content pipelines. CE marking requirements align with EU Ecodesign standards post-Brexit transition, maintaining regulatory continuity for display products. Corporate headquarters in the Southeast are leasing large-format LED deployments rather than capital purchase.
Japan
Broadcast facilities in Tokyo and Osaka are adopting sub-1.5mm COB panels for camera-proximity shooting without moiré artifacts. METI standards influence domestic procurement preferences for energy-efficient display technologies. Manufacturing clusters in Chubu region supply specialized die-bonding equipment to Guangdong production bases.
Pixel Pitch LED Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct strategic tiers: Guangdong-based captive manufacturers with integrated die-bonding capabilities, European and North American visualization specialists serving broadcast and control-room verticals, and mid-tier international platforms optimizing for standardized outdoor deployments. Two dominant competitive moves are reshaping positioning: leasing and project-finance arrangements that shift buyer preference toward vendor financial stability, and modular certification architectures that accommodate regional regulatory divergence without full product redesign.
Within the captive manufacturing tier, Unilumin Group and Absen Optoelectronic exemplify supply-side concentration in Shenzhen and Dongguan production corridors. Barco occupies a position among visualization specialists serving broadcast and control-room environments. Leyard Optoelectronic sits within the tier of China-based fabricators with integrated COB production capabilities. These three anchors demonstrate how geographic clustering around die-bonding expertise in Guangdong province limits replication of advanced architectures outside established manufacturing corridors.
| Leading Market Players |
|---|
| Liantronics |
| AOTO Electronics |
| Leyard Optoelectronic |
| SiliconCore Technology |
| Barco |
| Unilumin Group |
| Samsung Electronics |
| Planar Systems |
| Absen Optoelectronic |
| Others |
Value Network & Pricing Analysis
Shenzhen-Dongguan freight corridors connecting Guangdong assembly clusters to Shanghai and Hong Kong ports transmit driver IC cost volatility directly into panel pricing spreads. Logistics compression in this corridor amplifies margin pressure on mid-tier manufacturers while rewarding captive producers with in-house die-bonding capacity.
Pricing Analysis
Certification level creates the primary spread between domestic MIIT-compliant inventory and FCC-authorized export SKUs. Three-tier pricing structure across premium COB sub-1mm, standard SMD 2-4mm, and economy outdoor 4mm-plus configurations dominates transactional contracts. Cost compression in standard-tier panels is intensifying because driver IC allocation constraints force spot-market premiums during demand spikes. Event organizers and rental fleet operators exhibit highest price sensitivity; broadcast studios purchasing virtual production volumes show lowest sensitivity due to operational expenditure treatment.
Supply Chain Analysis
Driver IC wafer fabrication draws from Taiwan, South Korea, and Japan foundry capacity. LED die supply rests on epitaxial wafer production in China, Taiwan, and Germany. Phosphor materials and substrate ceramics hinge on Japanese and Chinese chemical processors. Single-source vulnerability concentrates in advanced node driver ICs below 28nm. Distribution runs through systems integrators bundling installation, content management, and maintenance into multi-year operational contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where modular certification architectures and leasing structures are redefining vendor lock-in. Interoperability between content management software and hardware platforms determines switching costs.
For Market Incumbents: Build captive die-bonding moats through Guangdong facility expansion to defend against micro-LED substitution in premium indoor segments. Deepen backward integration into driver IC inventory buffers to mitigate Taiwan foundry allocation risk. Secure MIIT and FCC pre-certification for modular panel designs to compress competitive response windows.
For New Entrants and Emerging Players: Latin American stadium infrastructure and Southeast Asian corporate headquarters represent underpenetrated white-space targets. Transparent LED architectural integration in Western European luxury retail offers premium pricing escape from SMD commoditization. Partner with regional systems integrators lacking captive manufacturing to bypass Guangdong supply concentration.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with underutilized COB production lines and dormant MIIT certification pathways. Long-term viability favors vendors with embedded software platforms and recurring maintenance revenue over pure hardware fabricators. Watch virtual production stage deployment velocity in Los Angeles and London as inflection signal for COB demand durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Certification Architecture | Enables Shenzhen manufacturers to swap MIIT, FCC, and CE driver configurations without full panel redesign. |
| Leasing Model Expansion | Shifts broadcast studio procurement from capital expenditure to operational expenditure with vendor lock-in. |
| COB Die-Bonding Scale-Up | Concentrates value capture at Guangdong production bases and collapses traditional LED packaging tiers. |
| Transparent LED Product Line | Opens premium pricing tiers in Western European luxury retail facades requiring physical sightline preservation. |
| Content Management Platform Integration | Creates switching costs between hardware vendors and studio production software ecosystems. |
Research Methodology
Desk research of customs trade databases, FCC equipment authorization filings, and MIIT certification registries preceded structured interviews with LED panel procurement managers at broadcast networks, systems integrators specializing in virtual production, regulatory affairs directors at Guangdong manufacturers, and content management software vendors. Primary fieldwork with Shenzhen and Dongguan production facility managers validated capacity utilization and driver IC inventory practices. Bottom-up volume estimates by pixel pitch tier and application were cross-checked against top-down industry revenue benchmarks.
Assumptions held constant include prevailing MIIT energy-label thresholds, FCC electromagnetic emission limits, and Taiwan foundry allocation patterns across the analysis window. Modeled segmentation spans product type, application vertical, end-user category, and technology architecture. CAGRs were derived from regression analysis of historical procurement cycles and projected replacement rates in virtual production environments. Driver IC pricing volatility and micro-LED yield improvement trajectories served as sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by micro-LED specialists or sudden MIIT standard tightening would shift outcomes. Cross-checking against hyperscaler capex disclosures for extended reality infrastructure and broadcast network public filings for stage refurbishment schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Encapsulation Market
LED
Saudi Arabia LED Lights Market
LED
LED Digital Scoreboard Market
LED
UAE LED Lights Market
LED
LED Display Control Card Market
LED
East Africa LED Lighting Market
LED
Microled Market
LED
LED Driver Market
LED
OLED Blue Emitter Market
LED
Chip on Board LED Market
LED
LED Floodlight Drivers Market
LED
Single-Digit 7 Segment LED Displays Market
LED
Led Video Walls Market
LED
LED Panel Market
LED
Outdoor LED Display Market
LED
High-Brightness LED Market