
 LED Driver Market | 2026-2036
LED Driver Market Size, Share, and Industry Trends Forecast 2026-2036
LED Driver Market Intelligence
Manufacturing expansion in Vietnam is narrowing the historic production concentration in mainland China. MEAN WELL Enterprises leverages its extensive catalog of standard power supplies for industrial and commercial channels. Signify sustains its market position through integrated lighting systems and controls. Texas Instruments competes on the basis of its semiconductor-level component integration for driver integrated circuits.
An LED driver is an electronic circuit that rectifies and regulates electrical power for light-emitting diodes. Its primary function is to convert AC mains voltage into a stable, low-voltage DC output, ensuring consistent current to prevent LED degradation. Street lighting and automotive OEM applications represent significant volume, demanding high reliability. Within product types, demand for programmable and dimmable drivers is accelerating for smart building and architectural lighting projects.
Product design is governed by multiple standards, including the EU's CE marking for safety and RoHS for hazardous substances. In the United States, FCC Part 15 regulations limit electromagnetic interference, a critical parameter for all electronic drivers. Component selection and circuit topology decisions will increasingly hinge on meeting stricter energy efficiency tiers and interoperability protocols.
Market Dynamics
The push for greater energy efficiency, mandated by regulations like the EU's Ecodesign framework, creates tension with the cost-sensitive nature of a market whose production capacity remains highly concentrated in specific manufacturing clusters within China.
Growth Catalysts
- Smart Building Integration:Demand for programmable and dimmable drivers is accelerating for smart building projects, which require interoperability with control systems like DALI to enable energy management and automated lighting scenes.
- Automotive Systems:The uptake of advanced driver-assistance systems and adaptive matrix headlamps in automotive OEM applications represents a significant volume catalyst, demanding high-reliability drivers certified for harsh operating environments.
- Efficiency Mandates:Regulations such as the EU's Ecodesign for Sustainable Products Regulation compel design innovation, pushing manufacturers toward more efficient circuit topologies and advanced semiconductor components to meet stricter energy performance standards.
Market Restraints
- Supply Chain Concentration:The heavy concentration of driver manufacturing and component sourcing within mainland China creates significant exposure to geopolitical tensions, logistical disruptions, and tariff risks for the global supply chain.
- Component Price Volatility:Fluctuations in the cost of essential semiconductor components, including MOSFETs and microcontroller units, directly compress manufacturer margins in a market characterized by intense price competition.
- EMI Compliance:Meeting stringent electromagnetic interference standards, such as FCC Part 15 in the United States, requires complex filtering and shielding, adding cost and design complexity, particularly for high-power drivers.
Strategic Opportunities
- Horticultural Lighting:The expansion of controlled environment agriculture creates a high-value opportunity for specialized drivers offering tunable spectrums and precise dimming control to optimize plant growth cycles.
- IoT Protocol Integration:Embedding connectivity for emerging IoT standards like Matter directly into the driver circuit opens opportunities for new data-driven services, remote diagnostics, and enhanced building automation capabilities.
- Manufacturing Diversification:Establishing or expanding production facilities in Southeast Asian countries, notably Vietnam, allows firms to mitigate geopolitical risks associated with China and serve growing regional electronics markets.
Industry Challenges
- Standardization Fragmentation:Navigating the complex and evolving landscape of competing communication protocols for smart lighting, including Zigbee, DALI, and Bluetooth Mesh, presents a significant interoperability challenge for product developers.
- Engineering Talent Scarcity:A shortage of power electronics engineers with dual expertise in analog circuit design and digital control firmware hinders the development of next-generation programmable and connected drivers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Driver Market |
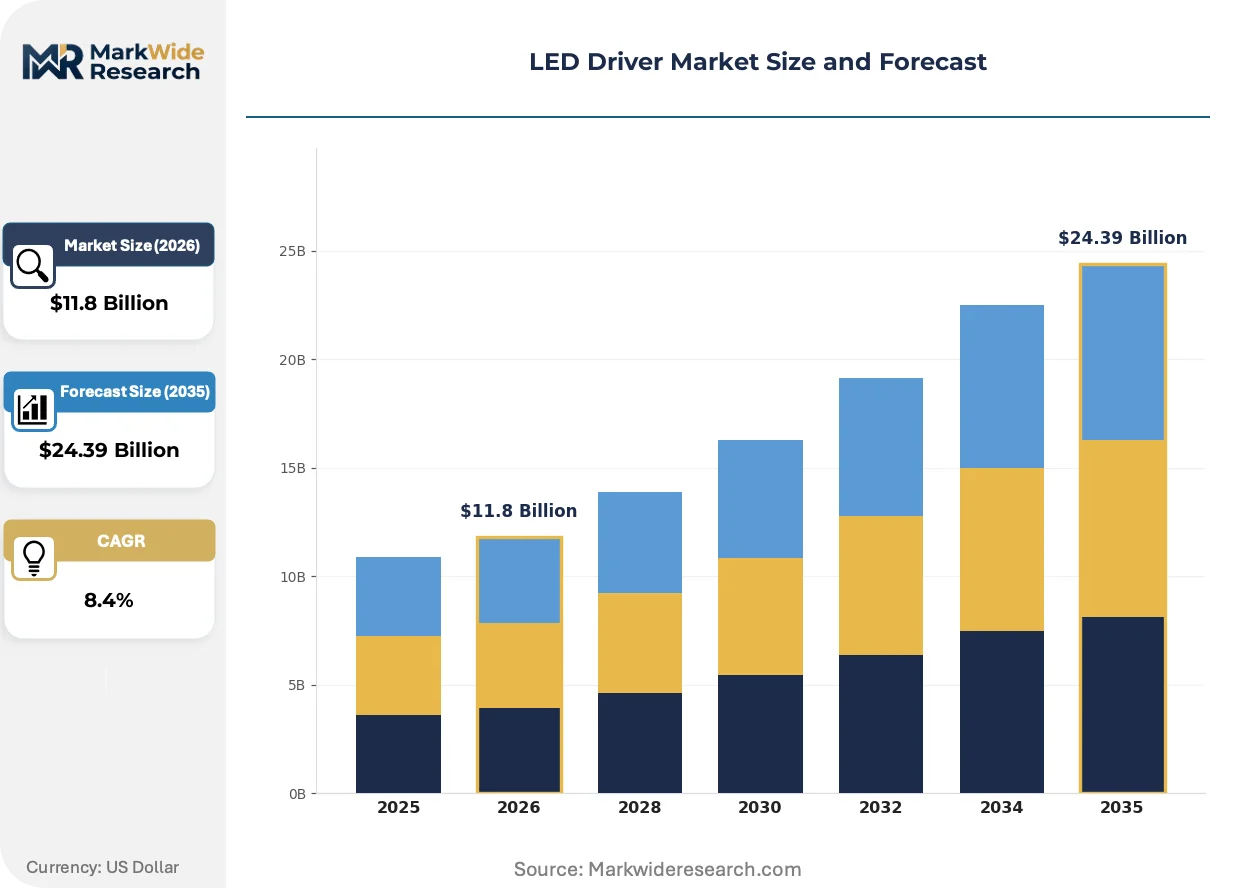
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Constant Current, Constant Voltage, Dimmable, Non-Dimmable, Programmable Technology: Analog, Digital, PWM, Hybrid, Resonant Application: Street Lighting, Display Lighting, Architectural Lighting, Automotive OEMs, Stage Lighting End User: Commercial Buildings, Industrial Plants, Transportation Hub, Sports Venues |
| Companies Covered | Signify, ams OSRAM, MEAN WELL Enterprises, Tridonic, Philips, Texas Instruments, Delta Electronics, Inventronics, ERP Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Driver Market Strategic Shifts & Innovations
The drive for miniaturization and deeper functional integration is reshaping product development. Intelligence, including dimming controls and connectivity protocols, is increasingly embedded within the driver itself, challenging traditional form factors and thermal management approaches.
Gallium Nitride (GaN) transistors are high-frequency semiconductors enabling smaller, more efficient power conversion. High-density applications like compact architectural lighting are adopting GaN to reduce physical footprint and heat dissipation requirements. The market for driver design is migrating from traditional silicon MOSFETs to GaN components to achieve superior power density.
Updated EU Ecodesign regulations now extend beyond energy use to include circular economy principles like reparability. This compels manufacturers to redesign drivers for easier disassembly and component recovery to maintain market access. The commercial and architectural lighting segments are most affected, requiring new compliance documentation for CE marking.
A notable demand-side shift sees building operators specifying complete, pre-validated lighting systems instead of procuring drivers as discrete parts. This trend disadvantages component distributors, favoring integrated system providers who guarantee interoperability. This is most visible in large-scale smart building projects in North America and Europe.
LED Driver Market Segmentation
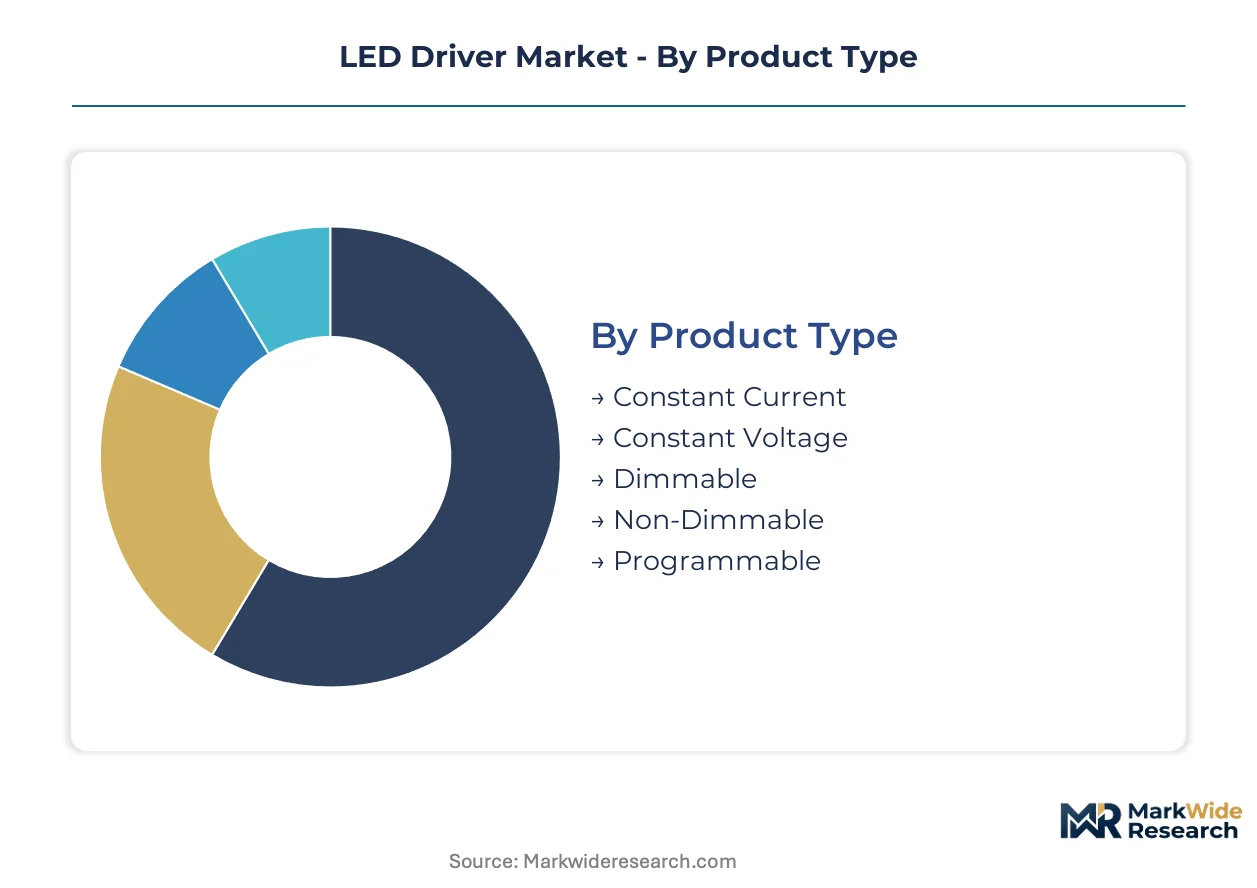
Understanding the LED driver market through segmentation reveals distinct demand patterns and technological requirements across various applications. This granular view helps identify where product innovation and manufacturing scale are most critical for market participants. Each segment reflects unique performance criteria and compliance standards for lighting systems.
Product Type:
The functional capabilities of LED drivers differentiate offerings, meeting diverse performance needs across lighting installations.
- Dimmable:These drivers incorporate circuitry allowing for adjustable light output, crucial for energy savings and ambiance control in residential and commercial settings. Demand concentrates in smart building projects in Europe, driven by EU Ecodesign framework mandates.
- Programmable:Offering customizable output parameters via software, programmable drivers enable precise control over current, voltage, and dimming curves. This is critical for architectural lighting in North America, where complex installations require fine-tuned light management.
- Constant Current:Constant current drivers provide a fixed output to LEDs, ensuring consistent brightness and extending diode lifespan in general illumination.
- Constant Voltage:Constant voltage drivers suit LED strips and modules needing stable voltage, simplifying installation in decorative and accent lighting.
- Non-Dimmable:Non-dimmable drivers offer fixed light output, serving as cost-effective solutions for utility lighting where intensity adjustment is unnecessary.
Constant Current commands the established base. The steepest expansion runs through Programmable drivers.
Technology:
Underlying circuit architectures define driver efficiency, compactness, and response characteristics for various demanding applications.
- Digital:These drivers utilize microcontrollers for precise control over output parameters, enabling advanced features like connectivity and diagnostics. Their adoption is significant in smart lighting systems for commercial buildings in Germany, integrating with management systems.
- Resonant:Employing resonant converter topologies, these drivers achieve high efficiency and reduced electromagnetic interference for compact and high-power applications. Horticultural lighting in the Netherlands benefits from their efficiency for optimizing plant growth cycles.
- Analog:Representing a foundational technology, analog drivers offer straightforward current regulation for basic LED lighting needs with lower cost.
- PWM:PWM technology enables dimming control by rapidly switching LED current, often used in display and architectural lighting applications.
- Hybrid:Hybrid drivers combine analog and digital control, balancing performance and cost for diverse mid-tier lighting requirements.
The majority of installations still rely on Analog technology. However, Digital solutions are gaining share fastest.
Application:
The specific operational environments and functional demands of end-use contexts dictate the required performance attributes of LED drivers.
- Street Lighting:Drivers for street lighting must offer high reliability, robust environmental protection, and often dimming capabilities for public safety. Municipal projects in the United Kingdom demand high-durability drivers to withstand harsh weather and reduce maintenance.
- Automotive OEMs:These applications require drivers certified for extreme temperatures, vibration resistance, and precise control for advanced lighting systems. Japanese automotive manufacturers integrate these drivers for critical safety and aesthetic vehicle components.
- Display Lighting:Display lighting drivers ensure uniform brightness and color consistency for digital signage, billboards, and retail installations.
- Architectural Lighting:Architectural lighting utilizes custom drivers offering precise control and programmable features for aesthetic and functional illumination of structures.
- Stage Lighting:Stage lighting requires high-power, dimmable, and DMX-compatible drivers for dynamic effects in entertainment venues.
While Street Lighting represents a foundational market segment, Automotive OEMs applications are expanding most quickly.
End User:
Different customer types drive demand based on their scale, operational requirements, and regulatory compliance needs for lighting infrastructure.
- Commercial Buildings:This segment includes offices, retail spaces, and hospitality venues, prioritizing energy efficiency, smart control, and aesthetic appeal. Smart building projects in North America increasingly specify drivers compatible with IoT protocols for energy management.
- Transportation Hub:Airports, train stations, and ports require highly reliable, long-life drivers for continuous operation, public safety, and clear signage. Infrastructure developments in Singapore emphasize robust drivers for critical public access areas.
- Industrial Plants:Industrial plants demand rugged, durable drivers capable of withstanding dust, vibration, and extreme temperatures in manufacturing environments.
- Sports Venues:Sports venues require high-power drivers with instant-on and precise dimming, crucial for broadcast quality and spectator experience in arena lighting.
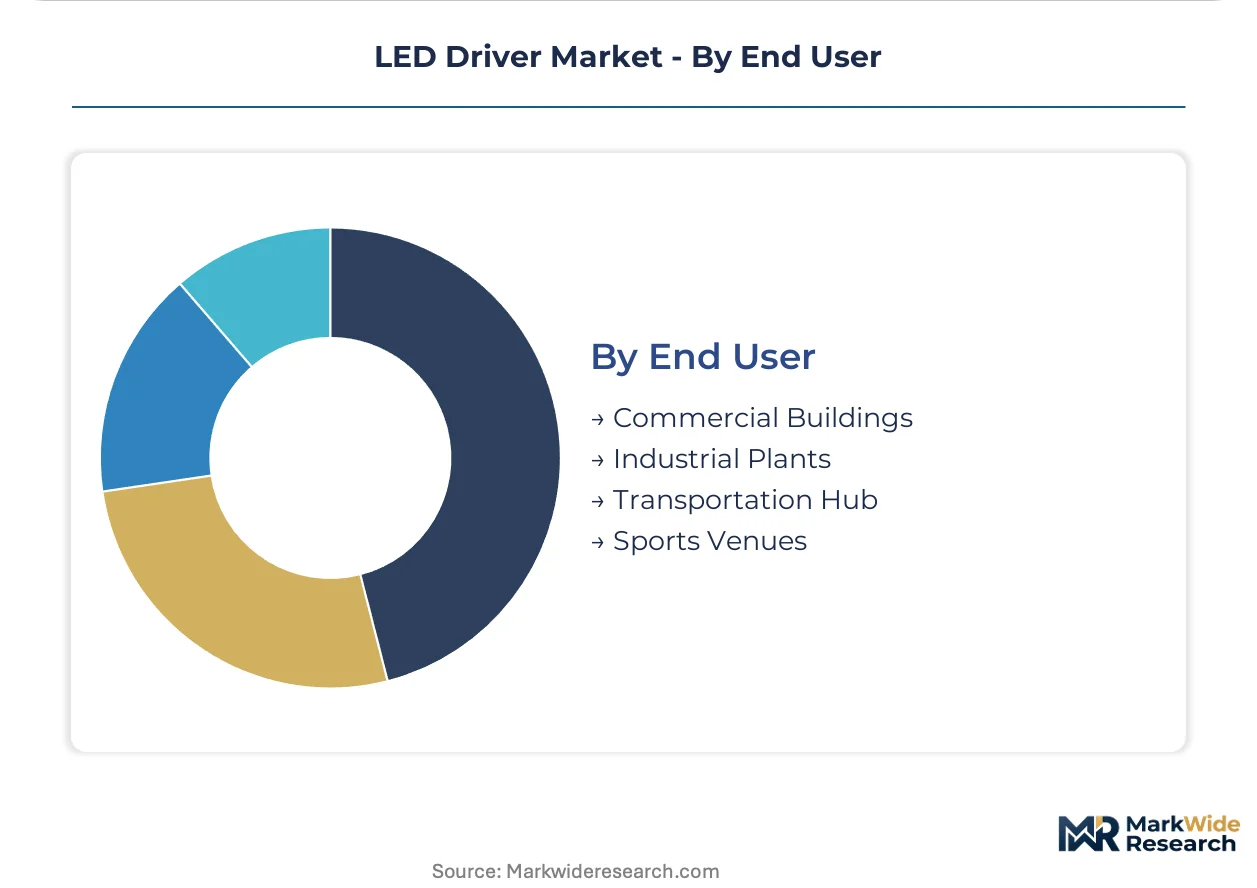
The largest installed base resides within Commercial Buildings. However, Transportation Hub is exhibiting the steepest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global LED driver market faces supply-side concentration, with manufacturing clusters in China historically dominating production capacity. This concentration influences global pricing and supply chain resilience. Diversification efforts, particularly into Southeast Asia, are now reshaping regional manufacturing footprints and distribution networks.
China
China remains the primary manufacturing hub for LED drivers, supplying components and finished products to markets worldwide. Domestic demand for LED drivers is strong, driven by extensive infrastructure projects and smart city initiatives. The country's GB standards dictate product quality and safety, influencing design and production processes for both local and international firms operating within China.
United States
Demand in the United States is spurred by smart building integration and automotive OEM applications requiring high-performance LED drivers. FCC Part 15 regulations govern electromagnetic interference, a critical design consideration for all electronic drivers sold in the country. Silicon Valley and other tech hubs drive innovation in digital control and connectivity for lighting systems.
Germany
Germany showcases significant adoption of digital LED drivers for commercial buildings and architectural lighting, integrating with advanced management systems. The EU's Ecodesign framework compels manufacturers to innovate for greater energy efficiency and circular economy principles, impacting product development. Munich and Berlin are centers for smart lighting technology development and deployment.
Japan
Japanese automotive manufacturers represent a key segment for high-reliability LED drivers, critical for advanced driver-assistance systems and adaptive headlamps. METI guidelines and JIS standards enforce stringent quality and performance criteria for electronic components. Major automotive and electronics manufacturing clusters in regions like Aichi and Kansai consistently drive demand for specialized drivers.
Vietnam
Vietnam is emerging as a strategic alternative for LED driver manufacturing, attracting investment as firms seek to mitigate geopolitical risks and diversify supply chains away from China. The country's growing electronics manufacturing sector supports the production of drivers for regional and international markets. Industrial parks around Hanoi and Ho Chi Minh City are expanding their capacity for electronics assembly.
LED Driver Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying the core semiconductor technology. The LED driver market exhibits a tiered structure, with firms specializing in either integrated lighting systems or fundamental driver components. Strategic archetypes include large lighting solution providers, dedicated power electronics manufacturers, and semiconductor component specialists. Competitive moves in this market involve deepening functional integration and diversifying manufacturing footprints.
Integrated lighting system providers like Signify exemplify the shift towards complete solutions, offering comprehensive control and interoperability. Conversely, firms such as Texas Instruments anchor the semiconductor component tier, specializing in driver integrated circuits. MEAN WELL Enterprises represents a segment focused on standard power supply modules for industrial and commercial distribution channels, leveraging extensive product catalogs.
| Leading Market Players |
|---|
| Signify |
| ams OSRAM |
| MEAN WELL Enterprises |
| Tridonic |
| Philips |
| Texas Instruments |
| Delta Electronics |
| Inventronics |
| ERP Power |
| Others |
Cost & Logistics Intelligence
Expanding manufacturing capacity in Vietnam is influencing supplier behavior and pricing posture, creating new dynamics in the global LED driver market. This shift challenges traditional pricing models and supply chain dependencies.
Pricing Analysis
The EU's Ecodesign framework dictates the pricing tier structure for LED drivers, emphasizing efficiency and circular economy principles. Per-unit transactional pricing dominates, with differentiation driven by CE and FCC Part 15 certification, programmable features, and brand reputation. Pricing pressure stems from intense market competition and semiconductor component price volatility. Commercial buildings exhibit high price sensitivity for general illumination, while automotive OEMs prioritize reliability and specialized performance.
Supply Chain Analysis
Trade policy restrictions, including potential tariff regimes, limit the free flow of critical LED driver components and finished products. Geographic supply concentration centers heavily in China, with Vietnam emerging as a diversification hub for production. The market relies on key inputs like MOSFETs, microcontroller units, and GaN transistors. Geopolitical tensions and logistical disruptions pose significant supply chain risks, impacting distribution channels across component distributors and integrated lighting system providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LED driver market presents a fragmentation opportunity, as the demand-side shift towards horticultural lighting creates high-value niches for specialized tunable spectrum drivers.
For Market Incumbents:Pre-empt component price volatility by securing long-term supply agreements for critical semiconductors like GaN transistors. Deepen functional integration of IoT protocols directly into driver circuits, challenging new entrants focused solely on hardware. Diversify manufacturing footprints into Southeast Asia, notably Vietnam, to mitigate geopolitical risks and tariff exposure. Invest in R&D for advanced thermal management solutions to support miniaturization trends.
For New Entrants and Emerging Players:Horticultural lighting in Northern European controlled environment agriculture represents the most penetrable entry point for specialized LED drivers. Target this niche with tunable spectrum and precise dimming control capabilities. Offer value-based pricing models linked to optimized plant growth cycles rather than per-unit cost. Focus on seamless integration with existing environmental control systems for rapid adoption.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upward across advanced digital and GaN-based LED driver manufacturing due to R&D and specialized equipment needs. Over the next 5-10 years, the market demonstrates sustained viability, driven by efficiency mandates. Target vertically integrated specialists in digital control firmware or GaN power electronics for strategic acquisition. The signal to watch is the adoption rate of GaN transistors in compact architectural lighting projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Diversify Manufacturing Footprint | Mitigates geopolitical risks associated with China's production concentration and serves growing regional electronics markets. |
| IoT Protocol Integration | Embeds connectivity for emerging standards like Matter, enabling new data-driven services and enhanced building automation. |
| GaN Transistor Adoption | Enables smaller, more efficient power conversion for high-density applications like compact architectural lighting. |
| Circular Economy Redesign | Ensures compliance with updated EU Ecodesign regulations, requiring easier disassembly and component recovery for market access. |
| Integrated System Offerings | Captures demand from building operators specifying complete, pre-validated lighting systems over discrete components. |
Research Approach
Cross-validation between primary interviews and secondary research anchors the qualitative findings for this LED driver market analysis. Industry stakeholders, including power electronics engineers, lighting designers, and automotive OEM procurement specialists, provided critical insights. Secondary data sources encompassed industry association reports, regulatory filings like FCC Part 15, and trade publications. This approach ensured robust bottom-up and top-down triangulation of market intelligence.
The forecast calibration approach integrates historical data across the analysis window with forward-looking market dynamics. Segmentation dimensions modeled include product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends, identified market drivers, and expert projections. Energy efficiency mandates and semiconductor component availability served as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in global trade policies or raw material costs would shift the trajectory of the LED driver market. Forecasts reflect documented assumptions, acknowledging specific risk factors like geopolitical tensions and supply chain disruptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Mini LED Display Market
LED
Pixel Pitch LED Market
LED
LED Display Market
LED
LED Digital Scoreboard Market
LED
High-Brightness LED Market
LED
China Indoor LED Lighting Market
LED
France Indoor LED Lighting Market
LED
LED Tube Drivers Market
LED
Global Industrial and Commercial LED Lighting Market
LED
Africa LED Lighting Market
LED
7 Segment LED Displays Market
LED
OLED Blue Emitter Market
LED
Africa LED and OLED Displays and Lighting Products Market
LED
Mexico LED Lighting Market
LED
US Outdoor LED Lighting Market
LED
UK Outdoor LED Lighting Market