
 LED Street Light Drivers Market | 2026-2036
LED Street Light Drivers Market Size, Share, and Industry Trends Forecast 2026-2036
LED Street Light Drivers Market Analytics
Direct procurement channels between driver manufacturers and municipal utilities is rewriting traditional distribution economics for LED street light drivers. Signify leverages its luminaire-to-driver integration to capture bundled infrastructure contracts across European cities. Mean Well Enterprises anchors its position through high-volume production of IP-rated outdoor drivers with standardized form factors. Inventronics competes aggressively in Asian markets with programmable current-output platforms designed for extreme thermal environments.
LED street light drivers are power-electronics modules that convert AC grid input to regulated DC output, typically operating between 50W and 400W with surge protection ratings up to 10kV and thermal management thresholds exceeding 85°C ambient. Constant current drivers dominate installed volumes due to their compatibility with high-power COB and SMD LED arrays, while dimmable variants represent the fastest-expanding margin pool as cities adopt DALI-2 and Zhaga-D4i interoperable controls. Multi-output technology leads innovation cycles by enabling single-driver architectures to service multi-lane roadway configurations without redundant hardware.
Regulators including the EPA, ECHA through REACH substance restrictions, and China's MEE under dual carbon mandates are elevating efficiency minimums and restricting hazardous substances in driver electronics. India's BIS certification requirements and the EU's Ecodesign Directive together compress market access for non-compliant suppliers. Stakeholders must monitor evolving interoperability standards and carbon-border adjustment mechanisms that will determine which driver architectures qualify for public infrastructure tenders.
Market Dynamics
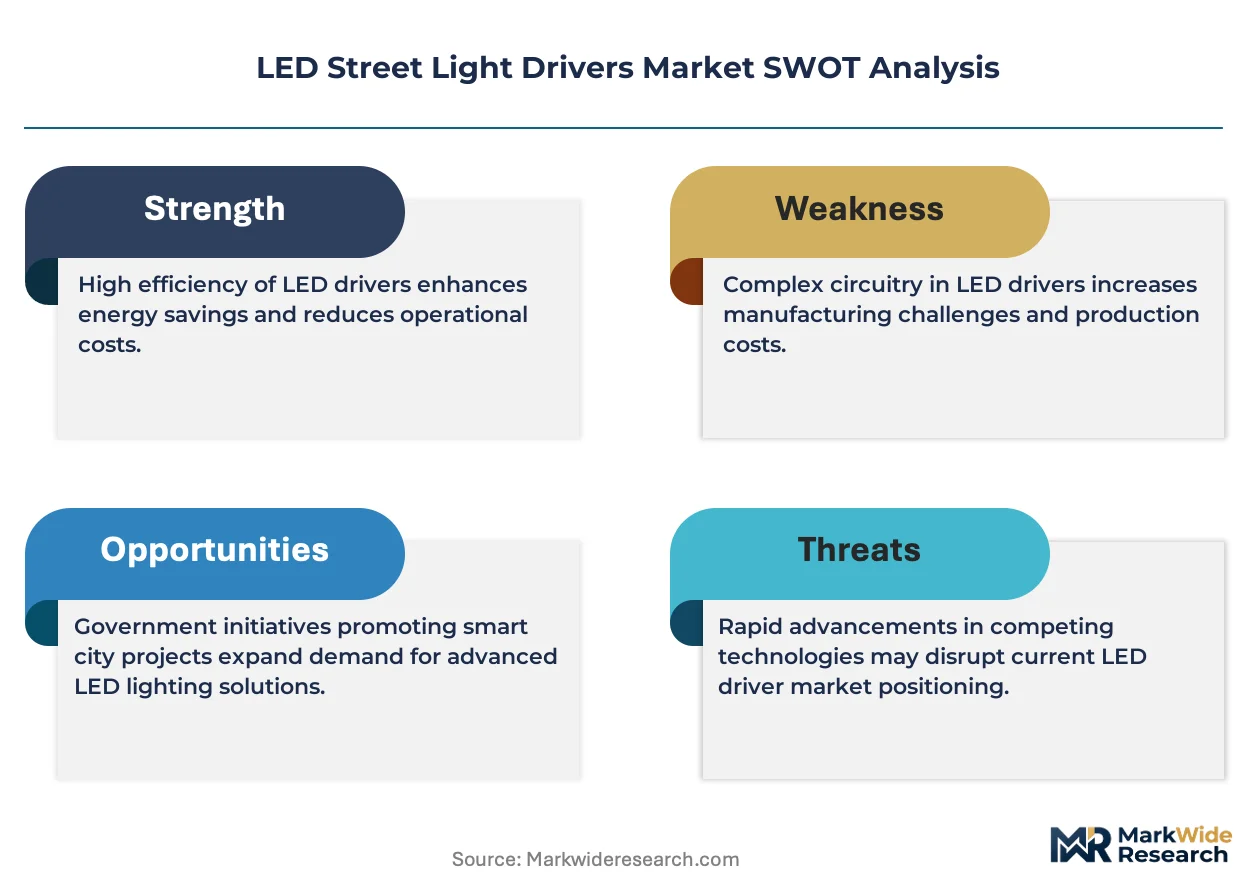
Smart city infrastructure mandates are compressing procurement cycles for intelligent driver systems, forcing power-electronics suppliers to integrate DALI-2 and Zhaga-D4i protocols at the design stage rather than as aftermarket add-ons.
Growth Catalysts
- India's Street Light National Programme:Central government tenders mandate programmable dimming interfaces, creating standardized demand pools for compliant driver architectures.
- COB LED thermal density:High-power chip-on-board arrays require precision current regulation, pulling constant-current driver volumes upward across municipal retrofit projects.
- East Asian manufacturing clusters:Concentrated production in Guangdong and Zhejiang provinces achieves cost structures that undercut fragmented European assembly operations.
Market Restraints
- Aluminum core PCB cost volatility:Raw material fluctuations in thermal substrate pricing compress margin stability for mid-tier driver assemblers.
- Single-source dependency on Taiwan semiconductor foundries:Power MOSFET and driver IC concentration creates supply vulnerability during geopolitical friction.
- EU Ecodesign Directive compliance overhead:Extended certification timelines and testing costs deter smaller manufacturers from accessing European public tenders.
Strategic Opportunities
- Brazil's municipal electrification gaps:Underpenetrated secondary cities present first-mover positioning for IP66-rated outdoor driver platforms with integrated surge protection.
- Photovoltaic-streetlight hybrid systems:Convergence of solar charge controllers with LED drivers enables single-enclosure designs for off-grid roadway installations.
- China's dual carbon mandates:Provincial efficiency subsidies for >95% conversion-rate power electronics accelerate premium product substitution against legacy magnetic ballast inventories.
Industry Challenges
- Embedded firmware engineering scarcity:Shortage of power-electronics software developers capable of implementing DALI-2 protocol stacks delays product release schedules.
- Multi-certification parallelism:Simultaneous pursuit of BIS, CE, and UL listings fragments engineering bandwidth and extends time-to-revenue for new platform launches.
- Legacy HPS fixture electrical incompatibility:Retrofit installations require custom wiring harness adaptations that complicate field deployment and elevate service call rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Street Light Drivers Market |
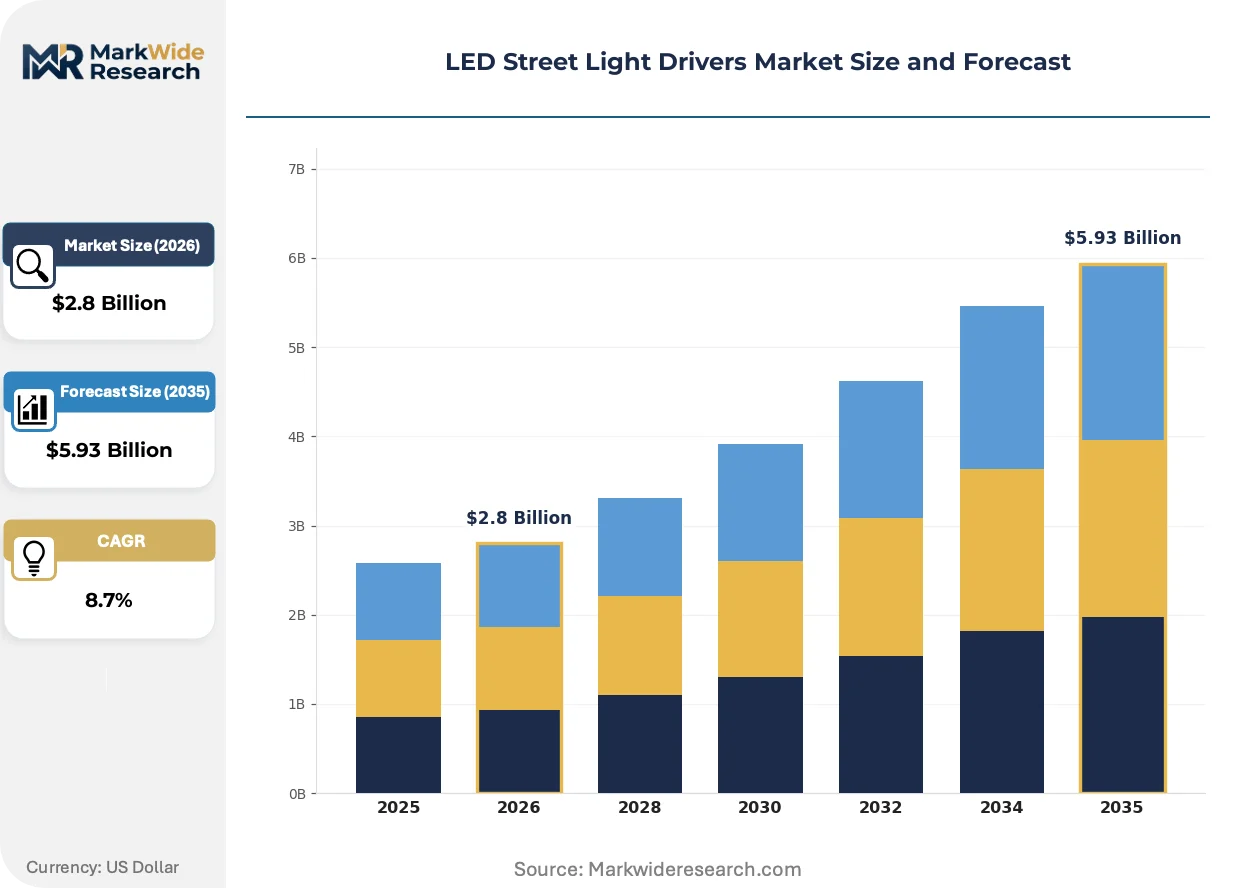
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Constant Current, Constant Voltage, Hybrid, Dimmable Technology: Linear, Buck, Boost, Multi-Output End User: Municipalities, Infrastructure, Commercial, Industrial Installation Type: Retrofit, New Installation, Integrated Systems, Wireless Solutions |
| Companies Covered | Signify, ams OSRAM, Mean Well Enterprises, Tridonic, Inventronics, Lifud Technology, Eaglerise, Texas Instruments, ON Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Street Light Drivers Market Evolving Landscape
Digital power management architectures are displacing analog control loops, enabling real-time telemetry and predictive thermal derating that analog designs cannot replicate.
Multi-output driver ICs with independent channel control are virtualizing the traditional one-driver-per-luminaire topology. Municipal utilities in Germany and the Netherlands are specifying these platforms for multi-lane arterial roads. This consolidation is virtualizing redundant hardware layers and compressing installed cost per kilometer of illuminated roadway.
REACH substance restrictions on halogenated flame retardants are forcing substrate material transitions. Driver manufacturers are migrating from conventional FR-4 to ceramic-filled thermally conductive laminates. Asian suppliers with in-house lamination capabilities are capturing specification advantages in European tender documents.
Direct factory-to-utility contracting is bypassing traditional electrical distributor networks. Large-scale infrastructure aggregators in India and Brazil are negotiating multi-year supply agreements with driver manufacturers for bundled smart-city deployments. This channel compression is most visible in states with centralized procurement authorities such as Maharashtra and São Paulo.
LED Street Light Drivers Market Segmentation
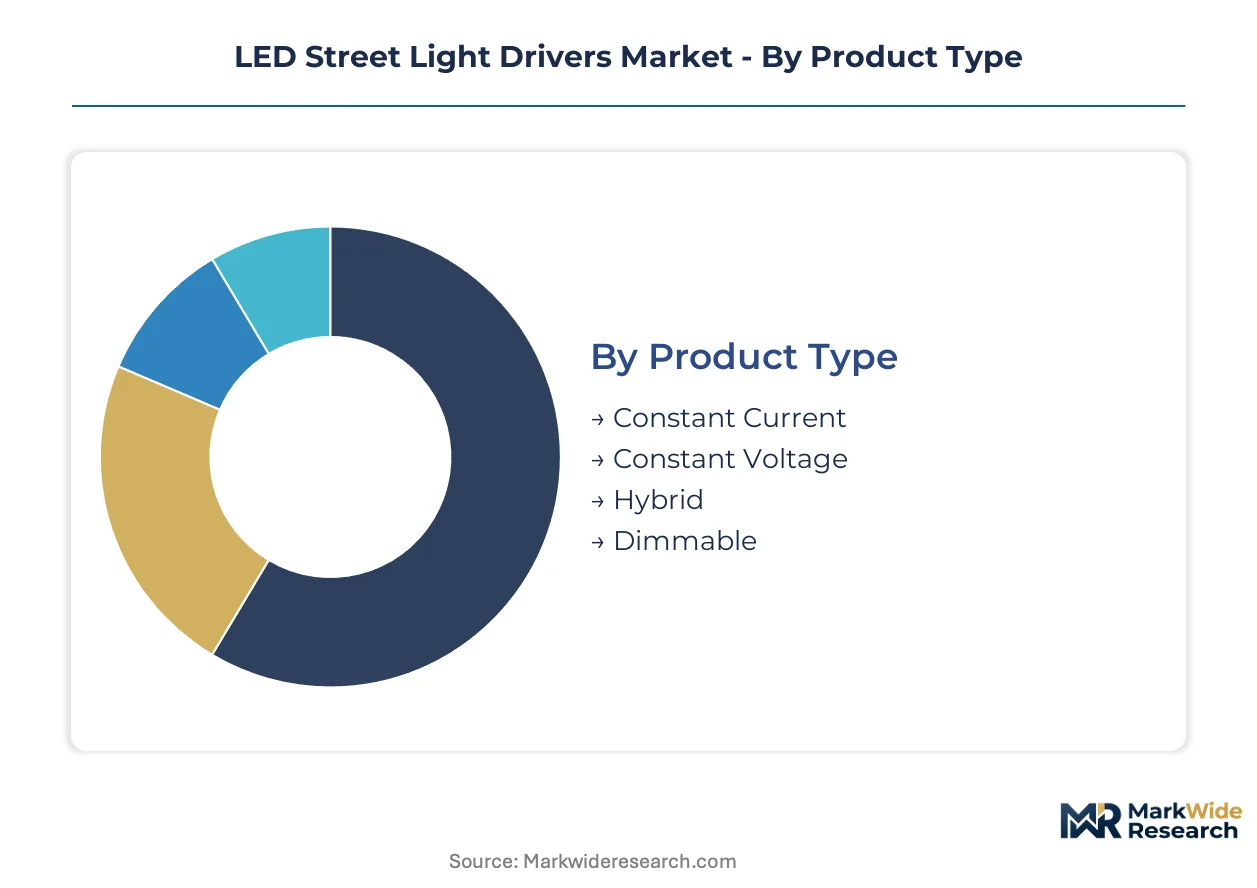
Segmentation in LED street light drivers determines procurement specifications, thermal engineering requirements, and interoperability mandates across divergent infrastructure lifecycles. Municipal buyers, commercial developers, and industrial operators each impose distinct current-regulation tolerances, surge-protection ratings, and dimming protocol requirements that fragment supplier strategies.
Product Type:
Replacement cycles vary dramatically across driver architectures, with dimmable platforms refreshing every 5-7 years against 10-12 year baselines for basic constant-current units.
- Constant Current:These drivers deliver fixed current output regardless of voltage fluctuations, matching the electrical characteristics of high-power COB and SMD LED arrays. Municipal street lighting programs across India and China specify constant-current architectures for their retrofit volumes, driven by compatibility with legacy luminaire designs and lower upfront procurement costs.
- Dimmable:Programmable output drivers integrate DALI-2 and Zhaga-D4i control interfaces, enabling remote dimming schedules and energy optimization. Smart city deployments in Germany and the Netherlands concentrate demand here, pulled by mandates for networked lighting management and real-time telemetry integration.
- Constant Voltage:Fixed-voltage output modules serve low-power decorative and auxiliary lighting applications where current precision is less critical.
- Hybrid:Dual-mode drivers switch between constant-current and constant-voltage operation, accommodating mixed LED configurations in complex roadway installations.
Constant current anchors the volume base while dimmable gains share at the steepest rate.
Technology:
Cost tiers separate these architectures, with linear designs occupying economy positioning and multi-output platforms commanding premium pricing for consolidated infrastructure.
- Linear:Simple pass-element regulation without switching components yields lowest BOM cost and minimal EMI generation. Basic municipal installations across Brazil's secondary cities specify linear drivers for budget-constrained electrification programs.
- Multi-Output:Single-driver ICs with independent channel control service multi-lane roadway configurations from one enclosure. German and Dutch arterial road specifications pull adoption, enabled by virtualization of redundant hardware and compression of installed cost per kilometer.
- Buck:Step-down switching converters achieve higher efficiency than linear alternatives in high-voltage grid environments.
- Boost:Step-up architectures accommodate low-voltage DC inputs from photovoltaic-streetlight hybrid systems in off-grid installations.
Linear technology dominates shipment volumes while multi-output climbs the fastest.
End User:
Customer type dictates certification burden and contract structure, with municipalities imposing extended warranty terms and commercial buyers prioritizing rapid installation turnaround.
- Municipalities:Central and state government procurement authorities issue multi-year tenders with standardized dimming interface requirements. India's Street Light National Programme and Brazil's municipal electrification gaps concentrate demand here, subject to BIS and INMETRO certification compliance.
- Infrastructure:Highway authorities and port operators specify IP66-rated outdoor drivers with integrated surge protection exceeding 10kV ratings.
- Commercial:Retail and parking facility operators prioritize rapid-payback retrofit economics over extended feature sets.
- Industrial:Heavy manufacturing and logistics campuses demand extreme thermal derating capabilities for ambient conditions exceeding 85°C.
Municipalities anchor the volume base while infrastructure gains share fastest.
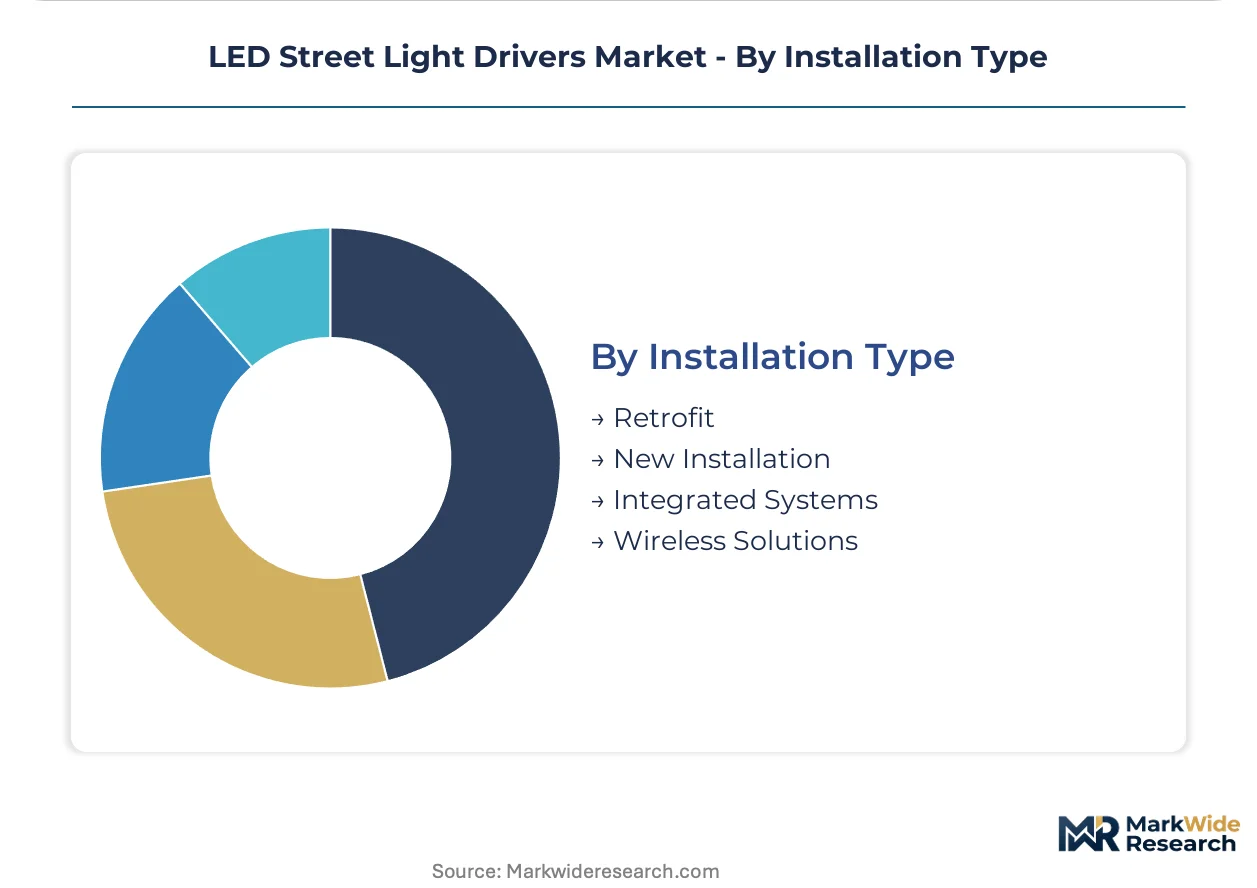
Installation Type:
Maturity gradients separate these segments, with new installations representing established specification practices and wireless solutions driving architectural disruption.
- Retrofit:Field adaptation of existing HPS fixture wiring harnesses requires custom electrical interfaces and elevates service call complexity. India's legacy street light replacement programs and China's magnetic ballast phase-out generate concentrated demand subject to legacy electrical incompatibility constraints.
- Wireless Solutions:Cellular and mesh-networked drivers eliminate control wiring infrastructure entirely. Smart city aggregators in São Paulo and Maharashtra specify these platforms for greenfield deployments, enabled by compression of installation labor and material costs.
- New Installation:Greenfield luminaire-and-driver bundled contracts follow standardized electrical specifications with minimal field customization.
- Integrated Systems:Pre-assembled driver-luminaire-control combinations reduce procurement fragmentation for large-scale infrastructure projects.
Retrofit anchors the volume base while wireless solutions expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta's dense manufacturing corridor underwrites China's dominance in LED driver production, while India's Street Light National Programme and Brazil's municipal electrification gaps concentrate procurement volumes across three continents.
China
Guangdong and Zhejiang provinces host concentrated driver assembly operations serving both domestic smart city deployments and export markets. GB standards for outdoor LED efficacy and the Ministry of Ecology and Environment's dual carbon mandates elevate efficiency thresholds above 95% conversion rates. Shenzhen and Hangzhou manufacturing clusters specialize in programmable current-output platforms engineered for extreme thermal environments.
India
Maharashtra and Gujarat states anchor procurement through centralized state electricity distribution company tenders under the Street Light National Programme. Bureau of Indian Standards certification requirements compress market access for non-compliant suppliers. Tamil Nadu's electronics manufacturing zones attract driver assemblers seeking proximity to southern municipal retrofit programs.
Germany
Ruhr metropolitan utilities and Bavarian highway authorities specify DALI-2 and Zhaga-D4i interoperable controls for multi-lane arterial road configurations. The EU Ecodesign Directive imposes extended certification timelines that deter smaller manufacturers from accessing public tenders. North Rhine-Westphalia's industrial corridor concentrates specification engineering for networked lighting management systems.
Brazil
São Paulo state's centralized procurement authority negotiates multi-year supply agreements for bundled smart-city deployments across underpenetrated secondary cities. INMETRO certification requirements structure competitive access for IP66-rated outdoor driver platforms. Minas Gerais and Rio Grande do Sul municipalities present first-mover positioning for integrated surge protection specifications.
United States
California and Texas municipal utilities drive demand through zero-emission street lighting mandates tied to federal infrastructure funding allocations. EPA efficiency guidelines and state-level carbon reduction targets compress procurement cycles for intelligent driver systems. Pacific Northwest utilities specify photovoltaic-streetlight hybrid systems for off-grid roadway installations in rural jurisdictions.
LED Street Light Drivers Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated luminaire-to-driver platforms, high-volume standardized component suppliers, and programmable specialists serving extreme environment specifications. European and East Asian players dominate premium positioning through protocol integration capabilities, while Chinese manufacturers anchor economy positioning via concentrated production in Guangdong and Zhejiang provinces. Dominant competitive moves include direct factory-to-utility contracting that bypasses traditional electrical distributor networks, and backward integration into thermal substrate lamination to capture specification advantages in REACH-compliant European tenders.
Among integrated platform providers, Signify exemplifies the luminaire-to-driver bundling archetype through its capture of municipal infrastructure contracts. Mean Well Enterprises anchors the high-volume standardized tier with IP-rated outdoor driver production. Inventronics occupies a position within the programmable specialist segment, competing aggressively in Asian markets with current-output platforms. These three companies represent the dominant competitive vectors reshaping procurement economics across municipal, commercial, and industrial end-use segments.
| Leading Market Players |
|---|
| Signify |
| ams OSRAM |
| Mean Well Enterprises |
| Tridonic |
| Inventronics |
| Lifud Technology |
| Eaglerise |
| Texas Instruments |
| ON Semiconductor |
| Others |
Value Network & Pricing Analysis
Overcapacity in Guangdong province's driver assembly corridor is forcing mid-tier suppliers into aggressive price positioning while premium manufacturers defend margin through certification-locked procurement channels. This utilization imbalance creates divergent pricing postures across the constant-current and dimmable product tiers.
Pricing Analysis
Volume-discount tiering structures separate municipal tender winners from fragmented distributor channels. Three-tier pricing stratification across premium, standard, and economy levels reflects differential certification burdens, with BIS and CE marking tiers commanding substantial premia over uncertified alternatives. Cost compression in economy-grade linear drivers is intensifying because East Asian manufacturing clusters achieve scale economies that European assemblers cannot match. Municipal procurement authorities exhibit lowest price sensitivity due to multi-year warranty requirements and protocol interoperability mandates, while commercial parking operators prioritize rapid-payback retrofit economics.
Supply Chain Analysis
Export-control regimes restricting power MOSFET and driver IC flows from Taiwan semiconductor foundries are elevating inventory carrying costs for non-integrated assemblers. Manufacturing gravity centers on China, Taiwan, and South Korea, with Guangdong and Zhejiang provinces hosting concentrated final assembly. The supply chain draws from aluminum core PCB substrates, ceramic-filled thermal laminates, and magnetics components. Single-source vulnerability in Taiwan foundry capacity creates procurement risk during geopolitical friction. Distribution runs through direct factory-to-utility contracting that bypasses traditional electrical distributor networks in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LED street light driver market is recovering from a cyclical trough driven by China's dual carbon mandates accelerating magnetic ballast phase-out programs. Municipal electrification gaps across secondary cities provide demand visibility through the projection horizon.
For Market Incumbents: Pre-empt margin erosion in constant-current segments by accelerating backward integration into ceramic-filled thermal laminate production, capturing REACH-compliant specification advantages in European tenders. Consolidate channel control through multi-year direct contracting with Maharashtra and São Paulo state procurement authorities before emerging Asian challengers achieve BIS certification parity.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's underpenetrated secondary cities by offering IP66-rated outdoor driver platforms with integrated surge protection and INMETRO pre-certification. Target photovoltaic-streetlight hybrid system integrators in the Pacific Northwest with boost-converter architectures designed for off-grid DC inputs, leveraging absence of entrenched incumbents in this convergence segment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across programmable dimmable driver sub-segments as digital power management architectures displace analog control loops and reduce BOM complexity. Acquisition targets should display in-house firmware engineering capabilities for DALI-2 protocol implementation, defensible against talent scarcity. Watch for inflection when embedded software developer wage inflation exceeds hardware margin compression rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Substrates | Captures REACH-compliant specification advantages in German and Dutch arterial road tenders. |
| DALI-2 Protocol Stack Development | Enables specification compliance for networked lighting management systems in Ruhr metropolitan utilities. |
| Direct Factory-to-Utility Contracting | Bypasses electrical distributor networks in Maharashtra and São Paulo state procurement authorities. |
| Photovoltaic-Driver Hybrid Platform Launch | Addresses off-grid roadway installations in California and Texas zero-emission mandate jurisdictions. |
| Multi-Output Driver IC Architecture | Virtualizes redundant hardware for multi-lane German and Dutch arterial road configurations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal procurement officers, power-electronics R&D directors, thermal substrate suppliers, and smart city infrastructure aggregators. Secondary validation drew from Bureau of Indian Standards certification databases, EU Ecodesign Directive implementation reports, Chinese GB standards documentation, and customs trade flow records. Bottom-up driver shipment estimates triangulated against top-down municipal tender value aggregation across the analysis window.
Calibration against historical constant-current and dimmable driver volume splits informed projection elasticity assumptions throughout the forecast period. Segmentation dimensions modeled include product architecture, switching technology topology, end-user procurement authority type, and installation methodology. CAGRs were derived from slope-constrained growth curve fitting anchored to announced municipal program targets and magnetic ballast phase-out schedules. Industry-specific inputs incorporated aluminum core PCB price indices and Taiwan foundry utilization rates.
Macroeconomic conditions sit as an overlay; deviation in Chinese provincial subsidy disbursement timing and Brazilian real exchange rate volatility would shift the trajectory. Forecasts reflect documented assumptions regarding DALI-2 protocol adoption curves and REACH substance restriction implementation pacing. Material shifts in Taiwan semiconductor export licensing regimes or India's BIS certification timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
China LED Lighting Market
LED
Mini LED Market
LED
High Power LED Market
LED
France Indoor LED Lighting Market
LED
LED Modular Display Market
LED
LED Mask Market
LED
LED Downlight Market
LED
US LED Downlight Market
LED
LED Power Supplies Market
LED
LED and OLED Display Market
LED
Superluminescent Diodes Market
LED
Africa LED Lighting Market
LED
Middle East LED Lights Market
LED
LED Light Bar Market
LED
Brazil LED Market
LED
Arrow LED Displays Market