
 Asia Pacific LED Lighting Market | 2026-2036
Asia Pacific LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific LED Lighting Market Insights
Japan's Top Runner program is consolidating efficiency benchmarks across the Asia Pacific LED Lighting Market. Seoul Semiconductor anchors its position through proprietary chip architectures that sustain premium positioning in automotive forward-lighting applications. Nichia Corporation dominates high-brightness discrete LED supply for precision industrial equipment, while Signify extends its installed base across Southeast Asian commercial retrofit channels through direct city municipality contracts.
Asia Pacific LED lighting encompasses solid-state semiconductor devices that emit visible light when electrical current traverses a p-n junction, typically operating at 2-4 volts DC with luminous efficacy exceeding 150 lumens per watt in premium architectures. The technology replaces legacy fluorescent and incandescent systems across commercial, residential, and outdoor infrastructure where operational longevity and spectral controllability reduce maintenance cycles. Smart Lighting technology leads technology segment value capture as building management system integration commands software-recurring revenue streams alongside hardware sales. Tubes retain volume leadership in commercial retrofit waves across aging office stock, while Downlights concentrate margin pools in premium residential developments across Singapore and Australian metropolitan corridors.
China's MIIT enforces GB standards for luminous efficacy and electromagnetic compatibility that gate domestic market access for imported LED modules. India's BIS certification mandates and Japan's METI energy conservation labeling collectively shape product specification requirements across the regional supply chain. Australia's MEPS program and South Korea's MFDS-equivalent energy efficiency frameworks add compliance layers for cross-border component flows. Stakeholders must monitor divergence between national efficiency tiers and smart grid interoperability protocols as fragmented standards threaten scale economics for unified product platforms.
Market Dynamics
China's dual carbon goals are compressing replacement cycles across commercial real estate portfolios, forcing semiconductor-grade illumination components into retrofit specifications ahead of natural depreciation schedules. Procurement officers now face accelerated compliance deadlines that reshape capital allocation timelines across the region.
Growth Catalysts
- India's Smart City Mission:Municipal infrastructure tenders mandate networked street lighting with remote diagnostics, creating bundled hardware-software procurement packages that lift contract values.
- Japan's Top Runner Program:METI efficiency benchmarks cascade across appliance categories, compelling manufacturers to redesign driver electronics and thermal management systems ahead of international competitors.
- Vietnam's Industrial Zone Expansion:Factory construction in Binh Duong and Hai Phong corridors specifies high-bay LED arrays with 50,000-hour lifespans to minimize maintenance access in automated facilities.
Market Restraints
- Epitaxial Wafer Supply Concentration:Sapphire substrate fabrication clusters in Fujian and Guangdong provinces, exposing downstream packagers to single-source disruption risks during power rationing events.
- Phosphor Material Cost Volatility:Rare-earth element pricing for yttrium-aluminum-garnet formulations fluctuates with Chinese export quota adjustments, compressing margin predictability for mid-tier luminaire assemblers.
- Incumbent Fluorescent Infrastructure:Ballast-compatible LED tubes face technical limitations in legacy magnetic-ballast installations, slowing penetration in aging Australian and Japanese commercial stock.
Strategic Opportunities
- Li-Fi Convergence:Visible light communication integration with building management systems creates new revenue streams in Singapore's financial district data centers where electromagnetic interference restricts radio-frequency alternatives.
- Indonesia's Regulatory Lag:Absence of mandatory efficacy labeling in Jakarta's commercial permitting process allows early movers to establish specification lock-in before BIS-equivalent standards emerge.
- Human-Centric Lighting:Circadian-tunable systems penetrate premium healthcare and education verticals in South Korea's MFDS-regulated facilities, commanding hardware-plus-service contract structures.
Industry Challenges
- Optical Design Talent Scarcity:Compound semiconductor physicists capable of ray-tracing simulation for automotive forward-lighting applications command premium compensation in Seoul and Nagoya labor markets.
- Multi-Jurisdiction Certification Burden:Cross-border component flows require simultaneous BIS, GB, and JIS testing protocols, extending product launch timelines by 8-14 months for unified platform strategies.
- Legacy BMS Integration Complexity:BACnet and DALI protocol mismatches in Southeast Asian hotel retrofits force custom gateway development, inflating project engineering costs beyond initial equipment quotations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific LED Lighting Market |
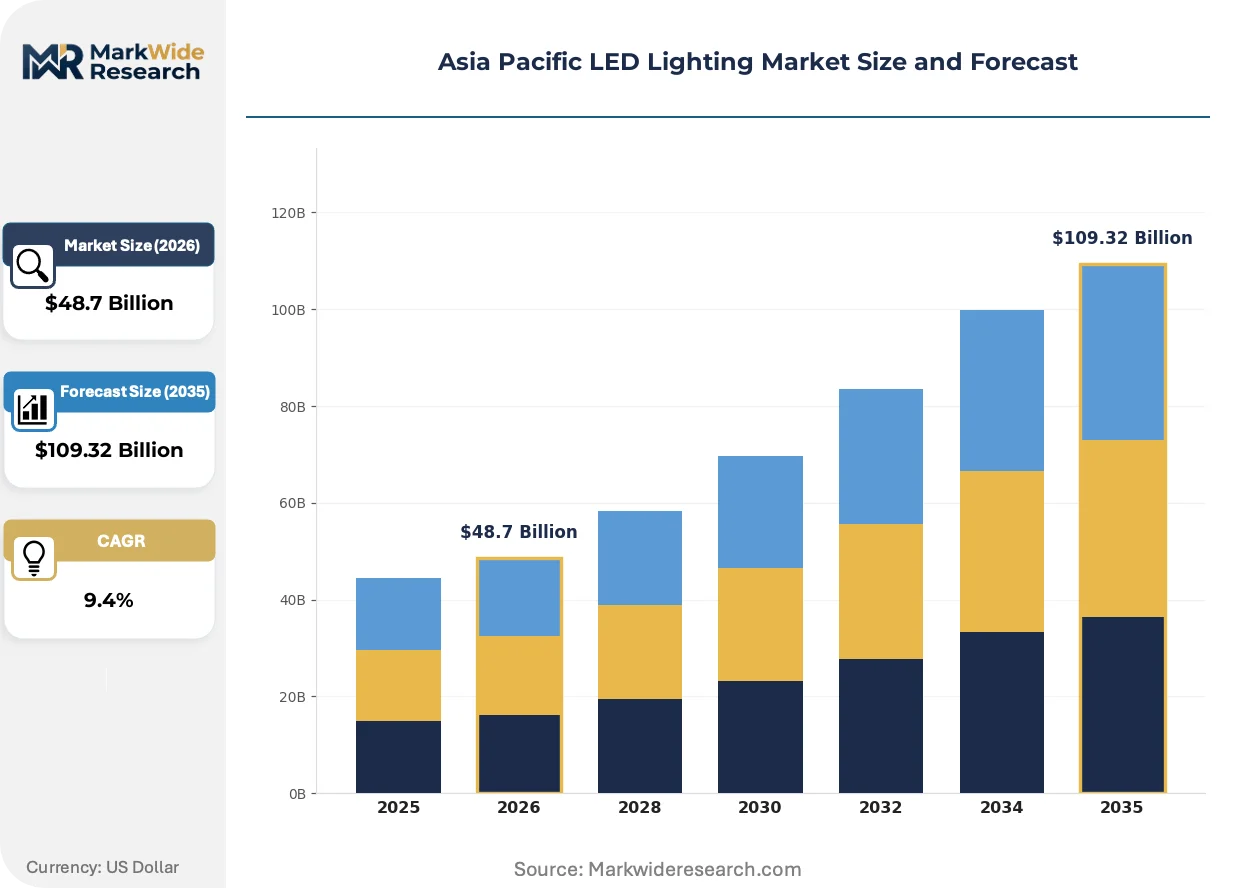
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $109.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Tubes, Fixtures, Downlights Technology: Smart Lighting, Solar LED, OLED, Traditional LED Application: Residential Lighting, Commercial Lighting, Architectural Lighting, Outdoor Lighting End User: Households, Retail Outlets, Offices, Industrial Facilities |
| Companies Covered | Nichia Corporation, Signify, Seoul Semiconductor, Panasonic Holdings Corporation, Koito Manufacturing, Opple Lighting, Samsung Electronics, Osram, Stanley Electric, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific LED Lighting Market Trends and Innovations
Spectral engineering and networked control architectures are redefining value capture models across the Asia Pacific LED Lighting Market. Hardware commoditization pressures are pushing suppliers toward software-recurring revenue structures and outcome-based service arrangements.
Human-centric lighting systems are automating circadian rhythm management in healthcare and education facilities. Seoul's university hospitals and Singapore's eldercare centers deploy tunable-white luminaires with melanopic lux scheduling. The technology is automating facility management labor previously dedicated to manual dimming protocols, compressing operational staffing models while raising equipment specification thresholds.
China's MIIT enforcement of updated GB standards for electromagnetic compatibility is disqualifying legacy import designs from domestic project eligibility. Foreign manufacturers must redesign driver architectures to meet conducted emission limits below 30 MHz. Industrial lighting suppliers targeting Shanghai's port automation projects face the steepest compliance redesign cycles, with some abandoning the certification pathway entirely.
Building management system unbundling is fragmenting procurement authority across Asia-Pacific commercial real estate. Property developers in Sydney and Melbourne now separate lighting hardware specification from controls integration, awarding contracts to distinct vendors. Facility managers in India's IT parks increasingly source luminaires through direct manufacturer relationships while outsourcing commissioning to specialized systems integrators, eroding traditional electrical distributor margins.
Asia Pacific LED Lighting Market Segmentation
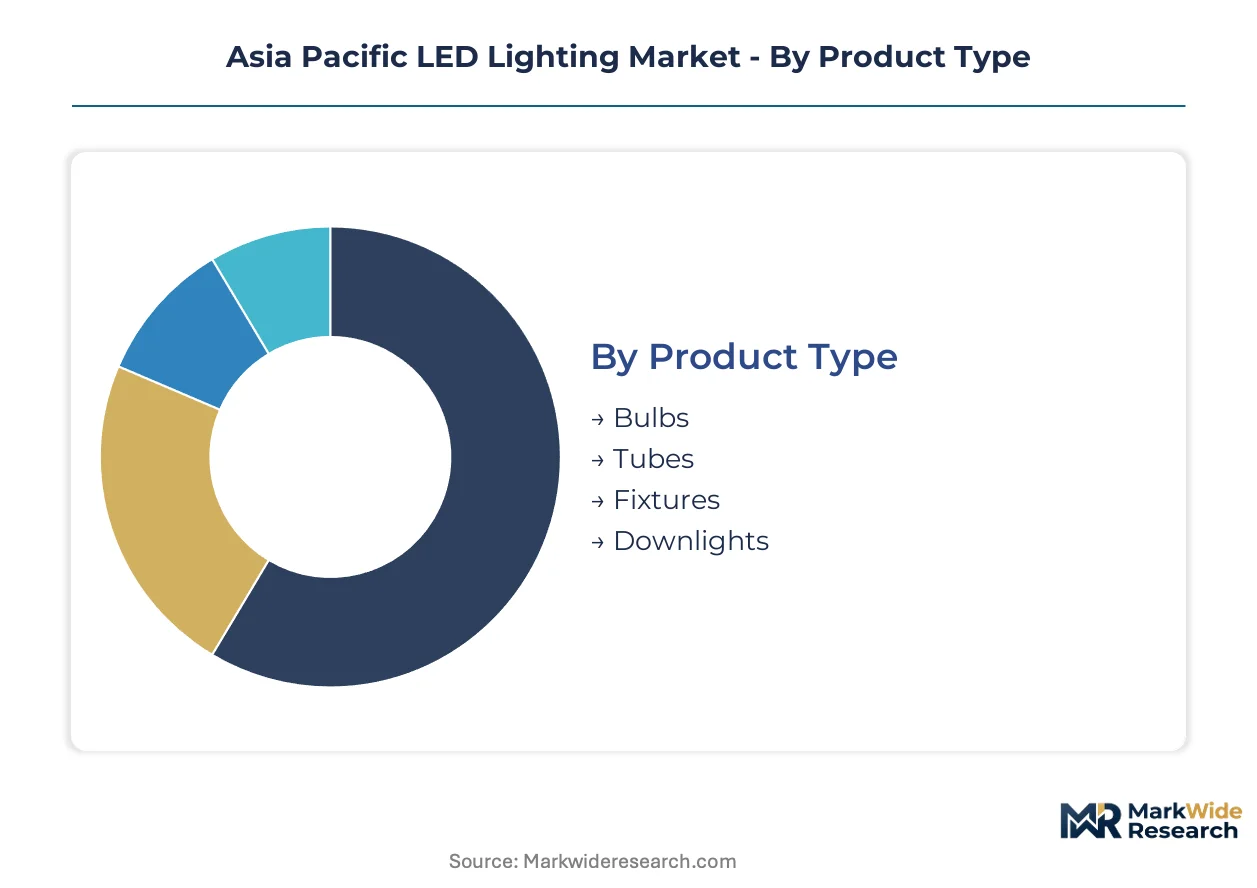
Asia Pacific LED Lighting Market segmentation reveals how certification requirements fragment procurement strategies across product architectures. Divergent national standards force manufacturers to maintain parallel SKUs, eroding scale economics for unified platforms.
Product Type:
BIS certification in India and GB standards in China impose distinct thermal management and driver efficiency requirements across each hardware category, complicating cross-border inventory deployment.
- Tubes:Linear retrofit formats dominate commercial replacement cycles across aging office stock in Tokyo and Sydney. Procurement officers specify ballast-compatible variants for magnetic-ballast legacy infrastructure, though compatibility limitations slow penetration in pre-1990s Australian and Japanese buildings.
- Downlights:Recessed ceiling luminaires concentrate margin pools in premium residential developments across Singapore and Australian metropolitan corridors. Melbourne and Sydney developers specify fire-rated housings with integrated emergency backup circuits, lifting unit costs above commodity bulb replacements.
- Bulbs:Standard A-shape and decorative formats face price compression in mass retail channels across Southeast Asian markets.
- Fixtures:Integrated luminaire-plus-housing systems command specification authority in new construction across Vietnam's industrial zones.
Leading the category by volume: Tubes. Growing fastest: Downlights.
Technology:
Technology selection determines software-recurring revenue potential and grid-interoperability compliance burdens across the region's divergent smart city protocols.
- Smart Lighting:Networked control architectures with BACnet and DALI protocol support capture building management system integration contracts. Singapore's financial district data centers and Seoul's university hospitals mandate remote diagnostics and melanopic lux scheduling, creating bundled hardware-software procurement packages.
- Traditional LED:Passive driver designs without networked controls serve price-sensitive replacement demand in secondary Chinese cities and Indonesian commercial permitting environments lacking mandatory efficacy labeling.
- Solar LED:Off-grid photovoltaic-integrated systems address rural electrification gaps in India's Smart City Mission peripheral zones and Indonesian archipelago infrastructure.
- OLED:Organic emitter panels penetrate high-end architectural accent applications in Tokyo and Seoul premium retail environments where spectral uniformity and form factor flexibility justify cost premiums.
Smart Lighting expands most quickly through software-recurring attach rates. Traditional LED retains volume leadership in replacement cycles.
Application:
Application segmentation maps directly to regulatory enforcement intensity, with commercial and outdoor verticals facing the stiffest efficiency mandate compliance deadlines.
- Commercial Lighting:Office, retail, and hospitality installations face accelerated replacement timelines under China's dual carbon goals and Japan's METI Top Runner benchmarks. Procurement officers in Shanghai and Osaka reallocate capital to semiconductor-grade illumination components ahead of natural depreciation schedules.
- Outdoor Lighting:Street and area illumination concentrates demand in India's Smart City Mission municipal tenders and Vietnam's industrial zone corridor expansions. Binh Duong and Hai Phong factory construction specifies high-bay arrays with 50,000-hour lifespans to minimize maintenance access in automated facilities.
- Residential Lighting:Household replacement cycles lag commercial mandates, though Australian MEPS programs and South Korean MFDS-equivalent frameworks tighten new construction specifications.
- Architectural Lighting:Facade and monument illumination projects in Singapore and Sydney command custom optical engineering for color consistency and weatherproofing.
Commercial Lighting leads by contract value. Outdoor Lighting climbs the fastest through smart city infrastructure deployment.
End User:
End user segmentation determines specification authority concentration, with industrial and office verticals centralizing procurement through facility management departments versus fragmented household decision-making.
- Industrial Facilities:Automated manufacturing plants in Vietnam's Hai Phong corridor and China's Guangdong province specify high-bay LED arrays with integrated motion sensing and daylight harvesting. Maintenance access constraints in ceiling-mounted installations drive 50,000-hour lifespan requirements and predictive analytics integration.
- Offices:Corporate real estate portfolios across Sydney, Melbourne, and Singapore separate lighting hardware specification from controls integration, awarding contracts to distinct vendors and eroding traditional electrical distributor margins.
- Retail Outlets:Brand-conscious merchants in Seoul and Tokyo deploy tunable-white systems for merchandise color rendering optimization.
- Households:Price-sensitive replacement demand concentrates in mass retail channels across Indonesia and secondary Indian cities.
Industrial Facilities lead by specification complexity and contract value. Offices gain share fastest through BMS unbundling trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Pudong corridor concentrates semiconductor-grade illumination procurement as China's dual carbon mandates compress commercial real estate retrofit timelines. Procurement officers across the Asia Pacific LED Lighting Market face divergent national efficiency standards that fragment inventory deployment.
China
Guangdong and Fujian provinces anchor sapphire substrate fabrication clusters that supply downstream LED packagers. MIIT enforces updated GB standards for electromagnetic compatibility that disqualify legacy import designs from domestic project eligibility. Shanghai port automation projects demand the steepest compliance redesign cycles for industrial lighting suppliers.
Japan
Tokyo and Osaka commercial portfolios face accelerated replacement under METI's Top Runner efficiency benchmarks. The program cascades across appliance categories, compelling manufacturers to redesign driver electronics and thermal management systems. Nagoya's automotive lighting specialists command premium compensation for compound semiconductor physicists capable of ray-tracing simulation.
India
Mumbai and Delhi-NCR municipal infrastructure tenders mandate networked street lighting with remote diagnostics under the Smart City Mission. BIS certification requirements shape product specifications for imported LED modules. Binh Duong and Hai Phong factory construction in neighboring Vietnam influences cross-border component flows through shared supply chain relationships.
South Korea
Seoul's university hospitals and eldercare centers deploy tunable-white luminaires with melanopic lux scheduling under MFDS-regulated facility standards. The capital area concentrates demand for human-centric lighting systems that automate circadian rhythm management. Busan-Ulsan manufacturing corridors supply high-brightness discrete LEDs for precision industrial equipment.
Australia
Sydney and Melbourne property developers separate lighting hardware specification from controls integration, awarding contracts to distinct vendors. MEPS programs tighten new construction specifications across residential and commercial verticals. Aging pre-1990s commercial stock in major metros slows LED tube penetration due to magnetic-ballast compatibility limitations.
Asia Pacific LED Lighting Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology differentiation and certification complexity. The Asia Pacific LED Lighting Market exhibits tiered concentration with semiconductor-grade component suppliers occupying protected positions while luminaire assemblers face price compression. Three archetypes dominate: integrated chip-to-fixture manufacturers, specialized optical engineering houses, and scale-driven assembly operations. Capacity expansion in Vietnam and Indonesia and strategic partnerships for smart grid interoperability represent the dominant competitive vectors.
Within the integrated manufacturing tier, Nichia Corporation and Seoul Semiconductor occupy positions defined by proprietary chip architectures and high-brightness discrete supply capabilities. Signify anchors the systems integration vector through direct city municipality contracts across Southeast Asian commercial retrofit channels. These three exemplify how geographic origin and structural positioning within the value chain determine margin capture potential.
| Leading Market Players |
|---|
| Nichia Corporation |
| Signify |
| Seoul Semiconductor |
| Panasonic Holdings Corporation |
| Koito Manufacturing |
| Opple Lighting |
| Samsung Electronics |
| Osram |
| Stanley Electric |
| Others |
Pricing and Supply Chain Analysis
Rare-earth element indices for yttrium-aluminum-garnet phosphors cascade through sapphire substrate fabrication costs into three distinct pricing tiers across the Asia Pacific LED Lighting Market. Procurement officers in Shanghai and Singapore face divergent landed cost structures depending on whether driver electronics meet GB electromagnetic compatibility standards or BIS thermal management requirements.
Pricing Analysis
Outcome-based pricing anchored to energy savings contracts dominates commercial retrofit procurement in Sydney and Melbourne property portfolios. Pricing stratifies across semiconductor-grade premium architectures, GB-certified standard modules, and uncertified economy luminaires for Indonesian secondary markets. Cost compression in the economy tier intensifies due to Vietnamese assembly capacity expansion. Industrial facility managers demonstrate lowest price sensitivity, while Indonesian household segments drive volume through mass retail channels.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong coordinate hub-and-spoke fulfillment patterns for Southeast Asian project sites. Sapphire substrate fabrication clusters in Guangdong and Fujian provinces feed downstream LED packagers, while phosphor material sourcing draws from Chinese rare-earth processing facilities. Single-source vulnerability in epitaxial wafer supply exposes downstream assemblers to power rationing disruptions. Distribution runs through direct manufacturer relationships with municipal procurement officers, bypassing traditional electrical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific LED Lighting Market sits in a technology-transition phase as networked smart lighting architectures displace passive driver designs across commercial building retrofits.
For Market Incumbents: Cement specification authority through proprietary chip architectures that sustain premium positioning in automotive forward-lighting applications. Deepen backward integration into sapphire substrate fabrication to mitigate single-source disruption risks from Guangdong power rationing events. Invest in simultaneous BIS, GB, and JIS certification pathways to compress product launch timelines for unified platform strategies. For New Entrants and Emerging Players: Capture white-space opportunity in Indonesia's regulatory lag environment before mandatory efficacy labeling emerges in Jakarta's commercial permitting process. Target human-centric lighting deployment in South Korea's MFDS-regulated healthcare facilities where circadian-tunable systems command hardware-plus-service contract structures. Pursue direct city municipality relationships for smart street lighting tenders under India's Smart City Mission. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized optical engineering houses with ray-tracing simulation capabilities in Seoul and Nagoya labor markets. Long-term viability rests on software-recurring revenue attach rates from building management system integration rather than hardware commoditization trajectories. Monitor divergence between national efficiency tiers and smart grid interoperability protocols as the critical inflection signal for unified platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Grid Interoperability Partnership | Secures BACnet and DALI protocol certification for Singapore financial district data center contracts. |
| Backward Integration into Sapphire Substrates | Captures Guangdong fabrication capacity to insulate against power rationing disruption risks. |
| Human-Centric Lighting Platform Launch | Addresses melanopic lux scheduling demand in Seoul university hospitals under MFDS standards. |
| Multi-Jurisdiction Certification Investment | Compresses BIS, GB, and JIS testing timelines for cross-border component flow scale economics. |
| Li-Fi Communication Module Development | Creates electromagnetic-interference-free alternative for Singapore data centers restricting radio-frequency systems. |
Research Methodology
Independent corroboration across facility management executives, municipal procurement officers, semiconductor physicists, and electrical distributor principals underwrites the qualitative findings. Primary fieldwork engaged plant engineers at Vietnam industrial zones, lighting specification consultants in Sydney, and regulatory affairs leads navigating MIIT GB standard updates. Secondary validation drew from customs trade data, BIS certification registries, METI energy conservation labeling databases, and SEC filings of listed lighting manufacturers. Bottom-up segment sizing triangulated against top-down macroeconomic anchors across the analysis window.
Comparable-period anchoring to historical retrofit cycle data informed the projection horizon segmentation across product type, technology architecture, application vertical, and end-user procurement authority. The analytical framework modeled smart lighting attach rates, traditional LED replacement velocity, and solar LED rural electrification penetration as distinct growth vectors. CAGRs derived from installed base depreciation schedules, regulatory compliance deadline clustering, and municipal tender award patterns throughout the forecast period.
The model holds under stable rare-earth export quota regimes and uninterrupted sapphire substrate fabrication; deviation in Chinese environmental enforcement intensity or ASEAN regulatory harmonization would shift component cost assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Encapsulation Market
LED
Thailand LED Market
LED
Saudi Arabia LED Lights Market
LED
Infrared (IR) LED Market
LED
Europe Indoor LED Lighting Market
LED
LED Lamp Market
LED
Micro LED Display Market
LED
UAE LED Lights Market
LED
LED Flip Chip Market
LED
Mexico LED Lighting Market
LED
UK Indoor LED Lighting Market
LED
LED and OLED Display Market
LED
Germany Outdoor LED Lighting Market
LED
Surface Mount PLCC Leds Market
LED
Europe Outdoor LED Lighting Market
LED
Germany Automotive LED Lighting Market