
 LED Phosphor Materials Market | 2026-2036
LED Phosphor Materials Market Size, Share, and Industry Trends Forecast 2026-2036
LED Phosphor Materials Market Foresight
Buyer concentration among automotive tier-1 lighting suppliers is rebalancing as electric vehicle platforms fragment procurement across new EV-native manufacturers. Nichia Corporation sustains technology leadership in narrow-band red nitride phosphors for high-CRI applications. Mitsubishi Chemical Corporation anchors supply security through backward integration into rare-earth oxide refining. Intematix Corporation differentiates via remote phosphor architectures that decouple thermal management from LED chip design.
LED phosphor materials are inorganic luminescent compounds, typically cerium-doped yttrium aluminum garnet or europium-activated silicates, that absorb blue or near-UV chip emission and down-convert it to broadband visible light through controlled crystal-field engineering. These materials determine color rendering index, luminous efficacy, and operational stability in solid-state lighting systems. Ce3+-doped YAG dominates volume owing to mature synthesis routes and cost structure, while Sr2SiO4N2:Eu2+ captures fastest growth in automotive forward lighting where thermal quenching resistance commands premium positioning. General lighting remains the largest application pool though display technology applications in quantum-dot-enhanced films are reshaping margin distribution across the value chain.
REACH restrictions on heavy metal content and RoHS substance thresholds constrain formulation flexibility for European-sourced materials, while China's GB standards and MIIT efficiency benchmarks mandate minimum luminous efficacy thresholds that filter lower-performance phosphors from domestic tenders. The EU F-Gas Regulation indirectly pressures LED retrofit demand by accelerating fluorescent phase-outs. Stakeholders must monitor rare-earth export licensing dynamics and nitride phosphor patent expiries to time capacity investments and geographic sourcing shifts.
Market Dynamics
Rare-earth supply concentration and dual carbon mandates are forcing reformulation strategies across LED phosphor supply chains, with nitride phosphor thermal stability now commanding decisive specification weight in automotive procurement.
Growth Catalysts
- Automotive LED headlamp mandates:OEMs across passenger and commercial vehicle segments are specifying high-CRI phosphor packages for forward lighting, creating sustained volume pull for nitride-based formulations.
- REACH and RoHS substance thresholds:European regulatory pressure on heavy metal content is filtering non-compliant formulations from tender pools, advantaging certified suppliers with established compliance documentation.
- China's MIIT efficiency benchmarks:Minimum luminous efficacy thresholds for domestic lighting tenders are accelerating retirement of legacy halophosphate and silicate phosphors from the country's manufacturing base.
Market Restraints
- Rare-earth oxide price volatility:Cerium and europium spot market swings transmit directly to YAG and silicate phosphor cost structures, compressing margin predictability for non-integrated compounders.
- Nitride phosphor synthesis complexity:High-temperature solid-state routes and oxygen-sensitive handling requirements limit qualified manufacturing capacity to a concentrated supplier set in East Asia.
- Quantum-dot film substitution:Cd-free quantum-dot enhancement layers in display backlighting are capturing premium margin pools that phosphor-converted white LEDs previously dominated.
Strategic Opportunities
- Remote phosphor architectures:Thermal decoupling from LED chip designs opens specification opportunities in high-lumen industrial and horticultural fixtures where junction temperatures exceed conventional package limits.
- India's LED streetlighting expansion:Bureau of Energy Efficiency procurement programs and Smart Cities Mission deployment targets are creating import demand for efficacy-certified phosphor materials.
- EU F-Gas Regulation fluorescent phase-outs:Accelerated retirement of mercury-containing lamps is retrofitting installed base demand toward LED phosphor-dependent solutions across commercial and institutional buildings.
Industry Challenges
- Nitride phosphor patent cliff navigation:Expiring composition and synthesis IP from 2005-2010 filings is triggering licensing complexity as second-tier manufacturers position for generic production entry.
- Phosphor-converter integration with mini-LED backlights:Tighter pitch arrays and chip-scale packages demand particle size distribution control and dispersion uniformity that legacy powder processing lines cannot achieve without capital retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Phosphor Materials Market |
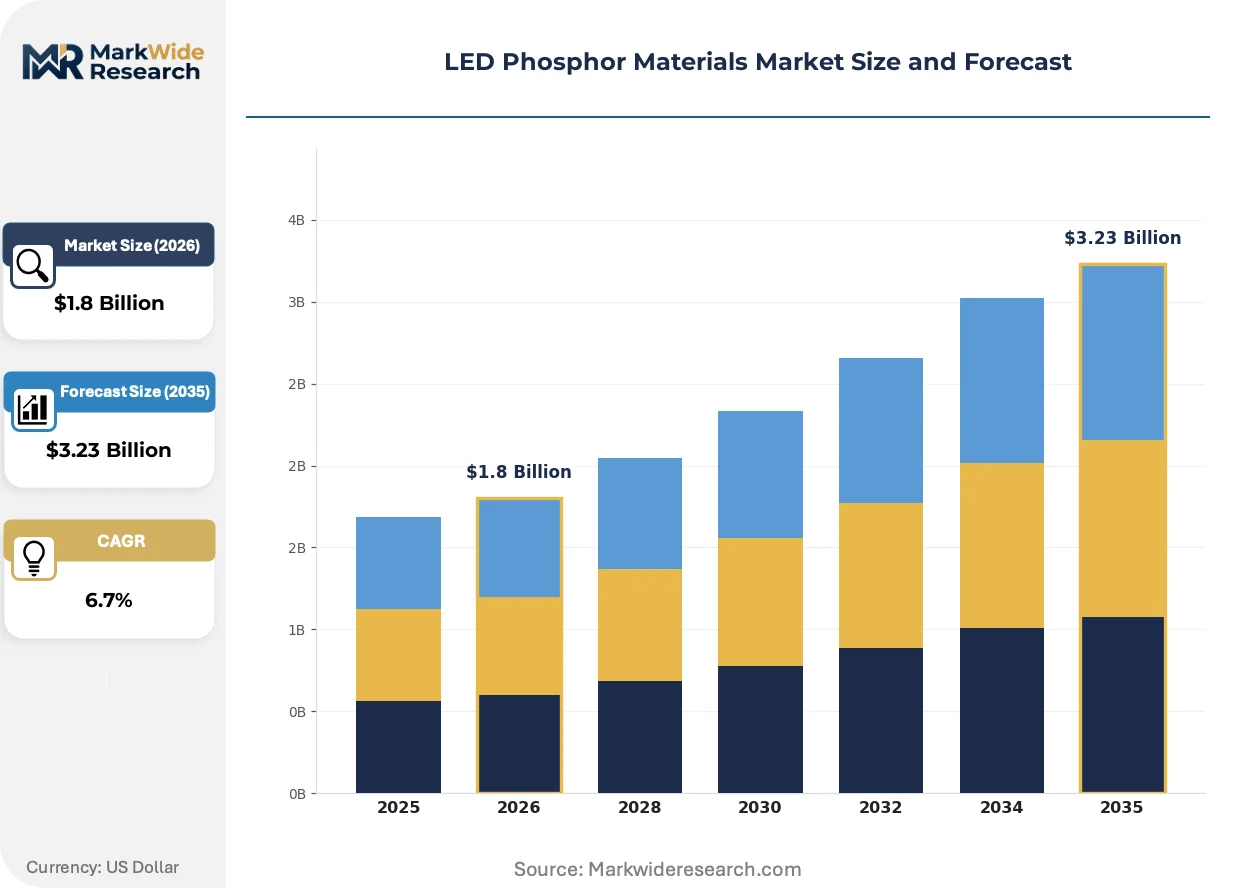
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ce3&doped YAG, Sr2SiO4N2:Eu2&, BaAl2Si2O8:Eu2&, Others Application: General Lighting, Automotive Lighting, Display Technology, Backlighting End User: Consumer Electronics, Automotive, Industrial, Retail Delivery Mode: Powder, Coating, Paste, Liquid |
| Companies Covered | Mitsubishi Chemical Corporation, Osram GmbH, Intematix Corporation, Epistar Corporation, Seoul Semiconductor Co. Ltd., Nichia Corporation, Denka Co. Ltd., Everlight Electronics Co. Ltd., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Phosphor Materials Market Shifts & Advancements
Computational materials discovery and thermal management architectures are compressing development cycles and expanding addressable applications beyond conventional solid-state lighting into spectral engineering domains.
Machine learning-guided crystal structure prediction is automating dopant site selection and host lattice screening for novel narrow-band emitters. Materials informatics platforms at national laboratories and specialty chemical firms are collapsing empirical synthesis iterations from hundreds to dozens. This acceleration is compressing time-to-market for automotive-qualified phosphor compositions.
China's GB standards and dual carbon goals are tightening rare-earth utilization efficiency requirements in domestic phosphor manufacturing. MIIT circular economy directives are mandating recovery rates from production scrap and end-of-life luminaires. Domestic compounders are responding with closed-loop hydrometallurgical refining investments.
Automotive tier-1 lighting suppliers are consolidating specification authority as EV-native OEMs bypass traditional supply chain hierarchies. Direct material qualification relationships between phosphor compounders and vehicle manufacturers are displacing distributor-mediated procurement in premium forward lighting programs. This pattern concentrates most visibly in German and South Korean automotive manufacturing clusters.
LED Phosphor Materials Market Segmentation
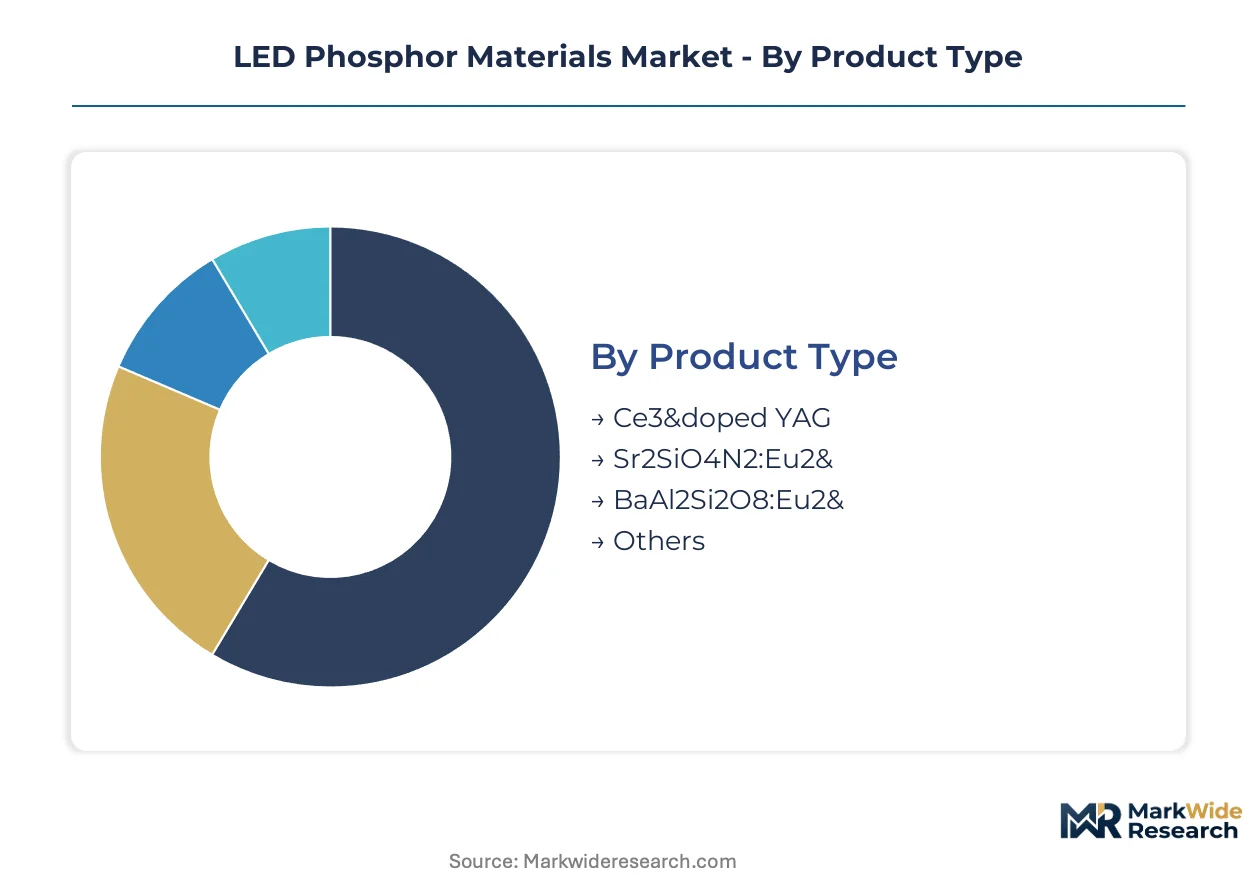
LED phosphor materials fragment across multiple technical and commercial dimensions. Product chemistry determines thermal limits and color rendering performance. Application requirements drive specification divergence between cost-sensitive general lighting and precision automotive forward illumination.
Product Type:
Ce3+-doped YAG dominates volume shipments while nitride phosphors command premium positioning in thermal-stress applications.
- Ce3+-doped YAG:Cerium-activated yttrium aluminum garnet crystals deliver broad yellow emission with mature high-temperature solid-state synthesis routes. General lighting manufacturers in China specify this composition for cost-optimized retrofit lamps and commercial fixtures where moderate thermal environments prevail.
- Sr2SiO4N2:Eu2+:Europium-activated oxynitride silicates exhibit superior thermal quenching resistance above 150°C junction temperatures. Automotive tier-1 lighting suppliers in Germany and South Korea specify these formulations for LED headlamp modules where thermal management constraints exceed YAG operational limits.
- BaAl2Si2Si2O8:Eu2+:Barium aluminum silicate hosts provide narrow-band green emission for display backlighting color gamut extension.
- Others:Fluoride phosphors and quantum-dot hybrid systems address niche spectral engineering requirements in horticultural and medical illumination.
Today's leader: Ce3+-doped YAG. Tomorrow's challenger: Sr2SiO4N2:Eu2+.
Application:
Automotive lighting specifications are climbing fastest as OEM mandates proliferate across vehicle platforms.
- General Lighting:Residential and commercial retrofit demand concentrates in China, India, and Southeast Asian manufacturing clusters. Bureau of Energy Efficiency procurement programs in India and China's MIIT efficiency benchmarks filter substandard formulations from tender pools.
- Automotive Lighting:Forward illumination specifications from German and South Korean OEMs mandate high-CRI nitride phosphor packages. Thermal stability requirements and direct qualification relationships between compounders and vehicle manufacturers reshape procurement hierarchies.
- Display Technology:Quantum-dot enhancement films are displacing phosphor-converted white LEDs in premium television and monitor backlighting, compressing margin pools for traditional rare-earth formulations.
- Backlighting:Mini-LED array integration demands tighter particle size distribution control than legacy powder processing achieves without capital retrofit.
General Lighting anchors current volume. Automotive Lighting expands most quickly.
End User:
Automotive direct procurement patterns are displacing distributor-mediated channels in premium lighting programs.
- Consumer Electronics:Smartphone, tablet, and laptop manufacturers specify phosphor-converted white LEDs for display backlighting, though quantum-dot substitution pressure intensifies in premium product tiers.
- Automotive:EV-native OEMs bypass traditional tier-1 hierarchies to qualify phosphor materials directly, concentrating specification authority in German and South Korean manufacturing clusters.
- Industrial:High-lumen fixtures and horticultural installations specify remote phosphor architectures that decouple thermal management from LED chip design.
- Retail:Commercial space illumination prioritizes color rendering index and luminous efficacy for merchandise presentation.
Automotive commands specification authority. Industrial applications open architecture diversification.
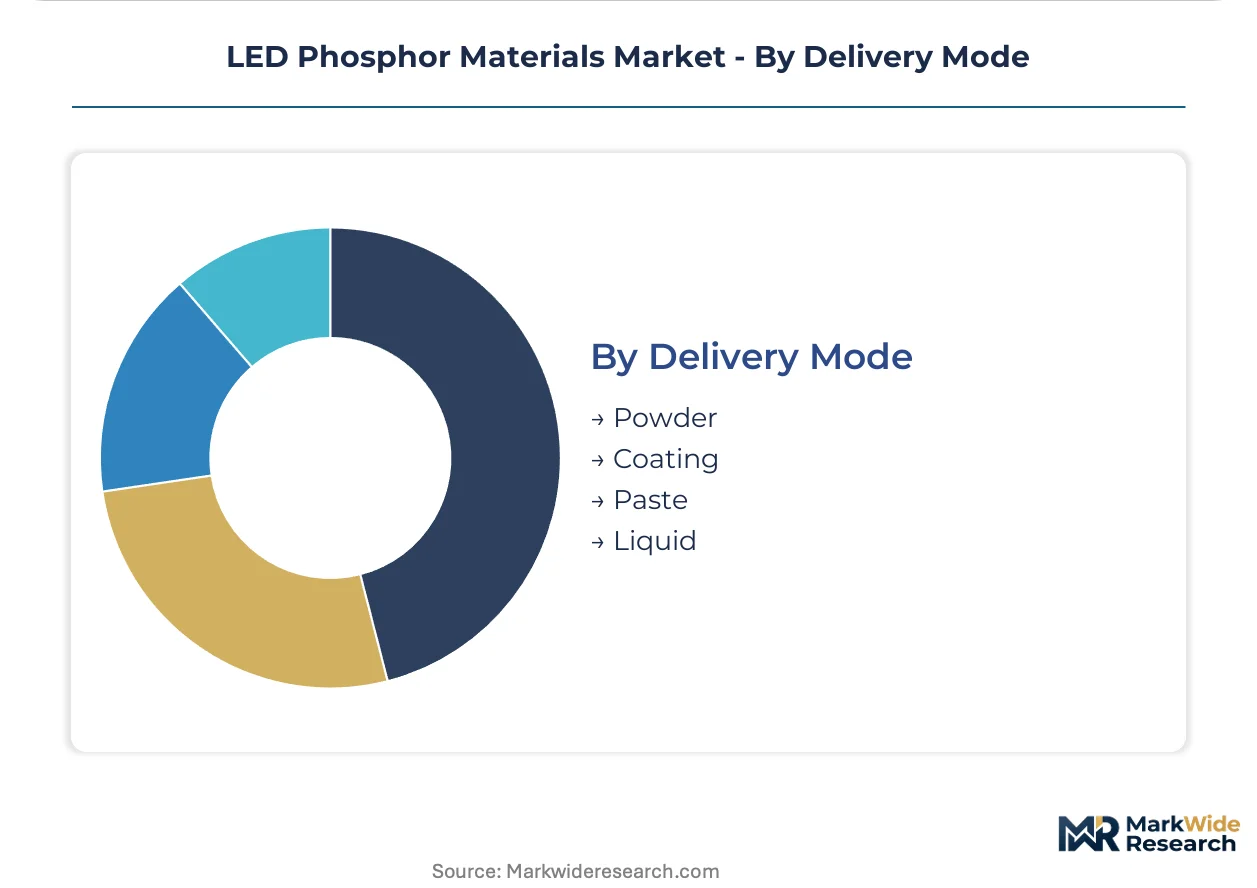
Delivery Mode:
Form factor selection tracks thermal management strategy and manufacturing integration requirements.
- Powder:Standard particulate formulations suit conventional chip-on-board packaging with established dispensing equipment.
- Coating:Pre-deposited phosphor layers simplify high-volume LED package assembly.
- Paste:Viscous dispersions enable precise volumetric control in automated die-attach operations.
- Liquid:Suspension formulations support spray deposition and inkjet patterning for remote phosphor and quantum-dot hybrid architectures.
Powder retains process familiarity. Liquid enables next-generation thermal decoupling designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon mandates and MIIT efficiency benchmarks are reshaping material specifications faster than European REACH compliance timelines, while automotive LED adoption in Germany and South Korea is accelerating specification divergence between thermal-stress and cost-optimized formulations.
China
Domestic lighting manufacturers in the Yangtze River Delta are retiring legacy halophosphate phosphors under MIIT circular economy directives that mandate rare-earth recovery rates from production scrap. GB standards tightening luminous efficacy thresholds filter substandard formulations from government tender pools. Shenzhen and Suzhou manufacturing clusters concentrate reformulation investments toward rare-earth-reduced nitride alternatives.
Germany
Automotive tier-1 lighting suppliers in Bavaria and Baden-Württemberg specify high-CRI nitride phosphor packages for LED headlamp modules across Mercedes-Benz, BMW, and Volkswagen platforms. EU F-Gas Regulation fluorescent phase-outs accelerate commercial building retrofit demand. KBA vehicle-type approval processes are tightening thermal stability documentation requirements for forward illumination systems.
South Korea
Hyundai Motor Group and Kia Corporation procurement programs mandate direct phosphor material qualification relationships, bypassing traditional distributor channels. Seoul Semiconductor and LG Innotek manufacturing clusters in Gyeonggi Province anchor nitride phosphor specification authority. MFDS industrial chemical regulations align with REACH substance thresholds for export-bound formulations.
United States
EPA energy efficiency programs and state-level building codes in California and New York drive LED retrofit demand across commercial real estate portfolios. NHTSA headlamp performance standards are converging with European ECE regulations, opening specification pathways for thermally robust phosphor packages. Detroit automotive engineering centers are qualifying materials directly for EV-native lighting platforms.
Japan
METI energy conservation standards for lighting equipment mandate minimum efficacy thresholds that favor phosphor-converted white LEDs over legacy technologies. Nichia Corporation's technology leadership in narrow-band red nitride phosphors anchors supply relationships with domestic and export automotive programs. Nagoya and Osaka industrial corridors concentrate precision phosphor synthesis capacity for display backlighting applications.
LED Phosphor Materials Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and thermal management architectures. The supplier set concentrates around three strategic archetypes: rare-earth-integrated chemical conglomerates, nitride phosphor technology specialists, and LED package manufacturers with captive phosphor operations. Competitive dynamics center on backward integration into rare-earth oxide refining and patent licensing negotiations as 2005-2010 composition IP expires.
Within the technology specialist tier, Nichia Corporation exemplifies narrow-band emitter leadership, while Mitsubishi Chemical Corporation anchors rare-earth supply security through in-house oxide refining. Intematix Corporation occupies a distinct position in remote phosphor architectures that decouple thermal management from chip design. These three entities represent divergent strategic bets on formulation chemistry, supply chain control, and system-level integration.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Osram GmbH |
| Intematix Corporation |
| Epistar Corporation |
| Seoul Semiconductor Co. Ltd. |
| Nichia Corporation |
| Denka Co. Ltd. |
| Everlight Electronics Co. Ltd. |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
China's dual carbon goals gate both qualified supply and premium-tier pricing access, filtering non-compliant compounders from domestic tender pools while concentrating rare-earth-reduced formulation premiums among certified suppliers. This environmental mandate reshapes procurement hierarchies as automotive tier-1 lighting suppliers demand thermal-stress documentation that only integrated manufacturers can reliably deliver.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for Ce3+-doped YAG formulations. Pricing stratifies across automotive-certified nitride phosphors, general lighting halophosphate replacements, and economy-tier silicate alternatives. Cost compression in standard YAG grades is intensifying because domestic compounders are retiring legacy synthesis lines under MIIT circular economy directives. Automotive OEMs exhibit least price sensitivity due to thermal stability mandates, while Indian streetlighting procurement programs drive highest volume-price elasticity.
Supply Chain Analysis
Rare-earth oxide supply rests on Chinese state-controlled mining consortiums and Japanese trading house import channels. Cerium and europium feedstocks draw from Bayan Obo extraction complexes and Malaysian Lynas refining operations. Single-source vulnerability concentrates in nitride phosphor qualified manufacturing, where high-temperature solid-state synthesis limits capacity to East Asian specialist compounders. Distribution runs through automotive tier-1 lighting suppliers for forward illumination programs, while general lighting channels flow via LED package manufacturers and distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with EU F-Gas Regulation fluorescent phase-outs driving retrofit demand acceleration across commercial building portfolios. Stakeholders must align capacity investments with compliance documentation timelines.
For Market Incumbents: Anchor rare-earth supply security through backward integration into oxide refining or long-term offtake agreements with Chinese state mining enterprises. Patent licensing negotiations around expiring 2005-2010 nitride phosphor composition IP demand proactive legal positioning to defend against generic manufacturer entry. Certification investment in REACH and RoHS documentation creates channel control leverage as European automotive procurement tightens substance thresholds. For New Entrants and Emerging Players: The price-point gap between premium automotive nitride phosphors and economy-tier silicate alternatives opens specification opportunities in India's Bureau of Energy Efficiency streetlighting programs. Remote phosphor architectures for high-lumen industrial and horticultural fixtures represent the most penetrable application segment, bypassing established chip-on-board packaging relationships. A certification-first go-to-market angle targeting efficacy benchmarks in tender-driven procurement pools accelerates qualification timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among rare-earth-non-integrated compounders facing margin compression from oxide price volatility. Long-term viability across the analysis window hinges on reformulation capabilities toward rare-earth-reduced alternatives and thermal management architecture patents. Patent expiry sequencing in nitride phosphor composition IP serves as the critical inflection indicator for generic entry timing and licensing revenue erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Oxide Refining | Mitsubishi Chemical Corporation's captive supply of cerium and europium insulates margin predictability from spot market swings. |
| Remote Phosphor Architecture Development | Intematix Corporation's thermal decoupling designs address high-lumen industrial fixtures where junction temperatures exceed conventional limits. |
| Automotive Direct Qualification Relationships | Hyundai Motor Group procurement programs bypass tier-1 hierarchies to specify nitride phosphor packages directly. |
| Closed-Loop Hydrometallurgical Refining Investment | Suzhou manufacturing clusters respond to MIIT scrap recovery mandates with production waste recycling infrastructure. |
| Computational Materials Discovery Platform Deployment | National laboratory partnerships accelerate dopant site selection for automotive-qualified narrow-band emitters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with phosphor compounder R&D directors, automotive tier-1 lighting procurement leads, LED package manufacturer supply planners, and rare-earth trading house analysts with secondary validation. Customs data from Chinese export licensing disclosures, MIIT efficiency benchmark publications, EU ECHA REACH registration databases, and automotive OEM supplier qualification portals anchored supply-side sizing. Bottom-up phosphor formulation demand modeling triangulated against top-down LED package production estimates.
Segment-weighting approaches applied chemistry-specific thermal stability coefficients and application-specific certification requirements across the projection horizon. Product type segmentation modeled Ce3+-doped YAG, Sr2SiO4N2:Eu2+, and fluoride phosphor growth trajectories. Application segmentation weighted automotive forward lighting mandates against general lighting retrofit cycles and quantum-dot substitution pressure in display backlighting. CAGRs derived from rare-earth oxide price elasticity assumptions and automotive LED headlamp penetration curves. Nitride phosphor patent expiry sequencing and China's dual carbon policy implementation velocity served as scenario-branching inputs.
Caveats apply where rare-earth export licensing dynamics or nitride phosphor synthesis capacity bottlenecks could materially shift the outlook. Forecasts assume continued MIIT efficiency benchmark enforcement and EU F-Gas Regulation fluorescent phase-out adherence. A small set of named triggers warrants ongoing watch: patent cliff navigation outcomes, automotive EV-native OEM procurement pattern stability, and quantum-dot film cost parity achievement in premium display tiers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
US Outdoor LED Lighting Market
LED
India LED Outdoor Lighting Market
LED
GCC LED Lighting Market
LED
LED Lighting Controllers Market
LED
France Outdoor LED Lighting Market
LED
Asia Pacific Indoor LED Lighting Market
LED
North America LED Packaging Market
LED
LED Panel Market
LED
LED Work Light Market
LED
Smart LED Indoor Signage Market
LED
Mini LED Display Market
LED
Light Emitting Diode (LED) Backlight Display Market
LED
Russia LED Market
LED
UV-C LED Market
LED
North America Outdoor LED Lighting Market
LED
Global Waterproof LED Module Market