
 GCC LED Lighting Market | 2026-2036
GCC LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
GCC LED Lighting Market Intelligence
Commercial real estate and hospitality is rebalancing the GCC LED Lighting Market as mega-projects across the Gulf diversify beyond oil-dependent infrastructure. Signify Holding leverages its Interact platform to dominate intelligent lighting controls in Dubai's smart district developments. Cree Lighting anchors its position through high-performance chip-on-board technology tailored to extreme desert thermal conditions. OSRAM Licht AG competes via specialized automotive-to-architectural LED transfer capabilities serving Saudi giga-project pipelines.
GCC LED Lighting comprises solid-state illumination systems utilizing semiconductor diodes emitting visible light when electrical current passes through p-n junctions, typically operating at 80-150 lumens per watt with color temperatures spanning 2700K to 6500K, primarily deployed to reduce energy consumption in commercial, industrial, and public infrastructure applications. Fixtures command the largest product type share due to integration complexity in large-scale construction, while Tubes represent the fastest-growing retrofit category as existing fluorescent stock across aging commercial buildings requires phased replacement. Smart installation types concentrate margin pools through recurring software and control-layer revenue, distinguishing premium suppliers from commodity bulb vendors.
Saudi Standards, Metrology and Quality Organization (SASO) energy efficiency mandates and UAE's Emirates Authority for Standardization and Metrology (ESMA) regulations enforce minimum luminous efficacy thresholds and restrict high-pressure sodium imports, directly shaping procurement specifications across Gulf public tenders. The EU AI Act's extraterritorial influence on automated lighting control exports and local green building codes such as Qatar's Global Sustainability Assessment System further tighten compliance requirements for multinational suppliers. Stakeholders must monitor evolving interconnection standards between legacy building management systems and emerging IoT lighting networks to preserve retrofit competitiveness.
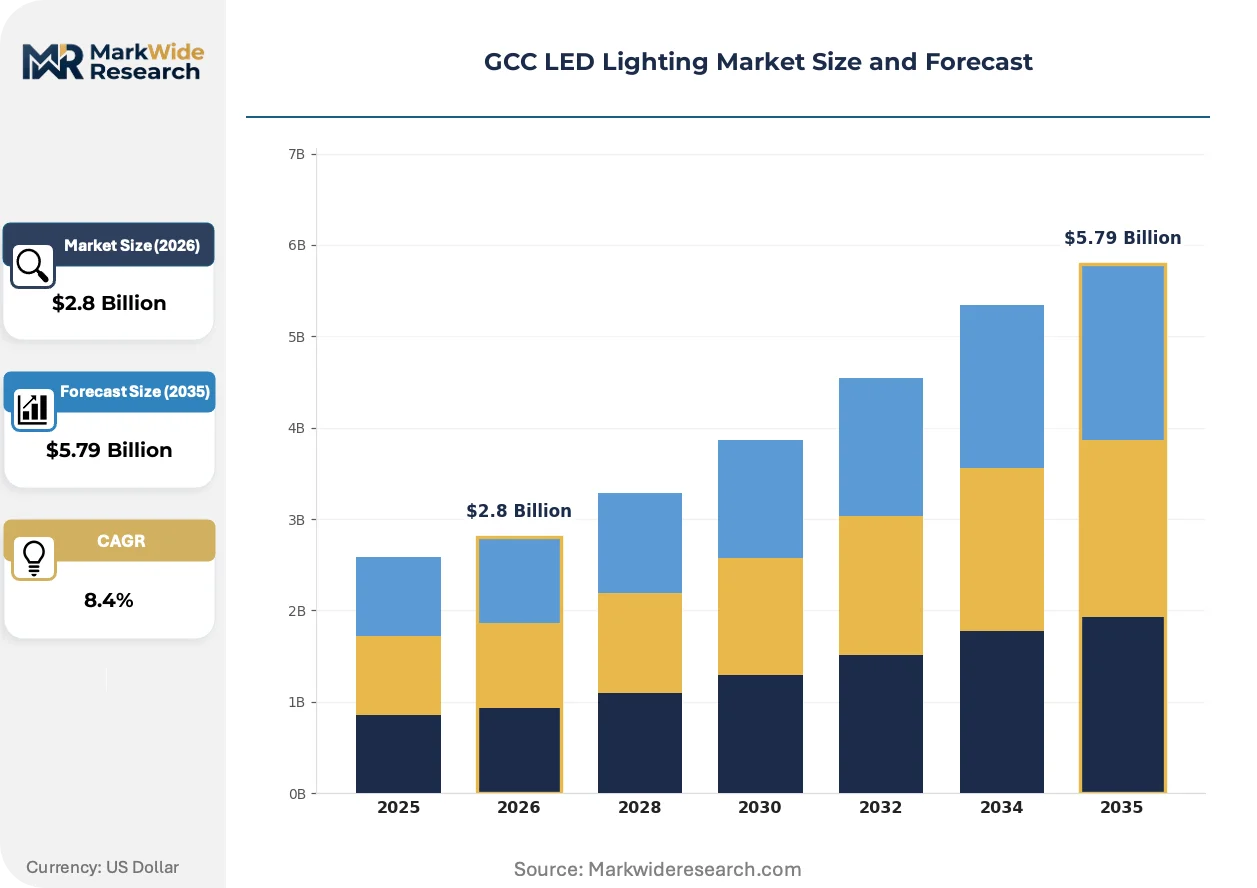
Market Dynamics
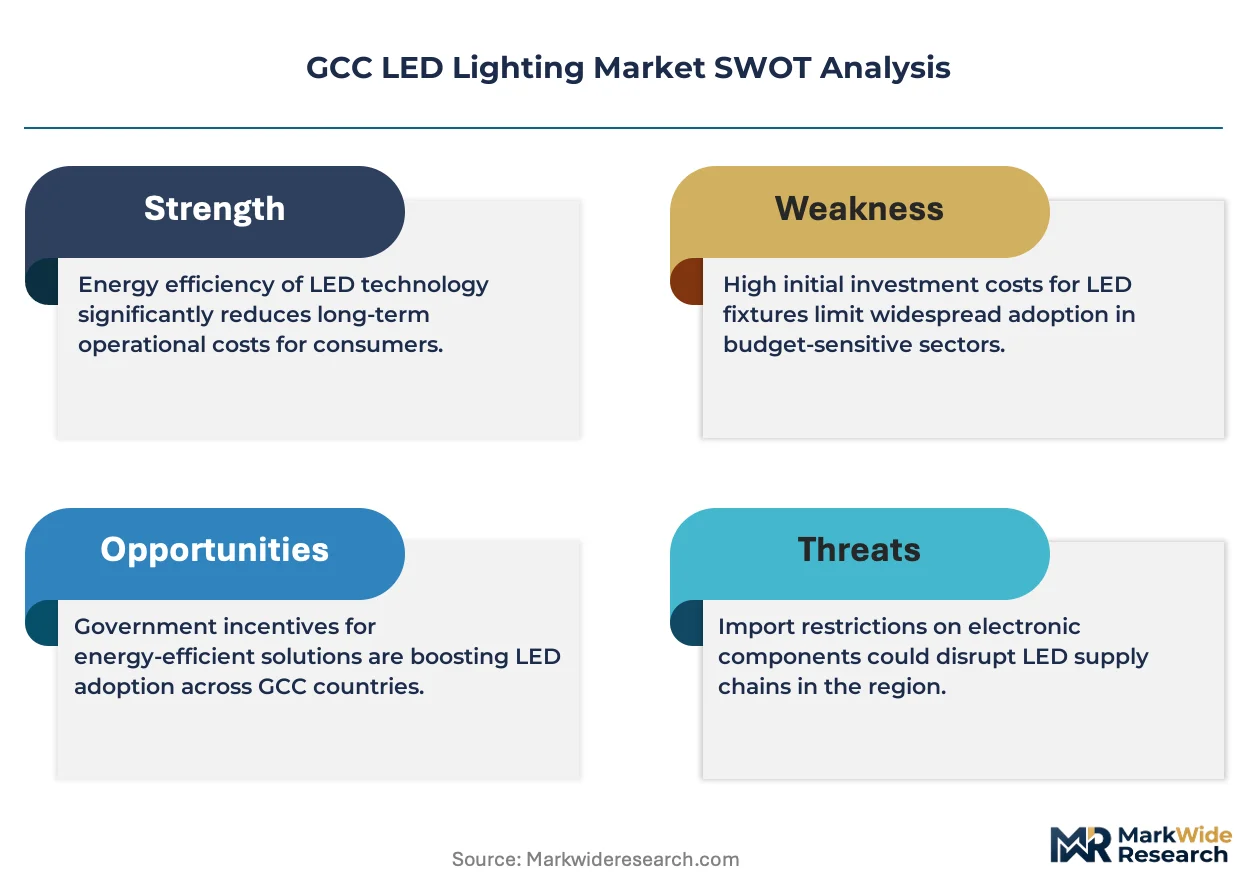
The GCC LED Lighting Market faces acute pressure from SASO and ESMA efficacy mandates that retroactively disqualify legacy inventory while accelerating replacement cycles across commercial portfolios. These regulatory compressions are forcing distributors to clear non-compliant stock and manufacturers to requalify entire product lines under tighter thermal and luminous benchmarks.
Growth Catalysts
- Smart City Infrastructure:Saudi giga-projects and Dubai smart districts deploy networked luminaires with sensor integration, creating bundled hardware-software procurement channels.
- Retrofit Mandates:Qatar's Global Sustainability Assessment System penalizes fluorescent installations in new construction, redirecting capital toward LED tube and fixture replacements.
- Extreme Climate Engineering:Thermal management advances in chip-on-board architectures sustain lumen maintenance above 90% at ambient temperatures exceeding 50°C.
Market Restraints
- Import Concentration:Fixture assembly relies on concentrated semiconductor substrate supply from East Asian foundries, exposing Gulf distributors to shipping volatility.
- Phosphor Cost Volatility:Rare-earth element pricing for yttrium and europium dopants fluctuates with Chinese export quota adjustments, compressing margin on high-CRI products.
- Technical Substitution Ceiling:OLED panel efficacy in architectural accent applications threatens premium LED downlight positioning in luxury hospitality segments.
Strategic Opportunities
- Underpenetrated Industrial:Saudi manufacturing zones and UAE free-trade warehousing retain metal-halide high-bay installations ripe for sensor-enabled LED retrofit.
- Human-Centric Lighting:Circadian-tunable systems are integrating with building management platforms in Doha healthcare and education verticals.
- Service Revenue Unbundling:Lighting-as-a-service contracts separate hardware ownership from energy performance guarantees, opening recurring revenue streams for controls specialists.
Industry Challenges
- Interoperability Fragmentation:Proprietary mesh protocols from competing controls vendors block seamless retrofit into legacy DALI-wired commercial buildings.
- Thermal Qualification Bottlenecks:Third-party testing capacity for SASO certification lags submission volumes, extending product launch timelines by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC LED Lighting Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Tubes, Downlights End User: Residential, Commercial, Industrial, Outdoor Installation Type: New, Retrofit, Replacement, Smart Distribution Channel: Online, Retail, Wholesale, Direct |
| Companies Covered | Panasonic Corporation, Cree Lighting, Signify Holding, Eaton Lighting, Zumtobel Group, OSRAM Licht AG, Acuity Brands, Dialight, Samsung Electronics, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC LED Lighting Market Strategic Shifts & Innovations
Intelligent control layers are separating premium LED suppliers from commodity fixture vendors across Gulf commercial tenders. Three convergent developments are reshaping procurement specifications and technical roadmaps.
Li-Fi visible light communication is integrating data transmission capability into standard luminaire form factors. Airport operators in Dubai and Doha pilot passenger guidance systems through modulated LED arrays. This convergence is compressing the boundary between illumination infrastructure and IT network deployment.
SASO's 2024 efficacy tier upgrade retroactively disqualifies mid-grade imports that satisfied 2019 thresholds. Wholesale distributors in Jeddah and Riyadh face inventory write-downs on non-compliant stock. Manufacturers are accelerating heat-sink redesigns to maintain lumen-per-watt ratings under tighter test conditions.
Facility managers in UAE commercial towers now specify outcome-based performance contracts rather than capital purchase of fixtures. Energy service companies assume upfront installation costs and recover investment through guaranteed savings shares. This shift concentrates buyer power among qualified ESCO consortiums and marginalizes pure hardware vendors lacking measurement and verification capabilities.
GCC LED Lighting Market Segmentation
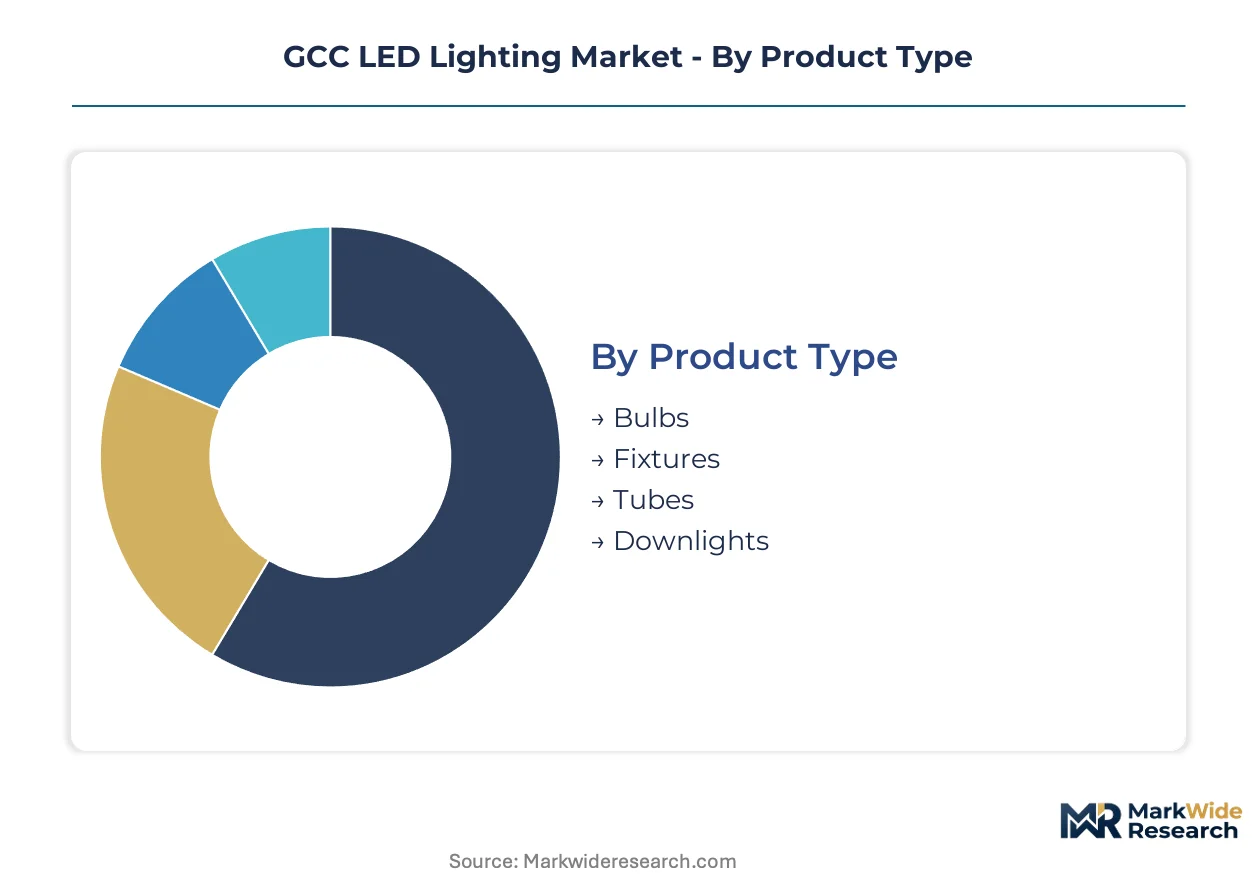
Segmentation reveals how procurement specifications diverge across GCC construction verticals. Thermal performance requirements, retrofit urgency, and smart infrastructure mandates fragment demand patterns across product categories and installation modes.
Product Type:
Supply concentration in chip-on-board substrates favors integrated fixture manufacturers over discrete component vendors.
- Fixtures:Complete luminaire assemblies incorporating heat sinks, drivers, and optical housings designed for 50°C+ ambient operation. Saudi giga-projects and Dubai commercial towers specify these for new construction, with procurement bundling controls and sensors.
- Tubes:Linear retrofit modules replacing T8 and T5 fluorescent stock in aging commercial buildings. Qatar's Global Sustainability Assessment System penalties on fluorescent installations accelerate replacement cycles across Doha office portfolios.
- Bulbs:Standard A19 and PAR form factors for residential and small commercial replacement demand.
- Downlights:Recessed ceiling modules targeting hospitality and luxury retail fit-outs.
Fixtures absorb the bulk of installed capacity; Tubes are expanding most quickly.
End User:
Margin pools concentrate where energy codes enforce minimum efficacy thresholds and penalty structures.
- Commercial:Office towers, retail malls, and hospitality properties subject to ESMA and SASO mandates. Procurement emphasizes lifecycle cost over first cost, with facility managers specifying 50,000-hour lumen maintenance guarantees.
- Outdoor:Street lighting, airport apron illumination, and highway infrastructure. Dubai and Riyadh smart city deployments network these assets for remote dimming and fault detection.
- Industrial:Manufacturing zones and logistics warehousing retaining legacy metal-halide high-bay installations.
- Residential:Villa and apartment stock with limited regulatory pressure, price-sensitive replacement demand.
Commercial captures dominant procurement volume; Outdoor climbs the fastest on infrastructure deployment timelines.
Installation Type:
Customer type stratification separates capital-project owners from operational retrofit managers.
- Smart:Networked luminaires with embedded sensors, wireless mesh connectivity, and software control layers. Dubai smart districts and Saudi giga-projects bundle hardware-software procurement, creating recurring revenue attachment for controls specialists.
- Retrofit:LED replacement of fluorescent and HID installations in existing buildings. Aging commercial stock across Jeddah and Doha drives tube and fixture replacement cycles.
- New:First-fit specification in ground-up construction, dominated by fixture-integrated solutions.
- Replacement:Like-for-like failure-driven demand in residential and small commercial segments.
Smart installation concentrates margin expansion; Retrofit sustains highest absolute unit volumes.
Distribution Channel:
Volume scale determines channel economics, with large project tenders bypassing traditional wholesale layers.
- Direct:Manufacturer-to-contractor relationships for mega-project procurement. Saudi giga-projects and Dubai smart district developments negotiate bulk supply agreements with performance guarantees.
- Wholesale:Distributor networks serving mid-scale commercial retrofit and replacement demand. Inventory risk concentrates here as SASO efficacy upgrades force non-compliant stock write-downs.
- Retail:Big-box and specialty lighting stores for residential and small commercial replacement.
- Online:E-commerce platforms gaining share in standardized bulb and tube categories.
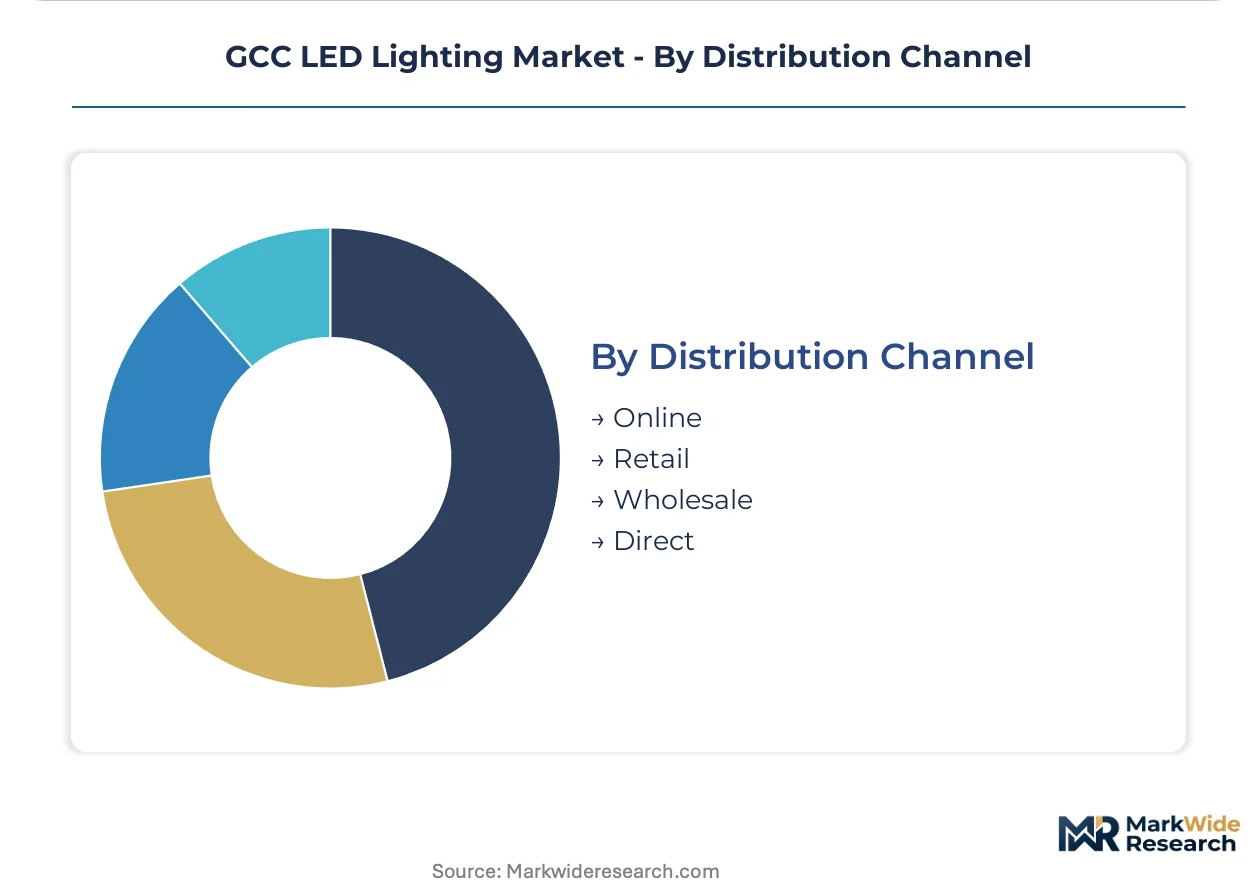
Direct channel commands project value concentration; Wholesale retains widest SKU coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones across the Gulf Cooperation Council states concentrate LED procurement through bundled infrastructure tenders. Free-trade warehousing in Jebel Ali, bonded logistics parks in Dammam, and technology clusters in Doha channel volume toward integrated fixture suppliers with regional certification capacity.
Saudi Arabia
NEOM and the Red Sea Project drive specification of networked luminaires with embedded environmental sensors. SASO's 2024 efficacy tier upgrade retroactively disqualifies legacy inventory, forcing distributors in Riyadh and Jeddah to clear non-compliant stock. The King Abdullah Financial District anchors smart district deployments with outcome-based performance contracting.
United Arab Emirates
Dubai's smart city mandate and Abu Dhabi's Masdar sustainable city initiative prioritize circadian-tunable systems for commercial towers. ESMA regulations enforce minimum luminous efficacy thresholds that block high-pressure sodium imports. Jebel Ali free zone warehouses serve as regional distribution hubs for East Asian semiconductor substrates.
Qatar
Lusail City and the FIFA legacy infrastructure program sustain fixture demand across hospitality and retail verticals. The Global Sustainability Assessment System penalizes fluorescent installations in new construction, redirecting capital toward LED tube replacements. Doha's Education City cluster pilots human-centric lighting in healthcare and research facilities.
Kuwait
Sabah Al Ahmad Sea City and Silk City developments specify marine-grade fixtures with enhanced thermal management. The country's national standards body aligns efficacy mandates with SASO benchmarks, tightening procurement specifications for public tenders. Shuwaikh industrial zone warehouses retain metal-halide high-bay installations targeted for sensor-enabled retrofit.
Oman
Duqm Special Economic Zone and Muscat airport expansion sustain commercial and outdoor lighting demand. The Authority for Electricity Regulation enforces minimum energy performance standards for new construction permits. Sohar port free zone concentrates logistics warehousing with aging HID stock requiring phased LED conversion.
GCC LED Lighting Market Key Industry Players
Top-tier vendors anchor premium specification in mega-project procurement, while mid-scale distributors compete on retrofit volume and certification speed. The vendor base stratifies across three tiers: integrated controls specialists capturing software-software revenue, thermal-engineering-focused fixture manufacturers qualifying for desert climate deployment, and commodity assemblers serving price-sensitive replacement demand. Dominant competitive moves include strategic partnerships with energy service companies and geographic expansion through regional certification licensing.
Within the controls-integrated tier, Signify Holding and OSRAM Licht AG exemplify archetypes that separate hardware ownership from performance-guaranteed service contracts. Cree Lighting occupies a position among thermal-engineering specialists with chip-on-board architectures designed for ambient temperatures exceeding 50°C. These three entities represent the competitive vectors reshaping procurement: software-layer attachment, climate-specific qualification, and outcome-based contracting.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Cree Lighting |
| Signify Holding |
| Eaton Lighting |
| Zumtobel Group |
| OSRAM Licht AG |
| Acuity Brands |
| Dialight |
| Samsung Electronics |
| Others |
Cost & Logistics Intelligence
Rare-earth phosphor costs for yttrium and europium dopants cascade through fixture manufacturing tiers, concentrating margin pressure on high-CRI product lines while commodity bulb assemblers in East Asian foundries absorb spot-price volatility through volume scale.
Pricing Analysis
Short lead-time premiums of 15-25% attach to SASO-certified fixtures cleared through Jebel Ali bonded warehouses, while spot inventory liquidations in Riyadh and Jeddah trade at distressed multiples. Three-tier pricing structure across premium controls-integrated, standard certified, and economy non-compliant tiers separates Signify's Interact bundles from wholesale tube distributors. Pricing pressure stems from Chinese export quota adjustments on rare-earth elements, compressing margin on hospitality-spec downlights. Industrial retrofit buyers exhibit highest price sensitivity; smart district procurement teams prioritize lifecycle performance over first cost.
Supply Chain Analysis
Reverse-logistics flows for failed driver modules and lumen-degraded arrays concentrate refurbishment activity in Dubai's Jebel Ali free zone, where third-party testing labs requalify components for secondary deployment. Semiconductor substrate supply draws from Taiwan, South Korea, and China's Yangtze River Delta foundries, with chip-on-board architectures sourcing gallium nitride wafers and aluminum nitride substrates. Single-source vulnerability concentrates in East Asian phosphor processing capacity. Distribution runs through direct manufacturer-to-contractor channels for Saudi giga-projects, while wholesale networks serve Doha and Kuwait City retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SASO's 2024 efficacy tier upgrade constructs a compliance moat that retroactively disqualifies mid-grade imports, elevating certified incumbents while raising capital barriers for unqualified entrants.
For Market Incumbents: Hedge thermal qualification bottlenecks by securing redundant third-party testing capacity in Jebel Ali and Riyadh before submission backlogs extend launch timelines. Deepen backward integration into chip-on-board substrate supply through captive sourcing agreements with Taiwanese foundries, insulating margin from rare-earth phosphor volatility. OLED panel substitution in luxury hospitality accent lighting threatens premium downlight positioning; accelerate circadian-tunable system development to defend specification share. For New Entrants and Emerging Players: Enter via Saudi industrial manufacturing zones and UAE free-trade warehousing, where metal-halide high-bay installations retain 60%+ penetration and sensor-enabled retrofit contracts carry lower certification burden than new-construction tenders. Target underpenetrated logistics facilities in Sohar and Duqm where aging HID stock requires phased LED conversion without smart controls complexity. Lead with lighting-as-a-service contracting to bypass capital-purchase procurement committees and capture recurring revenue attachment. For Investors and Strategic Acquirers: SASO certification backlogs clearing within 90 days is the leading indicator that compliant manufacturing capacity is scaling faster than demand absorption, compressing premium pricing windows. Five-to-ten year viability favors controls-integrated specialists with software-layer recurring revenue over pure hardware assemblers. Acquire thermal-engineering-focused fixture manufacturers with validated 50°C+ ambient performance records and existing Saudi giga-project reference contracts. Monitor phosphor export quota announcements from Chinese regulators as early signals of margin compression cycles.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Fast-Track Investment | Accelerated product launch timelines capture retrofit cycles in Riyadh and Jeddah before efficacy mandates tighten further. |
| Chip-on-Board Thermal Architecture Development | Desert-qualified lumen maintenance above 90% at 50°C+ ambient temperatures secures NEOM and Red Sea Project specifications. |
| Lighting-as-a-Service Platform Launch | Outcome-based performance contracts concentrate buyer power among ESCO consortiums and marginalize pure hardware vendors. |
| Li-Fi Communication Module Integration | Data transmission capability through modulated LED arrays compresses boundaries between illumination infrastructure and IT network deployment at Dubai and Doha airports. |
| Rare-Earth Phosphor Supply Hedging | Long-term offtake agreements with Chinese processors insulate high-CRI product margins from yttrium and europium export quota volatility. |
Research Approach
Independent corroboration across procurement directors at Saudi giga-project developers, ESMA compliance officers in Dubai, and wholesale distributors in Doha underwrites the qualitative findings on regulatory compression effects. Primary interviews with lighting controls engineers, facility managers at UAE commercial towers, and thermal testing laboratory directors in Jebel Ali combined with secondary validation from SASO technical regulations, ESMA energy efficiency circulars, and Qatar Global Sustainability Assessment System documentation. Bottom-up shipment data from bonded warehouse manifests triangulates against top-down construction permit analysis across the GCC.
Comparable-period anchoring to pre-2024 efficacy tier baselines established reference points for modeling replacement cycle acceleration through the projection horizon. Segmentation dimensions span product type, end-user vertical, installation mode, and distribution channel, with thermal performance tier and smart controls integration depth as industry-specific stratifiers. CAGRs derive from regression analysis against construction permit pipelines and energy code enforcement timelines. Forecast inputs incorporate phosphor cost indices, semiconductor substrate lead times, and third-party certification queue lengths.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Chinese rare-earth export restriction scenarios or extended SASO testing backlogs. Practitioners should monitor Jebel Ali warehouse inventory turnover rates and Doha commercial retrofit tender volumes for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
China Outdoor LED Lighting Market
LED
LED Panel Light Drivers Market
LED
US Outdoor LED Lighting Market
LED
OLED Blue Emitter Market
LED
Japan Outdoor LED Lighting Market
LED
Egypt LED Lighting Market
LED
Japan Indoor LED Lighting Market
LED
Global Chip Scale Package (CSP) LED Market
LED
LED Modular Display Market
LED
US LED Downlight Market
LED
Bluetooth LED Bulb Market
LED
Germany Automotive LED Lighting Market
LED
Dot-Matrix LED Displays Market
LED
LED Chip Market
LED
Germany Outdoor LED Lighting Market
LED
Asia Pacific Indoor LED Lighting Market